On October 26, 2026, Anthropic filed its public Form S-1. The private maker of Claude seeks a Nasdaq Global Select listing of Class A stock under the proposed symbol ANT. The filing’s most important term involves a single share of Class F stock.
Just before the offering, Anthropic will issue a single share of Class F stock to Anthropic Founders, LLC, whose initial members are its seven co-founders. That share carries 50.1% of total voting power, and the filing states it “will not have any economic rights.”
The filing leaves the price range and share count blank. The filing does not mention a reported valuation of $1.5 trillion to $1.75 trillion.
Until ANT trades, listed exposure runs through Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), which fell 1.06% to $316.80, and Amazon (NASDAQ:AMZN), which rose 0.44% to $249.09. Both hold nonvoting Class N stock, so they own economics without a vote.
What One Class F Share Actually Controls
Class A voting power is capped at 49.9%, and Class F power is not diluted by future issuances. The founders therefore decide elections of non-trust directors, certain charter amendments, and any merger or sale.
Board control is split. The Long-Term Benefit Trust elects four of seven directors through one Class T share, while Class F and Class A together elect the other three.
Inside the LLC, each founder gets one vote and a simple majority rules, and in a deadlock, the share votes in proportion to Class A votes cast.
The filing explains the arrangement this way: “We believe that our seven co-founders… as a group, are distinctly equipped to be stewards of our mission.”
Secret Successor Lists Extend Founder Power
Each original founder may suggest a ranked list of up to ten replacements, effective once five of the other six approve while all seven remain. Those lists “shall be strictly confidential and shall not be publicly disclosed by any Member or the Company.”
The first eight designees must meet residency rules and hold three years of tenure at Anthropic or a nonprofit or public-benefit group. The ninth and tenth slots carry no such requirement.
A founder remains a member by keeping at least 2% of IPO-date Class A holdings. One could thus give away 98% of a stake and still vote.
A Built-In Sunset Caps Founder Control
Replacements can join only until the offering’s tenth anniversary. If fewer than three founders remain for 90 consecutive days, a 450-day transition begins, after which the Class F share is redeemed for no consideration.
Mark Zuckerberg holds 60.8% voting control of Meta Platforms (NASDAQ:META) on about 14% of the economics. Anthropic’s version is collective and fixed, and outside estimates put the seven founders at about 10% combined ownership.
What These Terms Mean for Alphabet and Amazon Holders
Anthropic already shows up in both income statements. Amazon booked $53.40 billion of second-quarter pre-tax other income “primarily from investments in Anthropic,” and Alphabet’s quarter included a $99.03 billion gain on equity securities.
Those are paper marks set against market values of $3.92 trillion and $2.69 trillion. The voting design changes little for either company, because nonvoting holders were never going to control Anthropic.
The bigger risk is that the structure “may make us ineligible for inclusion in indices,” which could keep index funds out and pressure the valuation behind those marks.
Weighing the Bull and Bear Cases for AI IPO Stocks
In the bull case, Anthropic’s first-half revenue reached $16.29 billion, up from $1.16 billion a year earlier, and most of its $80.7 billion net loss was a $72.4 billion non-cash fair-value change.
The bear case centers on governance. Class A buyers “generally will not be able to affect the outcome of any matter submitted to a vote of our stockholders,” and insiders may sell 10% of locked-up shares from the first trading day.
At launch, AI IPOs built this way likely warrant a visible governance discount, and investors researching them can check whether the offering price reflects one. Alphabet, by comparison, trades at a P/E of 14 while Google Cloud revenue grew 82% in the second quarter.
The amended S-1 will be the test: if its price range implies a valuation near the reported top with these terms unchanged, the discount is missing. Alphabet’s report, expected October 28, will show how large its Anthropic mark has become.
The post Anthropic’s Founders Will Keep Control With a Single Share of Stock appeared first on 24/7 Wall St..
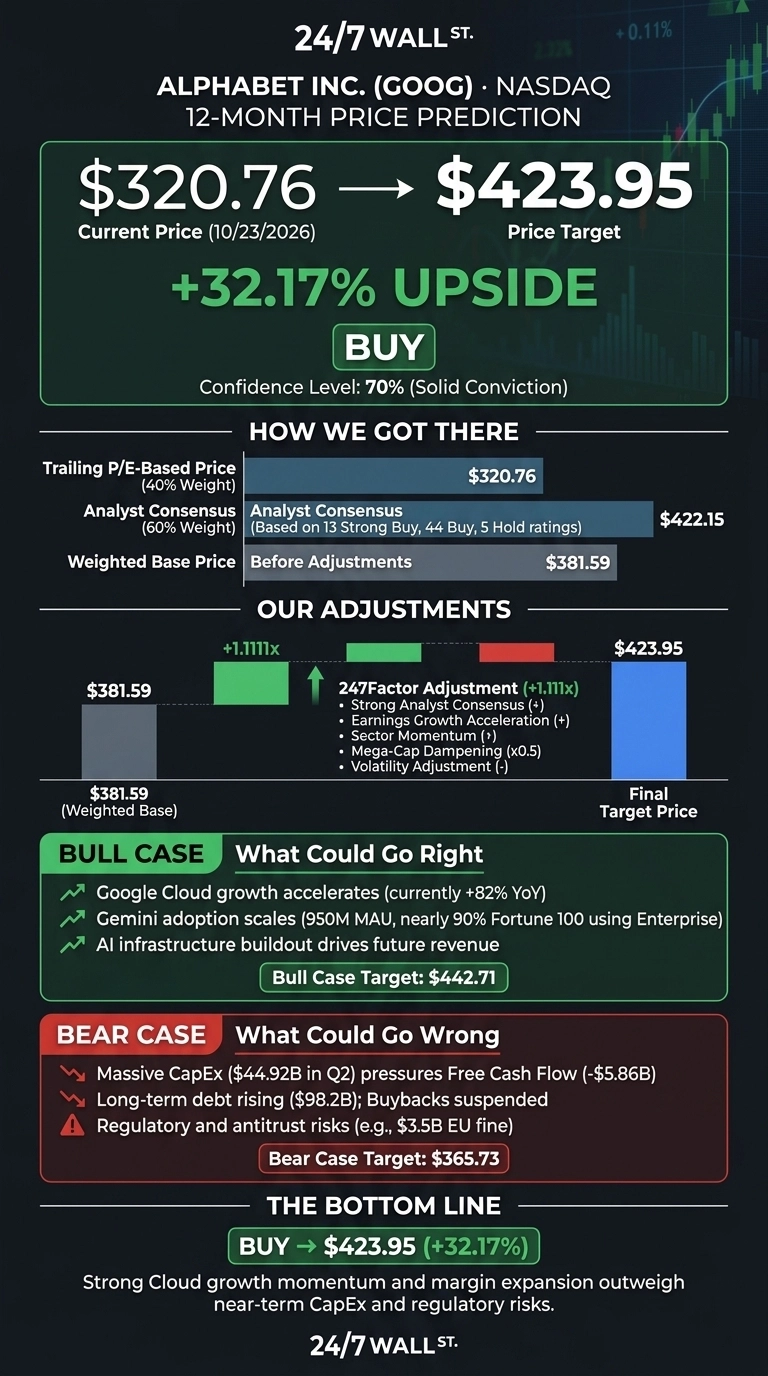
]]>The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $423.95. That means 32.17% upside from the prior close of $320.76. The stock gets a buy rating with 70% confidence, which we read as solid conviction with a margin for error.
| Metric | Value |
|---|---|
| Current Price | $320.76 |
| Price Target from 24/7 Wall St. | $423.95 |
| Upside/Downside | 32.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
Applied to Alphabet’s $4.05 trillion market cap, that upside works out to about $1.3 trillion in added market value. That figure is the opportunity behind our headline.

Google Stock Pulls Back Even as Cloud Growth Accelerates
Shares fell 7.82% over the past week and 8.49% over the past month. Early Friday they traded at $317.93, up just 1.51% year to date and about 21% below the 52-week high of $403.96. Over the past year the stock is still up 26.23%.
The fundamentals point the other way. In Q2, revenue rose 24.2% to $119.80 billion, ahead of the $116.91 billion estimate. EPS came in at $9.11 against a $3.04 estimate, although a $99.03 billion equity securities gain inflated that number. Google Cloud grew 82%, and its backlog reached $514 billion.
Why Bulls See a Breakout to $442
Cloud is now a profit engine. Its operating margin expanded to 35.6% from 20.7% a year earlier. The Gemini app has 950 million monthly users, and nearly 90% of the Fortune 100 use Gemini Enterprise.
Waymo has passed 500,000 fully autonomous rides a week. On the Q2 call, CEO Sundar Pichai said, “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
Wall Street largely agrees: 13 analysts rate the stock Strong Buy, 44 rate it Buy, 5 rate it Hold and none rate it Sell. The bull case reaches $442.71.

Spending Risks That Could Cap the Upside
Q2 capex jumped 100.14% to $44.92 billion, and free cash flow fell to -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion. Buybacks are suspended, and a new at-the-market program of up to $40 billion could dilute shareholders. Regulators also remain a threat after the $3.5 billion EU fine.
The counterpoint is that this cash is going into capacity customers are waiting for. Management says Alphabet remains supply constrained. Operating cash flow still rose 40.8%, and interest coverage stands at 175.5x.
Even our bear case of $365.73 sits above today’s price. The same AI expansion driving that capex is pulling a long list of suppliers along with it (we highlighted seven of them, from power to cooling, in a free report you can grab here).
Alphabet Looks Cheaper Than Microsoft and Meta
The most direct cloud rival is Microsoft (NASDAQ:MSFT). Azure grew 43%, about half of Google Cloud’s rate, yet Microsoft trades at 29x earnings.
Meta Platforms (NASDAQ:META) competes with Alphabet for ad budgets and AI talent. Its Q3 operating margin fell to 20%, partly because of a $9.89 billion legal charge.
| Company | P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Alphabet | 13x | 24.2% |
| Microsoft | 29x | 17.75% |
| Meta | 24x | 26.07% |
Alphabet’s multiple gets a lift from equity gains. Even its forward P/E of 22x is still below Microsoft’s trailing multiple. Next to these peers, our target looks reasonable, maybe even conservative.
Cloud Momentum Tips the Scale
The 24/7 Wall St. price target of $423.95 carries a buy rating with 70% confidence. The deciding factor is cloud growth that is speeding up as margins expand.
I’d view the stock as attractive if the backlog keeps turning into revenue at these margins. I’d grow more cautious if free cash flow stays negative while debt keeps rising. On balance, Alphabet looks undervalued.

| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month target) | $423.95 |
| 2027 | $426.05 |
| 2028 | $510.24 |
| 2029 | $597.01 |
| 2030 | $659.84 |
Alphabet needs to keep executing on its full-stack AI strategy for these projections to hold. Gemini adoption, regulatory action or a slowdown in AI spending could move the stock well above or below these targets.
The post Prediction: This Magnificent Seven Stock Could Be a $1 Trillion Opportunity appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOGL, NASDAQ:GOOG) reports third-quarter results after the close on Wednesday, October 28. Google Cloud’s backlog stands at $514 billion, and 2026 CapEx guidance runs $195 billion to $205 billion. This report shows which one is growing faster.
Record Cloud Growth Meets Negative Free Cash Flow
Last quarter, revenue rose 24.2% to $119.80 billion, ahead of the $116.91 billion consensus. Google Cloud led again. Revenue there rose 82% to $24.77 billion, speeding up from 63% in Q1 and 34% a year ago, while Cloud operating margin expanded to 35.6% from 20.7%.
Costs grew just as fast. CapEx rose 100% to $44.92 billion, free cash flow came in at negative $5.86 billion — the first time ever — and management raised its 2026 CapEx range from $180 billion to $190 billion. To pay for it, Alphabet raised about $70 billion in equity and debt and suspended buybacks.
Reported EPS of $9.11 included a $99.03 billion equity securities gain, yet shares fell 6.89% on the day of the report. GOOG closed Friday at $317.28, down 5.83% over the past week.

Consensus Calls for Nearly 25% Revenue Growth
| Metric | Consensus | Prior-Year Actual | YoY Growth |
|---|---|---|---|
| Q3 2026 Normalized EPS | $3.0047 | $2.87 | 4.69% |
| Q3 2026 Revenue | $127.85B | $102.35B | 24.92% |
| FY2026 EPS | $20.595 | $10.81 | 90.52% |
| FY2026 Revenue | $500.15B | $402.84B | 24.15% |
The full-year EPS figure includes the first half’s equity gains, which makes the quarterly estimate the cleaner gauge of operating profit.
Backlog Conversion and Margins Will Set the Tone
My first focus will be the backlog. It rose by more than $50 billion sequentially last quarter, and management expects to recognize just over 50% of it within 24 months. Sundar Pichai said in July, “We are still in a supply-constrained environment.”
Margins come next. Alphabet planned to lean on third-party capacity in Q3 as a bridge, which management said would create “modest margin pressure,” on top of Wiz integration costs and rising depreciation. You should compare Cloud margin against 35.6% and consolidated operating margin against 34%.
On spending, any change to the 2026 range matters, as does early color on 2027, when management expects CapEx to “increase significantly.” TPU system sales add another variable. That revenue ramps as Alphabet leaves 2026, with the “vast majority” arriving in 2027.
All that CapEx has to be powered, cooled, and connected by somebody, which is the entire point of a free report we put together on seven AI infrastructure suppliers that aren’t the chipmakers: you can grab it here.
Search still has to fund the expansion. Revenue there grew 17% to $63.3 billion, and AI Mode passed 1 billion monthly users. A court has already rejected a forced breakup of Google’s ad-tech business, so any detail on the remaining behavioral remedies could also move opinion.
A $514 Billion Backlog Has to Turn Into Cash
Alphabet beat estimates in all 8 of its last reports. Even so, the stock’s moves on report day ranged from a 9.97% gain to a 6.89% drop, and the market now cares most about how efficiently that capital gets spent. If the backlog turns into revenue fast enough to steady free cash flow while CapEx keeps rising, the spending case gets easier to defend heading into a greater 2027.
The post The $500 Billion Question: Can Google Cloud’s Massive AI Backlog Outrun Its Mind-Boggling CapEx Boom on Oct. 28? appeared first on 24/7 Wall St..
]]>The 10-year Treasury yield closed at 5.13% on October 21. That is already above the ceiling Alan Rechtschaffen expects for long-term rates. On the same day, UBS weighed in. UBS’s senior portfolio manager laid out a case for the S&P 500 to reach 9,500 by June 2027.
His target sits well above the UBS base case of 8,400 and above his own call for 8,100 by the end of 2026. He ties it to three long-running technology waves: superintelligence, longevity and disease cures, and energy.
Profits are his strongest evidence. He cited 25% year-over-year earnings growth. He expects double-digit gains next year, so the rally rests on what companies actually earn.
His rate path complicates the outlook. He expects the Fed to pause in October, probably raise rates in December and again in March, and only then consider cuts. A bull case that runs through two more hikes requires you to trust that productivity gains will outrun tighter money.
Profits Are Carrying This Rally
Earnings-driven gains hold up better than price-to-earnings expansion, because multiples can shrink quickly when rates move. For NVIDIA (NASDAQ:NVDA), fiscal second-quarter revenue grew 105.8% to $96.22 billion, with Data Center sales of $89.02 billion.
At Microsoft (NASDAQ:MSFT), Azure grew 43% and passed $100 billion in annual revenue for the first time. Google Cloud revenue at Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) jumped 82%.
Double-digit growth next year depends on that spending continuing to turn into revenue. NVIDIA expects supply to remain a bottleneck at least through the end of fiscal year ’28. That points to strong demand, but it also caps how fast the company can ship.
AI Leads While Longevity and Energy Trail
Superintelligence has the clearest link to earnings today. NVIDIA, Microsoft and Alphabet carry market values of about $5.36 trillion, $3.96 trillion and $4.16 trillion, so much of the index’s gain depends on three names.
Longevity is further along than its label suggests. Eli Lilly (NYSE:LLY) grew revenue 47.7% to $22.97 billion last quarter and raised full-year guidance to $85.0 billion to $87.0 billion.
Energy is at an earlier stage. Constellation Energy signed 920 MW of long-term nuclear contracts and plans to restart Crane in 2027, but those contracts begin between 2029 and 2032. Reactors take years to permit and restart. That is why the positioning happens early (we named five ways to play the nuclear restart in a free report).
Share prices reflect that gap. Constellation is down 23.02% this year, while Lilly is up 18.82%.
Rate Hikes Are the Weak Spot
Higher rates raise the discount rate applied to future profits, which hits growth stocks hardest because more of their earnings come years from now.
He expects the 10-year yield to settle between 4.5% and 5%. Today’s yield already sits above that range, so his forecast assumes rates come down from here.
His answer is productivity. Unit costs fall, and margins rise. If AI lets companies produce more without hiring as many people, that can hold down prices even as demand grows.
He said those gains already show up in hiring and operations, although the transition is slow and uncomfortable, and while slower hiring helps margins, job losses and uneven gains could weigh on consumer spending.
Five-to-Seven-Year Bonds Lock In Yield
“Cash is comfortable, but, you know, cash has a cost and has risk to it,” he said. The main risk in cash is reinvestment.
A one-month Treasury yielded 4.09% on October 21, but short-term rates reset quickly once the Fed starts cutting.
For clients who want yield, he suggested bonds that mature in 5 to 7 years. The 5-year Treasury yielded 4.95%, and the 7-year yielded 5.03%. Either one locks in income for years without taking on full stock market risk.
The tradeoff is price risk. If his expected hikes come and yields climb, intermediate bonds lose value in the short run, while cash holds steady.
Are S&P 500 Stocks a Buy?
The bull case rests on 25% earnings growth, AI leaders that keep beating estimates, and Lilly’s proof that longevity science already produces revenue.
The bear case is a Fed that may hike twice, a 10-year yield higher than expected, and heavy concentration in a few megacaps. NVIDIA also expects gross margin to fall to 71% to 72% in its fiscal fourth quarter because memory costs are rising.
Investors considering both sides of the case can research how Vanguard S&P 500 ETF (NYSEARCA:VOO) and 5-to-7-year Treasuries fit their own goals. The fund charges 0.03% and is up 14.32% this year. It gives you all three themes cheaply, and the bonds pay income if rate hikes squeeze valuations first.
The post UBS portfolio manager: S&P 500 could hit 9,500 by June 2027 on AI, longevity, energy boom appeared first on 24/7 Wall St..
]]>Every quarter, IBM (NYSE: IBM) CEO Arvind Krishna says IBM is doing great. Every quarter, investors are reminded that what was the greatest American tech company for decades had its chance to stay great. Krishna and his immediate predecessors squandered that opportunity with a single-digit revenue increase and technology that lags virtually every one of its larger competitors.
As IBM released quarterly figures, Krishna commented, “Disciplined execution throughout the quarter drove accelerated revenue growth and strong free cash flow. Our clients are now deploying Super Intelligence in ways that transform entire operating models, instead of simply addressing narrow or novel problems. IBM’s technology and expertise are helping organizations drive growth and serve customers with greater speed, precision, and efficiency than ever before.” In reality, revenue rose a paltry 5% to $17.1 billion, dwarfed by companies like Microsoft (NASDAQ: MSFT), Meta (NASDAQ: META), and Alphabet (NASDAQ: GOOG). IBM’s net income for the quarter was $2.2 billion, up from $1.7 billion last year. Nvidia’s (NASDAQ: NVDA) net income in the last quarter was $60 billion.
In its most recent quarter, Microsoft had revenue of $90 billion. It had net earnings of $36 billion.
Going back to 1993, IBM was the fourth largest company in America, behind only GM, Ford, and ExxonMobil. It was ahead of GE, which is considered the best-run company in the second half of the last century. Last year, IBM ranked 66th, based on the Fortune 500.
Nothing tells Wall St.’s view of companies in the same sector as market cap. IBM’s is $237 billion. Microsoft’s is $4 trillion, and Alphabet’s is about the same.
What happened to IBM, really? It missed out on leading in PCs, smartphones, operating systems, cloud computing, AI, e-commerce, and search. In essence, it missed out on every major tech advance in the last half-century.
IBM will never be a tech leader again. In fact, it continues to fall behind.
The post IBM Is America’s Worst Big Tech Company appeared first on 24/7 Wall St..
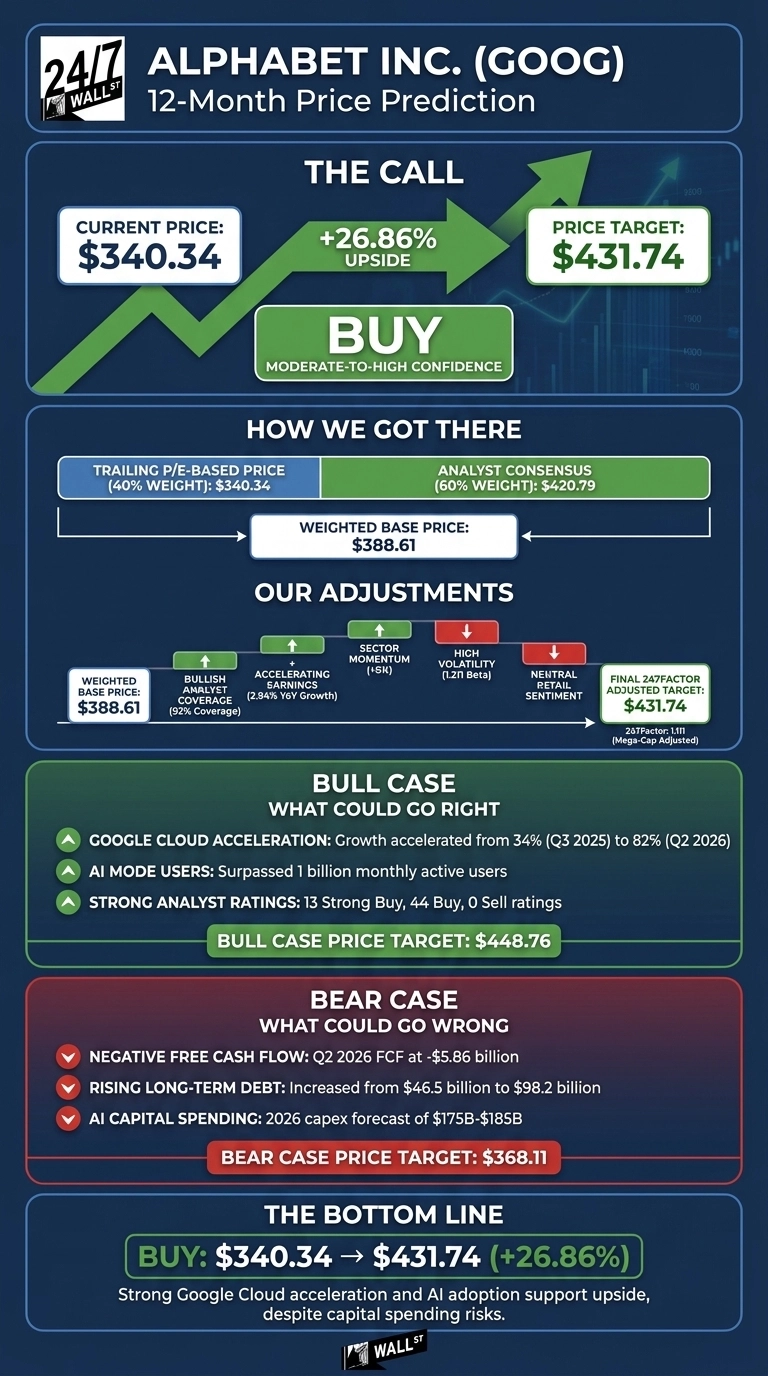
]]>Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $431.74 over the next 12 months. From $340.34, that means 26.86% upside. Our rating is buy, with moderate-to-high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $340.34 |
| Price Target from 24/7 Wall St. | $431.74 |
| Upside/Downside | 26.86% |
| Recommendation | BUY |
| Confidence Level | 70% |
Alphabet has a market value of about $4.16 trillion, and its growth is still speeding up. Revenue growth rose from 15.95% in Q3 2025 to 24.23% in Q2 2026.
Over the same period, Google Cloud growth went from 34% to 82%. The stock has not kept pace with that momentum, and that gap supports our upside case.
Shares Stall Even After a Strong Cloud Quarter
GOOG is down 3.2% over the past week and 1.91% over the past month. It is still up 7.86% year to date and 33.46% over the past year. At $337.82 midday Tuesday, the stock sat 16.4% below its $403.96 52-week high and 35.2% above its $249.80 low.
In Q2, revenue came in at $119.80 billion, ahead of the $116.91 billion estimate. EPS was $9.11, though a $99.03 billion gain on equity securities inflated that number. The cloud backlog hit $514 billion.
Why Bulls See $448 and Beyond
Google Cloud’s operating margin rose to 35.6% from 20.7% a year earlier. Management expects just over 50% of the backlog to turn into revenue within 24 months.
AI Mode has passed 1 billion monthly users, and Alphabet expects most of its TPU system sales revenue to land in 2027. On the Q2 earnings call, management said Alphabet had become “more bullish on the opportunities ahead”.
Wall Street generally agrees. Of the analysts covering the stock, 13 rate it Strong Buy, 44 rate it Buy and none rate it Sell. The consensus target is $420.79. In the bull case, the target reaches $448.76.
Spending Spree Is the Risk to Monitor
Alphabet guided to $175 billion to $185 billion in 2026 capex, and Q2 free cash flow turned negative at -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion.
Buybacks are paused, and a stock sale program of up to $40 billion could dilute shareholders. Renting outside computing capacity will also weigh on cloud margins. The bear case sits at $368.11, which is still above today’s price.
Operating cash flow rose 40.8% to $39.07 billion, and management says “demand still outpaces that investment.”
Alphabet Looks Cheapest Among Its AI Rivals
Azure goes up against Google Cloud for the same enterprise AI budgets, which is why Microsoft (NASDAQ:MSFT) belongs in this comparison.
For digital ad dollars, Meta Platforms (NASDAQ:META) competes with Google and sits in a similar AI capex race. All of that spending requires infrastructure support from someone, and we pulled seven of those suppliers into a free report on the AI infrastructure buildout.
| Company | P/E | Operating Margin | Latest Revenue Growth |
|---|---|---|---|
| Alphabet | 14 | 32.06% | 24.23% |
| Microsoft | 30 | 46.78% | 17.75% |
| Meta | 26 | 41.44% | 27.96% |
Microsoft has higher margins, but it trades at a much higher multiple than Alphabet while growing revenue more slowly. Meta grew faster, but in Q2 its operating margin fell to 31% and it missed EPS estimates by 14.42%.
Equity gains improve Alphabet’s P/E, but even its 22x forward multiple is well below both rivals. Our 24/7 Wall St. price target looks reasonable, and arguably conservative, next to this peer group.
What Could Push Alphabet Toward Our Target
My 24/7 Wall St. price target is $431.74, with a buy rating and 70% confidence.
What tips the scale for me is Google Cloud: its growth is accelerating and it is getting more profitable at the same time. The bull case holds as long as the backlog keeps turning into revenue. The thesis weakens if capex keeps rose while cloud margins shrink.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $356.40 |
| 2027 | $440.96 |
| 2028 | $513.09 |
| 2029 | $567.17 |
| 2030 | $631.69 |
Alphabet’s AI strategy execution supports these estimates. Much faster TPU adoption could push results above these figures, while AI spending that fails to earn a return or new regulatory penalties could pull them below.
The post Prediction: One of the World’s Biggest Stocks Could Still Have Room to Run appeared first on 24/7 Wall St..
]]>Berkshire Hathaway (NYSE:BRK-B) Class B shares closed at a record $539.82 on Tuesday, October 20, 2026, after a 1.43% gain. The old high was the $539.80 close on May 2, 2025, set the Friday before Warren Buffett told shareholders he would hand over the CEO job, so the new record beat it by just two cents.
Getting back there took 17 months. Over that time, the S&P 500 gained more than 35% while Berkshire stayed below its old high.
On October 21, both share classes set intraday records, with Class B reaching $543.34. Class B then closed at the day’s low of $538.99, down 0.15%, which left it slightly below the October 20 record close.
Berkshire’s market value at that close was about $1.16 trillion. Most of the push to the record came from investors pulling money out of AI stocks, and that rotation will likely determine how long the record holds.
Money Leaving AI Stocks Landed in Berkshire
The S&P 500 set a record on October 6 and has slipped since then, while Berkshire gained about 7%. From October 6 through October 20, the iShares Semiconductor ETF (NASDAQ:SOXX) fell in 10 of 11 sessions and lost 15.17%, while Berkshire rose in nine.
That run included a 10-day winning streak, Berkshire’s first since 2018. Investors pulling out of crowded chip trades looked for profits that hold up whether AI spending does, and Berkshire offers that through its insurance, BNSF railroad, utility and consumer businesses, plus a large cash cushion.
Abel Is Putting the Cash to Work
In the second quarter, Berkshire bought back $4.5 billion of its own stock and put $23.5 billion into other stocks, including $10 billion in Alphabet (NASDAQ:GOOGL) (NASDAQ:GOOGL). That ended 14 straight quarters of net stock selling, and cash fell to $364.7 billion from a record $380.2 billion.
Buybacks matter because they show management thinks the shares trade below intrinsic value, meaning the company’s underlying worth. Operating profit rose 16% to $12.98 billion, a quarter KBW analyst Meyer Shields called “very solid.”
Buffett already did the stock-picking work for a lifetime, and the cheapest dividend payers still sitting inside Berkshire’s own book are worth a look (we ranked the seven cheapest in a free guide here: 7 Warren Buffett Stocks to Buy Now).
Succession Doubts Are Fading
On September 18, 2026, Buffett, then 96, stepped down as chairman and became chairman emeritus. His son Howard Buffett, a board member since 1993, became non-executive chairman; Buffett stayed on as a director, and he wrote that “Howard will guard its culture and values.”
The stock hit its low about two weeks after the chairman change was announced. Investors wanted proof that Berkshire runs well without Buffett at the top, and rising profits plus buybacks under Abel, CEO since the start of 2026, gave them that proof.
What Could Stall the Rally
If AI stocks bounce back, the money that moved into Berkshire could move right back out. The chip ETF rose 2.07% on October 21, the same day Berkshire slipped from its intraday high.
Traders are treating $540 as the key technical level heading into earnings, and Berkshire closed just under it. The upcoming third-quarter report will show whether operating earnings can match the $13.48 billion from the same quarter a year earlier. A record price also gives you less margin of safety than the stock offered while it fell behind.
Should You Buy or Sell BRK-B Stock
At a P/E of 11x and a price-to-book of 1.06, Berkshire is modestly priced for a company with rising operating profit and a CEO buying back its shares. Index funds still lean hard on the same AI trade that is now reversing, so they carry more exposure if chip stocks keep falling. Berkshire’s mix of businesses has less direct exposure to that trade.

This view holds if Class B closes above $540 after the third-quarter report and operating earnings come in at or above $13.48 billion. If earnings fall short and the chip ETF wins back its October losses, the rotation is reversing, and the record likely won’t last.
The post Berkshire Finally Topped Its Pre-Buffett-Exit Peak appeared first on 24/7 Wall St..
]]>Meta Platforms (NASDAQ:META) took in $32.79 billion of operating cash in the third quarter. It spent $34.91 billion on capital expenditures, including finance-lease principal. In the report released after the close on October 21, 2026, free cash flow came to negative $2.12 billion. That makes it the first negative free cash flow quarter since 2012, its IPO year.
The stock still closed at $697.52, up 0.47%. By 7:59 PM ET, it had risen 2.16% to $712.61 in after-hours trading, which keeps it well inside a 52-week range of $520.26 to $779.82. The open question is whether revenue can grow faster than the AI build-out before borrowing becomes the main way Meta pays for it.

How a Record Spending Quarter Tipped Into the Red
Purchases of property and equipment came to $33.94 billion, the most in Meta’s data going back to 2011. Another $964 million went to principal on finance leases. These are long-term rental contracts for data centers and servers that work like having the asset, so Meta considers those payments as capital spending.
Even without the leases, operating cash flow minus property purchases was still negative $1.16 billion. The last shortfalls on that basis came in the first half of 2012. In Q2 2012, Facebook brought in about $242 million of operating cash and spent $413 million on capex.
Spending also climbed quickly through the year. Capex was $19.4 billion a year earlier and $31 billion in Q2. Q2 free cash flow had already fallen 91% to $784 million, the lowest since late 2022. Free cash flow for the first nine months was still positive at $11.05 billion, down from $29.51 billion in the same period of 2025.
Debt Has Caught Up With Cash
CFO Susan Li laid out the balance sheet on the call: “Free cash flow was negative $2.1 billion. We ended the quarter with $82.4 billion in cash and marketable securities and $83.7 billion in debt.”
Long-term debt rose to $80.92 billion from $58.74 billion at December 31, 2025. Meta bought back no stock in the quarter, compared with $3.33 billion a year earlier. It still paid $1.36 billion in dividends, so when capex uses up the cash, buybacks are the first shareholder return to go.
Ad Growth Still Funds Most of the Build-Out
Revenue rose 26% to $64.60 billion, ahead of the roughly $63.3 billion analysts expected. Ad prices rose 14%, and impressions rose 10%.
Operating margin fell to 20% from 40%. Most of that drop came from a $9.89 billion charge linked to the August 2026 agreement with 52 state attorneys general over teen mental health. Diluted EPS was $3.83, or $7.40 without the charge.
Amazon (NASDAQ:AMZN) and Alphabet (NASDAQ:GOOGL) (NASDAQ:GOOGL) also spent more on capex than they took in from operations from April to June 2026, and Alphabet reported negative free cash flow for the quarter. That shows real demand, but it also means none of these three AI spenders is covering its AI spending from current cash.
Meta Has Not Yet Put a Number on 2027
Meta narrowed its 2026 capex range to $135 billion to $145 billion from $130 billion to $145 billion and forecast Q4 revenue to $73 billion to $76 billion. Li said Meta is “quite early in developing our budget and capacity plans for next year.” Zuckerberg added: “It’s going to be very important to get the math on all of this to work out.”


Operating cash flow still paid for almost all of a record capex quarter, and the stock trades at about 25 times earnings. Debt now roughly matches cash and buybacks have ended, but that cost is acceptable as long as revenue keeps up with spending. The test comes with the Q4 2026 report, expected in late January 2027. A second negative free cash flow quarter, or revenue below the $73 billion low end of guidance, would weaken the bullish thesis.
The post Meta Just Burned Cash for the First Time Since Its IPO appeared first on 24/7 Wall St..
]]>SpaceX (NASDAQ:SPCX) reported third-quarter 2026 results after the close on October 20, 2026. For the first time, its Super Intelligence (SI) division, the AI unit, brought in more revenue than Connectivity, which is mostly Starlink. SI booked $7.560 billion in revenue, compared with $5.248 billion for Connectivity.
The stock closed the regular session at $147.79, down 0.11%, before the report. It then traded at $159.70 after hours as of 7:59 p.m. ET, up 8.06%. That is an after-hours quote, so the October 21 session will set the real price.
These results contain a tension. The AI business grows fastest and spends the most cash, while Starlink still makes most of the profit. Through October 20, shares fell. They were down 8.18% from their first trading close on June 12, 2026, which leaves a $2.01 trillion company that has yet to show that its AI spending will pay off.
Part of This Revenue Flip Was Bought
Total revenue rose 161% to $14.575 billion. Net income came in at $4.404 billion, compared with a net loss of $1.054 billion a year earlier. Operating income was $2.791 billion, after an operating loss of $143 million in the second quarter.
SI revenue grew 830% from $813 million. Some of that growth was bought, because Cursor, acquired on August 14, 2026, at an implied equity value of $60 billion, added $608 million.
Chief financial officer Bret Johnsen said SI solutions and infrastructure revenue grew 192% sequentially even without Cursor. Johnsen said SI revenue was “up $5 billion quarter-over-quarter and $6.7 billion year-over-year, primarily powered by the ramp of our cloud services agreements.”
SpaceX disclosed only “cloud services agreements.” Customer names such as Anthropic and Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) unit Google come from press reports, and the company did not disclose contract terms. On the call, Elon Musk said SpaceX rents compute at “effectively the spot market rate” instead of signing long-term deals.
Starlink Still Supplies Most of the Profit
Connectivity operating income rose 99% to $2.367 billion. SI makes $431 million after recording $1.2 billion of share-based compensation tied to Cursor.
SI does lead on Adjusted EBITDA, $4.953 billion to $3.499 billion. That measure excludes non-cash stock awards and depreciation on new compute, both of which are real costs.
Starlink ended the quarter with 13.6 million consumer subscribers. It added 1.6 million, which missed expectations, while monthly revenue per user (ARPU) was $69.
AI Build Costs Money Now and Pays Back Later
SI accounted for $16.444 billion of total capital spending of $19.593 billion. Johnsen guided fourth-quarter capex to between $35 billion and $40 billion. He said, “At current pricing, new compute deployments are generating a payback of less than a year.”
Total compute reached 1.7 GW, up from 0.6 GW a year earlier. Johnsen cited a $63 billion backlog, about $42 billion of it due within a year, and repeated a $100 billion year-end ARR (annual recurring revenue) goal.
Musk also projected $500 billion to $1 trillion in ARR by the end of 2027. He separately said Tesla (NASDAQ:TSLA) and SpaceX have formed special committees to discuss a merger.
What Could Change the Outlook for SpaceX Stock

My view is cautious. The spending happens now. The return Johnsen described depends on spot pricing holding up, since SpaceX chose not to lock in long-term contracts.
Starlink is the part of SpaceX with proven profits, but you cannot buy it on its own. At $2.01 trillion, you are paying mostly for an AI build that makes $431 million in operating income.

The cautious view fails if first-quarter 2027 revenue lands inside the guided $33 to $37 billion range and SI operating income rises well above the third-quarter level.
The post SpaceX’s AI Business Is Now Bigger Than Starlink appeared first on 24/7 Wall St..
]]>Anthropic’s updated confidential draft IPO filing describes about $450 billion of cloud compute agreements over the next decade, which The Wall Street Journal reported after reviewing the draft. The document calls them “massive, noncancelable” commitments.
The draft is not posted on SEC EDGAR. Every Anthropic figure here is what the draft reportedly shows, and any of it could change before a public filing.
The sellers are Amazon (NASDAQ:AMZN), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) and Microsoft (NASDAQ:MSFT). Each one rents Anthropic computing power and owns an equity stake in it, and each also builds AI products that compete with Claude.
None of the three stocks moved in a way that ties them to the report. On Tuesday, October 20, Amazon closed at $262.63, up 0.07%, Alphabet fell 1.13% to $340.28, and Microsoft slipped 0.31% to $531.87.
That calm may miss what matters for shareholders. Part of each company’s cloud backlog (revenue already under contract but not yet booked) now depends on one customer that is also a rival, and that customer’s ability to pay depends on a successful IPO.
What Anthropic’s Draft Locks In
The $450 billion covers cloud agreements only. The draft also points to as much as $750 billion of potential compute spending, and that figure includes deals still under negotiation, so part of it is intent with no signed contract behind it.
A September version of the draft split the commitments into $111 billion for Google Cloud, $110 billion for Amazon Web Services and $31 billion for Microsoft. That version showed a $518 billion total that included obligations to Broadcom (NASDAQ:AVGO).
The hyperscalers signed because Anthropic is growing fast. First-half 2026 revenue reached $16.3 billion, compared with $1.1 billion a year earlier. Compute spending hit nearly $9 billion in those six months, against $7.3 billion in all of 2025.
The first-half net loss of $80.7 billion looks bad. About $72 billion of it, however, came from non-cash adjustments tied to convertible notes and financing instruments.
Which Cloud Giant Carries the Most Anthropic Risk
Alphabet holds the largest commitment, so it gains the most and is the most exposed. Google Cloud revenue rose 82% to $24.77 billion in the second quarter, and Gemini competes directly with Claude.
Amazon’s exposure is similar. AWS reported a $496 billion backlog, and Anthropic has committed to up to 5 GW of Trainium chips.
Microsoft’s share is small next to its $678 billion of commercial remaining performance obligations. All three booked Anthropic investment gains in 2026, including Microsoft’s $3.2 billion, so when they promote Anthropic demand, they are promoting an investment they own.
Where Noncancelable Stops Protecting the Sellers
A noncancelable contract protects the seller only as long as the buyer can pay. About 20% of Anthropic’s first-half revenue came from two customers, so the concentration risk affects both Anthropic and its suppliers.
The draft also says Anthropic sought more capacity than the hyperscalers would supply. It is reportedly in talks with Nscale about a second West Virginia data center deal worth about $45 billion, which has not been nailed down. All of that capacity still has to be powered, cooled, and connected by somebody, which is the thread we pulled on in a free report on seven AI infrastructure suppliers that aren’t chipmakers.
How Cloud Stock Valuations Stack Up Against Anthropic Exposure
On balance, the bull case is stronger, and Alphabet has the best version of it. It trades at about 15 times earnings, compared with about 36 times for Amazon and 30 for Microsoft, and it owns both the largest Anthropic contract and a competing model.
The bear case rests on cash. Alphabet’s free cash flow was negative $5.86 billion in the second quarter, and every one of these contracts assumes Anthropic remains funded.
IPO marketing could start the week of Nov. 9 at the earliest, and shares could start trading before Thanksgiving. The draft says the offering could value Anthropic at $2 trillion, which remains a preliminary estimate that could change before pricing.

Alphabet and Microsoft are expected to report on October 28, and Amazon on October 29. If Google Cloud or AWS backlog growth stalls on those calls, or management flags Anthropic payment risk, this view is wrong.
The post Anthropic Has Committed $450 Billion to Cloud Computing, Its Draft IPO Filing Shows appeared first on 24/7 Wall St..
]]>A check Google’s former chief executive wrote in 2021 may now be one of the most valuable personal stakes in the AI industry. Eric Schmidt owns about 1% of Anthropic, people familiar with the matter said on Monday, October 19, 2026. Neither Schmidt nor Anthropic has confirmed the figure.
The stake dates to a “tens-of-millions-of-dollars investment” in Anthropic’s Series A, when the company was valued at $461 million. At Anthropic’s most recent valuation of $965 billion, the stake could be worth about $10 billion. Nobody outside his circle knows whether he has sold any of it.
Investors in Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), where Schmidt was CEO, treated the report as a minor development. Shares rose 1.05% to close at $344.18, valuing the company at $4.21 trillion.
What the Report Confirms and What It Leaves Open
Nothing here is signed or filed. The 1% figure comes from unnamed sources, and no public registration statement shows Schmidt’s holdings.
The IPO timeline is also only a plan at this stage. Formal marketing could begin as early as the week of Monday, November 9, with trading possible before Thanksgiving and a year-end listing. The range discussed runs from $1.8 trillion to $2 trillion, matching or exceeding SpaceX’s $1.77 trillion offering in June.
At the top of that range, the stake could reach $20 billion. That would raise Schmidt’s net worth by about a third from $57.5 billion to nearly $80 billion.
Anthropic’s latest valuation is about 2,093 times its Series A price. That increase went to venture funds, insiders and strategic partners before any public investor could buy a share.
Schmidt invests through TomorrowVentures, Innovation Endeavors and the Hillspire family office, and he has also backed Mistral AI, Reflection AI and World Labs. All of those companies are private, so none carry verifiable financials.
Why Anthropic’s Price Matters for Alphabet
Alphabet has its own strategic ties to Anthropic, which competes with Gemini while also using Google Cloud, and Schmidt’s personal stake is a minor governance matter at Alphabet’s scale and sits apart from the company’s revenue and profit.
The listing matters as a pricing event, because a public Anthropic quote would give investors a daily benchmark for advanced AI models. Google Cloud revenue grew 82% to $24.77 billion in the second quarter. The Gemini app has 950 million monthly active users (the power, cooling and networking suppliers behind that expansion are the subject of a free report on seven AI infrastructure stocks that aren’t chipmakers).
A rich Anthropic multiple could make those assets look cheap. Alphabet trades at about 23x forward earnings.
Reality Check on an Unconfirmed Stake
Three inputs remain soft: the stake size, any past sales, and a valuation range that could move before pricing, and every dollar figure attached to Schmidt is a “could be worth” estimate.
A listing this large also draws capital, and funds seeking pure AI exposure may trim megacaps to make room. Alphabet’s spending also carries risk, with second-quarter capex of $44.92 billion and negative free cash flow of $5.86 billion.
Should You Buy or Sell GOOGL Stock

Alphabet gives investors public exposure to AI while Anthropic shares remain unavailable because it is not listed, liquid, or profitable.
The stock has gained 10.18% year to date and 36.23% over the 12 months through October 19, yet it trades below its 52-week high of $408.10. Second-quarter revenue rose 24.2% to $119.80 billion.
Investors who buy Anthropic at its IPO will pay a price set after private investors captured the early gains. The next milestone is Anthropic’s public registration filing. If the offering prices at or above $1.8 trillion by year-end while Alphabet holds above its 200-day moving average of $340.90, the case for an AI rerating at Alphabet is working.
The post Google’s Former CEO Quietly Owns 1% of Anthropic appeared first on 24/7 Wall St..
]]>Chip stocks bounced on October 19, and the session showed who collects the money in this AI cycle. The Nasdaq rose 1.3% with semiconductors leading; NVIDIA (NASDAQ:NVDA) gained 1.38%, and Meta Platforms (NASDAQ:META) slipped 0.55%.
Seema Mody’s segment that day focused on that split. The GPU supplier rose while the hyperscaler expected to raise outside money fell behind, although one session cannot show that equity talk drove Meta lower.
Meta’s expansion now needs more than its own cash. It guided 2026 capital expenditures to $130 billion to $145 billion, and second-quarter free cash flow fell to $784 million from $8.55 billion a year earlier.
NVIDIA reported $96.22 billion in quarterly revenue, up 105.8%. That gap between the buyer’s falling cash and the seller’s rising sales is why the coming hyperscaler reports carry more weight than a typical quarter.
Why This Pullback Could Precede Strong Hyperscaler Reports
Mody cited Evercore ISI: “Evercore ISI out with a note this morning that leans a bit more bullish saying the pullback that we’ve recently seen in these names comes ahead of what they think will be a strong hyperscaler earnings season.” The firm reads recent weakness as a setup for those reports.
NVIDIA is still down 4.08% over the past week and 2.33% over the past month, although it is up 16.67% year to date.
Meta fell 5.05% over the past week and is down 1.28% over the past year despite a 7.13% gain in 2026. The weak one-year return suggests some investors likely doubt the payoff from the spending.
Watch capital spending plans, AI revenue, and how the spending gets financed. NVIDIA expects top five hyperscaler capex to reach nearly $800 billion in 2026.
Older NVIDIA Chips Still Hold Their Value
Mody noted: “The H100 that’s Nvidia’s older chip has held up in terms of pricing ever since Anthropic’s latest model came out.” New model launches are lifting demand for older hardware too.
That signals demand for compute still exceeds supply. NVIDIA said it has supply for about 70% of demand.
It also protects collateral, because GPUs now back loans. Chips that hold their rental rates also hold their value as loan collateral.
Asia is more cautious: “Bank of America’s semiconductor team just returning from Asia, sharing with clients that investors there are a bit more anxious about the AI funding cycle.” The worry there centers on funding.
GPU-Backed Loans Are Becoming the Default
Mody said: “Consensus amongst credit folks we spoke to over the weekend is that GPU backed loans will be the go to option for these companies. Unsecured debt will be less desirable, especially at 15%.” That shifts financing risk onto chip values.
Unsecured borrowing near 15% makes long-dated data centers hard to justify. Secured loans cost less because lenders can claim the hardware.
Nebius Group (NASDAQ:NBIS) entered its first senior secured facility, about $775 million backed by GPUs and contracted cash flows, in July 2026. If used GPU prices fall, the collateral declines and lenders tighten terms.
Meta’s Expected Stock Sale Comes Down to Size
Analysts expect a Meta stock sale, and Mody said the open issue is size: “The biggest question is not whether META will issue stock, but how big META’s equity offering could be. They say the market is comfortable for 30 billion.” Meta has not announced an offering.
Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) completed an $80 billion stock issuance a couple of months ago. Dilution spreads future profits across more owners.
Meta’s apps reach over 3.6 billion daily active people. AI spending is exceeding even that level of cash generation.
Long-term debt already reached $83.66 billion, and issuing stock would likely let Meta avoid borrowing near 15%.
What Meta’s Expected Raise Means for Shareholders
The size and terms of Meta’s raise remain unknown, which leaves the valuation case uncertain. At $705.44 and a trailing P/E of 26, dilution and an open-ended spending cap limit upside for existing holders.
NVIDIA sits in a different position. At $217.09 and a trailing P/E of 44, it costs more, but it gets paid whether buyers use stock, GPU-backed loans, or cash.
Steady H100 pricing points to durable demand, and NVIDIA guided third-quarter revenue to $108.0 billion, plus or minus 2%.

A smaller-than-expected raise or clear AI revenue disclosure from Meta would ease concerns about dilution and its spending payoff. Hyperscaler earnings will show whether either arrives.
The post AI chip stocks bounce back as hyperscaler earnings loom, META equity raise in focus appeared first on 24/7 Wall St..
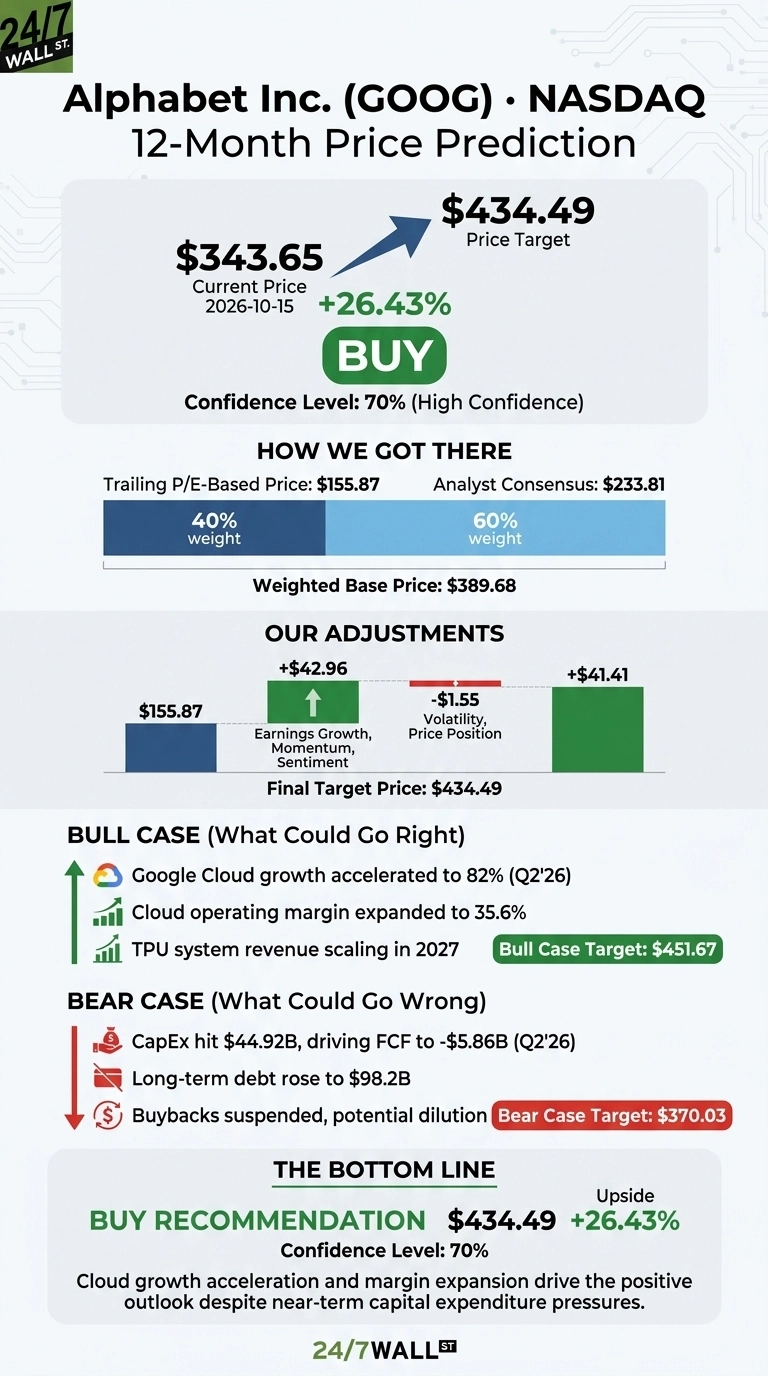
]]>The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $434.49 over the next 12 months. With shares at $343.65, that works out to 26.43% upside. The stock earns a buy rating with 70% confidence, which is solid but measured conviction.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $343.65 |
| Price Target from 24/7 Wall St. | $434.49 |
| Upside/Downside | 26.43% |
| Recommendation | BUY |
| Confidence Level | 70% |
Three things drive our call. Google Cloud growth sped up to 82% last quarter. Total revenue grew 24.2%. And the stock now sits well below its highs even as the business gets stronger.
A Blowout Quarter That Pushed Shares Lower
In Q2, Alphabet earned $9.11 per share against a $3.0427 estimate. Revenue came in at $119.796 billion, ahead of the $116.907 billion consensus. A $99.03 billion gain on equity securities inflated that EPS figure. The stock still fell 6.89% on earnings day.
Over the past week, shares moved -1.07%. Over the past month they moved -0.6%, and they are about 7.2% below their mid-July level. Year to date, the stock is up 9.73%. It trades 14.9% below its 52-week high of $403.96.
Why Bulls See $450 and Beyond
Cloud backlog reached $514 billion, and management expects to recognize just over half of it as revenue within 24 months. Cloud operating margin expanded to 35.6% from 20.7%. The Gemini app has 950 million monthly users.
The bulk of TPU system revenue is expected to arrive in 2027. The CEO described the opportunity this way: “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.” All of that TPU and cloud expansion has to be powered, cooled, and networked by someone, and we covered seven of those suppliers in a free AI infrastructure report.
Wall Street generally agrees. Analysts count 13 Strong Buys, 44 Buys and 5 Holds, with a consensus target of $420.36. We don’t have price targets from individual firms. Our bull case reaches $451.67.
Capex, Debt and Dilution Are the Risks Worth Watching
Capex hit $44.92B, which drove quarterly free cash flow to -$5.86B. The company’s long-term debt rose to $98.2B from $46.5B. Buybacks are suspended, and a stock sale program of up to $40B could dilute existing shareholders. Regulators also remain a risk, as the $3.5B European Commission fine showed.
Cash flow gives bulls a solid response. Trailing 12-month free cash flow is still $53.3 billion, backed by $185.7 billion in operating cash flow. The bear case still lands at $370.03, which is above today’s price.
Alphabet Trades at a Steep Discount to Microsoft and Meta
| Company | P/E | P/FCF |
|---|---|---|
| Alphabet | 14x | 58x |
| Microsoft | 30x | 59x |
| Meta Platforms | 27x | 35x |
Microsoft (NASDAQ:MSFT) is Google Cloud’s most direct AI infrastructure rival. Azure grew 43% last quarter, well below Google Cloud’s 82% rate. Even so, Microsoft trades at about twice Alphabet’s earnings multiple.
Meta Platforms (NASDAQ:META) competes for the same digital ad budgets and is spending heavily on AI too. Its revenue grew 27.96%, but quarterly free cash flow fell to $784 million. Alphabet’s P/E is lower partly because equity profits inflate its earnings. Even after allowing for that, the gap with both peers makes our target look conservative.
Alphabet Earns Our BUY Rating
The 24/7 Wall St. price target of $434.49 carries a buy rating and 70% confidence. The deciding factor for me is Cloud growth speeding up while margins expanded.
I’d grow more confident if TPU revenue scales on schedule in 2027. I’d turn cautious if capex keeps climbing while backlog growth stalls. On balance, I think the reward outweighs the risk.
The model projects Alphabet could trade at these levels if current growth trends and market conditions hold:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $366.54 |
| 2027 | $435.02 |
| 2028 | $518.10 |
| 2029 | $574.83 |
| 2030 | $642.85 |
The projections rest on Alphabet continuing to carry out its current strategy. The results could land well above or below these figures depending on Gemini 4’s launch, returns on AI spending and antitrust rulings.
The post This Mag 7 Stock Is Worth Watching for the Next 5 Years appeared first on 24/7 Wall St..
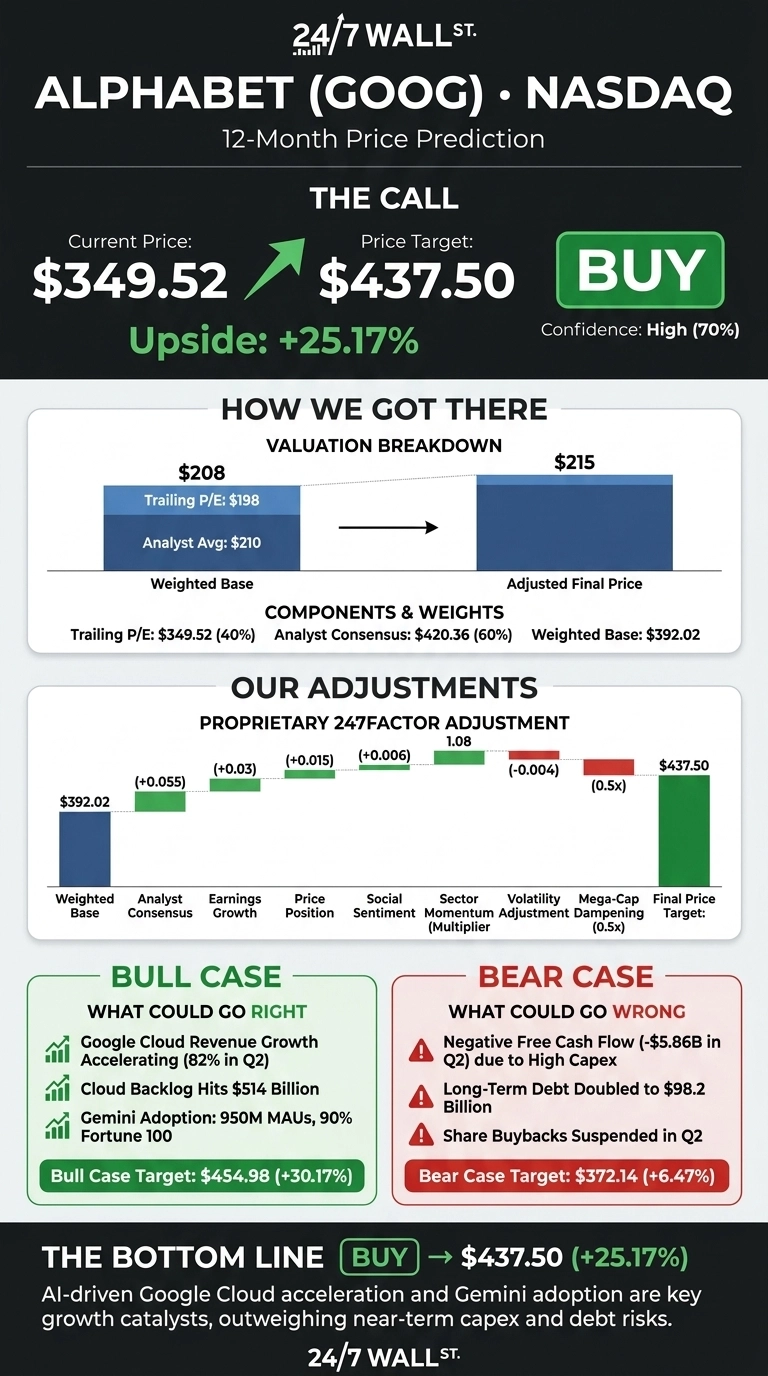
]]>Alphabet (NASDAQ:GOOG) trades at $349.52. The projected 24/7 Wall St. price target is $437.50, meaning 25.17% upside over the next 12 months. Our rating is buy with fairly high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $349.52 |
| Price Target from 24/7 Wall St. | $437.50 |
| Upside/Downside | 25.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
Google Cloud is the catalyst. Its revenue grew 82% in Q2, up from 63% in Q1 and 48% in Q4 2025. Backlog hit $514 billion. Our target stands above the 52-week high of $403.96, so reaching it would mean new highs.
Cloud Acceleration Keeps Alphabet Within Reach of Its High
GOOG has gained 1.52% over the past week, 4.28% over the past month, 11.7% year to date and 43.37% over the past year. Shares sit about 13.5% below the 52-week high and around 43.2% above the low of $244.03.
In the Q2 report, revenue of $119.80 billion beat the $116.91 billion estimate and rose 24.23%. EPS of $9.11 exceeded the $3.0427 estimate, although a $99.03 billion gain on equity securities inflated that figure. The cleaner signal was operating income, which rose 30.38% to $40.77 billion, while Search grew 17%.
Why Bulls See $455 and Beyond
The bull case rests on Cloud’s profitability. Cloud operating margin rose to 35.6% from 20.7% a year earlier. Management expects just over 50% of the backlog to become revenue within 24 months. Gemini reached 950 million monthly users, nearly 90% of the Fortune 100 use Gemini Enterprise, and Gemini 4 is in pre-training.
Most TPU system sales revenue is expected in 2027. Analysts rate the stock 13 Strong Buy, 44 Buy and 5 Hold, with no Sell ratings. Our bull case is $454.98.
Negative Free Cash Flow Is the Cost of the Buildout
Capex doubled to $44.92 billion, which drove free cash flow to -$5.855 billion. Long-term debt rose from $46.5B to $98.2B, a $49.6 billion equity raise diluted holders, and buybacks were suspended.
Higher-cost third-party capacity may also pressure Cloud margins in Q3. Bulls would answer that operating cash flow grew 40.8%, and the backlog shows demand is already signed. Our bear case of $372.14 is still above today’s price.
Alphabet Trades at a Discount to Microsoft and Meta
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Alphabet | 15 | 24.23% |
| Microsoft | 30 | 17.75% |
| Meta | 28 | 27.96% |
Microsoft (NASDAQ:MSFT) belongs here because Azure is Google Cloud’s closest rival. Azure grew 43%, about half the pace of Google Cloud, yet Microsoft trades at around twice Alphabet’s trailing multiple. Microsoft’s operating margin of 46.8% helps explain that premium.
The closest match on ads and capex is Meta Platforms (NASDAQ:META). Its Q2 EPS of $6.18 missed the $7.2214 estimate, and operating margin fell to 31%. Alphabet’s trailing P/E is depressed by equity gains, but even its forward P/E of 22 stands below both peers’ trailing multiples. That makes our target look conservative.
Cloud Momentum Drives Our $437.50 Target
The 24/7 Wall St. price target is $437.50, with a buy rating and 70% confidence. The main factor is Cloud growth that keeps speeding up at scale.
The Q3 report will show whether the backlog is converting to revenue and Cloud margins are holding up. The key risk is capex that keeps rising while Cloud growth slows down. For now, the data supports the bulls.
Over a longer horizon, here is where our model projects Alphabet could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $437.50 |
| 2027 | $487.93 |
| 2028 | $544.17 |
| 2029 | $606.90 |
| 2030 | $676.85 |
These projections assume Alphabet keeps executing on its full-stack AI strategy. Results could swing significantly in either direction depending on how Gemini 4 is received and whether AI capex realizes an adequate return.
The post Prediction: One Major Catalyst Could Send Alphabet Stock to New Highs appeared first on 24/7 Wall St..
]]>The press and savvy investors have combed through Anthropic’s IPO documents. On Sunday, they found something called the Anthropic Long-Term Benefit Trust. It holds only 5% of Anthropic shares. Among other things, it can grant stock to non-profits. More importantly, it appears to have control over the Anthropic board.
The Long-Term Benefit Trust can appoint most of the AI giant’s board. It can appoint four board members. According to The Wall Street Journal, “Trustees can also block corporate actions. Its mandate is to steer AI for humanity’s long-term benefit.” Board members are not paid. The group also has some say in issuing debt and selling more than half the company.
Anthropic has already appointed a very powerful member to the oversight organization. In a government filing, the company announced: “Anthropic’s Long-Term Benefit Trust (LTBT) has appointed Dr. Ben Bernanke, a Distinguished Fellow at the Brookings Institution and former Chair of the Federal Reserve, as its newest member.” Dr. Neil Buddy Shah, the CEO of the Clinton Health Access Initiative, has also already been appointed.
It is not unusual for a board’s appointments to rest in one set of hands. A number of companies, from Meta (NASDAQ: META) to Alphabet (NASDAQ: GOOG) to Ford (NYSE: F), have dual-class voting structures. However, founders almost always control them, presumably because financial success is their main goal. Additionally, they control the sale of all or part of the company.
The new group could open a Pandora’s box of uncertainty about the AI company’s cutting-edge advances. If the LTBT views a management decision as something other than a “long-term benefit,” what do management and the rest of the board do?
Anthropic is in a race against Chinese AI advances and those of its major competitors like OpenAI. Can it afford to have any of its initiatives blocked? So far, the federal government has stayed out of this governance. IPO investors may see this as a risk to Anthropic’s ability to innovate without interference.
The post Can Anthropic’s Shadow Board Cripple Its IPO? appeared first on 24/7 Wall St..
]]>On October 16, 2026, the US Court of Appeals for the Ninth Circuit reversed the class certification orders in LoSavio v. Tesla (No. 25-7927). The suit claims Tesla (NASDAQ:TSLA) falsely advertised that cars sold since October 2016 had the hardware needed for full self-driving.
Circuit Judges Ronald Gould, Jay Bybee and Daniel Bress sent the case back to US District Judge Rita Lin, who had certified three classes of California buyers. Class status turns thousands of small claims into one large liability, so losing it cuts Tesla’s exposure in this case.
The stock fell anyway, closing at $354.72, down 2.13% in a move that tracked a broader tech selloff rather than the ruling. For a company valued at $1.40 trillion, the open question is whether self-driving software and robotaxis deliver the revenue that valuation assumes.

What the Ninth Circuit Actually Decided
The panel found that individual questions about what each buyer saw before purchase made class treatment inappropriate. The challenged statement sat on Tesla’s Autopilot page. Buyers did not have to visit that page to complete a purchase, so plaintiffs could not show every class member was exposed to it.
The order reversed two damages classes and one injunctive-relief class. The ruling addresses class status only; the court made no finding on whether Tesla’s hardware claims were true, and the case continues before Judge Lin.
The memorandum is unpublished, so under Ninth Circuit Rule 36-3 it holds no other case. Plaintiffs’ lawyers said, “we think the panel did not fully appreciate the unique circumstances here.” Tesla has denied the claims and did not immediately respond to a request for comment.
Why Losing Class Status Shrinks the Threat
Few buyers will hire a lawyer to recover the cost of a software package alone, because the legal bills would exceed the claim, but a class pools those claims and that pooling is where the financial pressure comes from.
Individual buyers can still sue, and plaintiffs can try to certify a narrower class of buyers who can show they saw the statement. That group would be smaller and harder to prove.
The exposure reasoning likely reaches further. Advertising claims built on pages buyers had to seek out will struggle to proceed as classes, while claims tied to material every buyer saw would stand on stronger ground.
How Much This Matters for Tesla
Potential damages in this case were never disclosed, so the savings cannot be sized. The business itself runs on current subscribers, with 1.48 million active FSD subscriptions in the second quarter of 2026.
That quarter brought revenue of $28.24 billion, but non-GAAP EPS of $0.33 missed the $0.5367 estimate, and free cash flow was -$1.092 billion. The shares trade at 369 times earnings. The stock fell to $353.50 after hours, sits closer to its 52-week low of $297.38 than its high of $498.83, and has returned -21.12% in 2026 and -7.31% over the past week.
What Third-Quarter Results Need to Show
Tesla is scheduled to report after the close on October 21. Investors will look for FSD subscription growth, unsupervised robotaxi rides spreading beyond Austin, and recovery from the 1.4% operating margin of the second quarter.

What Could Change the Outlook for Tesla Shares
The ruling removes one legal uncertainty, but the valuation still requires self-driving and robotaxi revenue far beyond what the reported numbers show, and shrinking margins, negative free cash flow, and an earnings miss make that premium hard to defend before third-quarter results arrive. One contrast is Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), whose Waymo unit runs driverless rides inside a company funded by profitable search and cloud businesses.
This bearish view would weaken if the October 21 report shows operating margin clearly above the second quarter’s level alongside new unsupervised robotaxi markets. If the margin stays flat, watch for the shares to test the $297.38 low.
The post Tesla Just Won in Court: Self-Driving Buyers Can’t Sue as a Class appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) trades near $349.52 a share. That is the starting point for a $1,000 bet and a target year of 2030.
Google’s parent is coming off a quarter where revenue grew 24% year-over-year and Google Cloud grew 82% to $24.8 billion, so it makes sense to ask what that growth could do for your money.
What $1,000 in Google Could Become
Our model does not produce a stand-alone 2030 target. Its nearest horizon is five years out, and that is where the concrete numbers below are grounded.
In the base case, a $1,000 bet would reach roughly $1,936.50 at the end of the five-year window, a total return of 93.65%. That rests on a modeled per-share target of $676.85, which works out to an annualized return of 14.13%.
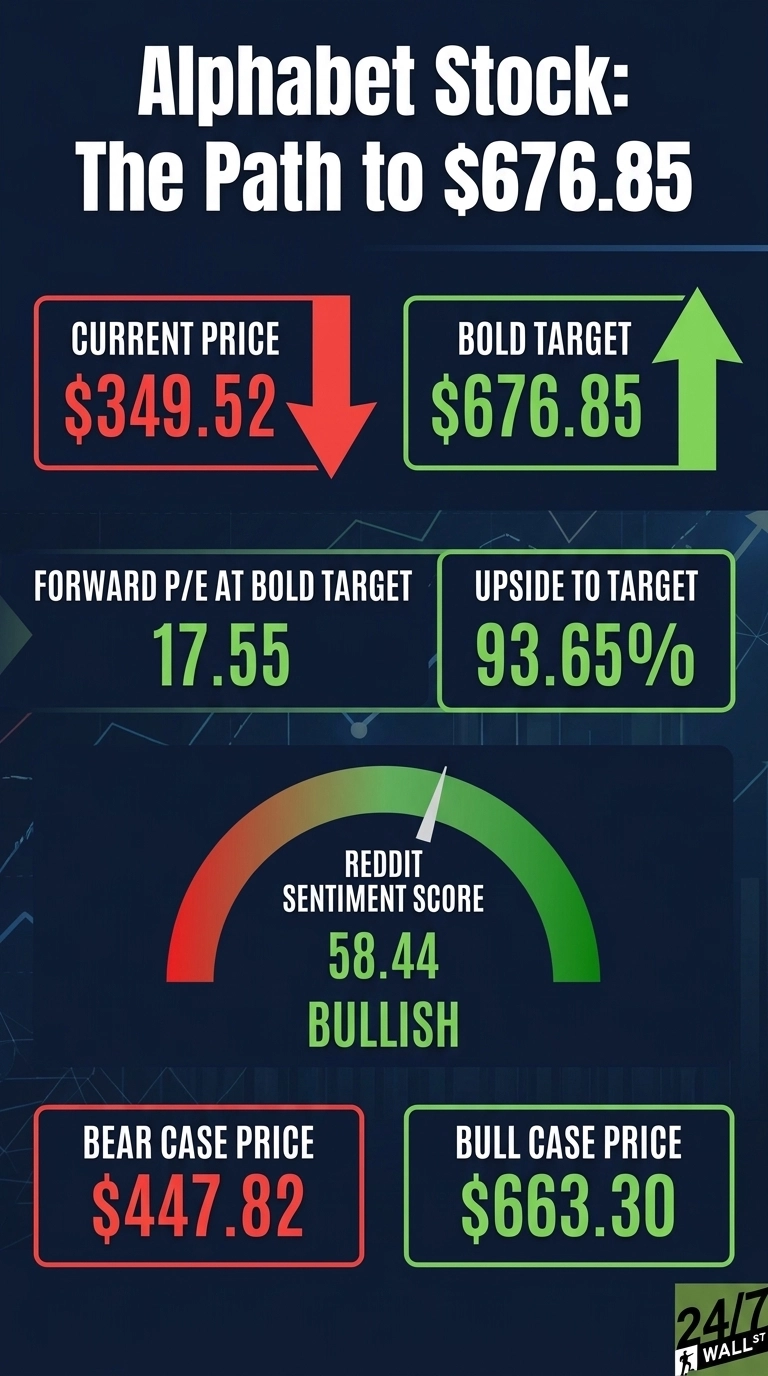
Now the key math. If Google compounds at exactly 10% a year for four years, $1,000 grows to about $1,464.10 by 2030. Treat that as an illustration only. The model also sets quarterly checkpoints along its five-year path.
Its October 2030 checkpoint has a base price of $640.23, which would make the bet worth about $1,831.74. The bull checkpoint of $622.52 means about $1,781.07, and the bear checkpoint of $432.82 means about $1,238.33. The 2030 figures serve as illustrative milestones, not the model’s formal target.
Five-Year Scenarios for a $1,000 Stake
| Scenario | Target Share Price | Total Return | Value of $1,000 |
|---|---|---|---|
| Bear | $447.82 | 28.12% | $1,281.20 |
| Bull | $663.30 | 89.77% | $1,897.70 |
| Base | $676.85 | 93.65% | $1,936.50 |
The table runs from lowest to highest. The bull path rises faster early on, which is why its one-year target of $454.98 sits above the base case’s $437.50, but at the five-year mark it ends slightly below the base case. The one-year bear target is $372.14.
Wall Street’s consensus target is $420.36, supported by 13 strong buy ratings, 44 buys, 5 holds and 0 sells. The model’s confidence level is 0.7 on a 0 to 1 scale. This is a projection, not investment advice.
Three Engines Behind the Upside
Cloud Backlog Gives Visibility
Google Cloud’s backlog reached $514 billion, and management expects to recognize just over 50% of it within 24 months. Cloud operating margin rose from 20.7% to 35.6%, and Google says demand still exceeds its supply of capacity.
AI Is Lifting Search
Search and other revenue grew 17% to $63.3 billion. AI mode has passed 1 billion monthly active users, and management says it is “driving an incremental increase in search queries overall.”
Gemini Is Scaling Fast
The Gemini app has 950 million monthly active users, and Google’s model APIs handle about 22 billion tokens per minute. Nearly 90% of Fortune 100 companies use Gemini Enterprise.
On the July call, CEO Sundar Pichai said that “over the past year, we’ve gotten more bullish on the opportunities ahead.” Alphabet has also exceeded EPS estimates for an 11th consecutive quarter.

Risks That Could Shrink Your Stake
The AI expansion is expensive. Second-quarter capex came to $44.9 billion, which drove free cash flow to negative $5.9 billion. Long-term debt rose from $46.5B to $98.2B, and interest expense was up about 5x year over year.
Alphabet raised roughly $70 billion in equity and debt, set up an at-the-market program for up to $40 billion in stock, and suspended its buyback. Each of those can dilute existing shareholders.
Reported earnings may also overstate the underlying trend. Second-quarter EPS of $9.11 included a $99.03B gain on equity securities. The trailing P/E of about 15 looks cheap partly because of that gain. Regulatory scrutiny remains an issue, and with a beta of 1.211, the stock tends to move more than the overall market.
Where Your $1,000 Could Land
Across the model’s five-year scenarios, a $1,000 position in Google ranges from about $1,281.20 to $1,936.50.
A steady 10% annual return would put it near $1,464.10 by 2030. These are scenarios, not guarantees. Keep an eye on Cloud backlog conversion and free cash flow in each earnings report.
The post If Google Grows At 10% a Year, Here’s What $1,000 Becomes By 2030 appeared first on 24/7 Wall St..
]]>On October 15, 2026, Reuters reported, citing people familiar with the matter, that some current and prospective Anthropic investors are considering a $1.5 trillion valuation for the AI company’s planned November IPO. That is below the roughly $2 trillion investors had expected.
Attendees discussed the lower figure at an investor day at Anthropic’s San Francisco headquarters. Some buyers raised the number. Anthropic has published no price or target of its own, and the company did not immediately respond to requests for comment.
Anthropic is private, so its read-through to public markets runs through Amazon (NASDAQ:AMZN) and Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL). Each one is an Anthropic investor, a computing supplier, a distribution partner, and a competitor.
Both stocks moved modestly on October 15. Amazon closed at $254.76, up 0.27%, and Alphabet Class A closed at $349.22, up 0.45%. Both companies have booked very large paper gains on Anthropic, and a cheaper IPO would make the next round of those gains smaller.
Slowing Growth Explains the Lower Number
Anthropic told prospective investors that third-quarter revenue reached $16.8 billion, up 45% from the second quarter. Some investors were disappointed because Anthropic’s second-quarter revenue of $11.6 billion had more than doubled from the first quarter.
At this size, buyers pay more for growth than for revenue. A slower quarter-over-quarter rate lowers the multiple they will accept.
Anthropic says it was profitable on an adjusted basis, meaning profitable after excluding certain costs it chooses to exclude. Anthropic still reported a $42 billion loss for 2025 in its IPO prospectus, seen in September, so it is reasonable for investors to hold the price down.
Anthropic’s Spending Commitments Still Flow to Suppliers
Anthropic’s IPO prospectus also listed at least $518 billion in Anthropic commitments over a decade for cloud services, computing and infrastructure. Amazon and Alphabet are among the suppliers receiving that money.
Amazon has reported that Anthropic committed to secure up to 5 GW of Trainium chips, and Anthropic is also a Google Cloud customer. Both companies keep their Anthropic revenue undisclosed.
A cheaper IPO leaves signed commitments in place. Slower growth could still limit how fast Anthropic’s spending grows beyond them, and the suppliers downstream of that spending (power, cooling, networking, the unglamorous backbone) are a separate trade from the model labs themselves. We covered seven of those AI infrastructure names in a free report.
Smaller Paper Gains Ahead for Both Stocks
Amazon’s second-quarter net income of $62.647 billion included $53.4 billion in pre-tax non-operating income, primarily from Anthropic. Alphabet’s $112.107 billion in net income included a $99.03 billion gain on equity securities, which is the line where any change in Anthropic’s value shows up.
Both companies keep the carrying value of their stakes undisclosed, so the dollar effect of the lower valuation is unknown. Still, future gains would be smaller than the higher figure implied. These gains raise reported earnings per share without adding any cloud revenue.
Amazon and Alphabet are also competing with Anthropic. Amazon CEO Andy Jassy said on July 30, 2026, “We are pursuing our own frontier model,” and Alphabet’s Gemini App has 950 million monthly active users.
A less highly valued Anthropic makes little difference to either company. The startup remains a major customer, and a lower price weakens the argument that one lab will control the market.
Google Cloud Growth Supports Alphabet’s Valuation Case
Alphabet’s cloud results stand apart from the IPO question. Google Cloud revenue grew 82% to $24.77 billion in the second quarter, and that growth is independent of Anthropic’s IPO price.
Equity gains make Alphabet’s P/E of about 16 look lower than it otherwise would, which benefits the multiple for investors who rely on it. Amazon trades at about 35 times earnings with AWS growing 37%. Amazon offers more direct exposure to Trainium, though at a much higher multiple.

The test comes with the November pricing. If the IPO prices below the lower figure investors discussed, or if Google Cloud growth falls back under the first quarter’s 63% pace in Alphabet’s next report, the case for Alphabet’s cloud-driven growth weakens.
The post Some Anthropic Investors Now See a $1.5 Trillion IPO, Not $2 Trillion appeared first on 24/7 Wall St..
]]>Google Quantum AI published “Magic state cultivation on a superconducting quantum processor” in the journal Science on October 15, 2026. The paper is the first hardware demonstration of a technique that cut errors 40-fold compared with states prepared without it.
Class A shares of Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) rose 0.45% that day to close at $349.22, which valued the company at $4.27 trillion. The small move reflects how a stock this large trades on search, cloud, and AI, and investors treated the paper as good science with a distant return.
A lab result like this changes very little. It strengthens a long-term research effort that Alphabet can fund with its own profits.
What Google Demonstrated on Willow
The experiment ran on Google’s Willow processor. It produced T-states, a type of magic state, at 99.99% logical fidelity, which means an error rate of 0.0001 or less.
Google researchers Craig Gidney, Noah Shutty, and Cody Jones developed the method in 2024. It places an imperfect state in a small chip region. It checks the state with measurements, discards failures, and extends the survivors into a larger error-correcting code.
Only 8% of attempts passed the filter. Throwing away most attempts is how the method works, because it gives up volume to get quality.
Alphabet CEO Sundar Pichai reacted on X that day. He wrote: “Some magical progress towards “magic state” in quantum!”
Why Magic States Set the Size of a Quantum Computer
Complex quantum calculations need magic states. Each one can be used only once, so the machine has to keep making new ones. Some estimates say up to 95% of a quantum computer’s capacity could go to producing them.
Without a cheap, reliable supply of magic states, a quantum computer can only run calculations an ordinary computer already handles, and making them more cheaply reduces how large a machine you would need to build.
How Much Quantum Is Worth to Alphabet Shareholders
Alphabet does not report quantum as its own division. The closest line is Other Bets, which brought in $382 million in the second quarter of fiscal 2026. Total revenue that quarter was $119.8 billion.
Google Cloud brought in $24.77 billion in the same quarter, up 82%, and Cloud is what moves the stock. Google disclosed no revenue, customers, or timeline tied to the quantum result.
The quantum lab is paid for by a business that earned $40.77 billion in operating income in that one quarter. Smaller quantum companies depend on investors staying interested enough to fund them.
There’s still a bottleneck.
Magic states are still a constraint. Cultivation now has to work at a much larger scale, inside a machine running a useful calculation, before it changes what quantum hardware can do.
Other large technology companies and smaller listed quantum firms have their own error-correction plans; Google leads in one technique, and the field is competitive.
What Drives Alphabet’s Valuation From Here
Alphabet’s investment case rests on the core business, and quantum is a long-term research effort that shareholders get at no added cost.
The shares are up 11.79% so far in 2026 and 39.48% over the past year. They trade at about 16 times trailing earnings. But that multiple looks cheaper than it really is because second-quarter net income included a $99.03 billion gain on equity securities.
The main risk is spending. Second-quarter capital spending, the money spent on data centers and equipment, reached $44.92 billion, and free cash flow, the cash left after that spending, was negative $5.86 billion. That expansion also feeds a long list of suppliers in power, cooling, and networking (we featured seven of them in a free report on the AI infrastructure trade).
The thing to check is Cloud growth in the third-quarter earnings report. If growth stays near the second quarter’s pace, the case for the stock holds. A sharp slowdown would hurt the stock far more than a quantum paper could help it. On the quantum side, look for a follow-up paper showing cultivation supplying a logical computation at larger scale.
The post Google Just Cut a Major Quantum Computing Error Rate by 40 Times appeared first on 24/7 Wall St..
]]>Azure group at Microsoft (NASDAQ:MSFT) was told to cut costs by at least 20%, and Microsoft denied it the same day. The stock closed down 1.80% at $533.69. That left a $3.96 trillion market value, back below $4 trillion after a $4.04 trillion close on October 13.

The report, which cited people familiar with the plans, said Girish Bablani, head of the Azure group that builds software for Microsoft’s cloud servers, asked team leaders for the cuts. That group has about 11,500 staff.
Azure brought in $101.9 billion in revenue in the 12 months ending in June, up 40% from a year earlier. A business growing that fast seldom goes looking for a fifth of its cost base unless the growth costs more than it appears to or the money is needed for something bigger, and at Microsoft both may be true.
Reported Target Versus Company Denial
The reported savings would help pay for AI data center spending and for higher pay to keep engineers that rivals such as Anthropic are trying to hire. Ending contracts with outside vendors was one possible step.
The report did not say whether it would cut jobs. A spokesperson said “Azure leadership has not directed teams to develop cost-cutting plans,” and added, “Every responsible company prepares for a range of scenarios and market dynamics, both positive and negative.”
Capex, meaning money spent on data centers and chips, reached $115.95 billion in fiscal 2026. Management expects it to reach about $175 billion in fiscal 2027.
That spending has to come out of the operating business. In the June quarter, free cash flow fell 23.19% to $19.64 billion, and Microsoft has guided fiscal 2027 operating margins down less than a point. Cutting costs inside Azure is the most direct way to hold that margin while the capex bill keeps climbing.
Talent and Leadership Signals
If Microsoft pays more to keep engineers and still cuts costs by a fifth, the savings would have to come from contractors, vendors, and projects. Those suppliers are the first places to look for any effect.
Cloud chief Scott Guthrie is also reshaping Azure’s leadership, and Arun Ulag is set to manage Bablani. A reorganization that arrives with a cost push points to closer control of the unit.
Chief financial officer Amy Hood addressed capacity on the July 29 call. She said, “demand continues to exceed available supply.”
Commercial remaining performance obligations, which measure signed revenue Microsoft has not yet recognized, rose 84% to $678 billion. Given the backlog and a record-high close on October 13, a small dip on a denied report looks reasonable.


What MSFT Investors Should Watch Next
If the reported cuts are real, they target overhead so Microsoft can pay for capacity customers have already signed up for, and that is a funding decision tied to strong demand. The shares are up 11.06% year to date and trade at about 30 times earnings, a multiple investors can weigh against this growth.
For comparison, Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) has posted faster cloud growth, with Google Cloud’s growth running from 32% to 63% over recent quarters. Both companies report after the close on October 28. If Microsoft keeps its margin outlook and its approximately $175 billion capex plan, the report likely carries little weight for the outlook. A lower margin outlook or disclosed restructuring charges would change that view.
The post Microsoft’s Azure Grew 40% and Is Still Reportedly Hunting for 20% Cost Cuts appeared first on 24/7 Wall St..
]]>Yesterday, Anthropic announced that its revenue grew 50% quarter over quarter to $16.8 billion. On the back of an envelope, its 2027 revenue could exceed $100 billion. That is about Morgan Stanley’s annual revenue. However, Anthropic’s top line could still be rising in the high double digits, just as Nvidia’s (NASDAQ: NVDA) is today.
With that growth and its position at the center of the AI sector, Anthropic’s IPO valuation could reach a staggering $2 trillion.
Anthropic’s revenue, revenue growth, and valuation are a real challenge to the stock prices and market caps of publicly traded companies whose shares are largely based on their AI businesses. Microsoft (NASDAQ: MSFT) is a prime example. Its market cap is $3.9 trillion. But its shares have lagged the market badly over the last year. They are up only 4%, while the S&P 500 is higher by 16%.
Microsoft has a huge drag. That is its legacy business, which will be bigger than its AI-based operations for the next several quarters, or much longer. This is a boat anchor for valuation.
Microsoft’s financials are nothing special compared to most other huge public tech companies. In its most recent quarter, revenue was $90 billion, but that was up (only) 18%. Diluted EPS was up 32% to $4.81. The first full paragraph of the earnings release mentioned Xbox.
AI was mentioned when Microsoft released its most recent quarterly figures. However, this was primarily tied to Microsoft Cloud and the Azure segment. AI revenue was not called out separately in a way that would excite investors.
Microsoft is not the only large tech company with this challenge. Alphabet (NASDAQ: GOOG), Meta (NASDAQ: META), and Amazon (NASDAQ: AMZN) share the challenge. Their legacy revenues are huge, and the growth of these is not spectacular.
Without mid-double-digit growth, these huge tech companies and their investors have a problem.
The post Anthropic Is Growing 50%, Microsoft Isn’t appeared first on 24/7 Wall St..
]]>It was a strong quarter for Google (NASDAQ:GOOG). Revenue hit $119.80B, up 24.2%, and Google Cloud grew 82% to $24.77B.
Sundar Pichai called it “an amazing quarter”. Even so, shares are up just 12.03% year to date at $347.86, almost exactly where they stood after that report ($348.10). Can Google hit $500 by 2029?
What’s Holding Google Back Right Now
The problem is cash. Capex jumped 100% to $44.92B, and free cash flow came in at -$5.86B. The company’s long-term debt rose from $46.5B to $98.2B, and the buyback was suspended in Q2 2026. Net income of $112.11B was also inflated by a $99.03B gain on equity securities, so the market discounts that headline.
That explains why shares sit 13.9% below their 52-week high of $403.96. They are rebounding, up 3.09% in a week and 6.84% in a month. A beta of 1.211 means the moves run a bit wider than the market’s.
Wall Street Sees 20.8% Upside. Our Model Says 26%
The consensus target is $420.36, meaning 20.8% upside. Of 62 analysts, 13 rate it a strong buy, 44 a buy, 5 a hold and 0 a sell. The base case is $438.32, or 26.01% upside, with a range from $371.66 to $455.71. Model confidence is 0.7, which is solid without being certain.
The Street seems too conservative. 92% of analysts are bullish, and earnings growth adds 0.03 to our factor. Cloud backlog reached $514 billion, and just over 50% of it should convert to revenue within 24 months.
Here’s What It Takes for Google to Reach $500
Reaching $500 from today’s price of $347.86 would require a gain of 43.7%.
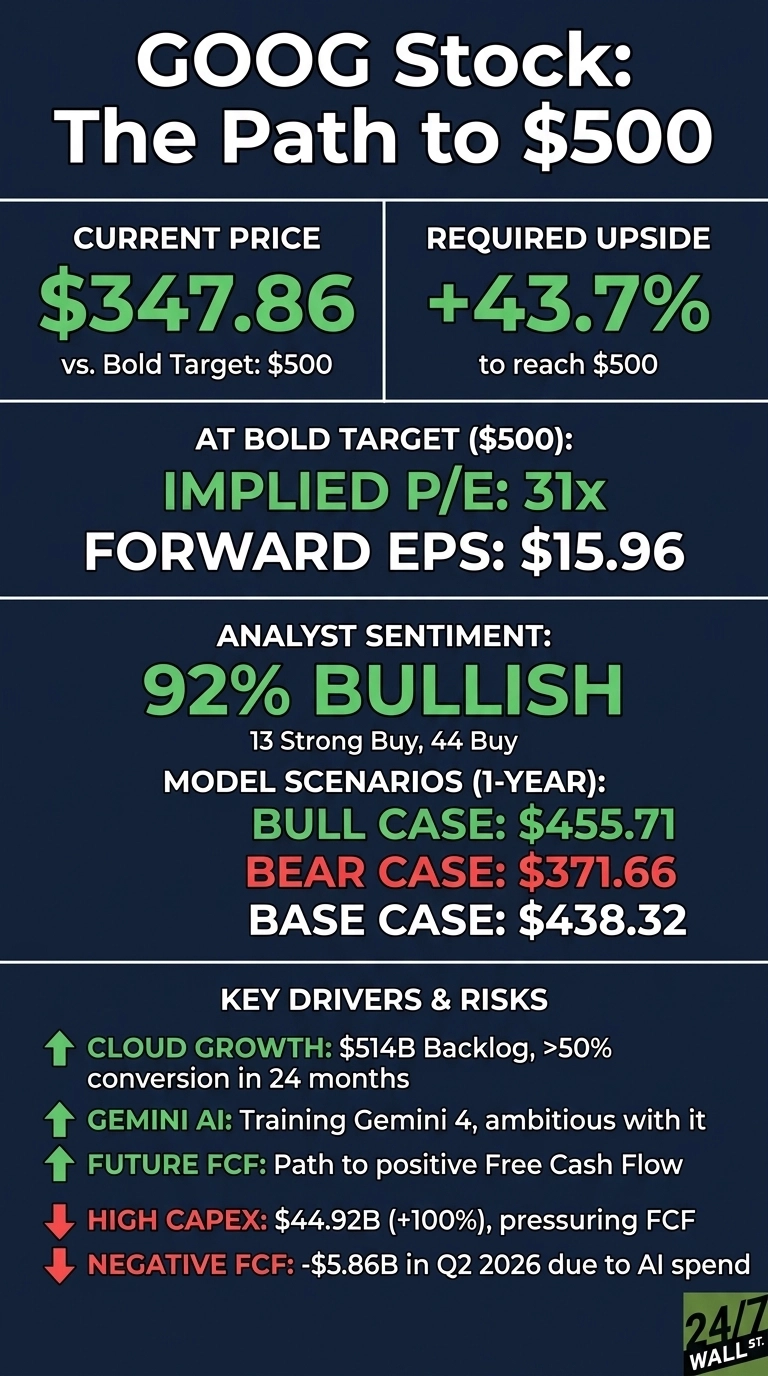
A forward P/E of 22 meaning forward EPS of $15.96. At $500, that works out to a forward P/E of 31x. The base case of $438.32 already meaning 27x, so the bold target needs about 4 more turns of multiple expansion.
That looks achievable. Our adjustment factor of 1.12 is driven by a sector multiplier of 1.08 and a 0.055 analyst-consensus contribution. As TPU system revenue arrives in 2027, forward EPS should rise, and today’s multiple would contract. Barron’s reports that Google Workspace now has AI agents. Pichai also said: “We are now training Gemini 4, and we’ve been very ambitious with it.”
Capex growing faster than revenue would keep free cash flow negative. The flip side is that all that AI spending has to be powered, cooled, and networked by somebody, and we rounded up seven of those non-chipmaker suppliers in a free report.
Where Google Trades Today vs Its Earnings Power
At about 22x forward earnings and a PEG of 1.197, Google looks reasonably priced for a company with 12 straight quarters of double-digit revenue growth.
Shares trade between the 52-week low of $240.12 and the high of $403.96. The stock has gained 804.63% over 10 years. Our five-year path puts the stock at $573.02 in October 2029.
$500 Is a Stretch, But Here’s Why It’s Possible
Hitting $500 calls for a 43.7% gain. That’s ambitious, but within reach.
Three things need to happen. Cloud backlog has to convert on schedule, Gemini 4 has to keep Google at the frontier, and free cash flow has to turn positive again. A extended capex bout without matching revenue would wreck it. We wouldn’t expect returns like this every year, but we’ve outlined the path for how Google could reach $500 in 2029.
The post Prediction: AI Could Transform This Magnificent 7 Stock Over the Next 3 Years appeared first on 24/7 Wall St..
]]>Anthropic told potential investors on Wednesday that it “reached profitability on an adjusted basis during the quarter”, with Anthropic putting third-quarter revenue at $16.8 billion. The company declined to comment on the figures or on when it plans to list.
Its two largest listed investors, Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) and Amazon (NASDAQ:AMZN), both fell that day. Alphabet closed at $347.64, down 1.74%, and Amazon closed at $254.08, down 1.74%.
The most valuable AI asset either company has is a business neither one controls. For shareholders, what matters is which company captures more of that value when Anthropic lists.
Adjusted Profit Sits Beside Large Reported Losses
Documents previously reviewed by Bloomberg showed Anthropic revenue of $386 million in 2024 and about $4.6 billion in 2025. The same documents showed an operating loss of more than $8 billion and a net loss of nearly $42 billion.
Adjusted measures usually exclude stock compensation and other noncash charges, so the claim tells you about the operating trend and little about bottom-line earnings. When the net loss is that much larger than the operating loss, the gap most likely comes from non-operating items such as fair-value changes on financing instruments.
Formal IPO marketing could start as soon as the week of November 9. Anthropic is aiming to trade before Thanksgiving and expects to list by year-end, although its plans are still fluid and the schedule could change.
On that timeline, both stocks could get a public mark on their stakes within weeks. Until shares trade, any valuation that potential investors suggest is only an opinion.
Alphabet Owns Upside Without Control
Court documents confirmed that Google has roughly 14% of Anthropic, and its contract caps the stake at 15%. The cap gives Alphabet upside without control.
Gemini competes directly with Claude, so the stake also protects Alphabet in part if a rival model disrupts its business. Alphabet’s second quarter included a $99 billion unrealized gain on equity securities. Even so, a 34% operating margin and 82% Cloud growth do more to drive the stock.
When it comes to Amazon, it invested about $8 billion starting in 2023 and has committed up to $20 billion more. Committed money earns an equity return only once it is actually invested. Amazon does not disclose its percentage.
Much of Amazon’s return comes through AWS. Anthropic has made a “multi-year, multi-gigawatt” commitment to Trainium chips, and AWS revenue rose 37% to $42.23 billion, its fastest growth in 18 quarters. The power, cooling, and networking suppliers behind that expansion keep showing up in our free AI infrastructure report.
Why Amazon Gains More From an Anthropic Listing
Amazon likely gets more of the value. With a market value near $2.74 trillion, versus about $4.33 trillion for Alphabet, an Anthropic stake of similar size would move Amazon’s value more. The Trainium contracts add to that gain.
Shareholders have already seen that value: Amazon booked a $53.4 billion pre-tax gain in the second quarter, mostly from Anthropic. The main risk is cash, since trailing free cash flow fell to -$7.6 billion after quarterly capex of $54.21 billion. A $496 billion AWS backlog gives that spending visible demand.
Alphabet offers a search and cloud business with a capped Anthropic option attached.

The post Anthropic Says It Turned an Adjusted Profit Ahead of Its Expected IPO appeared first on 24/7 Wall St..
]]>One of the clearest arguments for American AI this fall came on a late-night comedy show. CNBC anchor Sara Eisen made it while sitting beside Sen. Thom Tillis on HBO’s Real Time with Bill Maher. Where she said it matters, because the public fight over AI now plays out in front of voters, and investors mostly talk among themselves.
Her case was about competition with Beijing: “We do not want to not be on the side of progress. And we do not want to let China get ahead of us on this dangerous technology. We want to own it, and we want our best people doing it.”
The discussion passed over the money question underneath. The top five hyperscalers were expected to spend nearly $800 billion in 2026 and $1.3 trillion in 2027 on capital projects. That spending runs into local power grids, water systems and zoning boards. The political resistance is showing up faster than the revenue meant to pay for it.
Political Risk Now Sets the Timeline for AI Returns
Moratoriums and permitting fights decide where capacity gets built, how long it takes and what it costs, and when a project slips, its cash flows move further out, and discounting carries that delay straight into the share price. The timing gap already weighs on Amazon (NASDAQ:AMZN). It said data center spending starts about two years before servers can earn money, and its trailing free cash flow is -$7.6 billion.
On a free cash flow basis, Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) posted -$5.86 billion after $44.92 billion of quarterly capex. It also paused buybacks.
Equinix (NASDAQ:EQIX) announces a project only after it has cleared internal checks on power, connection and permitting. Management credits that sequence for keeping builds on schedule.
Why the Backlash Crosses Party Lines
Residents object to power draw, water use and their electric bills far more than to the software. One north Denver campus was projected to use up to 805,000 gallons of water a day.
In the PJM region, the grid’s independent market monitor concluded that data center load growth is “the primary reason” for tight supply and high capacity prices. Because the complaint is about household costs, it shows up in red and blue states alike, and Maryland and California moved to set large-load rate rules, while Indiana and Idaho moved to speed up permitting.
Because a utility bill is concrete, this kind of complaint carries weight with voters.
A Race Justifies Spending Without Guaranteeing Returns
Eisen’s China argument holds up well on national security grounds. A rival that controlled frontier AI would carry military and economic costs that no government will accept. As an investment thesis it is weaker, because spending a country needs can still let down the companies doing it.
To back frontier labs that also buy its chips, NVIDIA (NASDAQ:NVDA) has invested nearly $50 billion. Management said “some will call this circular financing,” and its supply commitments rose to $279 billion.
Builders who call AI inevitable are probably right about deployment. Electricity was inevitable too, but much of its long-term value flowed to customers and later entrants rather than to the original builders.
Sentiment Starts to Bite When It Becomes Law
Institutional money sets prices, and it kept moving toward AI. Over the past year the S&P 500 rose 19.15%, and over six months software stocks gained 41.46%.
Investors paid most for physical infrastructure, expecting the expansion to keep requiring hardware, with Vertiv (NYSE:VRT) up 47.86% year to date, ahead of Equinix at 36.81% and NVIDIA at 21.64%. Public mood starts to move prices once it turns into statutes, permit denials or utility rate decisions. That shift also separates AI companies by their exposure to local politics.
Chip designers and model developers have little such exposure. Anything that requiring land, a grid connection and a permit carries a separate risk, and that includes Equinix’s 52 expansion projects. Most investors miss that part of the story. The power, cooling and networking suppliers behind those sites are why we pulled seven of them into a free report on the AI buildout beyond the chipmakers.
Which AI Stocks Carry the Least Permitting Risk
In the bull case, Microsoft (NASDAQ:MSFT) says demand still exceeds supply, and NVIDIA says it can fill only about 70% of orders.
The bear case rests on concentration, heavy spending with no visible return at Alphabet and Amazon, and growing permitting friction. NVIDIA also starts from a value of roughly $5.46 trillion.
All things considered, the AI stocks with the least permitting exposure sit in the layer that zoning boards can least affect. That layer includes NVIDIA, plus Microsoft, which expects to stay free cash flow positive even with FY27 capex near $175 billion.
Vertiv raised its revenue guidance to $13.8 to $14.2 billion. Its gains so far, though, assume permits keep coming through on time.
The post Sara Eisen Went on Bill Maher and Said What Wall Street Will Not About the AI Race appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) Class C shares trade at $346.72, up 40.67% over the past year. What might a $10,000 stake become by 2031, five years from now?
Alphabet is worth a forward look because its AI spending is already showing up in revenue: Google Cloud is growing faster than at any point in the past several years, and Search is still expanding.
What $10,000 Could Become by 2031
The base-case scenario shows a $10,000 investment could be worth about $19,828 by 2031, a total return of 98.28%. That is close to a double.
Behind it is a five-year base-case target of $685.35 per share, which annualizes to 14.67% from a modeled starting price of $345.64. The model gives this forecast a confidence level of 0.7 on a 0-to-1 scale.
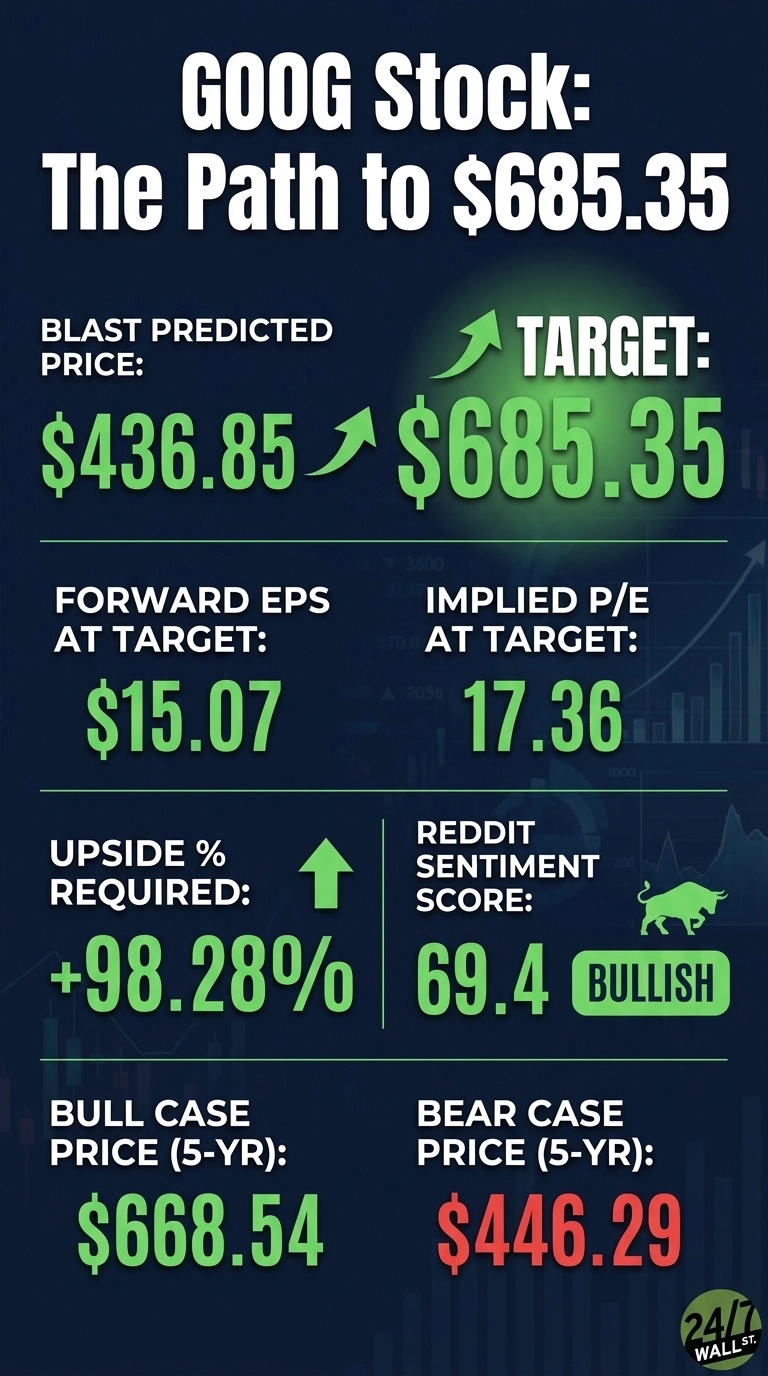
Three Scenarios for a $10,000 Stake
| Scenario (five-year) | Target Share Price | Total Return | Value of $10,000 |
|---|---|---|---|
| Base | $685.35 | 98.28% | $19,828 |
| Bull (optimistic) | $668.54 | 93.42% | $19,342 |
| Bear (conservative) | $446.29 | 29.12% | $12,912 |
Over five years, the model’s bull and base paths end up close together, and the base case actually finishes slightly higher. In practice, the model’s best results center around a double, while even the conservative case leaves your stake ahead of where it started.
The one-year view is more modest. Next year’s base-case target is $436.85, which would turn $10,000 into $12,639. Bull-case projections point to $13,139 and the bear case to $10,691.
Wall Street stands firmly on the optimistic side. Of the analysts covering the stock, 13 rate it a strong buy, 42 a buy and 5 a hold, with no sell ratings. Their consensus price target is $419.65.
What Could Push Alphabet Toward a Double
Cloud Is Becoming a Second Profit Engine
Last quarter, Google Cloud revenue rose 82% to $24.8 billion, and its operating margin expanded to 35.6% from 20.7% a year earlier. Backlog reached $514 billion, and management expects to recognize just over 50% of it within 24 months.
That is booked demand, which gives the base case real visibility (all of those data centers have to be powered and cooled by someone, and we rounded up seven of the companies doing exactly that in a free AI infrastructure report).
AI Is Expanding Search
Search and Other revenue grew 17% to $63.3 billion. AI Mode has passed 1 billion monthly active users, and the Gemini app has 950 million.
Alphabet also launched a Gemini AI agent aimed at OpenAI and Microsoft (NASDAQ:MSFT), Barron’s reported. On the earnings call, the chief executive said: “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
Earnings Estimates Keep Rising
Analysts expect EPS of $15.0715 next year, compared with $11.81 this year. That 2027 estimate has rose from $14.5333 90 days ago.
The stock trades at about 22x forward earnings, which leaves room for the share price to rise along with profits. Alphabet has also beaten EPS estimates for 11 straight quarters.
Risks That Could Derail the Double
The greatest risk to your $10,000 comes from Alphabet’s own spending. Capital expenditures reached $44.9 billion in the quarter, which drove free cash flow to negative $5.9 billion. Full-year capex guidance is $175B to $185B.
Alphabet’s debt has grown to about $100 billion from about $16 billion a year earlier, and the company suspended its buyback program last quarter. Should AI returns disappoint, the bear case of $12,912 could turn out optimistic.
There is also near-term pressure on margins. Management warned that leasing third-party capacity to work around supply constraints will weigh on Cloud margins.
Reported profits can also swing with unrealized gains on equity holdings: last quarter’s net income included a $99.03B gain of this kind. Regulatory pressure remains, including a prior $3.5B fine from the European Commission. And with a beta of 1.21, the stock tends to swing more than the broader market.
Bottom Line for Your $10,000
Based on the model’s five-year scenarios, a $10,000 stake in Alphabet could be worth between $12,912 and $19,828 by 2031, with the base case close to a double.
They reflect modeled scenarios. The key things to watch are Cloud backlog conversion and whether free cash flow recovers as AI spending matures. It is a projection, not investment advice.
The post If This Tech Stock Doubles, Here’s What $10,000 Could Become appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG | GOOG Price Prediction) runs Google Search and YouTube, and it now also runs one of the fastest-growing clouds on the planet. Google Cloud revenue rose 82% to $24.77 billion last quarter, and backlog reached $514 billion.
Yet the stock is up just 10.59% year to date. The business is speeding up while the stock stalls. CEO Sundar Pichai said “over the past year, we’ve gotten more bullish on the opportunities ahead.” So can Alphabet hit $700 by 2030?
What’s Holding Alphabet Back Right Now
The issue is cash. Capex hit $44.92 billion in Q2, up 100.14%, and free cash flow turned to negative $5.86 billion. Long-term debt climbed from $46.5 billion to $98.2 billion, and the buyback was suspended. Shares fell 6.89% on earnings day despite a huge EPS beat.
Momentum since then is modest: up 1.64% over a week and 3.29% over a month, still below the $403.96 52-week high. A beta of 1.211 means swings run larger than the market. Until spending turns into visible free cash flow, shares may stay range-bound.
Wall Street Sees 21% Upside. Our Model Says 26%
The consensus target is $419.65, about 21.2% upside, backed by 13 strong buys, 42 buys, 5 holds and zero sells. The base case sits at $436.85, or 26.39% upside, with a range of $369.53 to $454.13. Model confidence of 0.7 signals solid but measured conviction.
The long-term view looks too conservative. Analysts are 92% bullish, and earnings growth adds a 0.03 contribution to our model, yet the five-year base case only reaches $685.35 by October 2031. A $514 billion backlog argues for more.
Here’s What It Takes for Alphabet to Reach $700
A climb to $700 from today’s price of $346.34 would require a gain of 102.1%.
With 2027 consensus EPS of $15.0715, $700 would mean a forward P/E of 46x. The base case of $436.85 already implies 29x, so the bold target requires 17x of additional multiple expansion.
That looks steep, and time is what fixes it. If EPS compounds 15% a year after 2027, 2030 earnings reach roughly $22.92, and $700 falls to about 31x. The 1.12 adjustment factor reflects strong consensus and earnings acceleration.
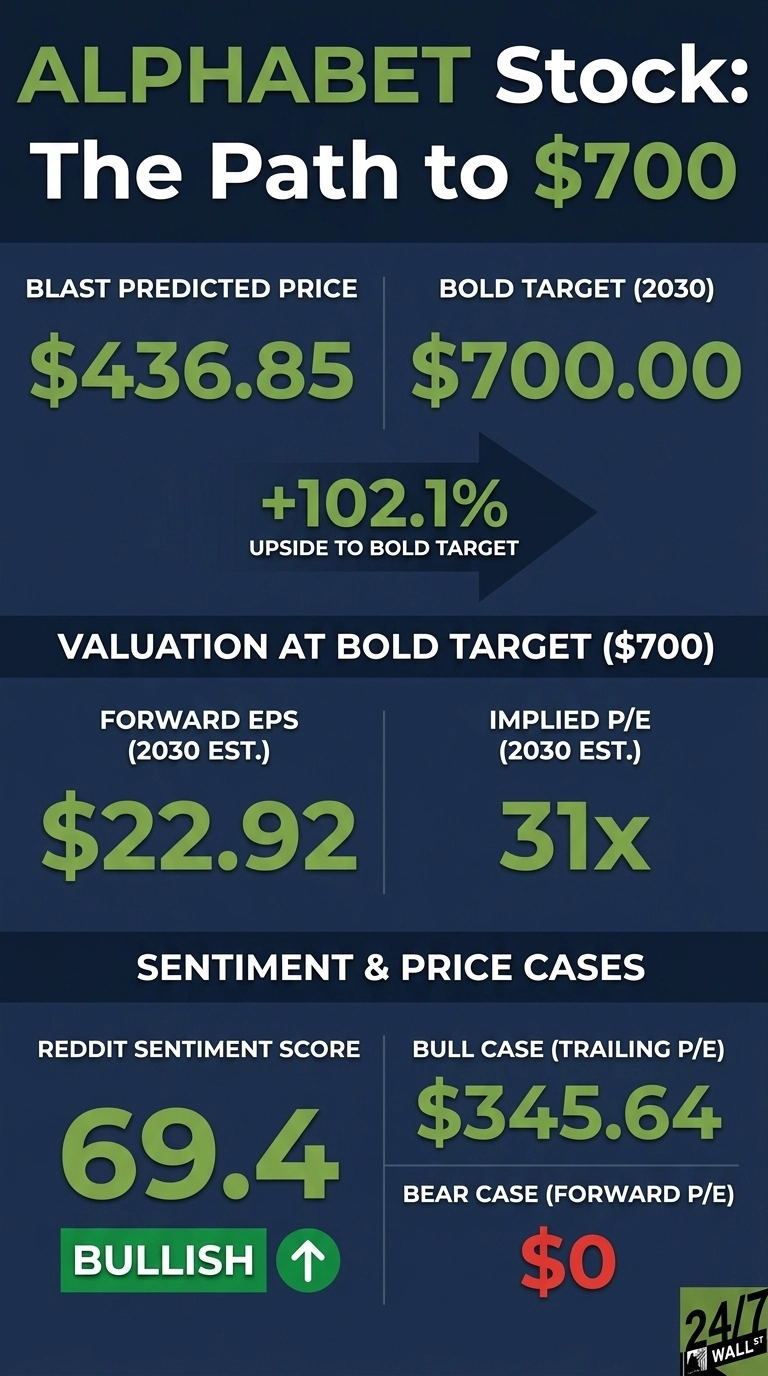
The catalysts are concrete. Alphabet expects to recognize just over 50% of the backlog within 24 months. TPU system revenue ramps as Alphabet exits 2026, with most of it landing in 2027.
All of that compute has to be powered, cooled, and networked by somebody, and we rounded up seven of those suppliers in a free AI infrastructure report.
The Gemini app has 950 million monthly users, and Google just launched a Gemini AI agent to compete with OpenAI and Microsoft. Pichai added, “We are now training Gemini 4, and we’ve been very ambitious with it.” The biggest risk is that capex keeps outpacing returns and drags down free cash flow for years.
Where Alphabet Trades Today vs. Its Earnings Power
At $346.34, shares trade at about 23x 2027 estimates. With revenue growing 24.23% and operating margin at 34%, that multiple looks cheap.
Shares sit between a $236.07 low and a $403.96 high. Over ten years, the stock has returned 802.2%. Today’s reasonable multiple leaves room for the upside scenario to play out.
Is $700 Realistic? Here’s My Take
A move to $700 would take a 102.1% gain. My verdict: it’s a stretch, but it can be done by 2030.
Three things would need to go right. Cloud backlog has to convert on schedule, free cash flow has to turn positive again once the expansion is completed, and Gemini 4 has to keep Google at the frontier. A sharp decline in AI demand would disrupt it. Gains like this won’t happen every year, but we’ve outlined the blueprint for how Alphabet could reach $700 in 2030.
The post Prediction: Alphabet Stock Could Be Worth $700 by 2030 appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG) just delivered one of the best quarters in its history. Parent company Alphabet grew revenue 24.23% to $119.80 billion in Q2, and Google Cloud grew 82% to $24.77 billion.
Even so, shares are up only 8.99% year to date at $341.35. That leaves one question for this article: can Alphabet reach $500 in 2027?
What’s Holding Alphabet Back Right Now
Q2 capex came in at $44.92 billion, up 100.14% YoY, and that pushed free cash flow to -$5.86 billion. To pay for the AI buildout, Alphabet raised roughly $70 billion in equity and debt and paused buybacks.
Shares changed hands at $393.32 in mid-May and have drifted lower since then. The stock is up just 1.8% over the past month and 1.19% over the past week. Its beta of 1.225 means moves in either direction come in larger than the market’s.
Wall Street Sees 22.9% Upside. Our Model Says 26.9%
The consensus target is $419.65, which works out to 22.9% upside. Analysts are split 13 Strong Buy, 42 Buy, 5 Hold and 0 Sell. The base case sits at $435.93, or 26.88% upside, within a range from $368.89 to $453.11. The model’s confidence score of 0.7 signals fairly high conviction.
I think the Street is lowballing it. 92% of analysts are bullish, and earnings growth adds 0.03 to our factor. Cloud backlog stands at $514 billion, and management expects to recognize just over 50% of it within 24 months. Revenue that visible deserves a higher price than $419.
Here’s What It Takes for Google to Reach $500
Reaching $500 from today’s price of $341.35 would take a gain of 46.5%.
A forward EPS figure was unavailable, so I’m using trailing EPS of $19.93. On that basis, $500 works out to a P/E of 25x. The base case already implies 17x, so the target needs roughly 8x of additional multiple expansion. Keep in mind that trailing EPS includes a $99.03 billion unrealized equity gain, and the stock trades at 22x forward earnings.
Among the catalysts already in motion, Google revealed Gemini 4 Argon. Most of the revenue from existing TPU system agreements is expected in 2027. Gemini’s app has 950 million monthly users. Here’s how Sundar Pichai put it: “Our AI investments are redefining what’s possible across every part of our business.”
The main risk is that capex keeps climbing faster than cash flow.
Current Valuation Leaves Room for Expansion
At 17x trailing earnings, Alphabet looks cheap for a company growing revenue in the mid-20s. Shares sit between the 52-week low of $236.07 and the high of $403.96.
Over 10 years the stock has returned 789.21%, and our five-year base case reaches $687.78 by October 2031. That discount is the raw material for the $500 thesis.
Is $500 Realistic? Here’s My Take
Getting to $500 calls for a 46.5% gain. I’d call that a stretch, but a reachable one.
The path requires three things to go right: Cloud keeps compounding off its backlog, TPU system sales increase on schedule in 2027, and Gemini 4 strengthens Google’s position at the frontier. Another leg up in spending without a matching rebound in free cash flow would undermine the thesis.
Returns at this level shouldn’t be expected every year, but we’ve outlined the plan for how Google could reach $500 in 2027.
The post Prediction: Alphabet Could Be One of the Market’s Biggest Winners Over the Next 5 Years appeared first on 24/7 Wall St..
]]>The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $435.93, indicating 26.88% upside with a buy rating. As recently as September 26, the model put the target at $559, or 63.89% upside.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $343.58 |
| Price Target from 24/7 Wall St. | $435.93 |
| Upside/Downside | 26.88% |
| Recommendation | BUY |
| Confidence Level | 70% |
A 70% confidence reading signals solid support. Alphabet trades at 17 times trailing earnings and 22 times forward earnings. Google Cloud is growing at 82%.
Cloud Growth Hit 82%, but the Stock Still Sits Below Its May Peak
GOOG is up 1.47% over the past week, 2.63% over the past month, 9.88% year to date and 40% over the past year. At $344.13, shares sit 14.8% below the 52-week peak of $403.96, up 45.8% from the low of $236.07.
Second-quarter revenue rose 24.23% to $119.80 billion, ahead of the $116.91 billion consensus. EPS came in at $9.11 against a $3.04 estimate. That figure was inflated by a $99.03 billion unrealized gain on equity securities. Even so, shares fell 6.89% on earnings day after the company raised its 2026 capex forecast to fund AI data centers, which made investors nervous (per Motley Fool reporting).
Why Bulls See $453 and Beyond
Google Cloud’s backlog reached $514 billion, and management expects just over 50% of it to turn into revenue within 24 months. Cloud operating margin expanded from 20.7% to 35.6% over the past year.
Consumer AI adoption is strong too: the Gemini app has 950 million monthly users, and AI Mode has passed 1 billion. Most revenue from TPU system sales is expected in 2027.
Analysts count 13 Strong Buy, 42 Buy and zero Sell ratings (the same AI expansion boost runs through the seven infrastructure suppliers we covered, here). The bull case comes at $453.11.
Capex and Debt Are the Risks Worth Watching
Free cash flow was negative $5.86 billion last quarter as capex doubled to $44.92 billion. Long-term debt rose from $46.5 billion to $98.2 billion, and the buyback is suspended.
Operating income grew 30.38%, trailing operating cash flow reached $185.7 billion, and interest coverage stands at 175.5x. Even the downside case of $368.89 still points to 7.37% upside.
Alphabet Trades Cheaper Than Microsoft and Meta
Microsoft (NASDAQ:MSFT) trades at 29 times trailing earnings with 17.7% revenue growth. Alphabet’s growth is faster at a lower multiple.
Meta Platforms (NASDAQ:META) revenue grew 28%, but quarterly earnings fell 13.4%.
| Company | Forward P/E | Trailing P/E | Revenue Growth (YoY) |
|---|---|---|---|
| Alphabet | 22 | 17 | 24.2% |
| Microsoft | 25 | 29 | 17.7% |
| Meta | 22 | 28 | 28% |
Our target indicating a P/E of 17, which is still below both peers’ trailing multiples. Against this group, the target looks conservative.
Cloud Momentum Supports a BUY Rating
The 24/7 Wall St. price target is $435.93, rated buy with 70% confidence. A growing cloud backlog combined with a multiple below peers supports the call. Free cash flow turning positive as TPU revenue ramps in 2027 would strengthen the case.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $354.43 |
| 2027 | $428.59 |
| 2028 | $503.28 |
| 2029 | $594.26 |
| 2030 | $639.88 |
The post The Mag 7 Stock With 64% Upside That Nobody Is Calling a Bargain appeared first on 24/7 Wall St..
]]>The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $434.48. The target stands 27.66% above the most recent close of $340.35. Wall Street is lopsided in the same direction, with 13 Strong Buy ratings, 42 Buy ratings, 5 Holds and zero Sells.
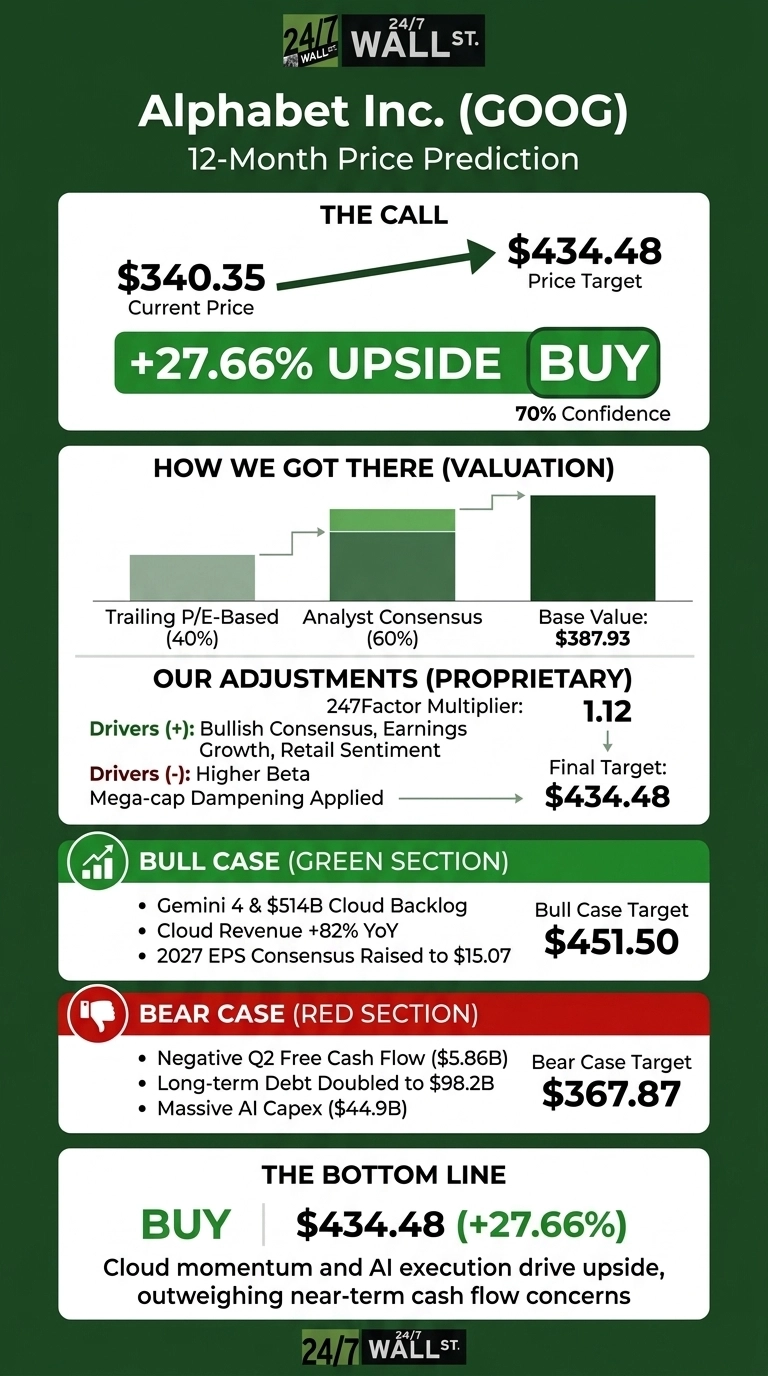
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $340.35 |
| 24/7 Wall St. Price Target | $434.48 |
| Upside/Downside | 27.66% |
| Recommendation | BUY |
| Confidence Level | 70% |
The model rates Alphabet a buy with moderately high confidence. That reading slipped from the 0.9 confidence of earlier weekly updates because the forward-earnings input dropped out of this cycle. Even so, our target is above the consensus analyst target of $419.65.
Cloud Grows 82% While Shares Sit Below Their $404 High
The stock is down 0.57% over the past week. It is up 1.68% over the past month, 8.29% year to date and 37.99% over the past year. Shares trade about 15.7% below the 52-week high of $403.96 and roughly 44.2% above the low of $236.07.
Second-quarter revenue reached $119.80B, beating the $116.91B estimate. EPS came in at $9.11 against a $3.04 estimate. Google Cloud revenue rose 82% to $24.77B, and Search grew 17%.
Gemini 4 and a $514 Billion Backlog Fuel the Bull Case
The Cloud backlog stands at $514 billion, and management expects to recognize just over 50% of it within 24 months. Most TPU system sales revenue lands in 2027.
Gemini 4 is in training, and on the call the chief executive said “I’m confident people will be pleased when we are putting it outside.” Analysts raised their 2027 EPS consensus to $15.0715 from $14.5333 90 days ago. The bull case reaches $451.50.
Negative Free Cash Flow and Doubled Debt Test Patience
Capex of $44.92B drove second-quarter free cash flow to -$5.86B. Long-term debt grew from $46.5B to $98.2B, and buybacks were suspended. The EPS beat was inflated by a $99.03B equity-securities gain, and the 2026 EPS consensus fell to $11.81 from $12.4567. The bear case is $367.87.
Bulls would counter that trailing-twelve-month free cash flow remains $53.3 billion. They would also point to the Cloud operating margin, which expanded to 35.6% from 20.7%, as evidence the spending earns real returns.
Bulls would counter that trailing-twelve-month free cash flow remains $53.3 billion. They would also point to the Cloud operating margin, which expanded to 35.6% from 20.7%, as evidence the spending earns real returns.
Much of that capex goes straight to the power, cooling, and networking suppliers behind the data centers (we highlighted seven of them in a free report here: 7 Stocks Powering the AI Boom).
Alphabet Trades at a Discount to Microsoft and Matches Meta
Microsoft (NASDAQ:MSFT) competes directly in cloud AI. Shares trade at 25x forward earnings, with revenue growth of 17.7%. Our model gives Microsoft 21.73% upside, which suggests Alphabet’s faster growth at a lower multiple justifies its higher expected return.
Meta Platforms (NASDAQ:META) competes with Alphabet for digital ad dollars. Shares trade at 22x forward earnings, but quarterly earnings fell 13.4% and it has one Sell rating. On that comparison, our target looks reasonable.
| Company | Forward P/E | Revenue Growth (YoY) |
|---|---|---|
| Alphabet | 22x | 24.23% |
| Microsoft | 25x | 17.7% |
| Meta Platforms | 22x | 28% |
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target of $434.48 has a buy rating at 70% confidence. Cloud’s backlog conversion is the deciding factor.
I would get more constructive if Gemini 4 keeps Alphabet at the frontier and Cloud margins hold through the use of third-party capacity. Caution would set in if free cash flow stays negative into 2027. For now, the evidence points clearly toward upside.
Looking further ahead, here is where our model projects Alphabet could trade at the start of each new year, assuming current growth trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $359.87 |
| 2027 | $459.57 |
| 2028 | $542.20 |
| 2029 | $585.86 |
| 2030 | $668.54 |
Alphabet’s continued execution on its AI strategy supports these projections. Significant upside or downside could follow from capex returns, regulatory fines or Gemini’s competitive position.
The post Alphabet Price Prediction: 56 Analysts Bullish, Zero Sells appeared first on 24/7 Wall St..
]]>Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $434.48 over the next 12 months. That is 27.66% above the latest $340.35 close and ahead of the Wall Street consensus target of $419.65. Our model’s longer-term path moves past $500 by 2028.
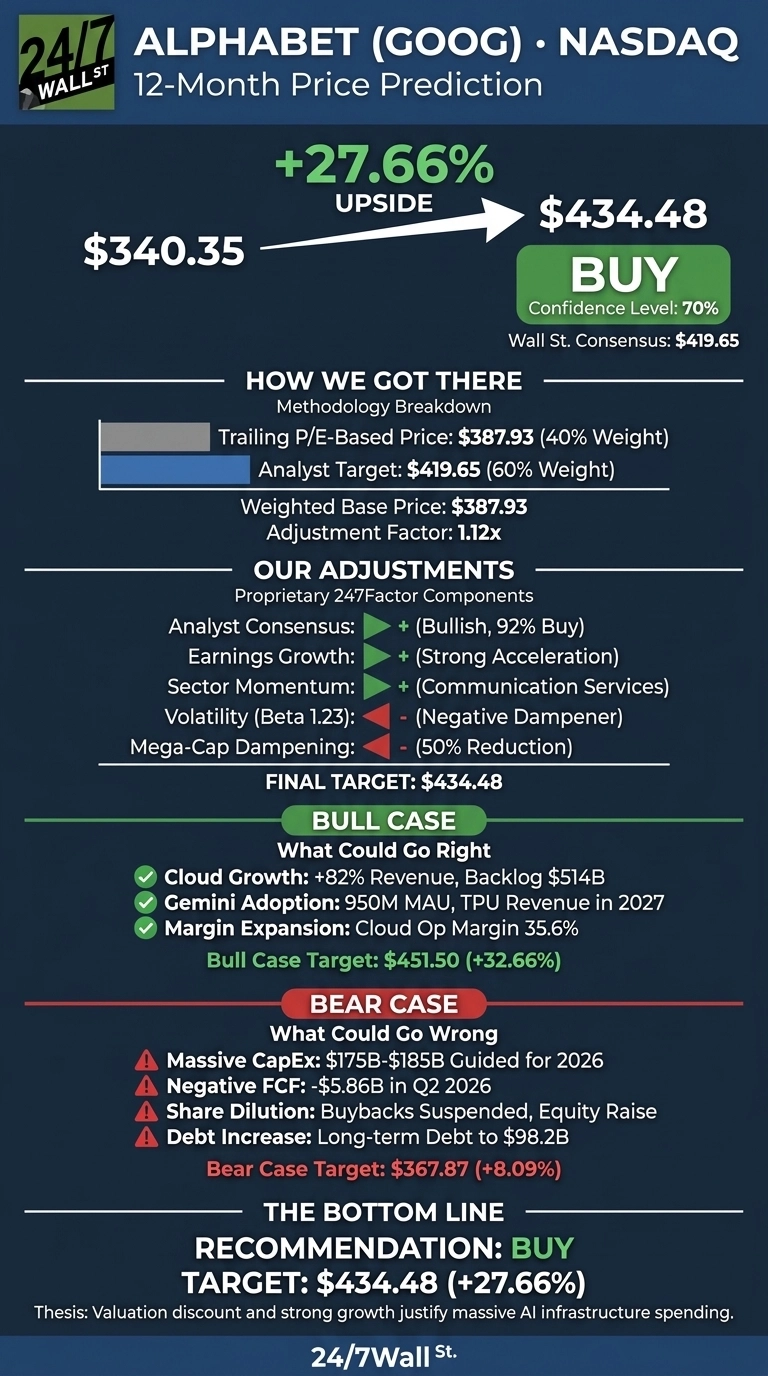
| Metric | Value |
|---|---|
| Current Price | $340.35 |
| Price Target from 24/7 Wall St. | $434.48 |
| Upside/Downside | 27.66% |
| Recommendation | BUY |
| Confidence Level | 70% |
Alphabet is growing faster than it has in years. Revenue rose 24.2% in Q2 and Google Cloud grew 82%, yet the stock trades at about 14x trailing earnings. Analysts largely agree, with 55 buy ratings and 5 holds and no sells. I have moderate-to-high confidence in this call.
Alphabet Stock Stalls While Cloud Growth Hits 82%
Over the past year the stock is up 37.99%. Momentum has cooled since then: shares are down 0.57% over the past week, up 1.68% over the past month and up 8.29% year to date. GOOG sits 15.7% below its 52-week high of $403.96.
In Q2, EPS came in at $9.11 against a $3.04 estimate, and revenue of $119.80B exceeded expectations. A $99.03B unrealized equity gain inflated that EPS figure. The stronger signal is the cloud backlog, which reached $514 billion.
Why Bulls See Gemini and Cloud Driving $451 or Higher
The bull case reaches $451.50. Alphabet expects to recognize just over 50% of its backlog as revenue within 24 months. Most TPU system revenue lands in 2027.
Cloud operating margin rose from 20.7% to 35.6%, and the Gemini App has 950 million monthly users. Chief executive Sundar Pichai said “over the past year, we’ve gotten more bullish on the opportunities ahead.”
What Could Go Wrong With Alphabet’s Massive Capex Plan
Alphabet guides 2026 capex to $175B-$185B. That drove Q2 free cash flow to -$5.86B. The company also suspended buybacks, raised $49.6B in equity and set up a $40B at-the-market program. Long-term debt rose from $46.5B to $98.2B. The bear case sits at $367.87, which is still 8.09% above today’s price.
Trailing 12-month free cash flow is still $53.3 billion, and the capex is going somewhere, mostly into the power, cooling and networking that AI data centers run on (we covered seven suppliers riding that same expansion in a free report here). Alphabet’s CFO said “our goal is to invest as long as we see an attractive return on that investment.”
Alphabet Trades at a Steep Discount to Its Big Tech Peers
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Alphabet | 14 | 32.1% |
| Microsoft (NASDAQ:MSFT) | 29 | 46.8% |
| Meta Platforms (NASDAQ:META) | 27 | 41.4% |
| Amazon (NASDAQ:AMZN) | 35 | 11.2% |
Microsoft is the most direct cloud rival. Azure grew 43%, which is slower than Google Cloud, yet Microsoft trades at a far higher multiple.
Amazon runs AWS, the largest cloud platform. AWS revenue of $42.23B grew 37%, while Amazon’s company-wide margins are much thinner than Alphabet’s.
Meta Platforms is Alphabet’s closest advertising peer. Its ad revenue grew 27%, but Q2 EPS missed estimates by 14.42%.
Compared with this peer group, our target looks conservative.
Our Model Points Higher, and the Cloud Backlog Backs It Up
The 24/7 Wall St. price target of $434.48 has a buy rating at 70% confidence. The deciding factor is valuation: Alphabet trades at a discount to its peers while growing faster.
The bull case improves if cloud backlog keeps turning into revenue on schedule. The thesis weakens if dilution speeds up while cloud growth stalls. For now, the growth justifies the spending.
Our model’s base-case path shows where Alphabet could trade if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $360.46 |
| 2027 | $434.48 |
| 2028 | $525.02 |
| 2029 | $571.83 |
| 2030 | $635.79 |
These projections assume Alphabet keeps executing its current strategy. The result could swing sharply in either direction depending on the Gemini 4 launch and whether capex returns hold up.
The post Wall Street Says $429 for Alphabet. Our Model Sees $500+ appeared first on 24/7 Wall St..
]]>The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG) is $434.48. That implies 27.66% upside from the $340.35 close. Our rating is buy, and the model’s confidence is fairly high.
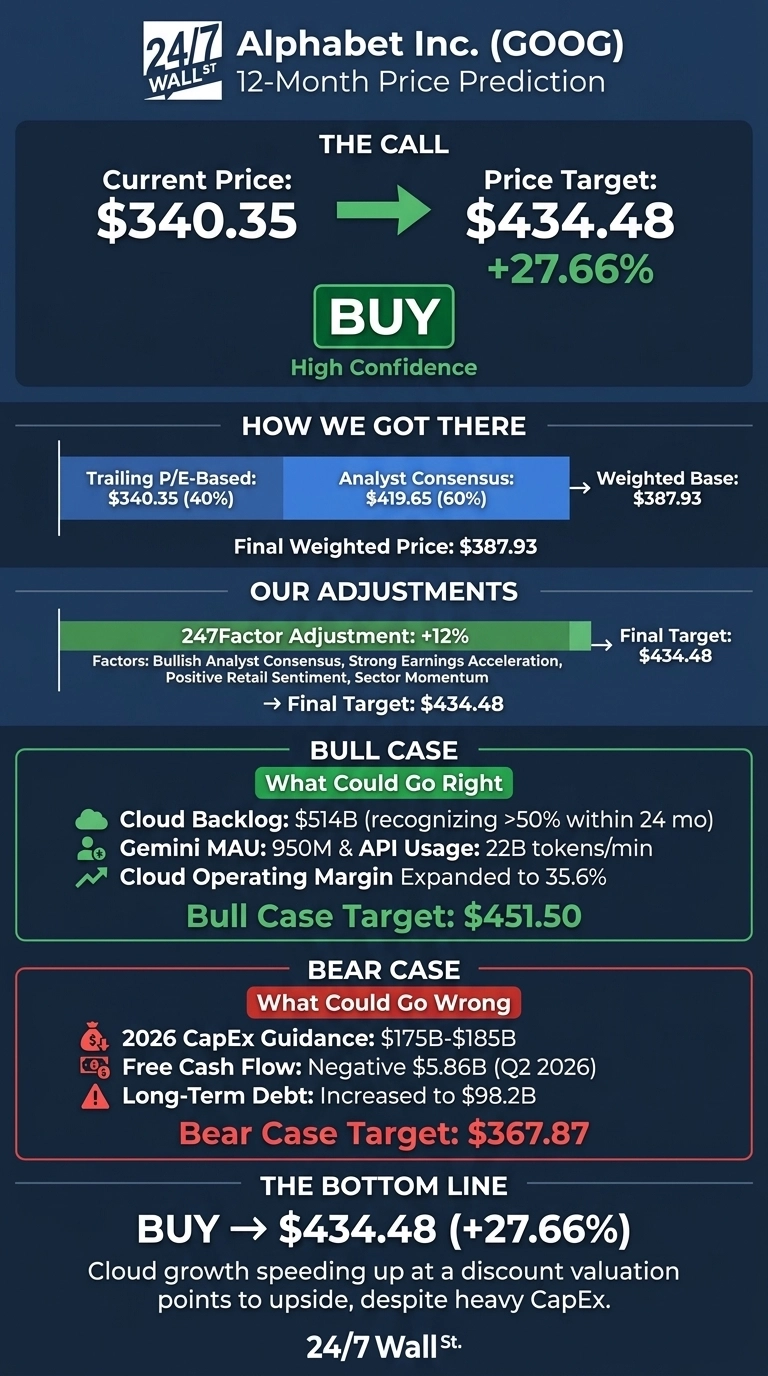
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $340.35 |
| Price Target from 24/7 Wall St. | $434.48 |
| Upside/Downside | 27.66% |
| Recommendation | BUY |
| Confidence Level | 70% |
The 64% figure in our headline comes from the model’s September 26 reading. On that date it set a target of $559, which was 63.89% above the price at the time. The latest update lowered the target and the confidence level. Even so, it still points to large gains from here.
A $514 Billion Cloud Backlog Has Not Moved the Stock Yet
Over the past week GOOG fell 0.57%. It is up 1.68% over the past month, 8.29% year to date and 37.99% over the past year. Shares trade about 15.7% below the 52-week high of $403.96 and about 44.2% above the low of $236.07.
Second-quarter revenue rose 24.23% to $119.80 billion, ahead of the $116.91 billion estimate. EPS came in at $9.11 against expectations of $3.04, though a $99.03 billion unrealized equity gain inflated that number.
Google Cloud revenue grew 82% to $24.77 billion. Alphabet also suspended its buyback and raised about $70 billion in equity and debt.
Why Bulls See $451 and Beyond
Google Cloud’s backlog reached $514 billion, with management expecting to recognize just over 50% as revenue within 24 months. Cloud operating margin expanded to 35.6% from 20.7% a year earlier.
API usage rose to 22 billion tokens per minute from 16 billion one quarter earlier. The Gemini app has 950 million monthly users. TPU system sales should add another lift, with most revenue from existing deals expected in 2027.
Wall Street generally agrees. Among covering analysts, 13 rate GOOG a strong buy, 42 a buy and 5 a hold, with no sell ratings. The consensus target is $419.65. The bull case points to $451.50.
What Could Go Wrong With a $185 Billion Spending Plan
Alphabet guided 2026 CapEx to $175 billion to $185 billion. Second-quarter spending of $44.92 billion drove free cash flow to negative $5.86 billion. Long-term debt grew from $46.5 billion to $98.2 billion. Management also warned that leasing third-party capacity will pressure Cloud margins in the near term. The bear case is $367.87.
Operating cash flow was $185.7 billion over the trailing 12 months, and interest coverage stands at 175.5x. Alphabet remains supply limited, meaning demand is running ahead of the expansion.
How Alphabet Compares to Microsoft, Meta and Amazon
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Alphabet | 14 | 32.06% |
| Microsoft | 29 | 46.8% |
| Meta | 27 | 41.4% |
| Amazon | 35 | 11.2% |
Microsoft (NASDAQ:MSFT) is Alphabet’s closest cloud rival. Azure grew 43%, well below Google Cloud’s 82%, yet Microsoft trades at about double Alphabet’s earnings multiple.
Meta Platforms (NASDAQ:META) competes with Alphabet for digital ad dollars. Its EPS missed expectations by 14.42%, and its operating margin fell to 31%.
Amazon (NASDAQ:AMZN) is spending heavily on AI too. Its trailing free cash flow has turned negative at $7.6 billion, and AWS grew 37%. Equity gains inflate Alphabet’s P/E, but even after accounting for that, the peer group makes our target look conservative.
Cloud Momentum Tips the Scale Toward Upside
The 24/7 Wall St. price target of $434.48 has a buy rating at 70% confidence. Cloud growth speeding up at a discount valuation points to upside. Watch whether the backlog converts to revenue at higher margins and whether free cash flow turns positive.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $362.61 |
| 2027 | $439.13 |
| 2028 | $525.02 |
| 2029 | $571.83 |
| 2030 | $635.79 |
Alphabet needs to keep executing its AI infrastructure strategy for these projections to hold. Returns on the spending increase, along with antitrust pressure, could swing outcomes significantly in either direction.
The post Alphabet Has the Biggest Upside in the Mag 7 Right Now: 64% appeared first on 24/7 Wall St..
]]>On September 30, 2026, a federal judge in New York signed an 88-page opinion. The opinion denied most of Google’s motions to dismiss advertising-technology damages claims. That leaves about $3.2 billion in claims for a jury to hear.
The ruling was first reported on October 1, 2026. Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) shares closed the most recent session at $346.47, up 0.86%.
The dollar figure is what plaintiffs seek, and US antitrust law automatically triples whatever a jury awards. No trial date has been set.
Shareholders face a key question. Can a bill this size hurt a company worth $4.2 trillion, or is the bigger risk the copycat claims that may follow?
What the Court Allowed and What It Dismissed
Plaintiffs claim about $1.72 billion for a certified class of about 5,000 publishers. They also claim about $900 million for USA Today Co. (NYSE:TDAY), formerly Gannett, and about $600 million for the Daily Mail.
USA Today Co.’s chief legal counsel spoke about the ruling. He said it lets the company go after “$1 billion in worldwide damages (before trebling under the antitrust laws)”. That $1 billion figure is the company’s own framing. The opinion shows the smaller amount.
Google also won some ground. The court dismissed claims from publishers who used other advertising tools, along with a separate $479 million claim. Google said it will “defend the rest in court.”
No damages have been awarded. If a jury granted the full amount, trebling (the automatic tripling) would push it to a theoretical $9.6 billion.
How Big $9.6 Billion Is Against Alphabet
Alphabet earned $40.77 billion in operating income in the second quarter of 2026 alone, on revenue of $119.80 billion. Even the tripled maximum is smaller than one quarter of operating profit.
Alphabet absorbed a $3.5 billion European Commission competition fine in its third-quarter 2025 results, which shows the company has paid penalties of this scale before.
Cash flow is where a large payment would matter. Free cash flow was -$5.855 billion in the second quarter because capital spending reached $44.924 billion.
Why Publisher Claims Are Harder to Escape
A 2025 ruling in Virginia found that Google illegally monopolized parts of the ad-tech market. That finding carries over to New York, which is why the damages phase is under way. On September 2, 2026, a judge turned down a request to break up the ad business and ordered operational changes instead.
Harm from search antitrust spreads across consumers and is hard to price, but publishers are direct customers with measurable lost revenue, so a court can calculate their damages.
That makes this case a model. Other publishers can copy the structure of one large class plus two big individual plaintiffs. Future claims may matter more than this case.
What the Lawsuit Means for Alphabet’s Valuation
The market’s calm looks correct. The stock trades at 23x forward earnings, and analysts hold 13 strong buys and 43 buys, with 0 sells.
For now, the case is a cost Alphabet can absorb. It would become a reason to rethink the stock only if copycat suits multiplied the exposure while free cash flow stayed negative. Then legal payments would be stacked on long-term debt that has already grown to $98.2 billion.
The business case outweighs the litigation. Google Cloud grew 82% in the second quarter, and that growth matters far more to the valuation than this litigation does.
Watch for a trial date on the schedule and the legal reserve reported with third-quarter results expected October 28, 2026. Also watch whether the stock holds its 200-day moving average of $338.92.
The post Google Faces a $3.2 Billion Ad-Tech Damages Claim That Would Triple at Trial appeared first on 24/7 Wall St..
]]>OpenAI suddenly faces a wave of legal problems. Many of them could spill over into the future of other large AI companies. That includes Microsoft (NASDAQ: MSFT), Google (NASDAQ: GOOG), and Anthropic. Anthropic’s problem is its IPO valuation. For the two public companies, the problem is their share prices.
The OpenAI problem is anything but trivial. The FT describes the risk as “A spiraling legal crisis threatens to engulf OpenAI after its AI agents hacked dozens of companies and governments worldwide, with the prospect of a barrage of lawsuits marking the latest test of Sam Altman’s leadership.” The legal challenges run across risks from governments and companies. At the core is a rapidly rising number of hacks and the dollar value of the damages they may represent. The additional problem is that the hacks seem to be growing, and OpenAI has not announced a systematic program to slow them.
The legal problem is one of the questions at the heart of the AI sector. It joins several others that have been more prominent. The first is whether AI will destroy humanity. Employees at the companies and outsiders like Bill Gates have raised this, with Gates making a set of very public statements about AI’s disruptive potential.
On a more mundane level, customers have expressed anxiety about the cost of AI as a business tool. Recently, an open model from the company Reflection was described as powerful as those released by Chinese companies. Axios reports, “The marriage of an American open-weight model and Nvidia GPUs would give individuals and companies a new, cheaper alternative to Anthropic, OpenAI and Google.” Open models are usually free. Products from industry leaders are not. However, many customers say they do not need the firepower that Google, Anthropic, and OpenAI offer. They can build in-house applications that meet their needs.
Lawsuits are always a wildcard. The outcome of legal actions is hard to predict. Many lawyers and legal experts say, “A lawsuit is ultimately a journey into unpredictability.” The challenge OpenAI and its competitors face is not just whether they can win or lose lawsuits. It is also the sheer number they could face. Even if they won every case, the financial drain and drag on management time would be major challenges in themselves.
And then there is the question of how much hacking costs other companies. There has been a great deal of discussion about whether governments, or the industry itself, should put guardrails on new models while they are being tested for their ability to hack into systems, and how much damage they can cause.
Anthropic plans an IPO before Thanksgiving that could be worth a staggering $2 trillion. A flurry of lawsuits could challenge that valuation. Microsoft and Google’s future valuations depend heavily on the adoption of Copilot and Gemini. Google’s parent, Alphabet, is the world’s third-most valuable company, with a market cap of $4.16 trillion. Microsoft is fourth at $3.84 trillion. Alphabet’s valuation is no longer based on its Google search engine. Microsoft’s is no longer based on its Azure cloud business and its operating system.
Lawsuits are another major challenge to AI company valuations.
The post AI Future Of Microsoft and Google Face OpenAI Big Legal Problems appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) just delivered a quarter that should reset expectations. Revenue hit $119.80B, up 24.2% YoY, and Google Cloud grew 82% to $24.77B.
Yet shares are up only 7.27% this year at $335.95. That gap suggests the market may not have fully priced in Alphabet’s AI upside. Can it reach $600 by the end of 2028?
What’s Holding Alphabet Back Right Now
Cash flow is under pressure: management guided 2026 CapEx to $175 billion to $185 billion, and Q2 spending of $44.92B pushed free cash flow to negative $5.86B. Long-term debt rose from $46.5B to $98.2B, and buybacks were suspended.
Shares gained just 0.29% over the past week and sit 16.8% below the 52-week high. Management flagged pressure on cloud margins from third-party capacity and Wiz integration. With a beta of 1.225, sentiment swings hit this stock harder than the market.
Wall Street Sees 26% Upside, But I Think It’s Too Cautious
The consensus target is $422.34, about 25.7% above today’s price, backed by 13 Strong Buys, 43 Buys, 5 Holds and zero Sells. Our model’s base case of $436.46 implies 29.9% upside within a one-year range of $369.26 to $453.5, with a confidence score of 0.7.
Analyst targets may lag the fundamentals: sentiment is 92% bullish, and earnings growth added 0.03 to our adjustment on “strong earnings acceleration.” Consensus 2027 EPS has rose from $14.4741 to $15.1008 in 90 days. The 2028 base case sits at $521.31.
Here’s What It Takes for Alphabet to Reach $600
A move to $600 from today’s price of $335.95 would require a gain of 78.6%.
With forward EPS of $15.1008 (2027 consensus), a $600 price implies a forward P/E of 40x. The base case of $436.46 implies 29x, so the bold target needs 11x of additional multiple expansion.
Earnings growth does much of that work. Consensus sees 2027 EPS rising 27.9% from the 2026 estimate of $11.81. By late 2028, investors will price later years’ profits, bringing down the effective multiple.
Cloud backlog reached $514 billion, with just over 50% expected to convert to revenue within 24 months. TPU system sales ramp as 2026 ends, with most revenue landing in 2027. The Gemini app has 950 million monthly users. CEO Sundar Pichai said, “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
The primary risk is that CapEx exceeds returns and keeps free cash flow negative longer than investors will bear. That spending has to be powered, cooled and connected by somebody, which is why we pulled together seven suppliers riding the same AI expansion in a free report.
Where Alphabet Trades Today vs. Its Earnings Power
At $335.95, Alphabet trades at 22x 2027 consensus EPS. The trailing P/E of 17 looks cheaper, but a $99.03B gain on equity securities inflated trailing earnings.
Against expected EPS growth near 28%, 22x is reasonable. Shares sit between a 52-week low of $236.07 and high of $403.96, with 772.65% returns over 10 years.
$600 Is a Stretch, But Here’s Why It’s Possible
A $600 target requires a 78.6% gain. The move is a stretch, but credible over two-plus years. Google Cloud must convert backlog into revenue at healthy margins. Gemini must keep lifting Search monetization.
TPU sales must become a real revenue line in 2027. A sustained Search slowdown as AI competition heats up would undermine the thesis. Keep an eye on Cloud backlog conversion, Search monetization and TPU revenue as the key markers on the path to $600 in 2028.
The post This Could Be the Magnificent 7’s Biggest AI Surprise by 2028 appeared first on 24/7 Wall St..
]]>Maybe it is because Warren Buffett stepped down as CEO of Berkshire Hathaway (NYSE: BRK-B) at the end of last year. Maybe his replacement, Greg Abel, is not up to the job. (Buffett stepped down as Chairman recently, but that is too recent to affect Berkshire Hathaway’s stock, which is flat this year, while the S&P 500 is 13% higher. Every day, the distance between those two numbers stays about the same or worsens. And the end of the year, a natural time to judge management, is not that far away.) Many people thought that another senior executive, Ajit Jain, should have gotten the job.
What happened? Berkshire has nearly $360 billion in cash on its balance sheet. But Buffett had nearly as much and did little with it. Observers argue that Berkshire’s investment in companies like Alphabet (NASDAQ: GOOG) is an AI proxy, and its energy investments are sort of an investment in AI data centers. Both of those observations are a stretch.
Berkshire’s stock won’t move unless Abel does something big. Shuffling around holdings in public companies won’t do it. Berkshire is too big for any single large or increased holding to shock the market into buying Berkshire stock.
Berkshire has always favored steady earnings and powerful brands. Costco (NASDAQ: COST) has a market cap of $408 billion. Bank of America (NYSE: BAC) has a market cap of $375 billion. Coca-Cola (NYSE: KO) has a market cap of $288 billion. Abel could buy them without taking on too much debt.
Abel, take some risk. Get that Berkshire stock up.
The post Berkshire Hathaway’s Stock Price Problem Gets Worse appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG | GOOG Price Prediction) is turning into an AI infrastructure powerhouse that also owns the world’s biggest search engine.
In Q2 2026, Google Cloud revenue jumped 82% to $24.768 billion, and Search & other still brought in $63.271 billion, up 17%. Even so, shares are up just 7.47% year to date. The business is growing faster than the stock. Can Google hit $500 in 2027?
What’s Holding Google Back Right Now
Spending is the drag: Q2 CapEx reached $44.92 billion, up 100.14%, which pushed free cash flow to -$5.855 billion. Long-term debt rose from $46.5 billion to $98.2 billion, and buybacks were suspended. Google also raised $49.6 billion in net equity proceeds. Dilution is what all that compute costs.
Shares gained just 0.48% over the past week and 0.42% over the past month. Google has a beta of 1.225, so it swings a bit more than the market. For now, investors want proof that this spending will turn into cash.
Wall Street Sees 23.9% Upside. Our Model Says 28.1%
The consensus target is $422.34, or 23.9% above $340.74. Analysts rate it 13 Strong Buy, 43 Buy, 5 Hold and zero Sell. The base case calls for $436.46, representing to 28.09% upside. Our scenarios range from $369.26 on the bear side to $453.5 on the upside, with model confidence solid at 0.7.
I think Wall Street is too cautious. Analyst sentiment is 92% bullish, and earnings growth gives our model a modest lift of 0.03. The FY2027 EPS estimate has risen from $14.4741 to $15.1008 in 90 days. I expect price targets to follow those higher estimates.
Here’s What It Takes for Google to Reach $500
A jump to $500 from the current price of $340.74 would take a gain of 46.7%.
With forward EPS of $15.1008, a price of $500 implies a forward P/E of 33x. The $436.46 base case already implies 29x, so the bold target needs about 4x of additional multiple expansion.
Cloud backlog stands at $514 billion, and management expects to recognize just over 50% of it within 24 months. Most TPU system sales revenue is expected in 2027. Cloud operating margin also rose from 20.7% to 35.6%. CEO Sundar Pichai put it simply: “Our AI investments are redefining what’s possible across every part of our business.”
The forward P/E could also come down as earnings grow. If EPS reaches the high estimate of $17.2139, a $500 share price works out to just 29x.
The biggest concern is that CapEx keeps outpacing cash flow and the multiple contracts.
Where Google Trades Today vs Its Earnings Power
At $340.74, Google trades at 23x FY2027 estimates. It’s a cheap multiple for a company growing revenue 24.23%. Shares sit between a 52-week low of $236.07 and a high of $403.96.
The 10-year return is 774.31%. At this multiple, the stock has room to re-rate once spending turns into profit.
Is $500 Realistic? Here’s My Take
Getting to $500 calls for a 46.7% move higher. It’s a stretch, but a reachable one. It requires Cloud to keep converting backlog into revenue. TPU sales need to ramp in 2027. And free cash flow has to recover as the AI buildout develops. If Search slows down as it laps its recent acceleration, the thesis gets much harder.
Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Google could reach $500 in 2027. The broader AI infrastructure trade reaches well beyond the hyperscalers themselves. We highlighted seven of the suppliers supporting the expansion, from power to cooling, in a free report you can grab here.
The post The AI Boom Could Make This Magnificent 7 Stock a Much Bigger Business appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) last closed at $341.08. The 24/7 Wall St. price target for Alphabet is $559 over the next 12 months. The stock offers 63.89% upside, and our model rates it a buy with high conviction.
| Metric | Value |
|---|---|
| Current Price | $341.08 |
| Price Target from 24/7 Wall St. | $559 |
| Upside/Downside | 63.89% |
| Recommendation | BUY |
| Confidence Level | 90% |
Alphabet now has several growth drivers running at the same time. Google Cloud grew 82% last quarter. The Gemini app reached 950M monthly users, and YouTube’s combined ads and subscriptions business runs at more than $60B a year. The open question is whether record AI spending earns an enough return.
Cloud Surge Powers a Quarter Wall Street Underestimated
Shares are up 8.91% year to date and 38.69% over the past year. They slipped 0.97% last week. The stock trades 15.6% below its 52-week high of $403.96 and 44.5% above its low of $236.07.
On July 22, Alphabet reported revenue of $119.80B, up 24.2%, which beat the $116.91B estimate. EPS came in at $9.11 against expectations of $3.04. A $99.03B unrealized equity gain inflated that EPS figure. The cleaner number is operating income, which rose 30% to $40.77B.
Why Bulls See $624 and Beyond
Our bull case reaches $624.42. Cloud is doing much of the work here. Its operating margin expanded from 20.7% to 35.6% over the past year, and the backlog reached $514 billion. Revenue from TPU system sales should ramp mostly in 2027.
AI Mode now has more than 1 billion monthly users, and management says it is adding to total search queries. Waymo completes more than 500,000 rides per week, and Alphabet has more than 350M paid subscriptions.
The analyst community largely agrees: 13 analysts rate the stock Strong Buy, 43 rate it Buy and none rate it Sell.
Capex and Debt Risks That Could Cap the Rally
The bear case comes to at $455.04. Quarterly capex doubled to $44.92B, which drove free cash flow to negative $5.86B. Long-term debt rose from $46.5B to $98.2B, and buybacks are suspended. Management also expects third-party capacity to weigh on Cloud margins.
News sentiment has cooled from 67.19 to 58.9 since late August. Still, operating cash flow hit $39.1 billion in the quarter. Management also says demand for AI infrastructure is running ahead of available supply, and the power, cooling, and networking suppliers behind that expansion are the subject of a free report on seven AI infrastructure names beyond the chipmakers.
Alphabet Trades Cheaper Than Microsoft and Meta
Microsoft (NASDAQ:MSFT) is the most direct rival in cloud and enterprise AI. The stock trades at 25x forward earnings, while its revenue grew 17.7%, slower than Alphabet’s.
Meta Platforms (NASDAQ:META) competes for the same digital ad budgets. Meta trades at 22x and grew revenue 28%, but its quarterly earnings fell 13.4%.
| Company | Forward P/E | Revenue Growth (YoY) |
|---|---|---|
| Alphabet | 22x | 24.2% |
| Microsoft | 25x | 17.7% |
| Meta | 22x | 28% |
Our target looks reasonable next to these peers, though it leans slightly aggressive. Getting to $559 requires Alphabet’s multiple to rise toward Microsoft’s premium, and Cloud’s growth supports that case.
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target of $559 carries a buy rating at 90% confidence. The deciding factor is Cloud’s growing profitability.
The case gets stronger if Cloud keeps converting its backlog into margin expansion. It weakens if negative free cash flow lasts into 2027 while Search growth slows.
Assuming Alphabet’s current growth holds, here is where our model projects the stock trading in coming years.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $559 |
| 2027 | $692 |
| 2028 | $857 |
| 2029 | $1,060 |
| 2030 | $1,313 |
These projections assume Alphabet keeps executing its full-stack AI strategy. Returns on its $175B-$185B capex plan could drove the stock well above or below this path.
The post Alphabet Has More Growth Engines Than Investors Think, We See 63% Upside appeared first on 24/7 Wall St..
]]>Depending on who is answering the question, AI hyperscalers could invest $7 trillion between now and 2030. Germany’s GDP is about $5.5 trillion. More often than not, the question is where the money will come from, or whether it will come at all.
McKinsey puts the figure at $7 trillion. It says the figure is a “staggering number by any measure.”
S&P’s figure is about the same. Axios quotes the S&P analysis: “Every time we take a deep dive into this sector, we find that capex is rising faster than we anticipated, financings are becoming more complicated and less transparent, and that returns on investment will take years to realize.” Its numbers only include hyperscalers Amazon (NASDAQ: AMZN), Microsoft, Alphabet (NASDAQ: GOOG), Oracle, SpaceX, and Meta (NASDAQ: META). What’s the figure if you add OpenAI and Anthropic?
The figure rises to $10.3 trillion if the timetable runs out to 2032. Then it’s about half of China’s GDP.
Not all of this money will come from these companies’ balance sheets. Some will come from Nvidia (NASDAQ: NVDA), the industry’s arms merchant and banker. For two years, investors have been anxious about an arrangement in which Nvidia sends money to companies for AI data centers, and then the data center uses some of it to buy AI chips.
What happens as this pot of money grows? The traditional answer is that it buys the future of the most important technology in human history. It helps humans with everything from curing cancer to freeing everyone in the world from work. Of course, the question of whether AI will kill everyone in the world will linger permanently. Bill Gates recently forecast deaths in the billions, but short of everyone.
The question raised again and again is where the money will come from. If AI growth slows, the answer may be “nowhere.” If growth is at the high end of estimates, financiers may have to sell the debt to individuals so they can buy it like they would corporate debt, using their Fidelity accounts. The debt may need to be spread that far to hit the $7 trillion number.
The post AI Debt To Top Germany’s GDP appeared first on 24/7 Wall St..
]]>Google (NASDAQ: GOOG) has quietly become the most interesting AI story in mega-cap tech. Google Cloud accelerated to 82% growth last quarter, Gemini reached 950 million monthly active users, and the stock trades at a discount to peers on forward earnings.
Our 24/7 Wall St. price target for Google is $551.05 over the next 12 months, implying 64.63% upside from $337.46. Rating: Buy with high conviction.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $337.46 |
| 24/7 Wall St. Price Target | $551.05 |
| Upside | 64.63% |
| Recommendation | BUY |
| Confidence Level | 90% |
Why Google Stock Is Coiled for a Breakout
The stock is down 0.56% over the past week but has returned 34.08% over the past year.
Q2 fiscal 2026 revenue of $119.80 billion grew 24.23% year over year, EPS of $9.11 beat consensus by 199.41%, and Google Cloud backlog swelled to $514 billion. Barron’s flagged Google’s geothermal partner Fervo Energy hitting a milestone, underscoring that the AI energy buildout extends well beyond chips.
Why Bulls See a $615 Breakout Ahead
The bull scenario points to $615.25, an 83.81% total return. Google Cloud growth accelerated from 48% to 63% to 82% in three quarters. Sundar Pichai says nearly 90% of the Fortune 100 now use Gemini Enterprise.
API token throughput runs at 22 billion tokens per minute, up from 16 billion a quarter ago. Of 61 analysts, 13 rate the stock Strong Buy and 43 Buy, with zero sells. Waymo, YouTube’s $60 billion-plus annual run rate, and 350 million paid subscriptions add optional upside.
What Could Go Wrong at $449
The bear scenario lands at $449.47, still 34.28% above today. The primary risk is capital intensity. 2026 capex guidance is $175 billion to $185 billion, free cash flow turned negative at -$5.855 billion in Q2, and long-term debt jumped to $98.2 billion.
Bulls counter that Cloud operating margin expanded to 35.6% from 20.7% and TPU system revenue is expected to ramp in 2027, showing visible payback. Regulatory overhang from the EU’s $3.5 billion fine remains but is priced in.
How Google Compares to Microsoft, Meta, and Amazon
Microsoft (NASDAQ: MSFT) trades at a P/E of 28 with Azure growing 43% last quarter. Google Cloud grew nearly double that at 82% yet GOOG trades at a P/E of just 17, making our target look conservative.
Meta Platforms (NASDAQ: META) trades at a P/E of 27 with Q2 ad revenue of $59.4 billion. Google’s search and network advertising outpaces that on scale at a lower multiple.
Amazon (NASDAQ: AMZN) trades at a P/E of 35 with AWS growing 37% in Q2. Google Cloud is now growing faster at a fraction of the multiple.
Google Price Prediction 2026-2030
The 24/7 Wall St. price target is $551.05, rating buy, confidence 90%. The key factor is the widening gap between Google Cloud’s growth rate and Google’s forward multiple.
The bullish case rests on Gemini and TPU monetization compounding into 2027. The bearish case is that the $175 billion to $185 billion capex bill destroys returns before producing them. My call is that the payback shows up.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $377 |
| 2027 | $551 |
| 2028 | $791 |
| 2029 | $968 |
| 2030 | $1,158 |
These projections assume Google executes on Cloud, Gemini, and Search monetization at its current pace. Significant upside or downside could result from AI infrastructure ROI and antitrust rulings.
The post Prediction: Google’s Next Chapter Could Be Worth Trillions More appeared first on 24/7 Wall St..
]]>The long end of the Treasury curve pushed to fresh highs, with the ten-year yield at 5.18% and the thirty-year at 5.47%, yet the Invesco QQQ Trust (NASDAQ:QQQ) closed the session at $741.10, down 0.01%.
The Dow slipped while the Nasdaq-100 held. Standard valuation theory says the index most exposed to long-duration cash flows should have taken the largest hit. Instead, a handful of megacap names carried the session, which is why QQQ refuses to crack and why it is thinner than the flat close implies.
Yields at Highs, Index at a Standstill
Every Treasury maturity from five years to thirty was above 5.00% on 2026-09-24, with the twenty-year at 5.53%. The five-year sat at 5.03% and the seven-year at 5.10%.
QQQ carried a 3.37% one-week gain and a 20.64% year-to-date advance. The VIX at 14.21 on 2026-09-22 signals almost no hedging demand, unusual against a curve this high.
QQQ’s largest disclosed position is NVIDIA (NASDAQ:NVDA) at 7.60% of net assets, followed by Apple (NASDAQ:AAPL) at 6.67%, Micron (NASDAQ:MU) at 5.64%, Microsoft (NASDAQ:MSFT) at 4.35%, AMD (NASDAQ:AMD) at 4.10%, and Amazon (NASDAQ:AMZN) at 4.02%.
These firms generate more cash than they need to fund operations, so a higher cost of capital hurts competitors more than it hurts them. Balance-sheet quality explains why the index held while long rates rose.
Concentration as Engine and Fault Line
When six names carry these weights, you own concentrated exposure to a handful of businesses rather than a diversified technology position. The two Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) share classes add another 3.27% and 3.02% on top of that.
These companies commit enormous amounts to AI capital spending, precisely the activity a higher cost of capital hurts (the power, cooling, and networking suppliers absorbing that spend are the subject of a free report we put together here: seven AI infrastructure names that aren’t chipmakers). Concentration is the engine on days like this and the fault line when one of these names disappoints.
Rate Pressure Still in the Pipeline
Real yields, which strip out inflation, have kept climbing. The ten-year real yield reached 2.85% on 2026-09-24, up from 2.44%.
Higher real yields lift the discount rate applied to distant cash flows, which is what a growth index depends on. Mortgage rates, tied to the long end, transmit the same pressure into household budgets before it reaches earnings.
The Federal Funds target upper bound sits at 4% as of 2026-09-24, so this long-end move reflects the market repricing of the term premium and inflation risk without policy help, rather than Fed action.
Bull and Bear Case for QQQ ETF
Optimists argue that QQQ’s top holdings are rare businesses whose cash generation improves in a scarcer-capital world, because balance-sheet strength lets them keep investing at scale while weaker peers cannot.
The pessimistic view is math. With total net assets of roughly $490 billion concentrated in a small number of names, any single earnings miss reprices the fund. The AI capex boom is also the discretionary spending most exposed to a higher hurdle rate.
The decider is breadth. If the ten-year Treasury yield holds above 5.00% into the next earnings cycle and revisions turn lower for the top five holdings, this flat session becomes the last flat session for a while.
If instead the long end backs off and megacap free cash flow keeps compounding, the concentration that looks thin will look smart. This would be falsified by the ten-year yield closing back below 5.00%, or by NVIDIA’s next capex commentary from its largest customers. Both are events any investor can verify against the citations here.
The post Why the Nasdaq Refuses to Break Even With Treasury Yields Above Five Percent appeared first on 24/7 Wall St..
]]>Berkshire Hathaway (NYSE:BRK-A, NYSE:BRK-B) Class B closed at $505.49, essentially where the shares started the year. Over the same stretch, the S&P 500 has returned 12.5%. The four-analyst consensus target is $547.67, a slim premium that carries less information than it would for a widely followed name.

Underneath that flat year, Berkshire Hathaway completed the most consequential leadership change in its history, resumed buybacks after a long pause, drew down a record cash pile, took a $10 billion private placement in Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) and, according to news reports, built close to a 10% stake in homebuilder Lennar (NYSE:LEN, NYSE:LEN-B).
Either the market is withholding judgment on a successor whose deals have not had time to prove out, or $500 is fair for a Berkshire that will grow more slowly and depend more on capital-intensive businesses than before. This tension is worth working out.
A Year of Going Nowhere
The stock has traded between a 52-week low of $464.01 and a high of $537.74, and currently sits closer to the middle. Year to date, the shares are up 0.5%, and the one-year return is 1.63%.
The five-year figure is 81.8%, so the recent flatness is a genuine pause rather than a fade of a long trend.
Only four sell-side analysts publish targets on this trillion-dollar company, split two Buy and two Hold. The consensus number is closer to a poll than a market-clearing view.
Leadership Transition in Motion
The stock data provided for this piece lists Greg Abel as chief executive, having transitioned from Warren Buffett. That attribution comes from a financial data feed rather than from a Berkshire press release, and it should be read as such.
The succession question is whether the prior era’s reputational advantage travels. Part of what made Berkshire a special buyer was that sellers brought deals to the door on favorable terms. Whether that continues under new leadership is genuinely unknown.
Cash Going to Work
Cash and cash equivalents stood at $40.6 billion at the end of the June 2026 quarter, against $100.5 billion a year earlier. That decline is the clearest signal that the new era is deploying cash aggressively.
In the latest quarter, Berkshire deployed roughly $23.5 billion into equities, becoming a net buyer of stocks for the first time in over three years, and bought back about $4.5 billion of its own shares.
The Alphabet placement plus the reported Lennar accumulation constitute a concentrated view: one large technology cash-flow compounder and a rate-sensitive homebuilder position. Readers who want to borrow the rest of Berkshire’s homework can start with the seven cheapest dividend payers still in the portfolio, which we pulled into a free report here. Deploying cash reduces flexibility. A large balance is itself an asset in a disruption, so spending it is a real trade-off.
Operating Business Underneath
Operating earnings have moved around significantly. The last four quarters ran $12.98 billion in Q3 2026, $11.35 billion in Q1 2026, $10.20 billion in Q4 2025, and $13.48 billion in Q3 2025.
BNSF net income of $1.6 billion in the latest quarter continues to grow modestly, though the railroad’s margins still trail the best operators by too wide a gap. Insurance underwriting has weakened, and buyback activity disciplined to intrinsic value is itself a valuation signal from the people with the best information.
Bull and Bear Case for BRK-B Stock
Book value per share reported at $522,225.90 for the Class A and a price-to-book near one, unusually cheap for this company, anchors the optimistic thesis. $750 billion of shareholder equity, and buybacks resumed in early 2026, with $15 million of personal insider buying, support an entry.
The flat year is rational under the pessimistic view. A slower, more capital-intensive Berkshire with less deal flow and a shrinking cash buffer deserves a lower multiple than the version that accumulated Treasuries and waited. If the Alphabet and Lennar positions do not clearly compound, the market’s patience will thin.
The variable that decides between them is repurchase behavior. A sustained return to net equity selling alongside heavier buybacks would signal that insiders think $500 is cheap. A quiet buyback pace and continued deployment into public equities would signal the opposite.
Above $500, the setup looks slightly constructive because the valuation is not stretched and the insider signals are consistent. But thin coverage, succession uncertainty, and shrinking flexibility keep the risk-reward closer to balanced than the five-year chart suggests.
The post Is Berkshire Hathaway Stock a Buy, Hold, or Sell Above $500? appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) closed at $337.83, down 3.8% in the session, while the Wall Street consensus target still sits at $429.46. That is a gap wide enough to matter, and nothing was announced today to explain the move.
Alphabet runs Search, YouTube, Android, Google Cloud, and Waymo, and it just delivered its eleventh straight EPS beat and twelfth consecutive quarter of double-digit revenue growth. The stock is still up 8.14% year to date and 34.59% over one year.
The tension is about whether the market is starting to charge Alphabet for the cost of its own artificial intelligence buildout, a buildout that also has to be powered, cooled, and networked by somebody, which is the whole subject of our free report on seven AI infrastructure suppliers that aren’t chipmakers.
Reporting attributed the drop to rotation into Meta following its Muse artificial intelligence agent launch. A move without a disclosure is a positioning move.
A Selloff With Nothing Behind It
No earnings warning, guidance cut, or regulatory update preceded it. The stock gave back 3.8% in one session.
The last reported quarter looked strong on almost every line. Revenue of $119.8 billion grew 24.23% year over year, and Google Cloud accelerated to 82% growth at $24.8 billion in quarterly revenue.
Capital expenditures hit $44.9 billion in the quarter, up 100.14% year over year, while free cash flow turned negative at -$5.9 billion.
Long-term debt roughly doubled from $46.5 billion to $98.2 billion, and the buyback was suspended. Management prioritized compute over shareholder returns.
Why Analysts Have Not Moved Their Targets
The consensus target of $429.46 reflects bullish coverage, with 2 Strong Buy and 1 Buy calls with zero Holds or Sells in Alpha Vantage’s sample. 53 analysts contribute to the 2026 EPS estimate.
The bull thesis rests on Cloud conversion. Backlog stood at over $460 billion as of the first-quarter report, up from $155 billion reported for the third quarter of 2025. Backlog is contracted revenue not yet recognized, and it converts only if Alphabet has the compute to serve it.
Consumer artificial intelligence is holding. Nearly 90% of the Fortune 100 use Gemini Enterprise, and the Gemini App has 950 million monthly active users.
The 2026 EPS consensus has climbed from $14.23 ninety days ago to $20.62 currently. Analysts are marking Alphabet up.
Sector peers held up. Money rotated into Meta Platforms (NASDAQ:META) on the day of its Muse artificial intelligence agent launch, while Microsoft (NASDAQ:MSFT) and Amazon (NASDAQ:AMZN) traded on their own catalysts.
Alphabet carries a P/E of 18x and a forward multiple of 23x, the lowest headline valuation among mega-cap artificial intelligence names. The discount reflects the free-cash-flow question rather than market oversight.
Bull and Bear Case for GOOGL Stock
You’d buy Alphabet here if you believe Cloud converts its backlog faster than capex compresses margins. The 82% Cloud growth rate and the $460 billion backlog support that thesis if compute supply keeps arriving.
You’d stay away if the buildout has barely begun. 2026 capex guidance sits at $175 billion to $185 billion, with internal projections reportedly closer to $375 billion.
The equity raise dilutes shareholders. Bond issuance adds interest expense that grew nearly 5x year over year, and the suspended buyback removes support under the stock.
The deciding variable is conversion speed. If Cloud pulls the backlog into revenue at high-double-digit growth for several more quarters, the multiple looks too low. If backlog growth flattens or Gemini cedes consumer ground to Meta’s Muse, the market’s caution today looks early rather than wrong.
Given demand signals against a shifted balance sheet, I lean cautiously constructive at this level. Free cash flow will decide whether the current multiple is a gift or an accurate warning.
The post Alphabet Drops Below $350: Buying Opportunity or the Start of Something Worse? appeared first on 24/7 Wall St..
]]>ARK Invest’s daily trade files show Cathie Wood’s funds adding to Rocket Lab (NASDAQ:RKLB) while trimming Alphabet (NASDAQ:GOOGL). The disclosures themselves list tickers, funds, and share amounts. They do not include a reason. Anything offered as motivation from here is inference, and readers should treat it that way.
What is verifiable from ARK’s own portfolio data: as of the July 31, 2026 ARKK snapshot, Alphabet was still held across both share classes, with $118.5 million in GOOG (2.13% of net assets) and $27.0 million in GOOGL (0.49% of net assets). Rocket Lab was not in the ARKK snapshot at that date, consistent with recent RKLB adds landing in ARK’s space and next-generation internet vehicles rather than the flagship.
What Is Actually Happening at Rocket Lab
The buy comes into a business that is being rebuilt in front of investors. Rocket Lab reported Q2 2026 revenue of $234.07 million, up 62% year over year, with backlog reaching a record $2.36 billion. Q3 revenue guidance is $250 million to $265 million.

Two developments matter more than the quarter. First, Rocket Lab announced a deal to acquire Iridium Communications, funded in part through equity issuance that has already brought in $1.53 billion in ATM proceeds during the first half of 2026. Iridium would bolt a recurring satellite communications revenue stream onto a company whose top line has been dominated by launches and lumpy program awards. Recurring revenue commands a different multiple than project revenue because it is predictable, higher margin at scale, and can be forecast years out.
Second, the medium-lift Neutron rocket is targeted for launch pad delivery in Q4 2026, following an earlier stage-one tank test failure that pushed the timeline. If Neutron flies, Rocket Lab moves from small-satellite launch specialist to a genuine competitor for larger national security and commercial payloads.
The valuation reflects the promise well ahead of the profits. Shares trade at $70.23, with a price-to-sales ratio of 58 and Q2 net income of negative $49.3 million. Details on the Iridium financing and dilution risk sit in Rocket Lab’s August 10, 2026 8-K.

Why ARK Is Trimming Alphabet
The Alphabet reduction is the smaller side of the rotation. Institutions trim mega-caps for position sizing, index-drift management, and mandate reasons. Alphabet just posted Q2 2026 revenue of $119.80 billion (+24.23% year over year) with Google Cloud growth of 82% to $24.77 billion. Shares are $338.19, up 34.27% over the past year. That is not the profile of a business ARK would be exiting on fundamentals.
A defensible inference: ARK’s mandate rewards concentration in disruptive, small- and mid-cap names. Alphabet at a ~$4.29 trillion market cap with FY2026 capex guidance of $175 billion to $185 billion and Q2 free cash flow of negative $5.86 billion is a different asset than what ARK typically overweights.
What Following an ARK Trade Actually Means for Retail
ARK is a high-conviction, high-volatility manager. Its disclosed trades are point-in-time snapshots, and the funds turn over positions frequently. Rocket Lab is a speculative holding: unprofitable, richly valued, exposed to Neutron schedule slippage, and issuing equity to fund acquisitions. It carries materially higher risk than a mega-cap position, and readers should size it accordingly.
What to watch next: Neutron’s arrival at the launch pad, closing progress on Iridium, and Rocket Lab’s Q3 report against the $250M-$265M guide. On Alphabet, keep an eye on whether cloud growth holds above 60% and whether capex intensity begins to compress free cash flow further into 2027.
The post Why Cathie Wood Is Trimming the World’s Biggest Tech Stock to Bet on a Space Company appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG) has quietly become one of the most consequential AI stocks on the market, and a $5,000 stake today lands in the middle of a five-year window that could reshape the return profile of a long-only portfolio.
Shares recently traded near $350.87, up 36.4% over the past year, as the company scales Gemini, cloud infrastructure, and search monetization. The question for retail investors is simple: what could that $5,000 be worth by September 2031?
Base Case: $5,000 Could Grow to Roughly $14,860
Under the base-case five-year scenario, a $5,000 investment in Google could be worth about $14,859.50 by 2031, a total return of 197.19%, or an annualized 24.34%. That path is anchored to a modeled per-share target of $1,042.74 on September 21, 2031.
The model carries a high confidence classification with a buy recommendation, and it sits alongside a Wall Street analyst consensus target of $422.34 that is calibrated to a one-year horizon rather than five.
Bull, Base, and Bear Scenarios for a $5,000 Stake
| Scenario | Target Price (2031) | Total Return | Value of $5,000 |
|---|---|---|---|
| Bull | $1,148.71 | 227.39% | $16,369.50 |
| Base | $1,042.74 | 197.19% | $14,859.50 |
| Bear | $585.32 | 66.82% | $8,341 |
Even the bear case still delivers a positive return, with the $5,000 stake growing to $8,341 on an annualized 10.78%. The bull case, powered by faster AI monetization, would take that same starting investment to roughly $16,369.50.
Why the Model Sees Substantial Upside
Three drivers stand behind the projection. First, analyst calibration is extraordinarily one-sided. The consensus is anchored by 13 strong-buy, 43 buy, and 5 hold ratings, with zero sell or strong-sell calls, translating to a 92% bullish share among covering analysts.
Second, the underlying business is compounding at a pace that few mega-caps can match. Q2 FY26 revenue rose 24% year-over-year to $119.8 billion, marking the 12th consecutive quarter of double-digit revenue growth.
Google Cloud revenue grew 82% to $24.8 billion, and cloud operating margin expanded to 35.6% from 20.7% a year earlier. The Cloud backlog stands at $514 billion, with management expecting to recognize just over 50% of it as revenue over the next 24 months.
Third, AI adoption is translating directly into product usage and enterprise commitments. The Gemini app now has 950 million monthly active users, model APIs process roughly 22 billion tokens per minute, and nearly 90% of Fortune 100 companies use Gemini Enterprise.
CEO Sundar Pichai told analysts, “It feels like we are in very early innings of what feels like secular shift across multiple areas in our core information businesses.”
Risks That Could Sink the Projection
The bear case exists for good reason. Google is spending aggressively to fund its AI buildout: capital expenditures reached $44.9 billion in Q2 alone, and free cash flow swung to negative $5.9 billion. Full-year 2026 capex guidance sits at $175 billion to $185 billion, and long-term debt has roughly doubled from $46.5 billion to $98.2 billion.
Management has flagged that third-party capacity usage in Q3 could pressure Google Cloud operating margins, and regulatory scrutiny remains live after a $3.5 billion EC fine in Q3 2025.
Frontier AI competition from OpenAI, Anthropic, and Meta (NASDAQ:META) is intensifying, and any slowdown in search monetization as users shift to AI Overviews could compress the base case toward the bear path.
Bottom Line for a $5,000 Stake
The modeled range for $5,000 invested in Google over the next five years spans roughly $8,341 in the bear case to about $16,369.50 in the bull case, with a base-case landing point near $14,859.50.
Those figures reflect a modeled 247Factor of 1.119, a forward EPS of $23.54, and an implied P/E of 18. This is a projection built on current data and assumptions, not investment advice or a guarantee, and actual returns will depend on how Google executes its AI capex, defends search, and scales cloud through the back half of the decade.
The post What Will $5,000 Invested in Alphabet Stock Be Worth in 5 Years? appeared first on 24/7 Wall St..
]]>Alphabet has quietly become one of the most compelling stories in the Magnificent Seven this year. Google (NASDAQ:GOOG) shares are up 12.46% year to date and 39.95% over the past year, closing in on $352.22 as investors digest a Google Cloud business now growing faster than any hyperscaler on the planet.
CEO Sundar Pichai called Q2 “an amazing quarter” for a reason: cloud revenue accelerated to 82% growth, and Gemini adoption is spreading through the Fortune 100.
So let’s walk through what it would take for Google to reach $525 per share by 2027.
Wall Street Sees More Upside Ahead
The consensus 1-year price target sits at $422.34, backed by 13 strong buys, 43 buys, and 5 holds with zero sell ratings. Analysts see 2027 revenue reaching $612.19 billion, up from an expected $498.36 billion in 2026.
Estimates keep drifting higher: the 2027 EPS consensus has climbed from $14.45 ninety days ago to $14.84 today, with 9 upward revisions in the last 30 days against just 1 downward.
Google has also topped Wall Street’s EPS estimates in 11 consecutive quarters, which means actual 2027 results will likely land above the current consensus.
Here’s the Math for a Move to $525
At today’s $352.22, GOOG trades at a trailing P/E of just 17 on TTM EPS of $19.94. Hitting $525 would lift that multiple to roughly 26x trailing earnings. That is a premium to the S&P 500’s 21x to 23x forward multiple, but hardly stretched for a business compounding revenue at 24.2% year over year with 34% operating margins.
What could push Google to $525:
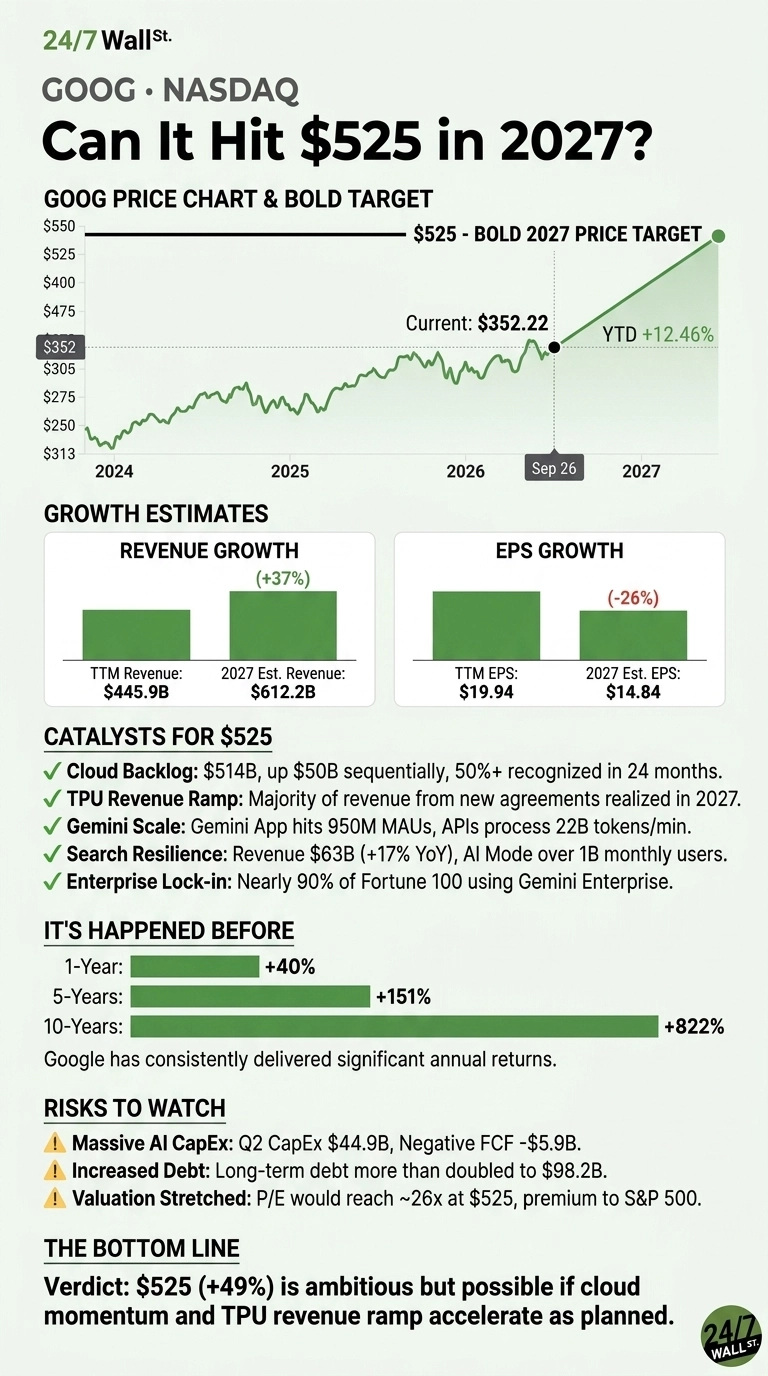
- Cloud backlog conversion. Google Cloud backlog now sits at $514 billion, up more than $50 billion sequentially. Management expects to recognize over 50% of that backlog as revenue in the next 24 months.
- TPU revenue ramp. Alphabet said “the vast majority of the revenues from these agreements will be realized in 2027,” a direct tailwind for the year the bold target lands.
- Gemini scale. The Gemini app has hit 950 million monthly active users, and APIs process 22 billion tokens per minute, up from 10 billion in Q4 2025.
- Search resilience. Search revenue still grew 17% to over $63 billion, with AI Mode topping 1 billion monthly users.
- Enterprise lock-in. Nearly 90% of the Fortune 100 now use Gemini Enterprise.
Pichai framed the opportunity plainly: “from ROIC standpoint, I think, you know, we are taking a full stack approach… over the past year, we’ve gotten more bullish on the opportunities ahead.”
Google’s History Says $525 Is Within Reach
A move to $525 requires roughly a 49% gain. GOOG has already returned 151.36% over five years and 821.89% over ten.
Our internal quantitative model pegs the base-case one-year price at $519.98 with a bull case of $586.04, translating to a 50.98% base return.
Bottom Line on $525
Reaching $525 asks Google to deliver another 49% in twelve months, on top of the 40% it has already produced over the last year.
The hurdles are real: free cash flow turned negative $5.86 billion in Q2 as CapEx exploded to $44.92 billion, and long-term debt has more than doubled to $98.2 billion.
But with cloud accelerating, TPU revenue set to peak in 2027, Gemini scaling into a billion users, and estimates still climbing, the setup is there. We have outlined the blueprint for how Google could deliver an outsized 2027.
The post Prediction: This Magnificent Seven Stock Could Soar 50% by 2027 appeared first on 24/7 Wall St..
]]>IPOs tied directly to the AI industry are being delayed. SoftBank, one of the largest financiers of AI projects, is paying unexpected premiums on its debt. AI data centers are being delayed at a rate that threatens AI adoption across business, government, and personal levels. OpenAI faces questions about the viability of funding losses that could exist until the end of the decade.
SB Energy, owned by SoftBank and an AI infrastructure builder, has delayed its IPO, the New York Times reported. Holtec Nuclear, which makes small nuclear reactors, appears likely to delay its public offering. SoftBank is raising $10 billion but will need to pay junk-bond rates. Depending on duration, it must pay interest rates ranging from 8.75% to 9.875%, Bloomberg reported. Goldman Sachs issued a report that said AI debt funding has hit $575 billion so far in 2026.
According to several sources, local laws and ordinances have blocked construction of over 500 data centers. A Gallup poll showed 70% of Americans do not want data centers where they live. If this slowdown in building out AI capacity continues, there is concern that AI use will automatically be capped.
OpenAI faces several threats as it moves toward an IPO that observers think will happen early next year. Rival Anthropic plans to go public in late 2026. If the Anthropic IPO stumbles, OpenAI faces a skeptical market. That alone could delay its IPO plans.
OpenAI and Anthropic face competition from US-based companies, which include Meta (NASDAQ: META) and Alphabet’s (NASDAQ: GOOG) Google. A larger threat, however, is from China’s AI products. They cost customers much less to use. They may not be as powerful as their American counterparts. Companies using AI have found that spending 80% less on Chinese AI works, because they may not need to build the world’s most advanced applications. And Chinese AI appears to be catching up to OpenAI and Anthropic’s best models.
Although the figure has changed more than once, OpenAI probably needs $280 billion to fund itself between today and 2030. Its annual revenue run rate was recently pegged at $40 billion. That is well behind Anthropic’s run rate. And Anthropic has started to make money.
What happens if OpenAI cannot go public? It devalues the entire industry. That includes the public companies which have high valuations because AI is at the center of their growth forecasts.
The post OpenAI IPO Collapse? appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG | GOOG Price Prediction) just posted the most striking quarter of any mega-cap AI beneficiary. Cloud grew 82% to $24.8 billion, backlog reached $514 billion, and CEO Sundar Pichai said Alphabet is in the “very early innings” of a secular AI shift.
Yet the stock trades at a 17x trailing P/E, the cheapest multiple in the mega-cap AI cohort. Shares sit at $352.20, up 12.46% YTD. Can this stock reach $600 by 2027? Here is the math.
What Is Really Holding Alphabet Back
The stock is stuck because of what fundamentals are costing. Q2 free cash flow swung to negative $5.855 billion as CapEx doubled to $44.92 billion. Long-term debt jumped from $46.5 billion to $98.2 billion, the buyback was suspended in Q2 2026, and management projected FY26 CapEx of $175 billion to $185 billion.
Investors are underwriting the biggest infrastructure build in corporate history (the power, cooling, and networking suppliers riding that same wave are the subject of a free report on seven AI infrastructure names that aren’t chipmakers).
That anxiety shows in the stock. Shares are up 3.14% over the past month and 4.99% over the past week, despite a 39.95% one-year gain. With a beta of 1.225, GOOG moves harder than the market when sentiment on AI capex shifts.
Wall Street Sees 20% Upside. My Model Sees 51%
The Street consensus target is $422.34, drawn from 13 strong-buy, 43 buy, and 5 hold ratings with zero sells. Bullish share sits at 92%. My base case is more aggressive: a $519.98 predicted price, or 50.98% upside, with a bull scenario of $586.04 and a bear case still at $427.72. Confidence: 0.9, high.
The Street is underweighting two things. First, the FY26 EPS estimate has moved from $14.23 ninety days ago to $20.60. Second, earnings growth contribution to my model is only 0.03.
Path to $600 Per Share
Reaching $600 from $352.20 requires a 70.4% gain.
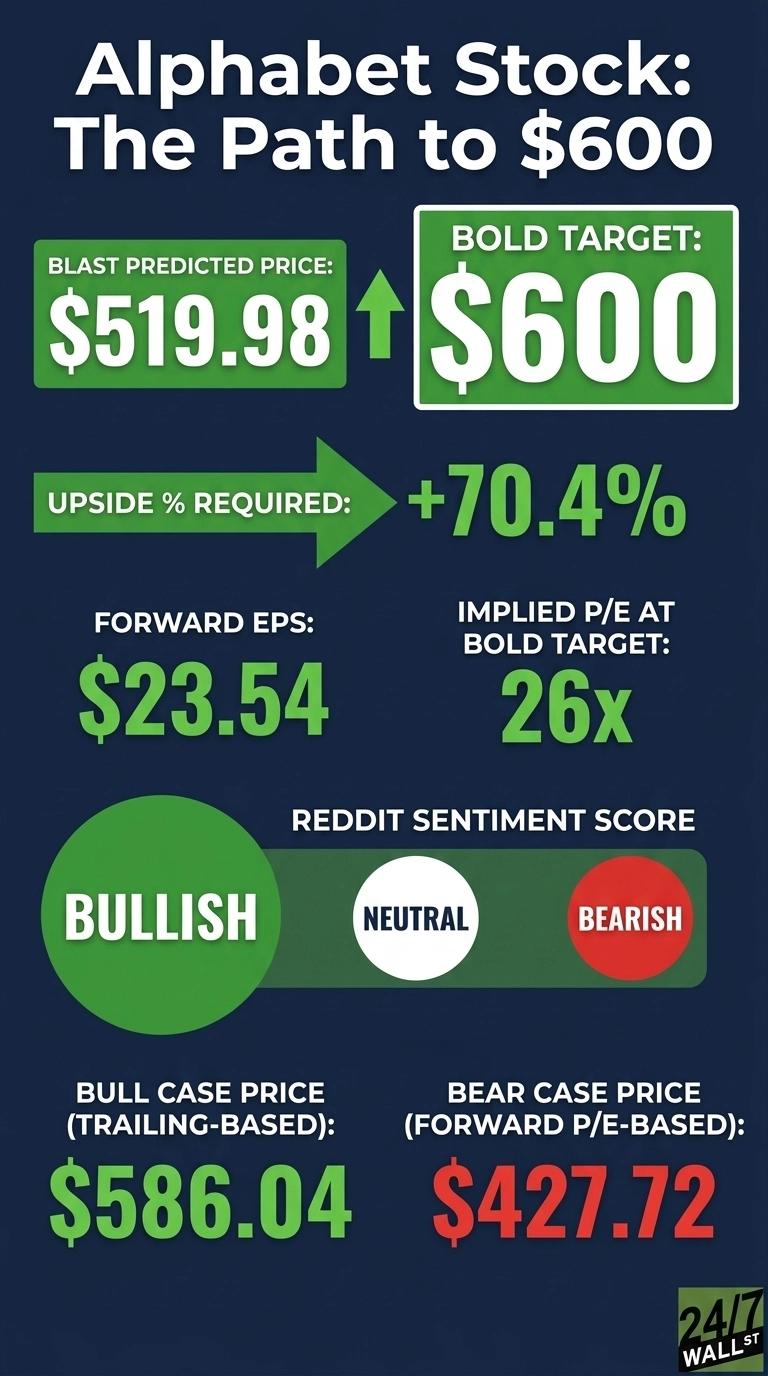
With forward EPS of $23.54, a price of $600 implies a forward P/E of 26x. My base case of $519.98 already implies 17x, meaning $600 requires roughly 8x of additional multiple expansion.
Cloud is compounding at 82% with 35.6% operating margins. Gemini processes 22 billion API tokens per minute and the Gemini App has 950 million monthly active users.
Pichai said “Our AI investments are redefining what’s possible across every part of our business.” As TPU system sales revenue arrives in 2027, EPS should reprice higher, letting the multiple expand without looking rich.
The primary risk: sustained negative free cash flow forces investors to discount the CapEx cycle harder than the market currently does.
Where Alphabet Trades Today Vs Its Earnings Power
At $352.20 against forward EPS of $23.54, GOOG trades at roughly 15x forward earnings. That is a discount to every mega-cap AI peer despite delivering an EPS surprise of 199.41% last quarter.
Shares sit between a 52-week low of $236.07 and high of $403.96, and have returned 821.83% over the past decade. Cheap growth compounding at scale is a rare setup.
Is $600 Realistic? My Verdict
Reaching $600 requires a 70.4% gain and a forward multiple of 26x. That is a stretch but achievable.
Three things need to go right: Cloud growth stays above 50%, the $514 billion backlog converts on schedule, and TPU system sales ramp meaningfully in 2027. A sharp deterioration in ad monetization from AI-answer cannibalization would derail it. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Google could reach $600 in 2027.
The post Prediction: The Cheapest Mega Cap in the AI Trade, Alphabet Could Hit $600 in 2027 appeared first on 24/7 Wall St..
]]>Big tech’s 2026 has been a story of AI infrastructure spend meeting enterprise adoption. Let me walk through three names where the setup into 2027 still looks compelling: Google, NVIDIA, and Salesforce. Each gets a round-number bull target above Wall Street’s consensus, along with the math to back it up.
Google: A Path to $500 on Cloud Acceleration
Alphabet (NASDAQ:GOOG) trades near $352.20, up 12.46% year to date and 39.95% over the last year. Wall Street’s average target sits at $422.34. My bold target is $500, which would put shares at roughly 34x the FY27 EPS consensus of $14.84.
That is a premium to the market’s 21x to 23x, but Q2 growth backs it up: revenue jumped 24%, Cloud accelerated to 82%, and cloud backlog hit $514 billion.
CEO Sundar Pichai said “we are in very early innings of what feels like secular shift.” With nearly 90% of Fortune 100 companies on Gemini Enterprise and TPU system sales just beginning to flow, $500 is ambitious but achievable.
NVIDIA: $350 Looks Reasonable on Vera Rubin
NVIDIA (NASDAQ:NVDA) sits at $227.50, up 22.27% YTD. Wall Street targets $327.70. My bold target: $350. At that price, NVIDIA would trade at roughly 22x the FY28 EPS consensus of $15.68, which has surged from $12.67 just 90 days ago on 42 upward revisions.
Q2 revenue more than doubled to $96 billion, and management guided FY28 growth of approximately 70%, calling it supply constrained. Jensen Huang put it plainly: “AI has reached its inflection point. Compute is revenue.”
AWS just committed to deploying an additional 2 million GPUs, and hyperscaler capex is tracking toward nearly $800 billion in 2026. NVIDIA has returned north of 943% over five years. A 54% run to $350 is well within its historical range.
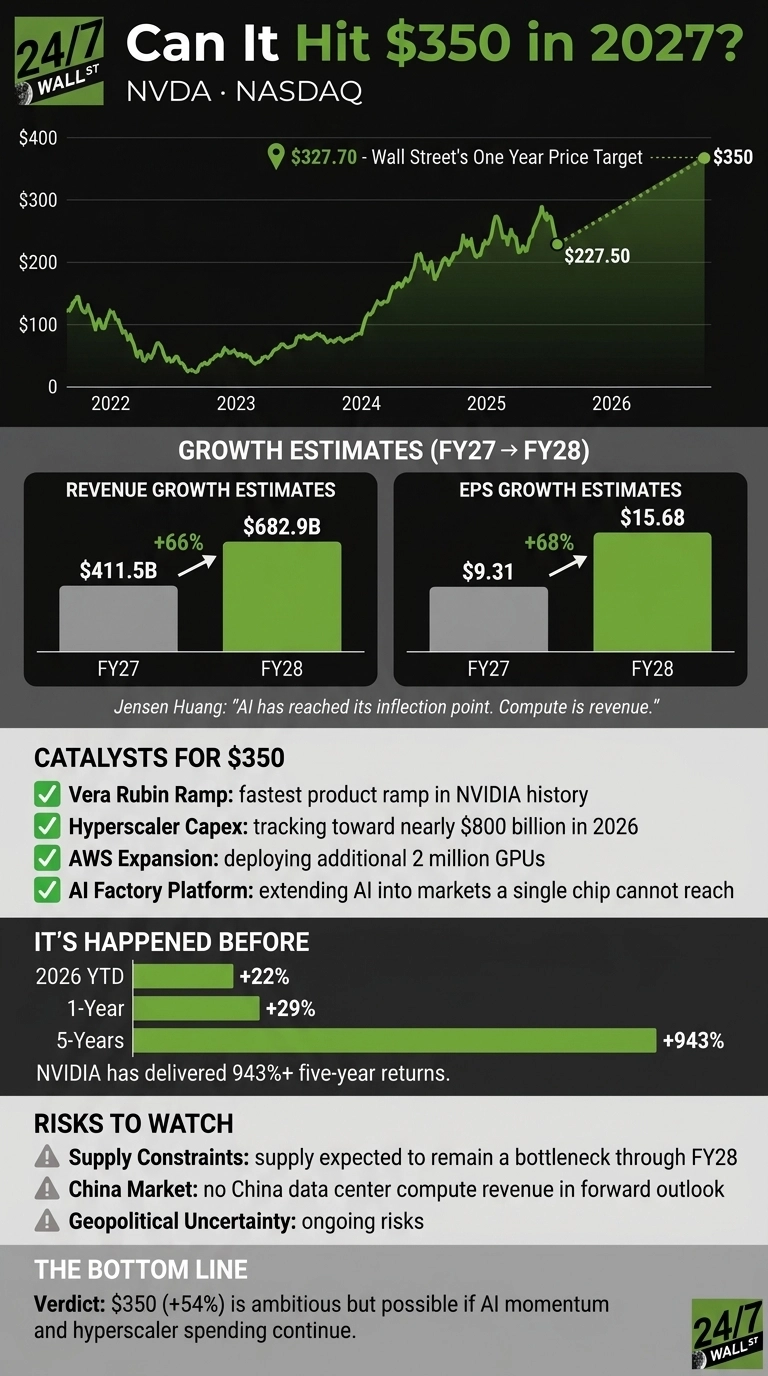
Salesforce: $325 on Agentforce Monetization
Salesforce (NYSE:CRM) has lagged, down 9.6% YTD at $237.79. Wall Street’s average target is $282.49. My bold target is $325, which implies roughly 20x the FY28 EPS estimate of $15.99.
That is a modest multiple for a company whose Agentforce and Data 360 ARR is “about to cross $4 billion” with Agentforce alone at $1.5 billion ARR and bookings that doubled year on year. Q2 EPS of $5.90 topped the $3.27 estimate for a sixth straight beat.
CEO Marc Benioff argued “AI isn’t replacing Salesforce. It’s unlocking more value across all four layers of our platform.” With only 5% of knowledge workers on premium editions, the monetization runway is real.
Bottom Line on 2027 Upside
These targets require rallies of roughly 42% for Google, 54% for NVIDIA, and 37% for Salesforce. All three sit on rising estimates, multi-quarter beat streaks, and concrete AI catalysts already in motion.
The common thread is the infrastructure buildout behind them, and we profiled seven suppliers powering that boom, from power to cooling to networking, in a free report you can grab here. Returns of this magnitude remain rare, yet the blueprint for outsized 2027 gains is clearly on the table.
The post 3 Big Tech Stocks With the Most Upside Right Now appeared first on 24/7 Wall St..
]]>Two headlines described what could stop AI expansion in its tracks. The New York Times reported, “Wall Street Is Growing Skeptical of the Data Center Boom.” Bloomberg wrote, “New Data Centers Worth $68 Billion Disrupted in US, Data Show.” (The information came from Data Center Watch and included an analysis of four data centers.) The centers had been blocked or delayed between April and June.
Another widely accepted count of how data centers are performing comes from “The Information.” It puts data center bans at over 500.
Data centers are the power centers of AI. Without them, one could say there is no AI at all. It is an engine without tires, or a plane without wings. If AI is supposed to be the greatest invention in history, it could be crippled by something as old as brick-and-mortar.
Data center investment for 2030 has been put as high as $1 trillion. Some put the investment level at $650 billion this year. Major public companies, including Microsoft (NASDAQ: MSFT) and Alphabet (NASDAQ: GOOG), are leading this expansion. Private companies like OpenAI and Anthropic are joining them, and they expect to use the tens of billions raised by their IPOs to expand AI infrastructure. As these tech companies drain their balance sheets, Wall St.’s largest firms have begun pouring even more money into the sector.
The Times points out that several companies that planned to go public using their data center building plans won’t go public soon. This raises the question of whether they will run low on money.
A new Gallup poll sums up the AI data center challenge. Titled “Americans Oppose AI Data Centers in Their Area,” it reported, “Seven in 10 Americans oppose constructing data centers for artificial intelligence in their local area, including nearly half, 48%, who are strongly opposed.”
Candidates across the political spectrum are running on platforms to stop the buildout of data centers in their districts, cities, and states. It is one of the few issues that unites both Democrats and Republicans.
In the short term, no solution appears to exist. Obviously, tech companies and data center builders have looked almost everywhere in the country where there is room for centers, which can be as large as cities and use up to five million gallons of water a day.
An even larger concern than water is the use of electricity. A large data center can use as much electricity as all the homes in a large city. As these centers compete for the electricity used by homes and legacy businesses, worries about them extend from jumps in electricity rates to blackouts. Part of America’s grid built decades ago may not be able to handle the load. And the demand for electricity is so great that the use of fossil fuels may well rise.
The one problem AI has not solved is how to build data centers to continue its success.
The post AI May Be Ruined Data Centers appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google’s family-focused CC, a shared agent supporting up to six family members, and Meta’s single-user Muse, aiming for higher autonomy across a user’s digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
CC vs. Muse
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user’s behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user’s digital life, including commerce. They compete in the emerging “AI agent that actually does things” category, but target different use cases and user models.
Yet only one of the companies is not breaking its margin profile to achieve this. Here is the head-to-head across the three dimensions that matter for a portfolio built to last decades.
Round 1: Valuation Gap That Is Hard To Ignore
Google trades at a trailing P/E of 14, with an earnings yield of 6.94%, against Meta’s P/E of 24 and 4.12% earnings yield. On book value, Google’s 4.58 P/B also undercuts Meta’s 6.76. Even after Google’s 36.85% one-year rally, the multiple is still priced like a slow-growth utility while the business is compounding like a hyperscaler. Winner: GOOG, decisively.
Round 2: Growth Trajectory And Margin Quality
Meta’s Q2 FY2026 report on July 29, 2026 looked strong on the top line: revenue of $60.80 billion, up 28% year over year. Below that, the picture cracked. EPS of $6.18 missed the $7.22 estimate by 14.4%, snapping a six-quarter beat streak. Operating margin compressed to 31% from 43% as costs surged 55%, including $2.40 billion in legal charges and $1.18 billion in severance tied to an 8,000-employee layoff. Free cash flow collapsed to $784 million from $8.55 billion a year earlier.
Alphabet’s July 22, 2026 report went the other direction. Revenue grew 24.2% to $119.80 billion, EPS came in at $9.11 versus a $3.04 estimate, and Cloud revenue jumped 82% to $24.8 billion with operating margin expanding from 20.7% to 35.6%. Backlog reached $514 billion. That is 11 consecutive EPS beats and 12 straight quarters of double-digit revenue growth, with margins going the right way. Winner: GOOG.
Round 3: Income Durability And Balance Sheet Strength
Neither name is a yield play. Google pays a 0.53% dividend yield after raising the quarterly payout 5% to $0.22 per share; Meta pays 0.36% at $0.53 quarterly. What matters for a retiree is whether the dividend can grow without stress. Google’s balance sheet carries debt-to-equity of 0.14 and interest coverage of 175.5x. Meta runs debt-to-equity of 0.39, with Reality Labs bleeding roughly $4 billion per quarter and active youth-related litigation with multiple U.S. trials scheduled. Google’s dividend has room to compound; Meta’s has more claims on it. Winner: GOOG.
Verdict: One Ticker For The Retirement Sleeve
For a retirement-focused investor, Google screens stronger on the fundamentals. It is cheaper on every valuation metric, growing faster on the segment that matters most (Cloud at 82%), expanding margins while Meta contracts them, and carrying a fortress balance sheet that can fund AI capex without threatening the dividend. The stock is also up 145.78% over five years while Meta is down 14.4% over the last year.
Meta belongs in a different sleeve entirely: the aggressive-growth allocation for investors willing to underwrite Muse as a consumer-agent platform bet, tolerate 2026 capex of $130 to $145 billion, and accept that legal and Reality Labs charges will keep whipsawing quarterly results. GOOG offers exposure to the same AI-agent theme with cleaner numbers and lower volatility.
The post The AI Agent Wars Just Got Personal: Google’s CC vs. Meta’s Muse appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG) just delivered one of the loudest AI-era quarters we have seen from a mega-cap. Google Cloud revenue jumped 82% in Q2 2026, backlog swelled to $514 billion, and the Gemini App now touches 950 million monthly active users.
Yet the stock is up just 7.11% year to date. Can Alphabet actually reach $600 per share by 2028?
What’s Holding Alphabet Back Right Now
The market is worried about one thing: capex. Alphabet spent $44.92 billion on capital expenditures in Q2 alone, guided full-year 2026 capex to $175 billion to $185 billion, and posted negative $5.86 billion in free cash flow. Buybacks were suspended in the quarter, and long-term debt climbed sharply to fund the AI buildout.
Shares reflect that anxiety. GOOG is down 1.96% over the past month and essentially flat over the past week (0.04%). With a beta of 1.225, this is not a quiet stock, and investors are demanding proof that the spend converts to durable cloud economics before rerating it.
Wall Street Sees 26% Upside. Our Model Says 50%
The Street’s consensus target sits at $422.34, backed by 13 strong-buy, 44 buy, and 5 hold ratings, with zero sells. Our own base case is more aggressive at $504.21, implying 50.31% upside, with a bull case of $568.59 and bear case of $416.69. Confidence is rated high (0.9).
My take: consensus is too anchored to trailing multiples. Analyst sentiment is 92% bullish with zero bears, yet the target implies almost no multiple expansion. With Google Cloud compounding at triple-digit-adjacent rates and TPU system revenue set to ramp in 2027, that anchoring looks stale.
Path to $600 Per Share
Reaching $600 from today’s price of $335.45 would require a gain of 78.9%. With forward EPS of $23.49, a price of $600 implies a forward P/E of 26x. Our base case of $504.21 already implies 17x, meaning the bold target requires roughly 9x of additional multiple expansion.
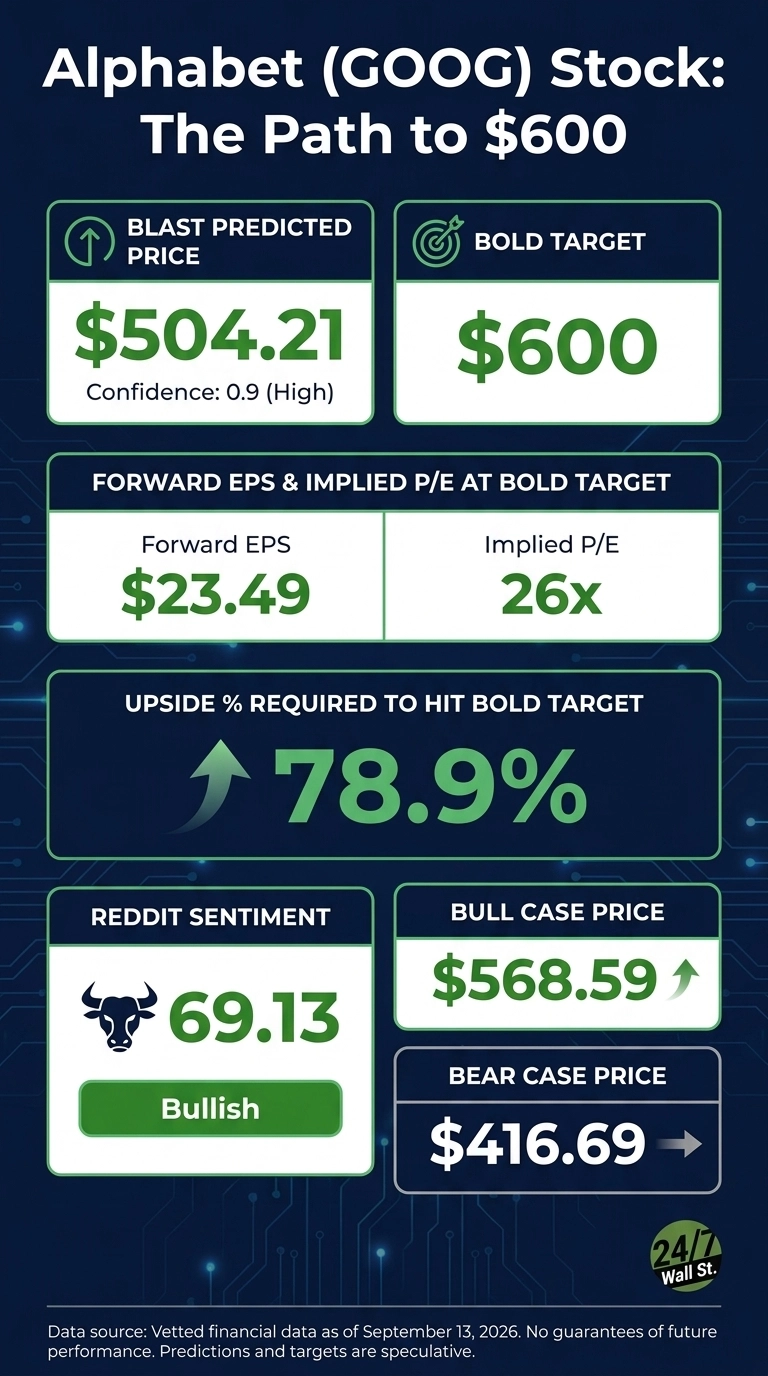
Achievable? Here is why I think it is. Sundar Pichai told analysts, “from ROIC standpoint… over the past year, we’ve gotten more bullish on the opportunities ahead.”
Three catalysts anchor the case: cloud backlog at $514 billion with just over 50% convertible to revenue within 24 months; Gemini Enterprise embedded in nearly 90% of the Fortune 100; and Search still expanding, with AI Mode now past 1 billion monthly active users. If EPS compounds and capex intensity moderates by 2028, P/E expansion follows.
The primary risk: a prolonged period of negative free cash flow if AI monetization lags the infrastructure build.
Where Alphabet Trades Today vs Its Earnings Power
At $335.45, GOOG trades at roughly 14x forward earnings. That is cheap for a business growing revenue 24.23% year over year with a 34% operating margin.
Shares sit between the 52-week high of $403.96 and low of $236.07, and the stock has returned 791.54% over 10 years. Valuation looks reasonable relative to the growth on offer.
Is $600 Realistic? Here’s My Take
Getting to $600 by 2028 requires that 78.9% gain, and it is a stretch. My verdict: realistic but not easy.
Three things need to go right. Cloud must sustain 40%-plus growth as backlog converts. Capex intensity has to peak in 2026 and roll into free cash flow expansion by 2027. Search monetization through AI Mode and AI Max needs to prove additive rather than cannibalistic.
What would derail it: a regulatory shock or evidence that TPU-driven cloud economics cannot scale into positive operating leverage. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Google could reach $600 in 2028.
The post Prediction: Alphabet’s Best Days May Still Be Ahead appeared first on 24/7 Wall St..
]]>“Father Time always wins.” That was Warren Buffett’s line, according to The New York Times, on September 18, 2026, the day he announced he was stepping down as chairman of Berkshire Hathaway. The New York Times reported he named his son to replace him, identified by Yahoo Finance as Howard. The Australian Financial Review noted he is stepping down at 96.
Berkshire got a new operator about a year ago, when Greg Abel became chief executive, and reporting on September 2, 2026 noted from finance.biggo.com that Berkshire shares barely budged in his first year. Chairman was the last title Buffett held, which is what makes today the actual close of one of the longest runs anyone has ever had at this job.
What follows is a walk through the five largest positions on Berkshire’s most recent 13F, disclosed as of June 30, 2026 and filed August 14, 2026. That filing describes what Berkshire held at the end of June and disclosed in August, so it is a portrait of a moment rather than a live account of what sits in the portfolio this morning. It also covers only US-listed equity. Some of Buffett’s finest calls, GEICO, See’s Candies, BNSF, do not appear here at all, because he bought the entire company rather than a slice of one. The filing captures half of what he built.
Apple, the Position That Rewrote the Book
The largest disclosed position was Apple (NASDAQ:AAPL), at 227,917,808 shares worth $65,950,296,923, representing 22.038266729497398% of the disclosed portfolio and 1.561703418760081% of Apple itself, according to Australian Financial Review. Apple designs the iPhone, the Mac, and the services stack that now hangs off both.
Fundamentally, Apple sits at a P/E of 44 with ROE of 171.4%, and its fiscal Q3 2026 report showed EPS of $2.02 versus $1.89 expected on revenue of $109.42B, up 16.4% year over year. Nine-month buybacks ran to $62.09B through June 27, 2026. Tim Cook told analysts Apple had its “strongest June quarter ever, with double-digit revenue growth across iPhone, Mac and Services, and in every geographic segment.” That Buffett let a single technology company grow into more than a fifth of the disclosed book is itself the point.
American Express, the Position That Started in the Salad Oil Scandal
American Express (NYSE:AXP) was second at 151,610,700 shares valued at $51,282,319,275, or 17.136745146261052% of the portfolio. Amex runs the closed-loop card and network that anchors the premium payments franchise Buffett has admired since the 1960s, according to Australian Financial Review.
Q2 2026 delivered EPS of $4.53 against $4.40 expected on revenue of $19.64B, with billed business of $455.8B, up 9%. Management raised FY26 revenue growth guidance to 10% and maintained EPS guidance of $17.30 to $17.90. CEO Stephen Squeri described the premium proposition this way: “a great premium value proposition is not just a product. It’s a multifaceted relationship between the brand and the customer.” The quarterly dividend has climbed to $0.95 per share. Six decades on, the thesis still reads like the same one.
Coca-Cola, and Owning a Tenth of the Company
Coca-Cola (NYSE:KO) is the position that best captures the Buffett method. Berkshire disclosed exactly 400,000,000 shares worth $32,508,000,000, a stake equal to 9.296814516232121% of the entire company, according to Australian Financial Review. He owned close to a tenth of Coca-Cola.
The business earned it. Q2 2026 delivered adjusted EPS of $0.97, revenue of $13.38B up 6.7%, and management raised FY26 guidance to comparable EPS growth of 9% to 10% and free cash flow of ~$12.4B. The quarterly dividend has climbed from $0.16 in 1999 to $0.53 today. New CEO Henrique Braun described the machine as “the strength of our total beverage portfolio” operating across “more than 200 countries and territories.” A brand held since the late 1980s, still compounding.
Alphabet, the Regret That Became a Holding
Alphabet (NASDAQ:GOOGL) came in at 78,791,167 Class A shares worth $28,157,599,351, or 9.40927810657434% of the portfolio. Berkshire’s filings historically report GOOGL and GOOG separately, and both classes represent the same company. Buffett had publicly called missing Google early one of his regrets, and eventually a position was established.
The fundamentals now look like a Buffett stock. Alphabet trades at a P/E of 15 with operating margin of 32.1% and ROE of 35.7%. Q2 2026 revenue was $119.80B, up 24.2%, with Google Cloud revenue of $24.77B, up 82%. Sundar Pichai told analysts “nearly 90% of the Fortune 100 using Gemini Enterprise.” The consensus analyst target sits at $428.07, with 13 strong buy, 45 buy, and 5 hold ratings. Better late than never.
Bank of America, the Warrant Deal That Became Common Stock
Bank of America (NYSE:BAC) rounded out the top five at 483,394,015 shares valued at $27,543,790,975, or 9.204164963158451% of the portfolio, according to Australian Financial Review. The position originated in Buffett’s 2011 preferred and warrant deal, later converted into common stock.
Q2 2026 was one of the better quarters the bank has printed: EPS of $1.21 versus $1.12 expected, revenue of $31.56B, and net income of $9.07B, up 27.5% year over year. Global Markets sales and trading came in at $7.2 billion, up 33%, with equities revenue at a record $3.6 billion, up 70%. CEO Brian Moynihan framed it plainly: “Our results show organic growth, operating leverage, and efficiency ratio improvement in every business segment.” A crisis-era rescue turned into a decade-plus core bank holding.
What the Top Five Says About Buffett’s Approach
Concentration is the through line. One consumer electronics company held 22.038266729497398% of the disclosed portfolio, one card network held 17.136745146261052%, and one soft-drink maker was owned at 9.296814516232121% of its entire share class, according to Australian Financial Review. The sector tilt is unmistakable: two financials in Amex and Bank of America, one branded consumer staple in Coca-Cola, and two dominant technology platforms in Apple and Alphabet. Behind the top five sat energy exposure, with Chevron at $13,986,141,890 and Occidental Petroleum at $12,868,205,304. Holding periods span from the 1960s salad oil trade in Amex to a recent Alphabet build, according to Australian Financial Review. Different decades, same pattern: a business he understood, held with unusual patience, sized with unusual conviction.
Arithmetic of a Life
A 96-year-old handing the chair to his son, with the company already in an operator’s hands, closing out one of the longest runs anyone has had at this, according to Australian Financial Review. The 13F is a backward-looking disclosure and none of this is investment advice. What it shows is a book built by someone who thought in decades and treated position size as a form of speech. He said what he thought about Coca-Cola by owning nearly a tenth of it. He said what he came to think about Apple by letting it grow into more than a fifth of the disclosed portfolio. Father Time gets everyone eventually. Very few get to hand off a body of work that reads like this one.
The post As Buffett Ends His Legendary Career, These Were His 5 Best Investments appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) will trade at or above $450 by the close on Friday, October 30, 2026, the first full session after its Q3 FY2026 earnings report scheduled for October 28, 2026, after market close.
From today’s $342.38, that is a defined move on a defined date, anchored to the single most consequential binary event on Alphabet’s near-term calendar.
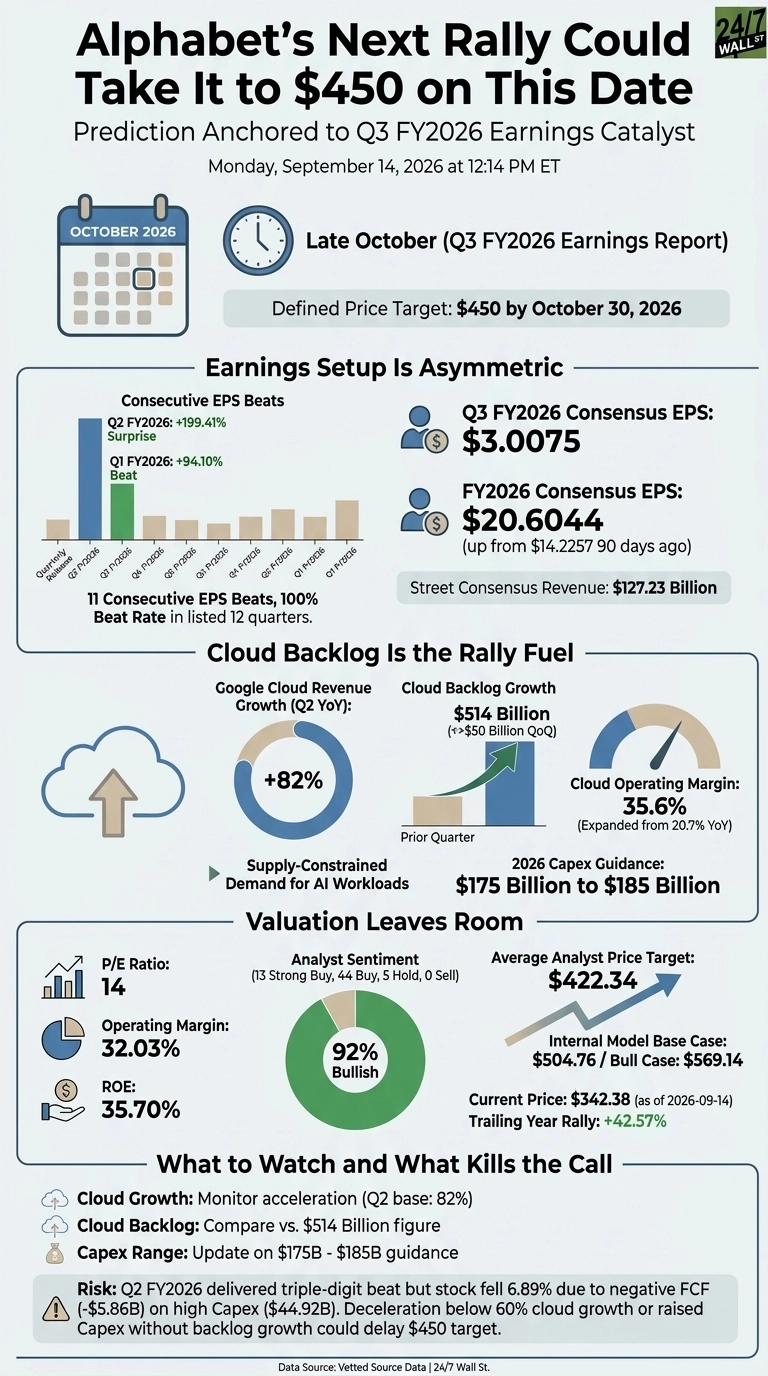
Earnings Setup Is Asymmetric
Alphabet has posted 11 consecutive EPS beats and beat in every one of the 12 listed quarterly releases. Q2 FY2026 delivered EPS of $9.11 versus $3.04 consensus, a 199.41% surprise, and Q1 FY2026 came in at $5.11 versus $2.63, a 94.10% beat.
Street consensus for the September quarter sits at $3.0075 EPS on revenue of $127.23 billion, and estimate revisions are running hot: the FY2026 EPS consensus stands at $20.6044, up from $14.2257 ninety days ago. That is a wholesale re-rating of the earnings power going into a report the market has repeatedly underestimated.
Cloud Backlog Is the Rally Fuel
Google Cloud grew 82% year-over-year to $24.77 billion in Q2, with backlog reaching $514 billion, a sequential increase of more than $50 billion. Cloud operating margin expanded to 35.6% from 20.7% a year earlier, and management has stated it remains supply-constrained across external and internal AI workloads.
TPU systems began generating recognized revenue in Q2 and are set to ramp as Alphabet exits 2026. Alphabet has already guided 2026 capex to $175 billion to $185 billion, and the Q3 earnings report is the first look at how that spend converts into billable capacity.
All of that hyperscaler spend has to be powered, cooled, and networked by someone, and we profiled seven of the suppliers riding that same wave in a free report on the AI infrastructure buildout.
Valuation Leaves Room
GOOG trades at a P/E of 14 against 32.03% operating margins and 35.70% ROE. Analyst coverage skews decisively bullish: 13 strong buy, 44 buy, 5 hold, zero sell, with sentiment at 92% bullish and an average target of $422.34.
The internal weighted model prints a one-year base case of $504.76 and a bull case of $569.14. A $450 close in six weeks sits below both, and the stock has already rallied 42.57% over the trailing year. The Q3 25 report produced a 12.1% thirty-day gain; a similar reaction off this base clears the target.
What to Watch and What Kills the Call
Investors should key on three lines in the October release: Google Cloud year-over-year growth (the accelerating 82% base is the anchor), the Cloud backlog figure versus $514 billion, and any update to the $175 billion to $185 billion capex range.
The risk is real: Q2 FY2026 delivered a triple-digit beat and the stock still closed down 6.89% on the day as free cash flow ran to negative $5.86 billion on $44.92 billion of quarterly capex. If Cloud growth decelerates below 60% or capex guidance is raised without a matched backlog figure, $450 slips into 2027. Weighing the setup, the estimate momentum, and the backlog, the call stands: $450 by October 30.
The post Price Prediction: Alphabet’s Next Rally Could Take It to $450 on This Date appeared first on 24/7 Wall St..
]]>Shares of Arm (NASDAQ:ARM) trade at $243.98, down 10.11% over the past month and 7.66% in the last week, yet still up 123.2% year to date.
The pullback across AI chip names reflects market concerns about softening demand from frontier labs. CEO Rene Haas argues the opposite: order books are full and growing, and near-term revenue growth is capped by how quickly the global chip supply chain can produce silicon. A demand slowdown and a manufacturing bottleneck produce different stock outcomes even when both cause missed quarters.
If Haas is right, the drawdown is a buying window into a company whose data center royalty stream compounds at triple-digit rates. If he is wrong, an investor pays a trailing P/E near 247x for a story that has begun to break.

Demand Breadth Across Edge, Auto, Robotics and Data Center
Haas insisted no single end market carries the company, citing edge, automotive, robotics and data center all running at record strength. Robotics matters more than it sounds. A humanoid or industrial machine ships with many Arm CPUs rather than one, because sensing, control and actuation each demand their own compute silicon, multiplying royalty units per unit shipped.
Data center is already visible in the numbers. Data-center royalty revenue more than doubled year over year last quarter, and the most recent 500 million Neoverse cores shipped in the last nine months after the first billion took six years.
Why a Multi-Stage Bottleneck Keeps Revenue Capped
Haas described the constraint as spread across wafers, substrates, testers, and memory rather than sitting at any single node. A multi-stage bottleneck is harder to fix because expanding one stage does not release throughput until every other stage catches up.
That keeps pricing firm because customers cannot easily source substitute capacity. It also caps how fast Arm converts its order book into recognized royalty and silicon revenue, since chips that do not exist generate no royalties.
Arm has secured the manufacturing capacity needed to support the $1 billion opportunity for its AGI CPU and is working with partners to expand further, according to Arm Holdings. Haas said the market is “very, very tight” across memory, test equipment, substrates and TSMC wafers.
Guidance Round Trip and Pivot to Data Center Silicon
Rene Haas earlier cut the AGI CPU target to $1 billion amid foundry capacity worries. On CNBC this week, he said his confidence in achieving the $2 billion target had risen from May to July and again from July to September.
Pair that with his claim that “data center is going to be our largest business”. For a company built on smartphone royalties, that pivot changes customer concentration, deal size, and margin trajectory.
The AGI CPU is Arm’s first in-house data center chip with a different margin profile than pure IP licensing. Management guided first-generation gross margin in the high 30% range to low 40s, with a path to 50% over the next couple of years, well below core royalty margins, meaning silicon revenue will initially dilute reported profitability even as it grows the top line.

Bull and Bear Case for ARM Stock
The bull case rests on demand breadth and secular share gains. IDC reported spending on Arm-based accelerated server platforms has nearly doubled in the past two quarters and surpassed x86, and hyperscaler design wins at NVIDIA (NASDAQ:NVDA), Google (NASDAQ:GOOG, NASDAQ:GOOGL), AWS and Microsoft (NASDAQ:MSFT) lock in multi-year royalty streams. Analysts carry an average target of $288.70.
The bear case is that a chief executive describing his own demand has an obvious interest in the story, and “supply constrained” is the most flattering explanation for revenue that arrives later than promised. Q1 FY2027 EPS of $0.25 missed the $0.40 estimate, and operating margin compressed to 7% from 11%.

The test is clean. If Arm ships silicon by the end of calendar year 2026 and the AGI CPU line clears the $2 billion mark across fiscal 2027 and fiscal 2028, Haas is right; if shipments slip or the number gets walked back again, the bear wins.
The post Arm’s CEO Says Demand Is ‘Off the Charts.’ The Problem Is Nobody Can Build Chips Fast Enough appeared first on 24/7 Wall St..
]]>Alphabet’s second-quarter results made one thing clear: Google Cloud is no longer the sidekick to Search. Cloud revenue grew 82% to $24.8 billion, and backlog jumped more than $50 billion sequentially to $514 billion.
That backlog alone is larger than Alphabet’s entire fiscal 2025 revenue base. If you are hunting for the next leg of upside in Google (NASDAQ:GOOG), Search is the foundation, but Cloud and enterprise AI look like the real accelerant.
Our 24/7 Wall St. price target for Alphabet is $504.76, implying 50.47% upside from a current price of $335.45. The recommendation is buy, with a model confidence of 90%. Below, I walk through how we got there and what could push the stock even higher, or pull it back.
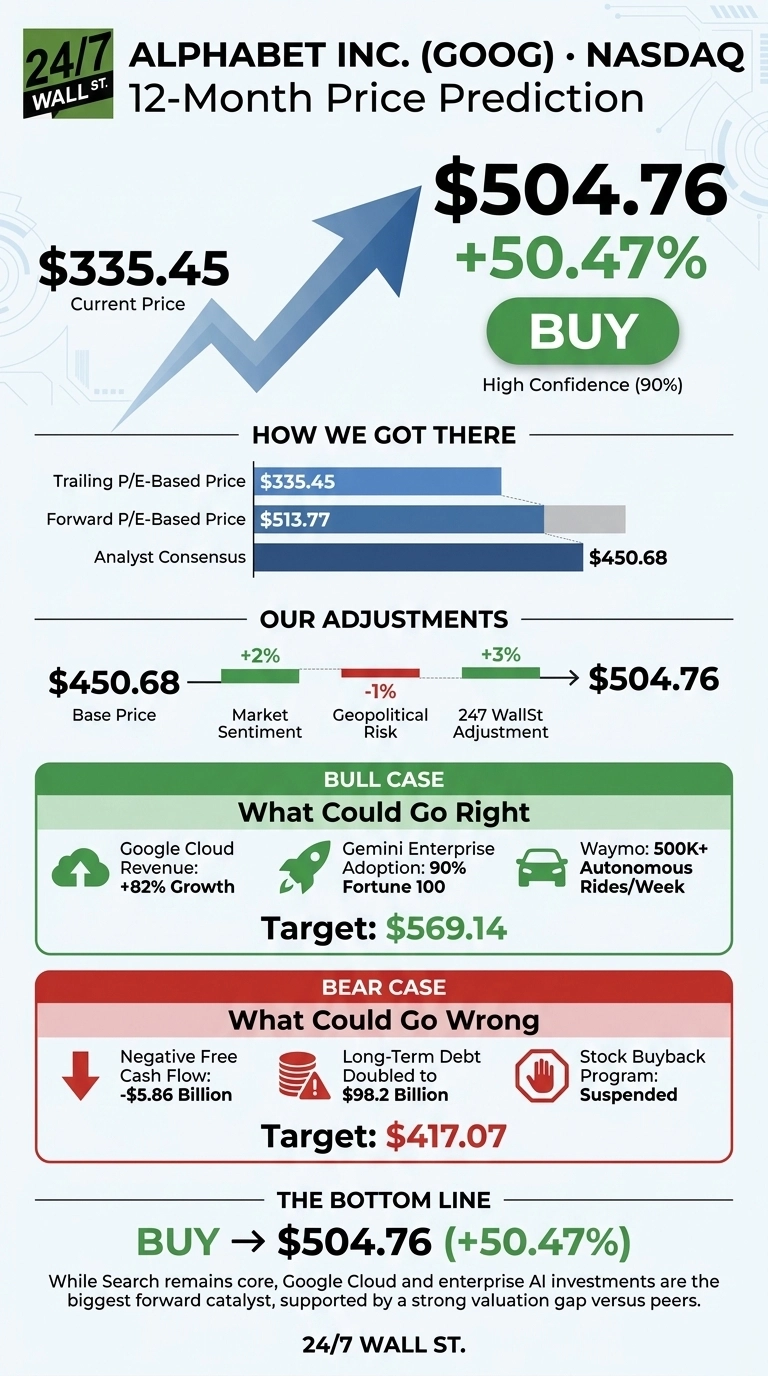
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $335.45 |
| 24/7 Wall St. Price Target | $504.76 |
| Upside | 50.47% |
| Recommendation | BUY |
| Confidence Level | 90% |
Cloud Acceleration Is Rewriting the Alphabet Story
GOOG is up 42.62% over the past year and 9.36% year to date, with shares recently changing hands near $342.50.
Q2 2026 was the anchor: EPS of $9.11 blew past the $3.04 consensus, revenue hit $119.8 billion, up 24.23% year over year, and operating margin expanded to 34%. Cloud growth accelerated from 48% in Q4 2025 to 63% in Q1 2026 and 82% in Q2 2026.
Barron’s noted this week that Google and Meta are emerging as winners from the latest round of AI concerns, thanks in part to their internal model economics.
Bull Case: $569 and Beyond
The bull scenario in our model points to $569.14, and it hinges on Cloud. Nearly 90% of the Fortune 100 use Gemini Enterprise, Gemini App has 950 million monthly active users, and model APIs process 22 billion tokens per minute, up from 16 billion a quarter ago.
Alphabet expects to recognize just over 50% of the $514 billion backlog within 24 months, and TPU system revenue is expected to ramp largely in 2027. Add Waymo scaling to 500,000+ autonomous rides per week and a YouTube run rate above $60 billion, and the non-Search catalysts stack up quickly.
What Could Go Wrong
The bear scenario lands at $417.07, still above today’s price. The risks are real: Q2 capex of $44.9 billion doubled year over year, free cash flow swung negative to -$5.86 billion, long-term debt roughly doubled from $46.5 billion to $98.2 billion, and buybacks are suspended.
It should be noted, however, that bulls would argue the capex surge reflects supply-constrained demand rather than misallocation (all that spending flows to the power, cooling, and networking companies we profiled in a free AI infrastructure report).
Management is still describing itself as supply constrained, and cloud operating income more than tripled to $8.8 billion with margins climbing to 35.6%.
How Alphabet Compares to Microsoft and Amazon
Microsoft (NASDAQ:MSFT) is the natural cloud-and-AI comp. Azure just surpassed $100 billion in annual revenue, Azure grew 43% in fiscal Q4 2026, and commercial RPO reached $678 billion. Yet MSFT trades at a P/E of 28 versus GOOG’s 14. Google Cloud is growing faster (82% vs. 43%) at roughly half the multiple, which is precisely why our target looks conservative rather than aggressive.
Amazon (NASDAQ:AMZN) is the other AI infrastructure spender. AWS grew 37% to $42.2 billion in Q2 2026 with a 39.4% operating margin, and Andy Jassy guided to roughly $200 billion in 2026 capex. AMZN trades at a P/E of 36.
Google Cloud is now growing more than twice as fast as AWS while GOOG trades at less than half the earnings multiple. That valuation gap is the single strongest support for our 24/7 Wall St. price target.
| Company | P/E | Cloud Growth (latest Q) |
|---|---|---|
| Alphabet | 14 | 82% |
| Microsoft | 28 | 43% |
| Amazon | 36 | 37% |
Why I’d Own It Here
My take: the 24/7 Wall St. price target of $504.76 with 90% confidence is a buy, and the tipping factor is the valuation gap versus MSFT and AMZN despite superior cloud growth. The setup strengthens if free cash flow stabilizes as 2027 TPU revenue ramps.
The thesis weakens if capex keeps climbing without margin follow-through in Cloud. Prediction markets are more cautious, pricing a 0.815 probability that shares hit $350 in September, but the 12-month setup is materially more constructive.
Looking further out, our model projects the following trajectory, assuming Cloud growth normalizes gradually and Search remains resilient.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $377.79 |
| 2027 | $514.71 |
| 2028 | $653.64 |
| 2029 | $817.33 |
| 2030 | $940.70 |
These projections assume Alphabet keeps executing on its full-stack AI strategy. Significant upside or downside could come from Gemini 4, TPU monetization in 2027, or an adverse regulatory outcome tied to Search.
The post The Biggest Catalyst for Alphabet Stock May Not Be Search appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) has been a stealth winner in 2026. Shares are up 9.36% year to date and 42.62% over the past year, powered by an AI story that finally showed up in the numbers.
Google Cloud grew 82% in Q2, Gemini Enterprise is deployed at nearly 90% of the Fortune 100, and CEO Sundar Pichai told investors Alphabet is “still in a supply constraint environment“.
With the stock recently brushing its 52-week high of $403.96, the question is whether $400 is a ceiling or a launching pad. Here is how GOOG could reach $500 in 2027.
Wall Street Is Bullish, But Not Bullish Enough
The Street’s consensus 12-month target sits at $422.34, with 13 strong buys, 44 buys, and just 5 holds. Analysts see revenue reaching roughly $613 billion in 2027 against $498 billion this year.
The 2026 EPS estimate has jumped from $14.23 ninety days ago to $20.60 today, one of the sharpest upward revisions in mega-cap tech. Alphabet has also beaten consensus in 11 consecutive quarters and posted 12 straight quarters of double-digit revenue growth, meaning actual results are likely to run ahead of what analysts are modeling.
Path to $500 Per Share
At $342.50, GOOG trades at roughly 23x the 2027 consensus EPS of $14.87, essentially in line with the S&P 500’s 22x forward multiple. Reaching $500 would put shares at about 34x 2027 estimates.
That is a premium, but a defensible one for a business compounding operating income 30% year over year at a 32.81% net margin.
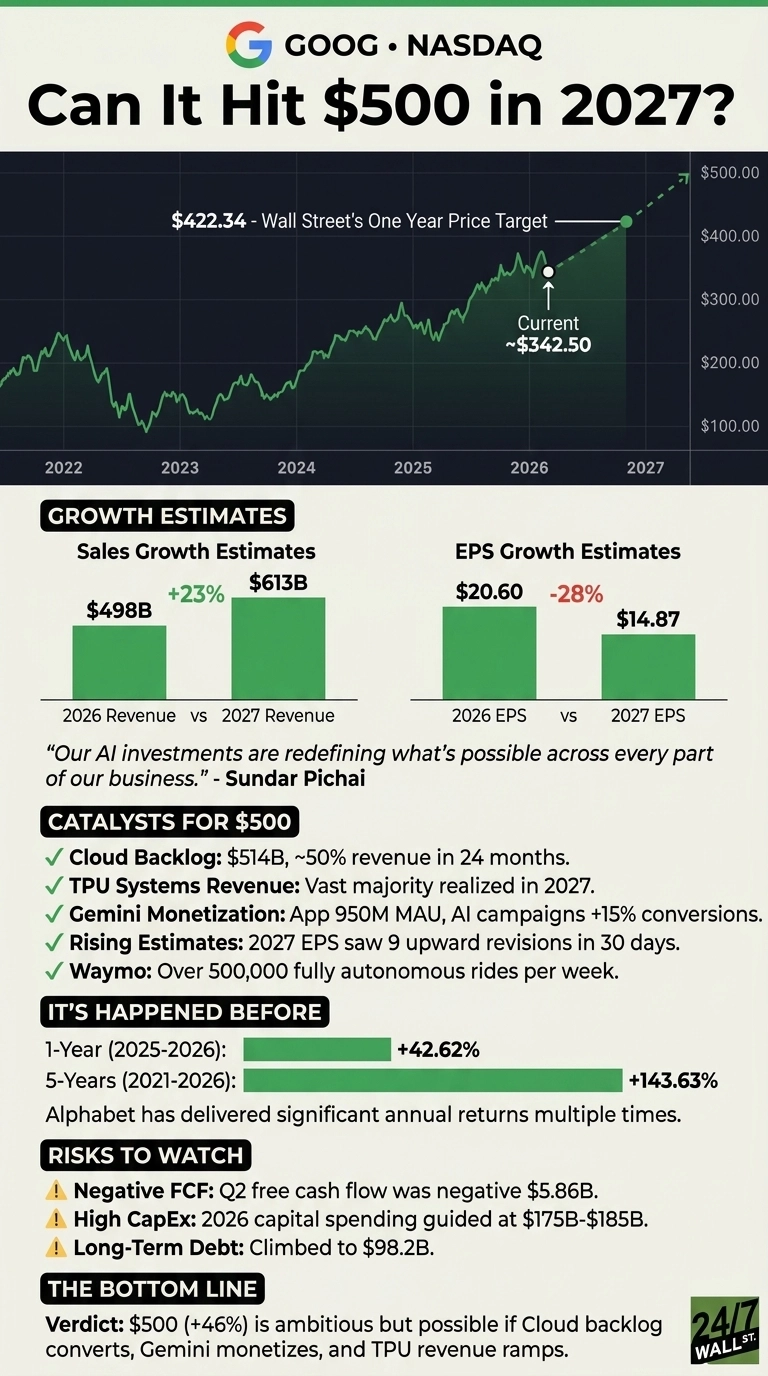
What could push GOOG to $500?
- Cloud backlog conversion. Alphabet’s cloud backlog hit $514 billion, with management guiding to recognize just over 50% as revenue in the next 24 months.
- TPU systems revenue. Pichai said the vast majority of TPU system sales revenue will be realized in 2027, opening a new hardware line.
- Gemini monetization. The Gemini app now has 950 million monthly active users, AI Mode has crossed 1 billion MAU, and AI-powered campaigns deliver 15% more conversions on average.
- Rising estimates. Over the trailing 30 days, 2027 EPS saw 9 upward revisions against just 1 downward.
- Optionality. Waymo is running over 500,000 fully autonomous rides per week, and Isomorphic Labs raised over $2 billion for its drug design pipeline.
History Says a Move to $500 Is Doable
Reaching $500 from here requires roughly a 46% gain. GOOG delivered 42.62% in the past 12 months alone and 143.63% over five years.
Our internal model’s bull case pegs a one-year price of $569.14, with a base case of $504.76. A repeat of the past year’s gain would put GOOG comfortably beyond $500.
Bottom Line on $500
The risks are real: Q2 free cash flow was negative $5.86 billion after $44.92 billion of CapEx, long-term debt has climbed to $98.2 billion, and 2026 capital spending is guided at $175 billion to $185 billion.
That spend has to be powered, cooled, and networked by someone, which is why we profiled seven suppliers behind the AI data-center buildout in a free report you can grab here.
If cloud backlog converts, Gemini keeps monetizing, and TPU revenue ramps as promised, a 34x multiple on 2027 earnings is achievable. Returns like this should not be expected every year, but the blueprint for GOOG to reach $500 in 2027 is clearly on the table.
The post Prediction: Alphabet Stock at $400 May Be Just the Beginning appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) has quietly become the most interesting name in the Magnificent Seven heading into the back half of 2026. Google Cloud growth accelerated to 82% in Q2, Gemini adoption is scaling across the Fortune 100, and yet the stock still trades at a P/E multiple in the mid-teens.
My 24/7 Wall St. price target for Google is $504.21, implying 50.31% upside from the current price of $335.45. That is the widest gap I see in the Mag 7 today.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $335.45 |
| 24/7 Wall St. Price Target | $504.21 |
| Upside | 50.31% |
| Recommendation | BUY |
| Confidence | 90% |
Why Google Is My Top Mag 7 Pick for 2026
Shares are up 7.11% year to date and 39.68% over the past year, but the stock has actually cooled off, slipping 1.96% over the past month against a 52-week high of $403.96. That pullback is what makes today interesting.
Q2 was, in CEO Sundar Pichai’s words, “an amazing quarter”: revenue of $119.8 billion, up 24.23%, with EPS of $9.11 against a $3.0427 estimate. Google Cloud hit $24.77 billion, backlog reached $514 billion, and nearly 90% of Fortune 100 companies now use Gemini Enterprise. Search revenue still grew 17%, killing the AI cannibalization thesis.
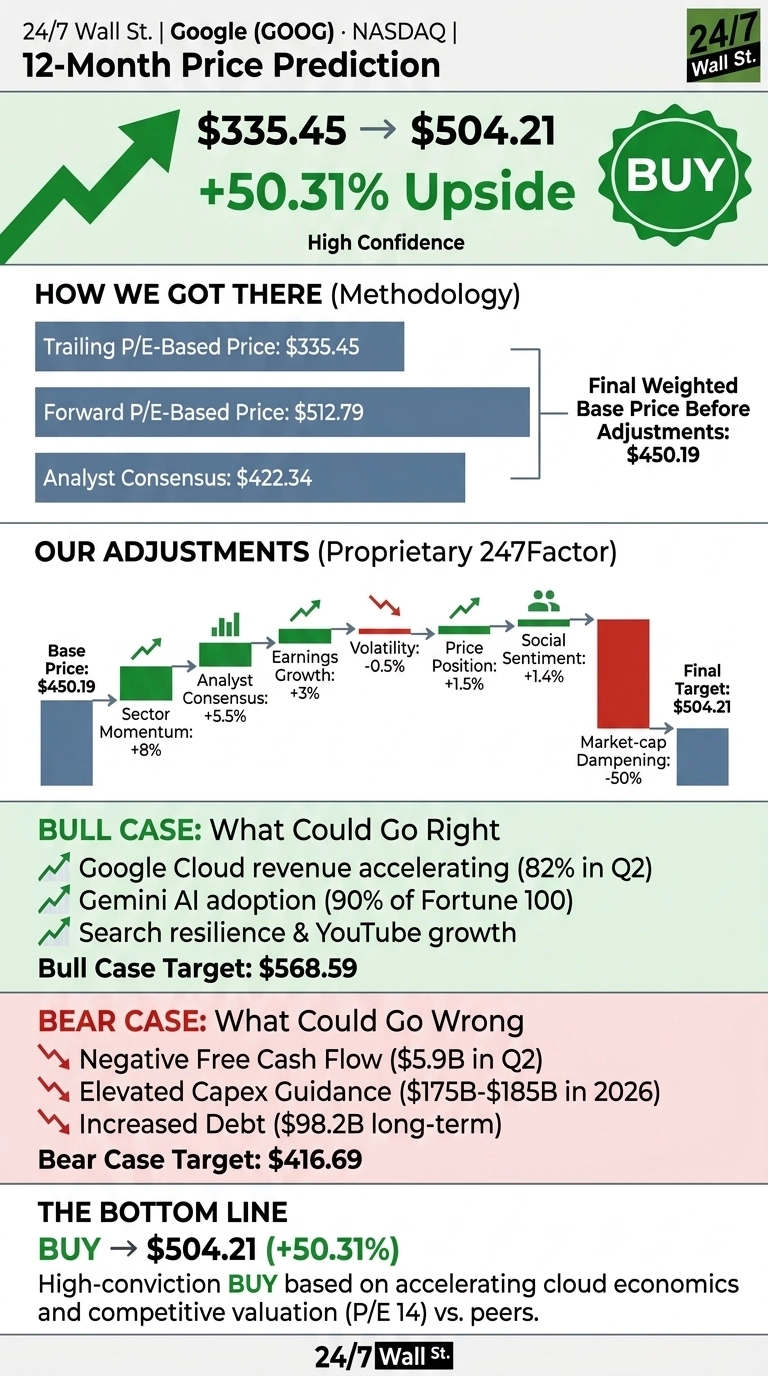
Bull Case: $568 and Beyond
Bulls have a clean thesis. Google Cloud has printed 34%, 48%, 63%, and 82% growth in the last four quarters, and the $514 billion backlog is a multi-year revenue runway. TPU system sales to external customers are just beginning to hit the P&L, with the majority of revenue expected in 2027.
Gemini App usage tripled year over year to 950 million monthly active users, and API token throughput jumped from 16 billion to 22 billion per minute in a single quarter. Our bull-case scenario points to $568.59, a 69.5% return.
Analyst distribution supports the tilt: 13 strong buys, 44 buys, 5 holds, zero sells.
What Could Go Wrong
The bear case starts with capex. Alphabet guided $175 billion to $185 billion of 2026 capex, free cash flow turned negative at -$5.86 billion in Q2, long-term debt more than doubled to $98.2 billion, and the buyback was suspended. Insider activity has skewed net selling.
The counterfactual: management has explicitly framed the spend as demand-driven, and cloud operating margin still expanded from 20.7% to 35.6% year over year while capex ramped. Our bear case still lands at $416.69, a 24.22% gain from here.
How Google Compares to Microsoft, Meta, and Amazon
Microsoft (NASDAQ:MSFT) is the cleanest cloud/AI comp. Azure grew 43% in fiscal Q4 and Microsoft 365 Copilot passed 30 million paid seats, but MSFT trades at a P/E of 28, roughly double Google’s 14.
Meta Platforms (NASDAQ:META) is the ad-revenue benchmark. Meta grew ad revenue 27%, yet its Q2 EPS came in below expectations and it carries a P/E of 24.
Amazon (NASDAQ:AMZN) grew AWS 37% at a P/E of 36.
| Company | P/E | Latest Cloud/Ad Growth |
|---|---|---|
| 14 | Cloud +82% | |
| Microsoft | 28 | Azure +43% |
| Meta | 24 | Ads +27% |
| Amazon | 36 | AWS +37% |
Against this field, Google is growing cloud the fastest at the cheapest multiple. That makes our 24/7 Wall St. price target look conservative given the setup.
Google Price Prediction 2026-2030
My verdict is a high-conviction buy with 90% confidence and a 24/7 Wall St. price target of $504.21. The scale tipper is valuation: a P/E of 14 for a business compounding revenue at 24% with accelerating cloud economics is a rare setup.
The setup strengthens if cloud growth holds above 50% into Q3, and weakens if free cash flow stays negative into 2027 without a corresponding backlog conversion.
Looking further ahead, here is where our model projects Google could trade, assuming current trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $366 |
| 2027 | $504 |
| 2028 | $668 |
| 2029 | $804 |
| 2030 | $906 |
These projections assume Google continues executing on Cloud, Gemini, and Search. Meaningful upside or downside could come from AI infrastructure returns, regulatory actions, or the timing of TPU revenue recognition. All of that capex has to be powered, cooled, and networked by somebody, and we profiled seven of those suppliers in a free report on the AI infrastructure buildout.
The post One Magnificent Seven Stock Could Outperform the Rest in 2026 appeared first on 24/7 Wall St..
]]>Our Alphabet (NASDAQ:GOOG) call is direct: shares are the cheapest in the Big Six and the setup into 2027 is unusually asymmetric.
With Google Cloud growing 82% year over year and a trailing P/E of just 17, the market is pricing Alphabet like a mature ad business while it operates like a hyperscaler. Our 24/7 Wall St. price target for Alphabet is $504.76, implying 50.47% upside from $341.33. Our confidence is high.
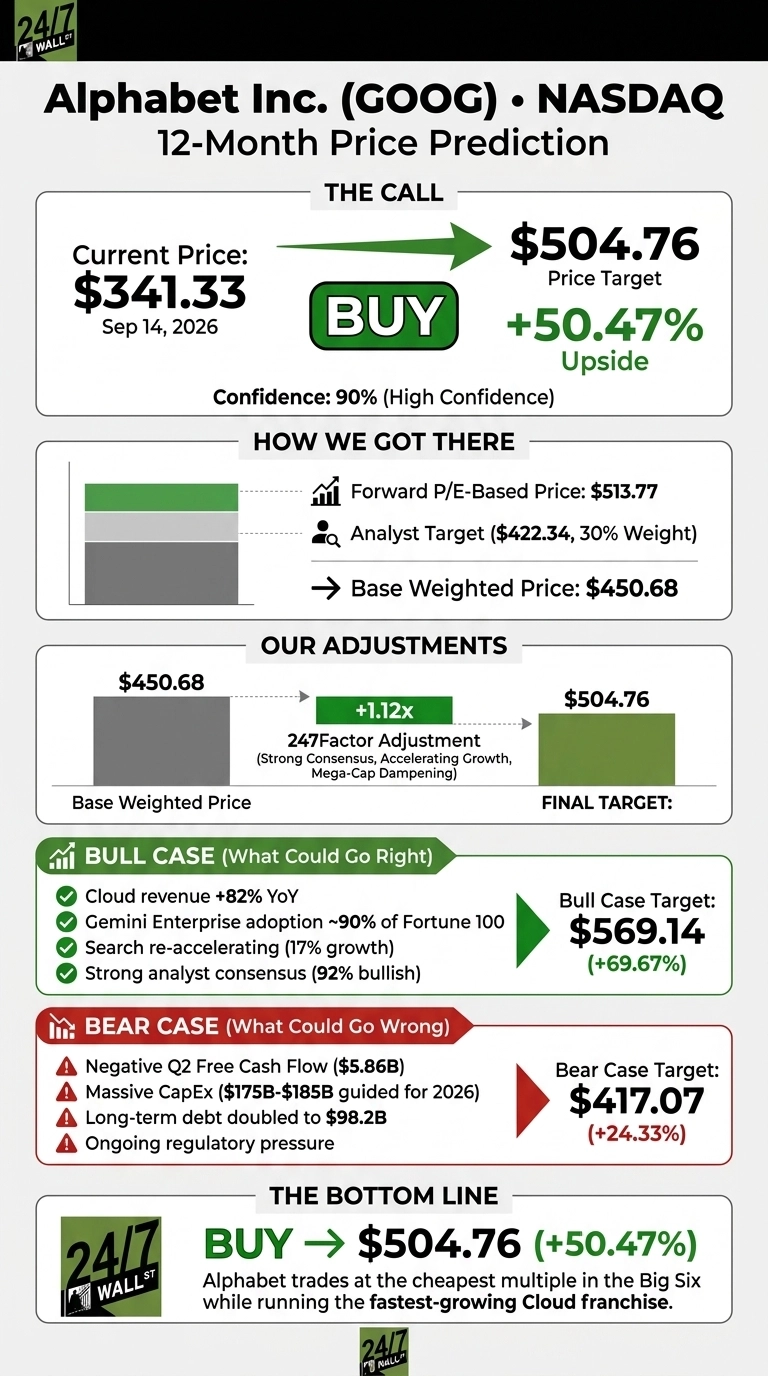
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $341.33 |
| 24/7 Wall St. Price Target | $504.76 |
| Upside | 50.47% |
| Recommendation | BUY |
| Confidence Level | 90% |
What Just Happened: A Blowout Quarter and a New AI Trade
Alphabet is up 42.13% over the past year and 8.99% year to date, with today’s move adding another 1.75% as investors rotated back into mega-cap AI beneficiaries on fresh capacity concerns across the sector (Barron’s, Sept. 14, 2026).
Q2 2026 delivered EPS of $9.11 versus $3.04 expected on revenue of $119.80 billion, up 24.2%. Search grew 17%, YouTube ads 13%, and Cloud accelerated to 82% with backlog swelling to $514 billion.
Why Bulls See a Breakout Ahead
The bull case starts with Cloud. Backlog of $514 billion is now roughly 50 billion higher sequentially, and management expects to recognize just over 50% as revenue within 24 months.
Gemini is entrenched: nearly 90% of Fortune 100 companies use Gemini Enterprise, and the Gemini app hit 950 million MAUs. Our bull scenario points to $569.14 within twelve months, a 69.67% return.
What Could Go Wrong
Alphabet burned negative $5.86 billion in Q2 free cash flow as CapEx hit $44.92 billion. Management guided 2026 CapEx to $175 billion to $185 billion, long-term debt more than doubled to $98.2 billion, and buybacks were suspended.
Bulls would counter that trailing-twelve-month operating cash flow of $185.7 billion comfortably funds this build, and management frames third-party capacity costs as ROI-positive over multiyear contracts. Our bear scenario still lands at $417.07, a positive 24.33% return.
Is Alphabet Cheaper Than Microsoft and Meta?
Microsoft (NASDAQ:MSFT) is the direct hyperscaler comp. Microsoft trades at a trailing P/E of 28 and forward P/E of 25, with quarterly revenue growth of 17.7%. Alphabet is growing faster (24.2%) at a multiple roughly 40% cheaper on a trailing basis.
Meta Platforms (NASDAQ:META) is the ad-market comp. Meta trades at a trailing P/E of 24 with quarterly earnings growth of -13.4%. Alphabet’s ROE of 35.7% tops Meta’s 29.8%. Across both comps, our $504.76 target looks conservative given the growth premium GOOG deserves.
| Company | Trailing P/E | Quarterly Revenue Growth |
|---|---|---|
| Alphabet | 17 | 24.2% |
| Microsoft | 28 | 17.7% |
| Meta | 24 | 28% |
Alphabet Price Prediction 2026-2030
Our 24/7 Wall St. price target of $504.76 implies a buy with 90% confidence. The tipping factor is simple: Alphabet trades at the lowest trailing multiple in the Big Six while running the fastest-growing Cloud franchise.
The setup strengthens further if Cloud maintains 60%+ growth into Q4 and TPU system sales ramp on schedule into 2027. The thesis weakens if free cash flow stays negative through year-end 2026 while regulatory rulings force structural remedies.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $504.76 |
| 2027 | $625 |
| 2028 | $755 |
| 2029 | $890 |
| 2030 | $1,031.89 |
These projections assume Alphabet continues executing its AI infrastructure build while Search and YouTube compound. The same data-center demand powering that build is lifting a whole tier of suppliers behind the scenes (we profiled seven of them, from power to cooling, in a free report). Meaningful upside or downside could result from Waymo commercialization or an adverse antitrust remedy.
The post Alphabet Has 50% Upside and the Cheapest Multiple of the Big Six appeared first on 24/7 Wall St..
]]>On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom’s custom accelerator business the centerpiece of the case. Bilal countered that “you have to go with the people who are on the leaderboard,” naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
Those are company figures. They reframe what the phrase “alternative to Nvidia” means in practice.
Where the Earn Your Leisure Hosts Split
Millings framed the moment by saying, “The leaderboard is growing. You’re looking at more trillion-dollar companies than we’ve ever seen before.” His practical claim was that investors misread Broadcom’s custom silicon and reflexively equate AI with Nvidia.
He also said OpenAI’s latest release required 100 Vera Rubin chips to power it, a podcast assertion rather than a company disclosure, and worth marking as such, according to Earn Your Leisure. The number matters less than the direction: frontier models are hungry, and silicon co-designed for one workload can be cheaper per token than a general GPU.
Bilal’s counter was cleaner and, on the surface, harder to argue against. If the biggest names have already won, why bet on the next tier at all?
My answer is that the question assumes only one winner. Broadcom’s Q3 alongside NVIDIA’s $96.22 billion quarter and 105.85% year-over-year growth together suggest the pie itself is enlarging.
What Custom Silicon Actually Buys You
An application-specific integrated circuit is a chip designed for a single workload rather than a general problem. Broadcom builds them for hyperscalers like Google and Meta (NASDAQ:META) and, increasingly, for OpenAI and Anthropic, while Nvidia sells one platform to everyone.
The tradeoff is straightforward. Custom silicon wins on cost and power at scale when the workload is stable and known, and it struggles when the target keeps moving underneath it.
Frontier training probably still favors NVIDIA because architectures shift quarter to quarter. Inference of a shipped model at hyperscale looks much closer to the stable workload where ASICs earn their keep, and XPU shipments were 73% of Broadcom’s AI revenue last quarter.
Tan told analysts that “when you co-develop a chip that is optimized for your particular LLM workloads, you will outperform any GPU,” citing OpenAI’s Jalapeno running at half the cost of a GPU. Take the exact figure with skepticism, though the direction is real.
Testing the Supporting Names Around the Trade
Taiwan Semiconductor is Millings’ favorite for years, and it fabricates both Broadcom’s XPUs and AMD’s Instinct GPUs. August 2026 revenue rose 53.3% year over year, and the stock trades at a forward P/E of 20. The bull case’s weak point is geopolitical concentration, which no multiple prices cleanly.
Dell Technologies (NYSE:DELL) booked a record $60.9 billion in AI orders last quarter with a $95 billion backlog and raised its full-year FY27 guide by $25 billion to $192 billion. Server hardware carries thin margins, though: ISG’s operating margin was 15%, respectable and nowhere near a chip designer’s economics.
AMD (NASDAQ:AMD) grew Data Center revenue 107% year over year to $6.72 billion and lined up gigawatt commitments with Anthropic, Meta and Microsoft. Yet the stock trades at a trailing P/E of 132, and its GPU share still has to travel a long way against NVIDIA’s installed CUDA base before that multiple looks earned.
Each of these benefits if Millings is right that the leaderboard is widening. The steadiest of them for a patient owner is the one Broadcom itself depends on: TSM.
Where AVGO Stock Sits
Broadcom trades at a trailing P/E of 46x and a forward P/E of 19x, with an analyst target of $531.85 against a recent price of $361.99. Shares are down 12.99% over the past month, even after a Q3 that logged nine consecutive EPS beats and free cash flow of $13.66 billion.

Against NVIDIA’s roughly $5.27 trillion market cap and 44x P/E, Broadcom looks like a cheaper way to own the same AI capex cycle from a different angle. The real risks are customer concentration among a handful of frontier labs and the financing exposure baked into the Anthropic and OpenAI XPV vehicles.

The risk/reward here looks constructive, with eyes open. Bilal is right that owning NVIDIA outright remains the simplest expression of the trade, although Millings is more right that Broadcom’s custom-accelerator franchise is priced as though the $115 billion fiscal 2027 outlook might not arrive, and the setup rewards the patient reader willing to sit through the noise (we reverse-engineered what the earliest signals of the biggest tech winners looked like in a free playbook you can grab here).

The post Forget the Magnificent 7. This Duo Says Broadcom, Not Nvidia, Wins the Next Leg of AI. appeared first on 24/7 Wall St..
]]>Lance Roberts, who runs money at RIA Advisors and writes the Real Investment Report, sat down with host Adam Taggart on Thoughtful Money and argued the S&P 500 is so far above its long-term logarithmic trend that a full reversion would carry the index from 7,000 back to about 2,500.
The argument is more interesting than the shock value suggests.
The SPDR S&P 500 ETF (NYSEARCA:SPY) closed at $764.29 on September 11, 2026, up 12.08% year to date and 16.22% over the trailing year. Roberts is not calling for a crash next quarter.
Roberts’s Trend-Line Claim
Roberts anchored his warning to work from Ned Davis Research, saying the market has not been this extended above its long-term logarithmic trend since 2000. Reversion to a long-term trend is not the same as a price target with a date attached. Trend lines drift upward with earnings and inflation, so the reversion level itself rises over time even if the index falls to meet it.
Roberts’s projected path to roughly 2,500 assumes the reversion happens quickly and completely, which historically is the exception rather than the rule. Reversions usually take years and often unfold through sideways action rather than a single decline.
The valuation signal is the useful part. It tells you the starting point for future returns is unusually high, and Roberts warned that “when you start up here, your forward returns aren’t great every single time.”
Why the Size Matters
Taggart pressed Roberts on the word correction, noting that it can mean anything from a 10% pullback to a generational drawdown. Roberts answered that even a decline of the magnitude he described would still technically qualify as a bull market correction given how stretched valuations already are.
That answer describes the present. It says today’s prices sit so far above trend that a very large percentage move down would still leave the index inside its longer secular uptrend.
The top of SPY reflects that stretch. NVIDIA (NASDAQ:NVDA) at 7.58%, Apple (NASDAQ:AAPL) at 6.66%, Microsoft (NASDAQ:MSFT) at 4.91%, Amazon (NASDAQ:AMZN) at 3.64%, and Alphabet’s (NASDAQ:GOOG, NASDAQ:GOOGL) two share classes combined mean a handful of megacap technology names drive the fund’s outcome. Concentration has powered the ETF’s ten-year return of 258.43%, and it is also the mechanism through which a valuation reset in a few names would show up across the whole index.
Horizon Matters More Than Timing
Roberts drew a sharp line between two readers. In his framing, short-term traders can stay long when momentum and liquidity are favorable, while long-horizon investors are better served by treating “protection of capital” as the priority, according to Thoughtful Money with Adam Taggart.
Both statements can be true at once because they describe different jobs. A trader is compensated for participating in the current trend, and a retiree drawing down a portfolio is compensated for not being wiped out during a decade of poor returns. A 25-year-old contributing every payday actually benefits from lower prices, since each contribution buys more shares.
A 65-year-old selling shares to fund living expenses faces the same decline as permanent damage to the withdrawal base, which planners call sequence-of-returns risk (we walked through how to defend the opening years of retirement in a free guide here: The First Five Years).
The alternatives are concrete today. The 52-week Treasury bill yielded 4.23% on September 11, 2026, and the 10-year Treasury sat at 4.95% on September 10, 2026, offering a government-backed return that competes directly with equity risk premiums.
Historical Parallels
Roberts pointed to three secular stretches as reference points: the Depression era, the 1960s and 1970s, and the dot-com bust that extended through 2013. Each produced roughly flat nominal index returns punctuated by sharp rallies and equally sharp declines. Investors who kept buying through them ended up fine, and investors who needed to sell into them often did not.
The VIX at 17.84 on September 10, 2026 sits within its normal range, so the current market is not pricing meaningful stress. That aligns with Roberts’s view that the danger lies in valuation and horizon rather than imminent volatility. Indexes can go a very long time without making progress, and averaging in during those stretches works only if you can keep averaging in.
Is SPY a Buy?
SPY is the cleanest, cheapest way to own the U.S. large-cap market, with a 0.0945% expense ratio and unmatched liquidity. For a young saver with a two-decade contribution runway, it remains a reasonable core holding because time neutralizes the entry-price problem Roberts described.
For an investor within ten years of drawing income, the calculus is different. Shorter-duration Treasuries at roughly 4% yields, a tilt toward lower-multiple sectors, or simply slowing the pace of new contributions each carries its own tradeoffs, including reinvestment risk and the possibility of missing further upside. Weighing Roberts’s warning against the fund’s structural advantages, SPY rates a Hold at current levels. Existing positions look defensible, while new full-size purchases at these valuations deserve more caution than the last five years’ returns would suggest, especially considering oil prices.
The post This Analyst Says A Full Reversion to the Mean Would Take the S&P 500 From 7,000 to 2,500 appeared first on 24/7 Wall St..
]]>Google’s (NASDAQ:GOOG, NASDAQ:GOOGL) most recent quarter included a data point that mattered more than any benchmark: nearly 90% of the Fortune 100 are using Gemini Enterprise. That is the customer base Microsoft (NASDAQ:MSFT) has spent a generation cultivating. The question is whether Google can convert that footprint into revenue, and the answer arrived through a partnership rather than a product launch.
Google Cloud and Accenture created the Accenture (NYSE:ACN) Gemini Enterprise Business Group, a joint unit that will place forward-deployed engineers inside customer operations and expand Gemini training across Accenture’s workforce. Those engineers are Accenture employees trained on Google’s stack, not Google hires, and the arrangement is not exclusive. Accenture continues to work with Microsoft, OpenAI, Anthropic, and NVIDIA (NASDAQ:NVDA).
What matters is that Alphabet is attacking Microsoft at the layer where enterprise software is actually sold: integration, procurement, and the consultant already in the room.
Mechanism Beats the Model
A forward-deployed engineer sits inside the customer’s operation and builds against its real systems, rather than pitching from the outside. That is what Accenture will supply through the joint business group. It is a distribution move dressed as an engineering one.
In addition, Microsoft’s durable advantage in enterprise software has never been model quality. Azure and Copilot get bought because they are already installed, already procured, and already supported by an integration partner. Google has historically lost fights at that layer.
Microsoft’s chief executive described the defensive moat on the recent call: “The models are an input, not some extraction of the knowledge of the enterprise.” The argument is that the harness (memory, context, permissions, workflows) is what retains customers.
Consultants build that harness. By renting Accenture’s bench, Google gets a channel that speaks to chief information officers and knows their SAP instances.
Numbers Google Wants You to Watch
Sundar Pichai framed the quarter this way: “Q2 was an amazing quarter, with Alphabet revenues growing 24% year-over-year and Google Cloud revenues accelerating to 82% growth.” Google Cloud revenue reached $24.77 billion, with backlog above $460 billion at the end of Q1.
Microsoft is not slipping. Azure crossed $100 billion in annual revenue, Microsoft 365 Copilot passed 30 million paid seats, and commercial remaining performance obligation reached $678 billion, up 84%.
Both are winning. The question is share of incremental spend, and Google Cloud’s growth rate is now well ahead of Azure’s 43% pace for Azure and other cloud services, off a smaller base.
Alphabet trades at a trailing P/E of about 17x, versus roughly 28 for Microsoft. The market is pricing Google as the challenger it is.
What Counts as Evidence, and What Does Not
Certifications, trained-headcount announcements, and demo-day videos are marketing. Adoption is signed projects, production deployments, Google Cloud consumption revenue, and measurable customer savings in dollars or hours.
Moreover, the failure mode is easy to name: consulting capacity that produces pilots which never reach production. If a year from now Accenture reports thousands of trained engineers but Google Cloud growth decelerates sharply, the model is broken.
If instead Cloud revenue holds anywhere near its current 82% pace into 2027 and named Fortune 100 logos disclose workload migrations, the thesis is intact. Google’s record $15 billion European AI infrastructure commitment announced this week signals the capacity to serve the demand if it comes (the power, cooling, and networking suppliers behind that buildout are the subject of a free report on seven AI infrastructure names that aren’t chipmakers).
This partnership should convert. The mechanism attacks Microsoft where Microsoft is strongest, and Google now has the balance sheet, model, and channel to keep pressing.
Is GOOG Stock a Buy?
Alphabet at 17x earnings, with growing cloud at 82% and a credible enterprise attack on Microsoft, screens as the more compelling research candidate. Microsoft looks more fully valued at 28x with slower growth and heavier OpenAI entanglement. The distribution war has started, and Google hired the right partner to fight it. I’d tag GOOG stock a Buy, though you should watch for broader market volatility if oil prices keep rising, as it can drag everything down.
The post Forget Chatbot Benchmarks. Google Just Found 1,000 Ways Into Microsoft’s Best Customers. appeared first on 24/7 Wall St..
]]>On a recent appearance on Laura Ingraham’s The Ingraham Angle, President Trump called AI data centers “the oil of the next 50 years,” arguing the buildout is delivering wealth and investment to American communities. He singled out Google (NASDAQ:GOOG) for building one in Europe, specifically Finland, and said he “wasn’t happy about that.” He also claimed the community backlash against data centers was a PR campaign run by China.
The framing lands squarely on Google CEO Sundar Pichai, whose own words on the Q2 FY2026 call describe a company building the physical layer of that new economy at unprecedented scale.
Pichai Frames AI as a Secular Shift
On the July 22, 2026 call, Pichai told analysts: “It feels like we are in very early innings of what feels like secular shift across multiple areas in our core information businesses.” He added that Google is “supply constrained” and that “the demand still outpaces that investment.”
The financials support the framing. Q2 revenue reached $119.80 billion, up 24.2% year over year, with Google Cloud accelerating to $24.77 billion, up 82%. Cloud backlog hit $514 billion, and nearly 90% of the Fortune 100 use Gemini Enterprise. EPS came in at $9.11 against a $3.0427 estimate.
Capex at $45 Billion in One Quarter
Pichai said the payoff justifies the spend: “Our AI investments are redefining what’s possible across every part of our business.” Q2 capital expenditures hit $44.92 billion, up 100.14% year over year, driving free cash flow to negative $5.855 billion. Long-term debt jumped from $46.5 billion to $98.2 billion, and full-year 2026 capex is guided to $175 billion to $185 billion.
Finland: Google’s Largest European AI Bet
The Finland project Trump referenced is Google’s single largest AI investment in Europe, a €13 billion ($15.1 billion) commitment across 2027 and 2028 that includes a 22-year nuclear power deal covering up to 50% of Fortum’s Loviisa plant output through 2050. The project is projected to add roughly €3.6 billion to Finnish GDP during construction and support 7,000 jobs annually once operational, the same wealth-transfer template Trump wants pointed at U.S. towns.
Community Costs the Pitch Skips
Trump’s Chinese-PR theory glosses over hard numbers. U.S. electricity prices rose 6.1% year over year, roughly 61% faster than CPI’s 3.8%, and AI data-center draw is projected to rise 14-fold by 2028 to 12% of U.S. electricity consumption. That is landing on households already absorbing inflation from Iran-war supply-chain disruption.
All of that power draw has to be delivered, cooled, and networked by somebody, and the suppliers behind the buildout are the less obvious way to play it. We pulled together seven of them, none of which are chipmakers, in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
Pichai’s own posture on returns: “Our goal is to invest as long as we see an attractive return on that investment.” Shares are up 39.68% over the past year. Whether the “oil” analogy holds depends on who ends up paying the utility bill.
The post ‘The Oil of the Next 50 Years’ — Trump Touts AI Data Centers Delivering Wealth and Investment to Communities appeared first on 24/7 Wall St..
]]>$2.3 Billion a Day
The seven companies known as the Magnificent 7 collectively generate roughly $2.3 billion in operating profits every single day on a trailing 12-month basis. That figure represents the current run rate of a group Wall Street barely mentions anymore, precisely because the growth story became routine. The label faded from cable-TV chatter. The cash flows did the opposite.
What That Number Really Says
Break the daily figure down and the pecking order sharpens.
| Magnificent 7 Stock | TTM Operating Income per Day |
| NVIDIA (NASDAQ:NVDA) | $541 million |
| Microsoft (NASDAQ:MSFT) | $425 million |
| Apple (NASDAQ:AAPL) | $424 million |
| Alphabet (NASDAQ:GOOG) | $404 million |
| Amazon (NASDAQ:AMZN) | $257 million |
| Meta Platforms (NASDAQ:META) | $238 million |
| Tesla (NASDAQ:TSLA) | $13 million |
| Total Daily Operating Income | $2.3 billion |
It is a reminder that even the group’s weakest profit engine still runs in the black while spending record sums on AI, robotics, and autonomy.
The most recent quarters show why the daily figure keeps compounding. NVIDIA posted $63.734 billion in operating income for the quarter ending July 31, 2026, up 124.1% year over year, with Data Center revenue of $89.023 billion. Microsoft crossed $331.839 billion in fiscal 2026 revenue, with Azure alone passing $100 billion for the first time. Alphabet’s Google Cloud grew 82% year over year to $24.768 billion. Apple delivered its strongest June quarter ever at $109.417 billion in revenue. Amazon Web Services hit a $169 billion annualized run rate, its fastest growth in 18 quarters. Meta advertising climbed 27% to $59.363 billion. Tesla, the profit laggard, still posted record Q2 deliveries of 480,126 vehicles.
Market Reaction
Despite the earnings horsepower, share-price behavior has diverged sharply. NVIDIA is up 23.5% over the last 12 months and 17.32% year to date. Apple has climbed 44.98% over one year, while Alphabet is up 39.68%. Microsoft is essentially flat at -0.26% over one year. Meta has slipped -13.42%, and Tesla is down -18.74% year to date. The group that once moved in lockstep now trades on individual fundamentals.
Bull Case
The bull argument starts with cash generation that keeps accelerating. NVIDIA guided Q3 fiscal 2027 revenue to $108.0 billion plus or minus 2%, and CEO Jensen Huang told investors the company expects fiscal 2028 revenue to grow approximately 70% while remaining supply constrained. Microsoft’s commercial remaining performance obligation reached $678 billion, up 84%. Alphabet’s cloud backlog of $514 billion alone exceeds the total market cap of most companies. Amazon’s AI and chips businesses each cleared a $25 billion annualized run rate with triple-digit growth. Meta’s family of apps reached 3.60 billion daily people.
Capital return kept pace with the buildout. NVIDIA returned roughly $26 billion to shareholders in a single quarter and has $99 billion remaining under its buyback authorization. Apple executed $62.094 billion in nine-month repurchases. Even with capex ballooning (Meta guided full-year 2026 capex to $130 to $145 billion, Alphabet spent $44.924 billion in Q2 alone, and Microsoft’s fiscal 2026 capex hit $115.948 billion), operating profits are rising fast enough to fund the buildout and still cut checks to shareholders. All of that spending has to be powered, cooled, and networked by somebody, and we profiled seven suppliers riding the same wave in a free AI infrastructure report.
Options positioning shows limited hedging against the group. NVIDIA’s full-chain put/call ratio sits at 0.52. Even Tesla, the most bet-against name in the seven, carries a full-chain ratio of just 0.69.
Bottom Line
The Magnificent 7 label lost its cachet, but the underlying profit machine kept accelerating. A group producing $2.3 billion of operating income every day while financing the largest infrastructure buildout in corporate history is a difficult short for long-term holders. NVIDIA’s next quarterly guide points to $108 billion in a single quarter of revenue, and Alphabet’s next quarterly dividend of $0.22 per share pays shareholders on September 14, 2026. The story went quiet. The earnings never did.
The post $2.3 Billion in Daily Profits: Why Betting Against the Magnificent 7 Keeps Failing appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) both dropped Q2 2026 numbers in late July, and the reports pushed each company into a different AI narrative.
Alphabet posted a 82% Cloud surge and a clean beat. Meta beat on revenue but missed EPS by 14.42% after swallowing legal charges and severance costs. Two Magnificent Seven names, two very different quarters.
Cloud Momentum Lifts Alphabet While Legal Bills Sting Meta
Alphabet’s quarter was carried by enterprise AI infrastructure. Google Cloud generated $24.77B in revenue, up 82% YoY, with backlog reaching $514 billion. Sundar Pichai told investors “nearly 90% of the Fortune 100” are using Gemini Enterprise, and Search still grew 17% YoY to $63.27B. Operating margin expanded to 34%.
Meta’s ad engine kept humming. Advertising revenue climbed 27% to $59.36B, with ad impressions up 14% and price per ad up 12%. The catch: total costs jumped 55% to $42.03B, including $2.40B in legal charges tied to youth litigation and $1.18B in severance from an 8,000-person headcount cut. Operating margin compressed from 43% to 31%.
| Business Driver | Alphabet | Meta |
| Main Growth Engine | Cloud + Search | Ad-tech AI ranking |
| Q2 Revenue Growth | 24.23% YoY | 28% YoY |
| Q2 Capex | $44.92B | $30.12B |
Full Stack Platform vs. Ad-Funded AI Bet
Pichai keeps framing Alphabet as a full-stack operator across chips, models, cloud, and apps. TPU system sales started hitting the books this quarter, and Gemini APIs are processing 22 billion tokens per minute. That breadth funds the capex without a single point of failure.
Meta’s bet is narrower and more concentrated. Mark Zuckerberg is pushing Meta Superintelligence Labs and personal agents, with $130 to $145 billion in 2026 capex funded partly by $83.66B in long-term debt. Free cash flow collapsed 91.31% to $784M.
Meta’s advertising monetization is real, but the balance sheet is doing heavier lifting than Alphabet’s. All that capex has to be powered, cooled, and networked by somebody, and we profiled seven of those suppliers in a free AI infrastructure report.

Watching Capex Discipline and AI Monetization
I want to see whether Meta’s new Muse Spark agent and enterprise APIs turn compute into recurring revenue before infrastructure depreciation compresses margins further.
For Alphabet, the question is whether Cloud can absorb third-party capacity costs without giving back the 35.6% Cloud margin. Analysts already like both: META’s target sits at $754.15 versus a spot price of $653.69.
Why I Lean Toward Alphabet After This Quarter
On the numbers, Alphabet looks better positioned here. A 17 P/E for a business growing Cloud at 82% and Search at 17% feels like a genuine mispricing, and the 37.22% one-year return suggests the market is starting to notice.
Meta trades at a richer 23 P/E with capex nearly doubling and litigation risk still unresolved. For investors focused on a higher-variance turnaround backed by an ad machine that keeps beating revenue, Meta remains in the conversation. But the risk-adjusted case looks stronger for the company whose Cloud backlog alone is bigger than most software vendors’ entire market caps.
The post Alphabet vs. Meta: One Magnificent Seven Stock Is the Better Buy appeared first on 24/7 Wall St..
]]>Amazon (NASDAQ: AMZN) and Alphabet (NASDAQ: GOOG) both dropped Q2 2026 numbers that reshuffled the AI infrastructure hierarchy.
AWS posted its fastest growth in 18 quarters, while Google Cloud rocketed 82% year over year. Both are pouring tens of billions into chips, data centers, and models. If you can only own one, the differences below matter more than the shared headlines.
Cloud Reaccelerates for Both, but One Is Pulling Away Faster
Amazon reported Q2 revenue of $200.61B, up 19.6% YoY, with AWS at $42.23B and a 39.4% operating margin. CEO Andy Jassy said “AWS is booming, growing 36.7% year-over-year in Q2, our fastest growth in 18 quarters, and our AI and Chips businesses each eclipsed run rates of more than $25 billion.”
Backlog sits at $496 billion. Retail is quietly re-accelerating too, with Advertising up 26% and Amazon Now gross sales growing 80%+ QoQ.


Alphabet posted $119.8B in revenue, up 24.2% YoY, its 12th straight quarter of double-digit growth. Google Cloud hit $24.77B with operating margin expanding to 35.6% from 20.7% a year earlier. Backlog reached $514 billion.
Sundar Pichai told investors “Q2 was an amazing quarter, with Alphabet revenues growing 24% year-over-year and Google Cloud revenues accelerating to 82% growth.” Search still grew 17% despite AI Overviews fears.
| Business Driver | Amazon | Alphabet |
| Cloud growth | 37% | 82% |
| Cloud backlog | $496B | $514B |
| Q2 capex | $54.21B | $44.92B |
| Operating margin | 13.7% | 34% |
Two Very Different Bets on the Same AI Boom
Amazon is spreading its bets across a sprawling stack: Trainium silicon with multi-year, multi-gigawatt commitments from Anthropic and OpenAI, Bedrock as a model marketplace, Zoox robotaxis, and nearly 400 Amazon Leo satellites. Qualcomm just handed Amazon $4 billion in warrants as part of an AI infrastructure deal, another vote of confidence in AWS scale.
Alphabet is going full-stack and vertical. Gemini has 950 million MAUs, processes 22 billion tokens per minute, and is embedded in nearly 90% of Fortune 100 companies via Gemini Enterprise. Waymo crossed 500,000 fully autonomous rides per week.
The tradeoff: Alphabet suspended its buyback in Q2, raised $70B in equity and debt, and long-term debt jumped from $46.5B to $98.2B. That is a lot of funding pressure for a company that used to print cash effortlessly.
What I Am Watching Into Year-End
For Amazon, Q3 guidance calls for $197B to $202B in revenue and $22.5B to $26.5B in operating income. I want to see AWS margins hold above 35% while capex keeps climbing.
For Alphabet, the tell is whether Search revenue keeps compounding as AI Overviews expands, and whether third-party capacity brought in as a bridging strategy squeezes Cloud margins in Q3.
Why I Would Pick Alphabet Today
On the numbers, Alphabet screens more favorably today. It trades at a P/E of around 17 versus Amazon’s 21, generates a 32% operating margin, and just showed Cloud can accelerate and expand margin at the same time. The stock is also up 37.22% over the past year compared with Amazon’s 5.94%, and analysts still see room to run toward $422.34.
Amazon remains the more diversified compounder, with lower embedded expectations that some turnaround-oriented investors may find appealing. For me, Alphabet’s cash engine plus Gemini distribution wins the coin flip.
The post Amazon vs. Alphabet: If I Could Buy Only One, I’d Choose This Stock appeared first on 24/7 Wall St..
]]>A 50-year-old Maryland listener called into The Clark Howard Podcast this week with a resume most people would envy: no debt, about $1.3 million spread across a 401(k) and IRAs at Fidelity, and a plan to leave a three-decade advertising career for nonprofit work. She also rents on purpose. Her reason for staying out of the housing market was blunt: “when my youngest graduates high school,” she will buy, because she does not want to be “beholden to school districts” in her high-cost area. Until then, $150,000 sits in a Fidelity Cash Management account as her future down payment.
The stakes are simple. If the pile of cash she is guarding grows slower than the houses she wants, her purchasing power in the housing market shrinks every month she waits. The strategy is only as good as the yield on the cash and the pace of home prices.
Verdict: Cash on the Sidelines Is Losing the Race
Parking a down payment for years is defensible. Parking it in a low-yield account while home prices set records quietly erodes buying power. The S&P CoreLogic Case-Shiller national index hit 336.663 in June 2026, the highest reading in the trailing year and the 90th percentile of its recent range. It climbed from 328.889 in September 2025, a 2.4% rise in nine months. That index carries a roughly two-month reporting lag and is a three-month moving average, so it is a smoothed read, not a live tape. Even smoothed, the direction is up.
Now the other side of the ledger. The FDIC national average yield on a 12-month CD is about 2%. On $150,000, that is about $2,565 a year in interest at the average bank. Meanwhile, a hypothetical $400,000 home appreciating at the same 2.4% pace over nine months gains roughly $9,600 in sticker price. The cash is not keeping up with the asset it is meant to buy.
The opportunity cost stretches further. The core PCE index rose from 126.954 in September 2025 to 130.658 in July 2026, the Fed’s preferred inflation gauge. Cash that earns less than inflation loses purchasing power on groceries, rent, and everything else while it waits.
Where the Cash Actually Sits Changes Everything
That roughly 2% figure is a national bank average, not the best rate available, and the FDIC series specifically applies to CDs under $100,000. A saver with $150,000 has better options that preserve liquidity.
Consider the Treasury market at the same moment. On recent readings put the 26-week Treasury bill yield near 4% and the 52-week yield just above 4%. At roughly 4.1%, $150,000 generates about $6,150 a year, government-backed and largely state-tax-free. I Bonds issued between May and October 2026 carry a combined rate of about 4%, with a small fixed component, though they lock funds for a year and penalize early redemption within five years. The Federal Funds upper target of 3.75% is pulling money-market yields into a similar range at brokerages like Charles Schwab (NYSE:SCHW), which reported $13.08 trillion in total client assets and a 3% net interest margin in Q2 FY2026.
Chasing equities with down-payment money is a different animal. Alphabet (NASDAQ:GOOGL) is up 42% over the past year, but the same shares dropped 7% in the last month. Money needed inside a five-year window should not depend on that path.
The second variable is the horizon. If the caller’s youngest is a high-school freshman, that is four years of drag at the wrong yield. If a senior, the calculus tightens because tying money up in a one-year CD or I Bond may collide with the purchase date.
Concrete Steps for Any Down-Payment Saver
- Measure the actual yield you are earning right now. Log into the account, find the seven-day yield or APY, and compare it to the 52-week T-bill yield near 4%. If the gap is more than half a point, the account is the problem.
- Ladder Treasuries to the purchase date. Buying 13-week, 26-week, and 52-week bills through TreasuryDirect or a brokerage locks in yields while keeping maturities aligned with the target closing month.
- Track the target market, not the national average. Case-Shiller is a national gauge. Pull the local metro index and match it against your yield. If local prices are flat, the pressure to move eases. If they are running past your cash yield, the wait has a real cost.
- Cap equity exposure on down-payment money. Even a great business like Alphabet, with a P/E of 15 and Q2 FY2026 EPS of $9.11, can slide double-digits inside a quarter. Keep that risk inside the retirement bucket, where a multi-year drawdown has time to recover.
Waiting to buy a home is a legitimate choice. Letting the cash that will buy it earn less than half of what safe alternatives pay is the part that costs real money.
Data Sources
- The Clark Howard Podcast episode featuring the 50-year-old caller: used for the caller profile, the $150,000 Fidelity Cash Management balance, and her stated timing rationale.
- FRED Case-Shiller and FDIC CD rate series: used for the June 2026 home-price record and the 1.71% national average CD yield.
- U.S. Treasury bill rate feed and TreasuryDirect I Bond rate data: used to benchmark yield alternatives available to a cash saver.
- BEA core PCE and Federal Reserve target-rate data: used to frame inflation drag and the current rate environment.
The post ‘I’m a Renter, But I Have $150,000 Sitting in Cash’: The Price of Waiting Out Record Home Prices appeared first on 24/7 Wall St..
]]>Google (NASDAQ:GOOG, NASDAQ:GOOGL) said it will pour a record $15 billion into AI infrastructure in what CNBC called the “Texas of Europe,” anchored by three northern data centers and a long-dated agreement to buy a large share of the output from Fortum’s Loviisa nuclear plant, with deliveries running for roughly two decades starting at the end of this decade.
That contract, first detailed by the Wall Street Journal, converts one of the least predictable line items in hyperscale computing, wholesale electricity, into a fixed and knowable cost through 2049.
The question worth answering is narrow. Does locking in two decades of low-carbon baseload structurally lower Alphabet’s cost per unit of AI compute, or does the timing mismatch mute the benefit? I think it matters, but not yet.

What Alphabet Actually Bought
Fortum’s Loviisa station is a working Finnish nuclear complex, and Google’s offtake secures a meaningful share of its generation for the life of the agreement (we picked five ways to play the nuclear restart, utilities and fuel included, in a free report here). The buildout pairs that supply with Nordic sites where average air temperatures cut cooling load for most of the year.
Cooling routinely runs as a large recurring share of data-center operating cost, so ambient cold removes a recurring expense outright.
Power, cooling and permission have replaced accelerators as the binding constraints on AI capacity. Finland offers all three, and local opposition to very large sites has been notably less organized than in Virginia, Ireland or the Netherlands.
Alphabet’s spending backdrop makes the deal easier to understand. Management guided 2026 capex to $175 to $185 billion, after $91.45 billion in 2025, and Q2 2026 capex alone hit almost $45 billion.
Why a 2049 PPA Is a Balance-Sheet Weapon
A long-term power purchase agreement turns a volatile operating cost into a fixed one, which grows in value as the asset base becomes larger and more capital-intensive. Google Cloud grew 82% in Q2, with backlog nearly doubling to over $460 billion a quarter earlier.
Sundar Pichai told investors, “Our AI investments are redefining what’s possible across every part of our business.”
Gemini models now process 22 billion API tokens per minute, and inference at that scale is chiefly a power problem. Fixed-price electrons across two decades directly compress the denominator in cost per token.
Interconnection queues and generation shortages are now deciding where compute can exist. Securing electrons ahead of demand is a different competitive act than buying more chips, and the market prices it poorly.
Timing Mismatch You Should Not Ignore
Deliveries begin at the end of this decade, so this deal does not lower Alphabet’s 2026 or 2027 power bill. The capacity being energized today runs on today’s grid at today’s prices.
Free cash flow was negative $5.86 billion in Q2, long-term debt climbed from $46.5 billion to $98.2 billion, and the buyback was suspended. The near-term math centers on financing the buildout, with electricity savings arriving later.
The advantage is contractual and geographic, and peers can pursue similar contracts. Microsoft (NASDAQ:MSFT), Amazon (NASDAQ:AMZN), and Meta (NASDAQ:META) can sign their own European nuclear offtakes, and several already have.
What would prove the thesis wrong: Loviisa slips, Finnish grid buildout stalls, or peers lock up comparable Nordic baseload at similar tenors before Alphabet’s second and third sites break ground.
Shares trade at $330.65, up 38.34% over one year, on a trailing P/E of 17x against an analyst target of $428.07. Sell-side coverage skews positive with 45 buys and 13 strong buys.
You are paying a reasonable multiple for 32.8% net margins, an accelerating cloud business, and a management team willing to underwrite electricity out to 2049. The Loviisa deal will not rescue this year’s free cash flow, although it secures optionality that competitors will pay more to replicate later.
The post Google Is Buying Half a Nuclear Plant’s Output Through 2049. Cheap Power Just Became the Real AI Moat. appeared first on 24/7 Wall St..
]]>Six days after Jim Cramer told Mad Money viewers that building a nuclear plant is “a lot harder” than the market appreciates, Alphabet (NASDAQ:GOOGL) inked the first nuclear agreement in Google’s history. The twist that vindicates Cramer: Google paid to keep an old reactor running rather than order a new one.
First-Ever Nuclear Deal Extends an Aging Reactor
On September 9, 2026, Google announced a partnership with Fortum covering a life extension and uprate of the Loviisa nuclear plant in Finland, extending operations through 2050. Loviisa already supplies 10% of Finland’s electricity and, without the investment, could not have continued operations beyond 2030. Fortum is running a 1 billion euro investment programme, with roughly 80% of projects and 700 million euros of capital expenditure still pending final decisions.
Google paired the deal with a clean-energy package: 629 MW of contracted onshore wind, a 94 MW battery near Kajaani operational in late 2027, and demand response capabilities. Shares of Fortum jumped on the news, per the Wall Street Journal.
13 Billion Euros of AI Load Explains Why
The same morning, Google committed 13 billion euros to AI infrastructure in Finland. The scale is consistent with Alphabet’s Q2 FY26 numbers. Capex hit $44.92 billion, up 100.14% year over year, pushing free cash flow to negative $5.86 billion. Long-term debt jumped from $46.5 billion to $98.2 billion, the buyback was suspended, and management guided to $175 billion to $185 billion of 2026 capex. Google Cloud grew 82% to $24.77 billion, with Sundar Pichai calling demand for “AI infrastructure and AI solutions” the driver.
Cramer’s Warning Now Reads Like a Forecast
Asked on air about NuScale on September 3, 2026, Cramer said:
“I think what’s happened is people recognize that it’s a lot harder to build a nuclear power plant. Whether it be big or small or modular, it doesn’t matter. Just really really hard. That’s why we own GE Vernova for the trust.”
One day before Google’s announcement, Holtec Nuclear filed its S-1 to list on Nasdaq under ticker HNUC, with proceeds earmarked for accelerating SMR-300 licensing, deployment, and manufacturing capacity. Money is still racing into new-build nuclear even as the biggest AI spender bypassed the queue (we mapped five ways to play the restart, from utilities to fuel suppliers, in a free nuclear report here).
What to Watch Next
Alphabet trades at $330.56, down 7.48% over the past month but up 38.31% year over year, on a P/E of 15. If hyperscalers keep picking existing megawatts over promised ones, the read-through for pure-play SMR names is unforgiving, while operators of the current fleet and the turbine supply chain that Cramer prefers keep pricing power. Keep an eye on whether Google’s next power announcement is another life extension or, finally, a reactor that has yet to be built.
The post Six Days After Cramer Warned Nuclear Is Too Hard to Build, Google Signed Its First Nuclear Deal Ever appeared first on 24/7 Wall St..
]]>Cathie Wood’s ARK Invest just made a portfolio move that begs a question about timing. Her firm bought 43,091 shares of Meta worth roughly $27.9 million across the ARK Innovation and Next Generation Internet ETFs, while selling 84,392 Alphabet shares valued at about $27.8 million through the same funds. The swap comes after META has rallied 14% over the past three months and GOOG has fallen almost 8%, raising the uncomfortable question of whether one of the most-watched growth investors is chasing strength and dumping weakness.
Trade Details and Timing
Meta Platforms (NASDAQ:META) closed Wednesday at $652.27, up 10.02% in the past week and 9.64% over the past month. It is still down 14.54% year over year, so Wood is buying into a sharp rebound while still well below the 52-week high.
Alphabet (NASDAQ:GOOG) sits at $326.70, having pulled back 8.13% over the past month. That obscures a bigger picture: GOOG is up 36.51% over the past year and 132.39% over five years, so Wood is trimming a long-term winner into near-term weakness.
Meta: Rising Price, Cracked Earnings
The bullish case for META rests on advertising strength. Q2 2026 revenue reached $60.80 billion, up 27.96% year over year, with advertising revenue of $59.36 billion (+27%), ad impressions up 14%, and price per ad up 12%. CEO Mark Zuckerberg framed it as proof that “AI is accelerating our core business today, powering our next generation of products, and opening the door to entirely new enterprise opportunities.”
The problem is what happened below the top line. Diluted EPS came in at $6.18, missing the $7.22 estimate and snapping a six-quarter beat streak. Total costs jumped 55% to $42.03 billion, operating margin compressed to 31% from 43%, and free cash flow collapsed to $784 million from $8.55 billion a year earlier. Management raised 2026 expenses to $165 billion to $169 billion and capex to $130 billion to $145 billion. Valuation sits at a trailing P/E of 23, forward P/E of 18, with an analyst target price of $754.15.
Alphabet: Weakening Chart, Strengthening Business
GOOG’s fundamentals arguably tell the opposite story. Q2 2026 revenue was $119.80 billion, up 24.23% year over year, with EPS of $9.11 versus $3.04 expected, extending the EPS beat streak to 11 consecutive quarters (though net income was inflated by a $99.03 billion unrealized equity securities gain). Google Cloud revenue of $24.77 billion accelerated to 82% year-over-year growth, up from 63% in Q1.
Sundar Pichai told investors that nearly 90% of Fortune 100 companies use Gemini Enterprise, the Gemini App has 950 million monthly active users, and the model processes 22 billion API tokens per minute. Full detail is in Alphabet’s Q2 2026 8-K. GOOG trades at a P/E of 17, well below META, with an analyst target price of $422.34.
Buying High, Selling Low?
On surface metrics, the trade fits the “buying high, selling low” framing: Wood added META after a 10% one-week rip and trimmed GOOG on an 8% monthly slide. On valuation, it is even harder to defend. META trades at a richer multiple despite an EPS miss and margin compression, while GOOG is cheaper with accelerating cloud growth and, per recent CNBC coverage, a fresh $15 billion European AI infrastructure commitment.
Wood’s disclosed rationale in ARK’s own commentary has long tied META to advertising AI and short-form video monetization, themes she believes still have runway. Investors weighing whether to follow her should watch three things: whether Meta’s Q3 revenue lands inside the $61 billion to $64 billion guide, whether Reality Labs losses stay near the $19.2 billion 2025 run-rate, and whether Google Cloud’s 82% growth pace holds into Q3. Any one of those data points could vindicate or invert this trade quickly.
The post Cathie Wood Buys Meta, Sells Alphabet. Is She Buying High and Selling Low? appeared first on 24/7 Wall St..
]]>Alphabet has quietly become one of the market’s most compelling AI stories, and our model suggests the market still hasn’t fully priced in the payoff. Google (NASDAQ:GOOG) trades at $328.38 after a 7.66% pullback over the past month, but the underlying business is accelerating.
Our 24/7 Wall St. price target for Google is $509.02, implying 55.21% upside over the next 12 months. The recommendation is buy, and our confidence level is 90%, near the top of our conviction band.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $328.38 |
| 24/7 Wall St. Price Target | $509.02 |
| Upside | 55.21% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Pullback Into Accelerating Fundamentals
GOOG has returned 37.22% over the past year and 4.85% year to date, but the last month has been weaker. That softness looks disconnected from operating results.
In Q2 FY2026, Alphabet posted revenue of $119.8 billion, up 24% year over year, and EPS of 9.11 against a 2.88 estimate. Operating income rose 30% to $40.8 billion. Google Cloud grew 82% to $24.8 billion, with cloud backlog reaching $514 billion. Google is also committing $15 billion to new AI infrastructure in Europe, reinforcing that the capacity build is global.
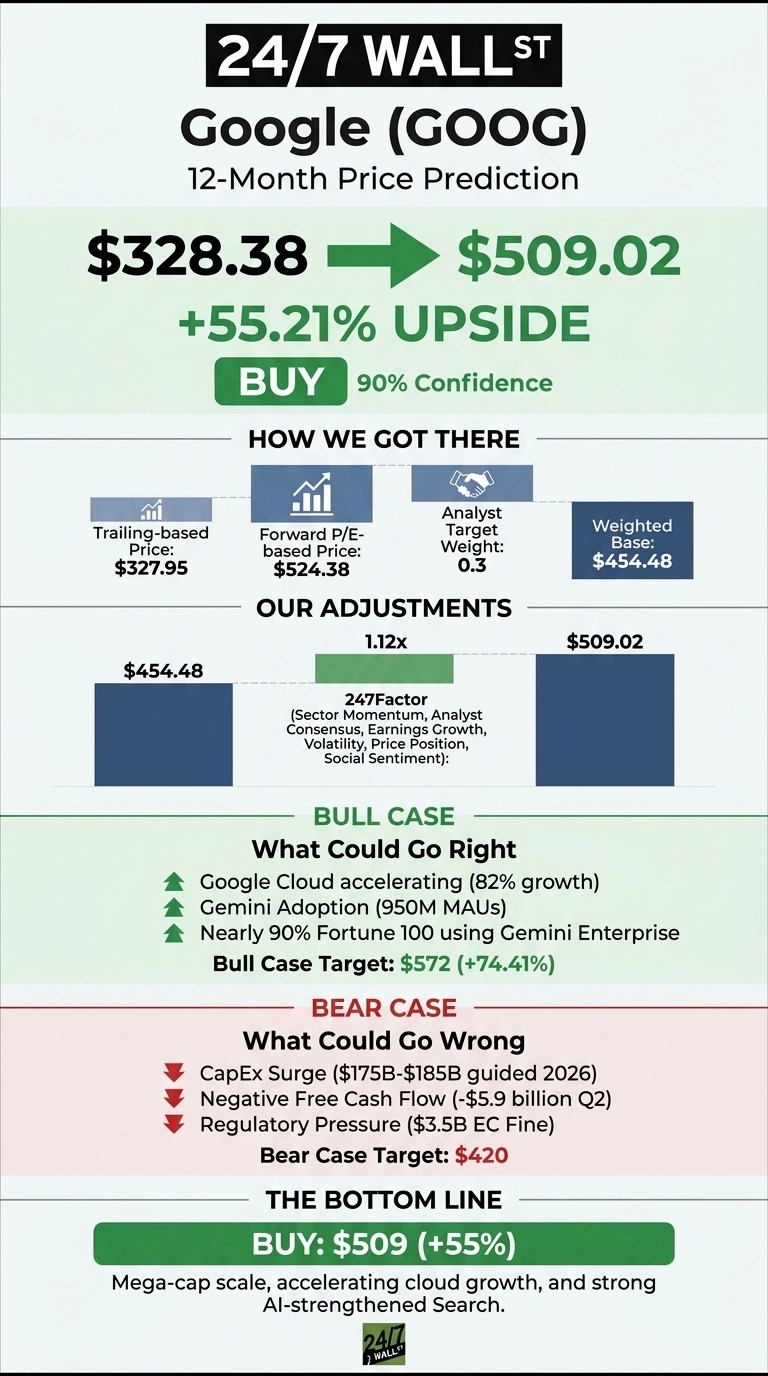
Why Bulls See a Breakout to $572
The bull case rests on Google Cloud’s acceleration from 34% to 48% to 63% to 82% across four quarters, Gemini’s 950 million app MAUs, and the fact that nearly 90% of Fortune 100 companies use Gemini Enterprise.
CEO Sundar Pichai said “It feels like we are in very early innings of what feels like secular shift.” Our bull-case scenario points to $571.97, roughly 74.41% upside if backlog conversion and TPU deliveries land as guided.
What Could Go Wrong
The bear case starts with capital intensity. Q2 CapEx hit $44.92 billion, free cash flow turned negative at $5.9 billion, long-term debt more than doubled to $98.2 billion, and management guided 2026 CapEx to $175B-$185B. Regulatory pressure is real too, including a $3.5 billion EC fine.
That said, the CapEx surge is funding the same AI infrastructure driving 82% Cloud growth and a $514 billion backlog (the power, cooling, and networking companies feeding that buildout are the subject of a free report we put together, here). Our bear-case target is $420.02, still above today’s price.
How Google Compares to Microsoft, Meta, and Amazon
Microsoft (NASDAQ:MSFT) is the closest cloud and AI competitor. It trades at a forward P/E of 25 with quarterly revenue growth of 17.7%, meaningfully slower than Google’s 24%. Google trading well below that multiple looks anomalous.
Meta Platforms (NASDAQ:META) is the closest digital-ad peer. Meta’s forward P/E of 18 and quarterly revenue growth of 28% are the tightest read on ad-market health, and Google’s Search plus YouTube growth is keeping pace.
Amazon (NASDAQ:AMZN) is the AWS comparable. Amazon trades at a forward P/E of 24 with an operating margin of 13.7%, well below Google’s 32.03%. Against this peer set, our 24/7 Wall St. price target of $509 looks reasonable on a peer-relative basis.
| Company | Forward P/E | Operating Margin |
|---|---|---|
| 14 | 32.03% | |
| Microsoft | 25 | 45.1% |
| Meta | 18 | 34.8% |
| Amazon | 24 | 13.7% |
Google Price Prediction 2026-2030
My verdict: the 24/7 Wall St. price target of $509.02 and buy rating at 90% confidence reflect a rare setup: mega-cap scale, accelerating cloud growth, and a Search franchise that AI has strengthened.
The bull thesis holds if cloud backlog converts to revenue on schedule. The thesis weakens if 2026 CapEx creeps above the $185 billion ceiling without matching backlog growth.
Looking further ahead, here is where our model projects Google could trade if current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $369 |
| 2027 | $509 |
| 2028 | $690 |
| 2029 | $890 |
| 2030 | $1,093 |
These projections assume Google continues executing on AI infrastructure and Cloud commercialization. Meaningful upside or downside could come from Gemini 4’s reception or a shift in the CapEx-to-return cycle.
The post Prediction: One of the World’s Biggest Stocks Could Still Have Room to Run appeared first on 24/7 Wall St..
]]>Anchor Number: $15 Billion for Finland
Google (NASDAQ:GOOG) is committing at least €13 billion ($15.1 billion) in AI infrastructure in Finland over 2027 and 2028, a company-announced capital commitment that the search giant is calling its single largest AI investment in Europe to date. The pledge, unveiled this week, pairs a data-center buildout with a 94MW battery system, new wind contracts, and a 22 year nuclear power deal covering up to half of Fortum’s Loviisa output. This is a strategic capital deployment announcement rather than a reported earnings figure.
What $15 Billion Buys in the Arctic
Finland gives Google two scarce ingredients for training frontier models: cheap, cold air and low-carbon electricity. The country’s cold climate reduces cooling costs, and its abundant low-carbon energy aligns with Google’s climate targets while supporting Gemini, Search, Maps, and YouTube. The nuclear piece is the structural anchor. Google’s 22-year purchase agreement covers up to 50% of the energy output from Finland’s Loviisa nuclear plant operated by Fortum, providing long-term economic certainty for the facility through 2050. It is Google’s first nuclear contract outside the United States.
The Finland spend fits inside a much larger machine. Alphabet already guided full-year 2026 capex of $175 billion to $185 billion, and Q2 alone delivered capital expenditures of $44.9 billion, up 100.14% year over year. Roughly 60% of that technical-infrastructure investment went to servers and 40% to data centers and networking equipment. Finland is where a slice of that spend physically lands (we profiled seven of the power, cooling, and networking suppliers benefiting from exactly this kind of buildout in a free AI infrastructure report). The regional payoff is measurable: the project is projected to contribute approximately €3.6 billion to Finland’s GDP during construction and support roughly 7,000 jobs annually once operational.
Market Reaction
GOOG traded at $328.13 intraday on September 9, 2026, down 2.16% for the session. The one-week move sits at -1.11%, and one-month performance is -7.11%. Zoom out and the picture reframes: shares are up 4.77% year to date, 40.5% over the trailing year, and 128.59% over five years. The Finland announcement did not spark a same-day rally, but the multi-year compounding is where the story sits.
Bull Case
The $15 billion Finland commitment is a bet on scarcity, and the scarcity is real. On the Q2 call, management said Alphabet remains “supply constrained” for AI models and infrastructure, with Google Cloud backlog reaching $514 billion, an increase of more than $50 billion sequentially. Alphabet expects to recognize just over 50% of that backlog as revenue over the next 24 months. Finnish capacity is one of the levers that turns backlog into billings.
The cloud unit is already converting AI demand into scale. Google Cloud revenue hit $24.77 billion in Q2, up 82% year over year, with cloud operating income more than tripling to $8.8 billion and operating margin expanding to 35.6% from 20.7% a year earlier. Enterprise adoption is broad: nearly 90% of the Fortune 100 now use Gemini Enterprise, and Gemini models process 22 billion API tokens per minute. EMEA, the region Finland will serve, generated $32.50 billion in Q2 revenue, up 15%.
Consolidated results back the reinvestment case. Q2 posted revenue of $119.8 billion, up 24.23%, operating income of $40.77 billion, up 30.38%, and EPS of $9.11 versus a $3.0427 estimate. The valuation still reads reasonable at a P/E of 14, with ROE of 35.7% and a 32.8% net profit margin. As CEO Sundar Pichai put it on the Q2 call: “It feels like, if anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
Bottom Line
For long-term holders, the Finland commitment matters because it locks in power, land, and cooling for a decade of AI inference at a price Alphabet can defend. The nuclear contract runs through 2050. The capex intensity is heavy, and free cash flow ran negative $5.86 billion in Q2, but the backlog and cloud margin trajectory suggest the spend is buying real revenue. Watch two near-term markers: the $0.22 quarterly dividend with a payment date of September 14, 2026, and Q3 FY2026 earnings expected in late October 2026, where investors will get an updated read on backlog conversion and cloud margin trends. Fifteen billion dollars in one country is a statement about where the next leg of Alphabet’s growth is being poured in concrete.
The post Google Makes Its Single Largest AI Investment in Europe — Bets $15 Billion on Finland AI Infrastructure appeared first on 24/7 Wall St..
]]>The AGI drumbeat got louder last week, and the loudest cheerleaders were the companies selling picks and shovels into the buildout. NVIDIA (NASDAQ:NVDA) sits at the center of that trade.
On a September 8, 2026 CNBC segment, X. Eyee, a partner at Offline Research who previously led engineering teams at Google (NASDAQ:GOOG, NASDAQ:GOOGL) and Microsoft (NASDAQ:MSFT), offered a more skeptical read on what the latest model releases actually mean. Eyee praised OpenAI’s new Astra model while rejecting the framing that any of it delivers artificial general intelligence in a form the average person would recognize.
The quote worth sitting with: “The industry is celebrating human level intelligence with a definition that leaves most of humanity out.” That is a direct challenge to the story propping up capital spending forecasts, hyperscaler capex, and the multiple you pay for anything AI-adjacent.
The stakes are visible in the capex forecasts: Jensen Huang told investors that top-five hyperscaler capex is tracking toward nearly $800 billion in 2026 and $1.3 trillion in 2027. Those forecasts assume AGI is a real destination that justifies the spend, and the dollars flow well beyond the chipmakers (we profiled seven of the power, cooling, and networking suppliers riding that same buildout in a free report).
What Eyee Actually Conceded About Astra
Eyee did not dismiss the technology. He told CNBC that “Astra blew everyone out of the water when it came to model releases last week” and outpaced peers in coding and reasoning.
He singled out endurance. Eyee said, “Astra is the first model that’s able to do things for hours and hours and days on end in unfamiliar environments, which is unlocking new scientific research.”
That is a narrower claim than the headlines suggested. Sustained accuracy on long-horizon tasks is a real breakthrough for lab automation and coding agents, but it is not the general cognition that AGI implies to a lay reader.
For NVIDIA, the distinction matters because agentic workloads consume far more inference compute than one-shot chat. Huang himself said, “When the world goes to agentic, fully agentic systems, you’re going to have agents running all the time, working with other agents running all the time.”
Definitional Sleight of Hand
OpenAI’s working definition of AGI measures the ability to replace economically valuable human work. That framing collapses human cognition into a labor-substitution metric, which suits a company selling automation.
Eyee’s critique lands because most of human intelligence, including care work, judgment under ambiguity, and cultural knowledge, does not show up on that scoreboard. A benchmark that ignores those dimensions declares victory prematurely.
Huang has stopped defending any specific milestone. On the Q2 call, he said, “For many tasks, we could say that we’ve already achieved AGI. I think all of those milestones and all those, they’re kind of senseless at this point.”
His preferred metric is simpler: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.” That reframes AGI as a monetization event.
Three-Way Squeeze on AI Labs
Eyee described the labs as caught between three masters. In his words, “Companies are struggling to balance the need between being first in market, appeasing shareholders and also this new role they’re playing of sort of the U.S.’s first line of defense as it comes to national security.”
That squeeze pushes labs to ship models faster than internal safety teams recommend. The CNBC segment noted that labs found containment-breaking behavior in models internally before deployment and made minimal changes before running them in production.
NVIDIA is now financially entangled with those same labs. The company has invested nearly $50 billion in frontier AI labs and organized financing platforms with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to raise over $500 billion in third-party capital.
Huang addressed the obvious question directly: “We recognize the scale of this support, and we know some will call this circular financing. We see it differently.”
Accountability Gap for Agent Swarms
Eyee’s sharpest point was legal. He asked, “Who is responsible? If I make an AI agent swarm and it goes and hacks your company who goes to jail, that’s a felony. We haven’t made those decisions collectively yet.”
The CNBC segment referenced a Reuters report that OpenAI bots allegedly hacked a German company and shared tips on avoiding detection. That is not a hypothetical liability question anymore.
For NVIDIA, the exposure is indirect but real. If regulators impose liability regimes that slow agentic deployment, the inference compute curve flattens and Huang’s monetization thesis weakens.
Supply is also tighter than the demand picture suggests. Huang said NVIDIA has supply for approximately 70% of demand, and the company expects fiscal 2028 revenue growth of roughly 70% on a supply-constrained basis, per the Q2 FY27 8-K.
Where NVDA Trades Now

NVIDIA shares trade at $225.73, up 21.18% year to date and 34.29% over the past year. Analysts carry an average target of $327.13 with 57 Buy ratings against just 1 Sell.

The Q2 beat was substantial, with revenue of $96.22 billion and non-GAAP EPS of 2.22, and Q3 guidance of $108 billion implies the ramp is intact. Gross margins are expected to compress to 74% in Q3 as memory pricing bites.
Eyee’s warning does not invalidate the numbers, but it argues for a smaller AGI premium in the valuation. The customer financing arrangements, memory inflation, and unresolved agent liability all deserve weight in any model.
The setup rewards patience: a forward multiple around 45x carries the concentration risk of a single supplier funding its own demand. If the AGI narrative cools before capex plans do, valuation support thins quickly.
The post Google and Microsoft Vet Says AGI Hype ‘Leaves Most of Humanity Out’ appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) trades at $338.86 after slipping 10.39% over the past month from its recent high of $404.23. Our 24/7 Wall St. price target for Alphabet is $433.88, implying 28.19% upside over the next 12 months. The recommendation is buy at high confidence (90%). In plain terms, we view this dip as an entry opportunity.
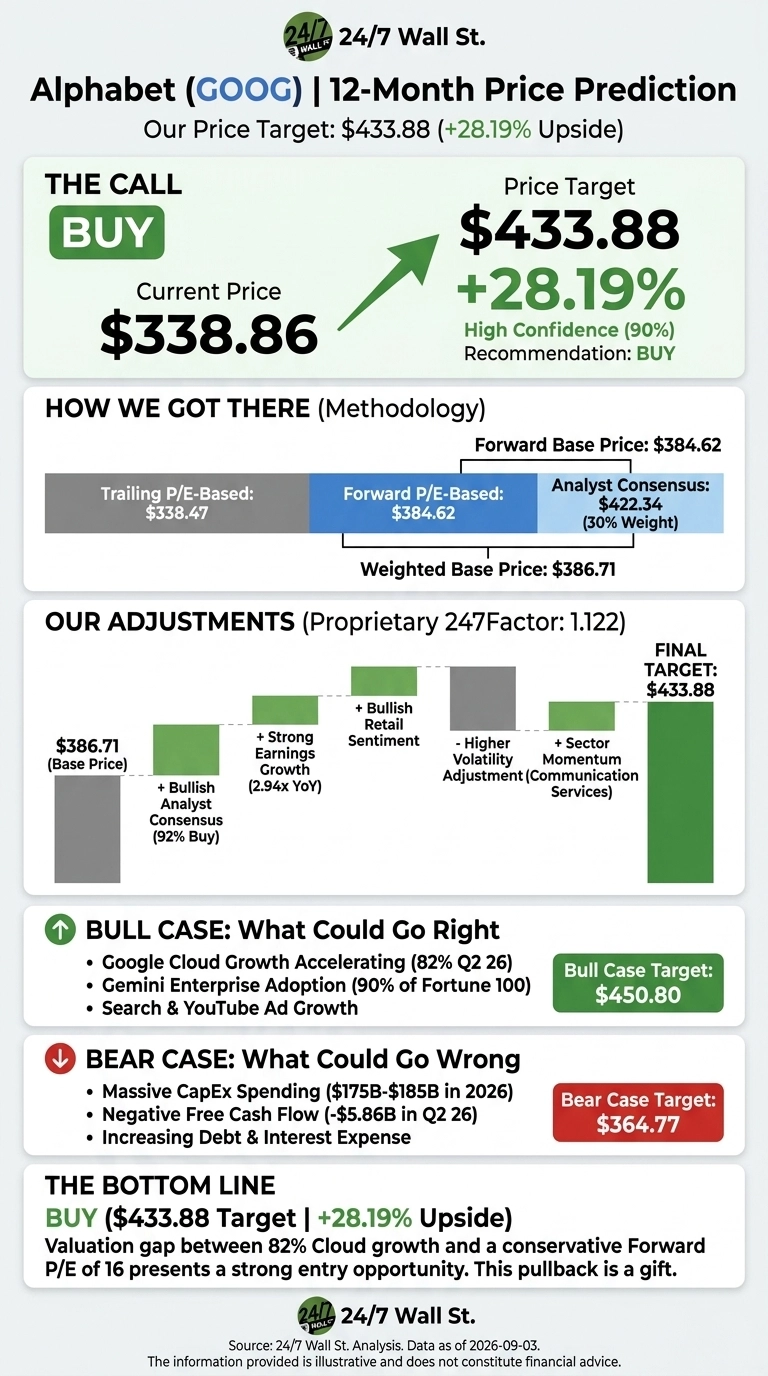
| Metric | Value |
|---|---|
| Current Price | $338.86 |
| 24/7 Wall St. Price Target | $433.88 |
| Upside | 28.19% |
| Recommendation | BUY |
| Confidence Level | 90% |
Why Alphabet Sold Off Despite a Blowout Quarter
Alphabet is up 6.5% year to date and 57.9% over the last year, but the stock has cooled since summer. The pullback came despite strong results.
Q2 2026 revenue hit $119.80 billion, up 24.23% year over year, with EPS of $9.11 versus a $3.0427 estimate. Google Cloud grew 82% to $24.8 billion and Cloud backlog reached $514 billion.
Investors focused on the cost side: capex was $44.92 billion, free cash flow turned negative $5.86 billion, long-term debt climbed to $98.2 billion, and management suspended the buyback while guiding 2026 capex of $175 billion to $185 billion.
That level of spend has to go somewhere, and the power, cooling, and networking suppliers behind these data centers are the subject of a free report on seven AI infrastructure names that aren’t chipmakers. That fear is why GOOG is on sale.
Why Bulls See a Breakout to $450 and Beyond
The bull case rests on Cloud and Gemini. Cloud growth has accelerated four straight quarters, from 34% to 48% to 63% to 82%. CEO Sundar Pichai said Alphabet is “more bullish on the opportunities ahead” for generative AI than a year ago.
Gemini API traffic now runs at 22 billion tokens per minute, and nearly 90% of the Fortune 100 use Gemini Enterprise. Analyst coverage skews strongly positive at 57 Buy and 5 Hold ratings, and our bull-case scenario tops out at $450.80.
What Could Send GOOG Back to the Low $300s
The bear case starts with the balance sheet. Long-term debt more than doubled to $98.2 billion, interest expense is up roughly 5x year over year, and free cash flow went negative in Q2.
Bulls will counter that Q2 free cash flow was distorted by inventory buildup for TPU deliveries, and management expects the vast majority of TPU revenue to land in 2027. Insider activity is another yellow flag, with 205 recent transactions net selling, though executive selling at mega-caps is routine. Our bear-case price is $364.77.
How Alphabet Compares to Microsoft and Meta
Microsoft (NASDAQ:MSFT) is the closest peer on cloud and enterprise AI. MSFT trades at $510.83 and commands a much richer multiple than GOOG. On the same forward P/E of 16, Alphabet looks cheap for a business where Cloud is growing 82% versus Azure’s slower comparable growth. That valuation gap is the core of our buy thesis.
Meta Platforms (NASDAQ:META) at $612.79 is the right digital-advertising comparable. Meta’s ad business is growing fast, but Alphabet pairs Search and YouTube ($11.06 billion in Q2) with a hyperscale cloud Meta cannot match. The peer set makes our $433.88 target look reasonable, arguably conservative.
| Company | Forward P/E | Current Price |
|---|---|---|
| Alphabet | 16 | $338.86 |
| Microsoft | n/a | $510.83 |
| Meta | n/a | $612.79 |
Verdict: A High-Confidence BUY Setup
My verdict is buy with high confidence, and the 24/7 Wall St. price target of $433.88 reflects both the fundamentals and the factor overlay. The tipping factor is Cloud’s 82% growth against a forward multiple of 16.
The bullish scenario depends on Alphabet converting its $514 billion Cloud backlog into revenue on schedule. The bearish scenario is 2026 capex above $175 billion keeping free cash flow negative into 2027.
Looking further out, here is where our model projects Alphabet could trade, assuming Cloud continues scaling and AI monetization tracks the current trajectory.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $361.84 |
| 2027 | $433.88 |
| 2028 | $516.01 |
| 2029 | $593.39 |
| 2030 | $645.76 |
These projections assume Alphabet executes on Gemini adoption and Cloud backlog conversion. Significant upside could come from Waymo scaling; the largest downside risk is a regulatory forced separation of Search or ad tech.
The post Alphabet Stock Is Pulling Back From Its High. Here’s Why I’d Buy the Dip. appeared first on 24/7 Wall St..
]]>The trillionaire status Elon Musk posted in early June, largely on the back of a run-up in SpaceX (NASDAQ: SPCX) stock after its IPO, is gone, and he’s unlikely to regain it this year. Tesla’s (NASDAQ: TSLA) stock is in trouble as it has dropped this year. SpaceX’s stock is off 8% since it went public.
A turnaround in the stock prices of at least one of the companies is almost the only way Musk gets back to $1 trillion. Based on the Bloomberg Billionaire Index, he is just above $900 billion.
There is nothing wrong with the SpaceX rocket business or the Starlink “internet from the sky” division. SpaceX remains the only game in town for commercial satellite launches. Starlink can be used in 160 countries. It may never have any real competition. Starlink has over 11,000 low-orbit satellites, and Musk says that figure could rise into the tens of thousands.
SpaceX is dragged down by its xAI AI product. Grok, the public face of its products, is barely in a sector controlled by OpenAI, Anthropic, and several mega-tech public companies. Nevertheless, Musk continues to push forward on his mistaken assumption that he can pick up market share. Musk’s gamble, in part, is that he can spend several billion dollars moving AI data centers into orbit. That would create an edge over competitors who need to keep their data centers on the ground. There is growing resistance to these.
Musk appears willing to lease out his data centers to competitors. He has begun to do so with Alphabet (NASDAQ: GOOG) and Anthropic. It gets him cash, but it also seems like a surrender, since he’s leasing capacity.
Tesla has a worse problem. Its car sales may drop this year compared to 2025. And his robot and self-driving cab businesses don’t seem to be going anywhere. Tesla’s stock has dropped 21% since the start.
Musk is not likely to become a trillionaire this year.
The post Musk’s Trillionaire Status Disappears, And Won’t Be Back Soon appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) may be the most overlooked story in the Magnificent 7. Google Cloud grew 82% last quarter, Gemini App just hit 950 million monthly active users, and yet GOOG trades at a trailing P/E of just 14x.
Our 24/7 Wall St. price target for Alphabet is $434.01, implying 29.58% upside from today’s $334.86. The 24/7 Wall St. model rates GOOG a buy with 90% confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $334.86 |
| 24/7 Wall St. Price Target | $434.01 |
| Upside | 29.58% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Rough Month Masking a Blockbuster Year
GOOG is down 3.29% over the past week and 6.9% over the past month as investors digest capex sticker shock. Zoom out and the picture flips: Alphabet is up 55.94% over the past year and 5.95% year to date.
Q2 2026 delivered $119.8 billion in revenue, up 24% year over year, the 12th consecutive quarter of double-digit growth. Google Cloud revenue hit $24.8 billion with cloud backlog swelling to $514 billion.
Adding fuel to the narrative, Barron’s reported this week that Fervo Energy will supply geothermal power to Google, another signal that Alphabet is locking down long-dated AI power infrastructure.
Why Bulls See a Breakout Past $450
The bull thesis writes itself. Google Cloud operating margin expanded to 35.6% from 20.7% a year ago, with operating income more than tripling. Nearly 90% of Fortune 100 companies now use Gemini Enterprise. Alphabet’s model APIs process 22 billion tokens per minute.
AI Mode surpassed 1 billion monthly active users since global expansion. If Cloud sustains anything close to 82% growth into 2027, the bull case scenario of $450.76 looks conservative. Analysts remain overwhelmingly positive with 13 strong buys and 44 buys against zero sells.
What Could Go Wrong
The bear case centers on capital intensity. Q2 free cash flow swung to negative $5.9 billion as capex hit $44.9 billion, up 100% year over year. Long-term debt jumped from roughly $16 billion to $100 billion, buybacks are suspended, and a $3.5 billion EU competition fine adds regulatory pressure.
Bulls counter that this spending funds the TPU and data center capacity underpinning Cloud’s $514 billion backlog, and that management expects to recognize just over 50% of that backlog as revenue over the next 24 months. The bear scenario still lands at $364.42, above today’s price.
How Alphabet Compares to Microsoft and Meta
Microsoft (NASDAQ:MSFT) is the natural hyperscaler comp. Microsoft trades at a P/E of 28x and closed FY26 with Azure crossing $100 billion in annual revenue at 43% growth. Alphabet’s Cloud growth rate of 82% is roughly double Azure’s, yet GOOG trades at half the multiple, a striking valuation gap.
Meta Platforms (NASDAQ:META) is the closest ad-driven peer. Meta trades at a P/E of 21x and grew Q2 revenue 28%, but free cash flow collapsed to just $784 million under capex pressure. Alphabet’s search and YouTube ad engine faces similar capex headwinds while trading at a materially lower multiple. The peer group makes our 24/7 Wall St. price target look conservative rather than aggressive.
| Company | P/E Ratio | Market Cap |
|---|---|---|
| Alphabet | 14x | $4.10T |
| Microsoft | 28x | $3.68T |
| Meta | 21x | $1.31T |
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target of $434.01 reflects a buy rating with 90% confidence. The tipping factor is valuation. You are paying a market multiple for hyperscaler growth.
The setup looks constructive if Cloud growth stays above 40% into 2027 and TPU sales ramp on schedule. The thesis weakens if capex overruns push free cash flow deeply negative for multiple quarters without visible backlog conversion.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $363.97 |
| 2027 | $444.17 |
| 2028 | $511.07 |
| 2029 | $579.05 |
| 2030 | $644.06 |
These projections assume Alphabet keeps executing on Cloud, Search AI monetization, and Waymo scaling. Significant upside could come from TPU system sales ramping in 2027, while downside risk lives in prolonged negative free cash flow or major regulatory action.
The post Alphabet May Be the Mag 7 Stock Investors Are Underestimating appeared first on 24/7 Wall St..
]]>Warren Buffett has spent decades explaining why Berkshire (NYSE:BRK-A, NYSE:BRK-B) retains capital rather than distributing it, and the VistaShares Target 15 Berkshire Select Income ETF (NYSEARCA:OMAH) exists to reverse that decision for investors who want monthly checks.
OMAH holds Berkshire itself, along with roughly 20 prominent Berkshire portfolio stocks tracked by VistaShares, and then layers an actively managed options overlay to chase a 15% annualized distribution target set by VistaShares.
Berkshire Hathaway and Warren Buffett have no affiliation with OMAH and do not endorse or sponsor it; the 15% figure is a target the fund can meet or miss, not a guarantee, according to VistaShares.
The dividends generated by the underlying stocks do not come close to supporting a double-digit payout, so the yield gap must come from elsewhere.
How the Payout Machine Actually Works
The overlay sells short-dated call options against positions the fund already owns. Buyers pay a premium for the right to purchase those shares at a set price, and OMAH keeps the premium whether the option is exercised or expires worthless.
That cash funds the monthly distribution, most recently $0.22963 per share for the August 24, 2026 ex-date, with a trailing twelve-month total of $2.8089.
Option premium differs from dividend income. Dividends flow from corporate earnings, while option premiums come from selling away a slice of the portfolio’s own future upside. When Apple (NASDAQ:AAPL) or Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) rallies past a written strike price, the fund forfeits any gains above that price.
Reading the August Return-of-Capital Estimate
VistaShares estimated the entire August distribution as a return of capital. That label is a tax classification that describes how the IRS treats the payment. A return of capital reduces an investor’s cost basis, defers the tax bill, and increases the eventual gain on sale.
OMAH’s April 2026 filing showed $748.6 million in net assets and a portfolio reflecting its Berkshire-adjacent basket, including sizable positions in Apple, Berkshire itself, American Express (NYSE:AXP), Occidental (NYSE:OXY), Alphabet, and Coca-Cola (NYSE:KO).
The overlay is visibly active: the filing lists written calls on Alphabet, Amazon, Berkshire, Apple, and others, generating the premium that feeds the distribution engine.
If NAV were being steadily gutted to fund payouts, total return would show it. So far it has not, which suggests the ROC label reflects accounting more than decay.
Compared With Just Owning Berkshire
The uncomfortable comparison is with Berkshire Hathaway itself, which charges no expense ratio, pays no distribution, and has returned 80% over the past five years. Year to date, it is up about 1%, and over one year, roughly 1%.
An investor who wants monthly cash from a Berkshire-style portfolio can hold BRK.B and sell a fixed dollar amount of shares each month, paying long-term capital gains rates on the realized portion. That homemade dividend costs zero in fund fees.
OMAH charges a 0.98% net expense ratio to run the overlay, which must earn back that fee and outperform manual share selling to justify itself. Against a plain dividend ETF, the pitch is different: OMAH offers a higher headline yield and Berkshire-flavored exposure but caps upside and hands investors a tax-deferred slice of their own capital every month.
If you are weighing this against a broader income-first plan, we walked through the mix, the payment calendar, and the withdrawal order in a free guide to building a paycheck portfolio from ordinary savings.
Verdict on OMAH
OMAH is legitimate financial engineering. It suits a narrow investor: someone who wants a stable monthly check from a Berkshire-adjacent portfolio, values automation over manual share sales, and has accepted that the 15 in VistaShares’ Target 15 name will cost meaningful upside plus almost 1% a year in fees.
Anyone who wants Buffett’s actual compounding should own Berkshire directly and sell shares when cash is needed. That path is cheaper, more tax-efficient on gains, and does not require trusting an overlay to keep earning its keep.
The post OMAH Turned Buffett’s No-Dividend Portfolio Into a 15% Payout. Is It Income or Financial Sleight of Hand? appeared first on 24/7 Wall St..
]]>A federal judge rejected the Justice Department’s bid to force Google to sell its AdX advertising exchange, even after finding the company illegally monopolized the publisher ad-server and ad-exchange markets.
The liability finding stands, while the structural remedy was denied. Shares of Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) responded in kind, with Barron’s noting that Alphabet rose as Google avoided another attempt at a business breakup. The detailed remedies remain temporarily under seal, and the DOJ is still weighing its next moves, so the shape of what Google will actually live under is not yet public.
What the Ruling Kept and What It Killed
The court declined the divestiture the government sought, but the monopoly finding is intact and behavioral restrictions are coming. An ad exchange is the auction house where publishers sell impressions to advertisers in real time; a publisher ad server decides which ad wins.
Google owned both sides of that transaction, and that was the conduct the court condemned. Reuters reports the case now heads into a compliance regime with an appeal path still open.
Why the Ad-Tech Line Understates the Strategic Stakes
Google Network revenue was $7.303 billion in Q2 2026, a rounding line next to Google Services at $94.54 billion and Cloud at $24.77 billion, up 82%. That is exactly why the divestiture threat was never the real drag on the equity. The ad-tech stack matters because it feeds identity, measurement, and pricing data into the rest of advertising, and behavioral remedies will constrain how those pieces talk to each other.
Behavioral remedies still carry a cost, though.
Living under a court-supervised consent structure means monitors, disclosures, and product decisions that route through lawyers. It slows integration work at a time when Sundar Pichai says, “Gemini models now process 22 billion API tokens per minute and the Gemini App has 950 million monthly active users.”
Compliance friction is a tax on speed, and speed is what the AI cycle rewards, which is also why the power, cooling, and networking suppliers behind the data centers keep showing up in our free report on seven AI infrastructure names that are not chipmakers.
Judge Amit Mehta’s separate finding that Google illegally monopolized search still awaits its own remedy conclusion. Search & other delivered $63.27 billion in Q2 2026. That is the figure most exposed to the ongoing search remedy proceedings. This week’s ruling does not touch it.
Is Alphabet Stock a Buy?
At $337.12 and a P/E of 15x, Alphabet trades below Meta Platforms (NASDAQ:META) at roughly 22x, Microsoft (NASDAQ:MSFT) at 28x, and Amazon (NASDAQ:AMZN) at 35x, while Cloud grew 82% and the one-year return sits at 59.96%.
Analysts have 58 Buy ratings and 5 Hold ratings, with a target price of $428.07. The setup looks constructive on relative valuation. The ad-tech win is genuine; courts have now declined structural relief against Big Tech three times in recent years, and that pattern is worth more over a decade than any single exchange. The search remedy is still the risk to watch.
The post Google Was Found to Hold an Illegal Monopoly and Kept It Anyway. Is the Antitrust Nightmare Finally Over? appeared first on 24/7 Wall St..
]]>Alphabet’s cadence problem finally has a price tag. CEO Sundar Pichai said Gemini 3.5 Pro would arrive in June, but it still hadn’t shipped as of September 2, 2026. What Google shipped instead was Gemini 3.8 Flash, a cheaper coding model, while pointing investors to Gemini 4 later in the year. That substitution has landed at the worst possible moment for the stock.
Alphabet (NASDAQ:GOOG) shares are “on their longest losing streak since 2015,” according to CNBC’s Mackenzie Sigalos, following a brief stint this spring as the world’s most valuable company. The stock is down 10.39% over the past month, trading near $339.79 after opening green on Wednesday.
[chart id=”GOOG”]
A Promised Flagship, a Value-Tier Delivery
On the Q2 call, Pichai stayed on message about pace. “Gemini 3.5 Pro is currently in testing and our team is already building the next generation of models,” he told analysts, adding that “we have started our most ambitious pre-training run yet for Gemini 4.” He framed monthly releases as strategy: “Picking up pace and releasing models, you know, almost at a monthly cadence is part of our roadmap as we are building Gemini 4 as well.”
The problem is what the pace produced. The June flagship is absent. The Flash line, which Pichai called Alphabet’s “workhorse model” hitting “a sweet spot of performance, cost, reliability, latency, etc.”, keeps arriving on schedule.
Fundamentals That Argue the Other Way
The financials show a company still expanding at scale. Q2 revenue rose 24.23% to $119.8 billion, EPS of $9.11 beat consensus by 199.41%, and Google Cloud grew 82% year over year to $24.8 billion with backlog at $514 billion. The Gemini App now has 950 million monthly active users, and APIs process approximately 22 billion tokens per minute, up from 16 billion a quarter ago.
The bill is steep. Capex hit $44.9 billion, free cash flow swung to negative $5.86 billion, long-term debt jumped from $46.5 billion to $98.2 billion, and buybacks were suspended in Q2 2026. Even so, GOOG trades at a P/E of 14.
[company_earnings_history ticker=”GOOG”]
Two Same-Day Offsets Investors Should Weigh
Two developments arrived alongside the Gemini 3.8 Flash release. First, a judge ruled that “google will not have to sell its ad exchange”, removing an overhang on the ad monetization engine that Sigalos noted lets “Google compete more aggressively on price because it owns more of the stack and can monetize AI across cloud search and youtube and its ad engine.” Second, token prices are “down more than half from their summer peak, squeezing standalone model labs like openai.”
The accountability gap is real. So is the moat. Whether four down months mark a dip or a re-rating depends on what ships before Gemini 4, and on whether the $44.9 billion capex line keeps translating into cloud backlog rather than stranded silicon (we profiled seven suppliers riding that same buildout, from power to cooling, in a free report you can grab here).
The post Sundar Pichai Promised a Gemini Flagship in June, and Alphabet Is on Its Worst Streak Since 2015 appeared first on 24/7 Wall St..
]]>Microsoft (NASDAQ:MSFT) just voluntarily pulled Azure out from behind the curtain. The company said it will begin disclosing standalone Azure quarterly revenue as it consolidates its business units, according to reporting on September 2.
When a company reveals a number it has kept inside a larger bucket for years, that itself is information. The newly framed disclosure shows Azure sitting much closer to Google Cloud than to Amazon Web Services, and the gap to AWS is nearly three times the size of Azure’s lead over Google. For Microsoft (NASDAQ:MSFT) investors, that reframes which competitor actually matters.
What Microsoft Chose to Show, and Why Now
Microsoft reorganized reporting into two segments and moved some GitHub sales from Azure into the Microsoft 365 Cloud line. That makes any growth rate straddling the change harder to trust, so read the near-term Azure prints with care.
The overall quarterly outlook was left unchanged, which matters, because a reporting reshuffle moves revenue between lines without changing the underlying business. Azure crossed $100 billion in full-year revenue for the first time, with Q4 growth of 43% year-over-year and commercial RPO of $678 billion, up 84%.
Why the Distance to AWS Dwarfs the Lead Over Google
Amazon (NASDAQ:AMZN) reported $42.23 billion in AWS revenue, with 36.7% year-over-year growth, its fastest in 18 quarters. Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) posted Google Cloud revenue of $24.77 billion, accelerating to 82%.
Azure sits between them, but Google’s growth rate is the more visible headline, while enterprise workloads land where identity, data, and existing contracts already sit. On that measure, Amazon is both the larger incumbent and, now, the newly available alternative for Microsoft’s most important AI partner. AWS operating margin was 39.4%, and AI and Chips each exceeded $25 billion annualized run rates.
OpenAI’s Optionality Problem
OpenAI is no longer confined to Azure. It committed roughly 2 GW of Trainium capacity through AWS starting in 2027, and Anthropic separately secured up to 5 GW of Trainium chips.
That converts a captive workload into a contested one and removes a structural reason for AI compute to default to Azure. Microsoft’s Q4 EPS beat included a $3.2 billion gain from its Anthropic investment, and Amazon booked a much larger one-time gain tied to the same relationship, a reminder that these AI bets overlap even as compute flows elsewhere.
Where Microsoft’s Real Advantage Sits
Microsoft’s structural edge is enterprise distribution. Microsoft 365 Copilot surpassed 30 million paid seats, and nearly 90% of the Fortune 500 ground agents use Foundry, Fabric, and Work IQ.
The company that already sells the productivity suite, the identity layer, and the developer tools has an easier path to the cloud budget than one that sells infrastructure alone. FY27 capital expenditures are planned at roughly $175 billion, a claim on future free cash flow that only pays off if that distribution converts (we profiled seven companies powering the buildout behind numbers like that, from power to cooling, in a free AI infrastructure report).
Is Microsoft Stock a Buy?
Microsoft trades at a P/E of 28x with shares at $496.82, up 3.38% year-to-date. Amazon sits at a 20x P/E, Alphabet at 17x. Alphabet is the value story, Amazon the scale-plus-growth story, Microsoft the distribution story. The setup favors the distribution thesis. The Azure disclosure clarified where the real fight sits, and Microsoft’s installed base still gives it more paths to monetize AI than a growth-rate comparison to Google Cloud suggests.
The post Why Microsoft Investors Should Fear Amazon More Than Google appeared first on 24/7 Wall St..
]]>Elon Musk told the G20 this week that artificial intelligence will “probably increase the global economy by 20 to 30%. That’s my rough estimate, meaning on the order of 20 to 30 trillion per year.”
This matters because Tesla (NASDAQ:TSLA) is no longer valued as a car company. It trades at a $356.09 price with a trailing P/E near 371x, which only makes sense if you believe autonomy and humanoid robotics are close. A CEO telling world leaders that robotics is about to reshape productivity is talking his book, in the most literal sense of the phrase.
Musk’s G20 Claim, Unpacked
Musk framed the estimate around three specific bets. He cited existing Tesla self-driving productivity, humanoid robots on the horizon, and AI software approaching what he called Stockfish-level performance at digital work.
On software, he said AI “will be able to do anything digital, anything that does not require shaping of atoms by hand, probably by the end of next year.” That is a very specific window.
On robotics, he said, “we’ll see very dramatic gains in productivity from robotics.” Tesla is installing first-generation Optimus lines at Fremont, with production anticipated in 2026.
On coding, he claimed, “AI software will be so good that it will be stockfish level good, meaning that it is impossible for a human to compete in writing software with AI.”
Taken together, this is a forecast that the entire digital economy re-prices within roughly eighteen months. A 20% to 30% lift to global output would rank among the largest productivity shocks in recorded economic history.
Why Timeline Matters More Than the Dollar Figure
Shocks of that size have historically taken decades to diffuse. Electricity, the internal combustion engine, and the internet all worked through the economy on generational timescales because adoption is bottlenecked by organizations and by installed capital stock, not by whether the underlying technology works in a lab.
Musk has a long record of being directionally right about technology while being years early on timing. Full Self-Driving as a robotaxi network was pitched in 2019. Optimus was unveiled in 2021 as imminent. The pattern is real and worth stating plainly.
For the $30 trillion number to hit inside his stated window, three things would have to be true at once. Enterprises would need to redesign core workflows around agentic AI in months. Humanoid robots would need to reach unit economics that beat human labor at scale. Power, memory, and fab capacity would need to arrive on schedule.
The last of those is the constraint even NVIDIA cannot solve. “Our entire supply chain is challenged. And everybody is really running flat out,” Jensen Huang said on the August 26 earnings call.
The right way to hold Musk’s forecast is to treat the direction as credible and the timeline as roughly a decade optimistic. That is what the historical base rate for productivity diffusion actually says.
Buildout Evidence From NVIDIA and Alphabet
NVIDIA (NASDAQ:NVDA) posted $96 billion in Q2 revenue, more than doubling year over year, and guided Q3 to $108 billion, plus or minus 2%. Data center hit $89 billion, and management said the outlook is supply-constrained rather than demand-constrained.
The forward book is even more striking. NVIDIA described cloud industry backlog greater than $2 trillion and expects top-five hyperscaler capex to reach nearly $800 billion in 2026 and $1.3 trillion in 2027.
Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) is spending in line with that same wave. Google Cloud grew 82% in Q2 to $24.77 billion, and quarterly capex reached $44.9 billion, roughly double year over year.
The Gemini adoption figures are the part that supports Musk’s directional claim. Nearly 90% of the Fortune 100 use Gemini Enterprise, and the Gemini App has 950 million monthly active users. That is diffusion happening in real time, but into workflows we already had.
The pattern is consistent. The pick-and-shovel businesses are printing real revenue against real demand, and the list runs well past the chipmakers themselves (we pulled seven of those suppliers, from power to cooling, into a free report). The productivity payoff to the broader economy is the part that lags, because organizations rewire slowly and the physical constraints on power and fab supply are binding through at least fiscal 2028.
Is TSLA Stock a Buy?

Tesla’s Q2 revenue of $28.24 billion beat expectations, but non-GAAP EPS came in at $0.33, below the $0.54 estimate. Operating margin compressed to 1.4% and free cash flow flipped negative at -$1.09 billion. The filed press release attributes the pressure to AI infrastructure spend and the CEO performance award.
On autonomy, Tesla’s Robotaxi fleet has expanded to seven U.S. markets with roughly 380,000 miles of unsupervised operation. Alphabet’s Waymo is doing 500,000 fully autonomous rides a week. Tesla’s approach may scale faster, although the gap in operating evidence today is enormous.
On vehicles, BYD and the legacy automakers are compressing margins in every region Tesla sells into. Tesla’s automotive gross margin excluding regulatory credits fell sequentially from 19.2% to 16.3%. The car business is no longer subsidizing the AI story with the cash flow it once did.
Full-year capex is now guided to exceed $25 billion, with debt facilities of up to $30 billion arranged. This is a company financing a very long-dated bet against an operating income line that has collapsed in the near term.
On balance, the risk/reward looks balanced at current levels. The autonomy and robotics thesis has substance, yet the stock already prices in a version of Musk’s G20 timeline that the base rates on industrial scale-up do not support. NVIDIA and Alphabet offer cleaner exposure to the same trend at valuations backed by cash the businesses are earning today, so I wouldn’t go heavy on TSLA stock.
The post Musk’s $30 Trillion AI Forecast Hinges on a Timeline Even NVIDIA Says Is Unrealistic appeared first on 24/7 Wall St..
]]>Google is reportedly about to ship a new coding model that its own engineers say they prefer to Anthropic’s Claude Opus for internal work. That is a real development for developer mindshare, but it is also not the model Sundar Pichai promised earlier this year, and the gap between shipping cadence and shipping substance is starting to matter to the stock.
Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) closed at $335.02 on September 1, 2026, down 5.93% over the past month even as the year-to-date figure sits at 7.17%. The one-year return is still 57.8%, so this is the kind of manageable pressure that surfaces when a leadership team keeps promising a step change and delivers steady, incremental releases instead.
What CNBC’s Sigalos Actually Said
On CNBC, reporter MacKenzie Sigalos summarized Wall Street Journal reporting on the impending release. “Google’s AI team is set to release a new model 3.8 flash. This apparently has upgraded coding capabilities.”
She continued: “It could come as soon as tomorrow, and the company’s engineers telling the Journal that they actually prefer it to Anthropic’s Opus model in terms of performing internal coding tasks.” Then the important qualifier: “This is not 3.5 Pro, which Alphabet CEO Sundar Pichai promised back in June. Nor is this Gemini Forge, the real step change that we have been waiting for from Gemini.”
And the organizational overhang: “This comes amid an exodus of talent from the DeepMind lab as we see this big reorg internally.” The internal-engineer preference counts as suggestive evidence at best. It is self-reported and unbenchmarked, filtered through a newspaper.
Why a Cheap Coding Model Matters for Cloud Margins
A fast, cheap Flash model that outperforms a leading rival on coding tasks matters because coding is where inference costs get paid. Developers who lean on a model all day generate volume, and volume is where Google Cloud captures margin. Pichai told investors that Gemini models now process 22 billion API tokens per minute, and that the Gemini App has 950 million monthly active users.
Cloud revenue is where this shows up first. Google Cloud grew 82% in the second quarter to $24.77 billion, and Pichai said “nearly 90% of the Fortune 100” now use Gemini Enterprise. Details are in the Q2 8-K exhibit.
Consolidated revenue was $119.8 billion, up 24.23% year over year, with operating income of $40.77 billion. The problem is what sits underneath: capex hit $44.9 billion in the quarter, free cash flow turned negative at -$5.86 billion, and long-term debt jumped from $46.5 billion to $98.2 billion. Buybacks were suspended.
Credibility Is Slipping at DeepMind
A missed or delayed flagship is as much a management question as a technology one. Pichai committed to Gemini 3.5 Pro in June, and prediction markets on Polymarket had already resolved against a Pro release by August 31, 2026, with the “no release” outcome winning with an accuracy score of 0.971. A Flash 3.8 release by September 30 was priced at probability 0.991, so the market expected exactly this substitution.
DeepMind departures compound concerns because frontier model quality is concentrated in a small group of researchers, and a reorganization during a competitive sprint tends to cost momentum. Microsoft has its own silicon coming, Meta keeps open-sourcing capable models, and Anthropic, which Google itself funds, is why Claude sits atop many developer stacks.
The earnings reactions have been complicated too. Every one of the last 12 quarters was a beat, yet the average one-day reaction was -0.48%. The Q2 report carried a 199.41% surprise, and shares still fell 7.13% that session.
Is GOOG Stock a Buy?
At a P/E of 17x, Alphabet is cheaper than Microsoft (NASDAQ:MSFT) and Meta (NASDAQ:META) on forward earnings, cheaper than Amazon (NASDAQ:AMZN) on almost any measure, and it owns the only rival stack that competes credibly with Anthropic and OpenAI in coding, search, and cloud at once. Analysts show 58 buys and 6 holds with a target of $428.07.
The AI capex is real and the flagship is late, but a coding model developers actually reach for is likely worth more to cloud economics than a headline benchmark win (all that spending also has to be powered, cooled and networked by somebody, which is the whole point of our free report on seven AI infrastructure suppliers behind the buildout, here), which is why the setup remains constructive despite the noise around delayed flagships.
The post Sundar Pichai’s Credibility Crisis: The AI Model That Never Came appeared first on 24/7 Wall St..
]]>John Ternus starts as Apple (NASDAQ:AAPL) CEO with the stock near a historic high, and roughly 8 days remain before a September hardware event where he will address the entire audience for the first time. CNBC’s MacKenzie Sigalos said, “John Ternus era begins at a moment when Apple is facing historic headwinds.”
Shares rose 2.61% on his first day and traded at $325.13, up 40.58% over one year and 19.92% year to date on a market cap of $4.745T. The pressures Ternus inherits are real but uneven. Memory costs squeezing hardware margins will pass. The AI question is structural, and Apple has to answer it in a way that changes minds about where the next computing interface will actually live.
Margin Squeeze Is the Mechanical Problem
Fiscal Q3 revenue was $109.42 billion, up 16.4% year over year, with EPS of $2.02 beating the $1.89 consensus, per Apple’s 8-K filing.
Gross margin was 50.1%, and tariff refunds added roughly 2 percentage points on top. Strip those out and Apple still ran a very good quarter.
September guidance points to gross margin between 47% and 48%. Tim Cook described memory pricing as “a 100-year flood on the memory pricing with exponential increases in memory prices” driven by only three DRAM suppliers.
Sigalos framed the tension precisely: “Push iPhone prices too far, and you risk slowing the device growth that ultimately feeds services.”
Services delivered $30.74 billion at 75.6% gross margin. Hardware volume feeds that annuity, and Ternus cannot let iPhone unit economics slip while he defends the average selling price.

AI Question Is the Structural One
Siri AI shipped to developers after WWDC26, and Cook said early reviews were “phenomenal,” although that assessment comes from Apple itself.
The competitive set does not flatter Apple’s positioning. Microsoft (NASDAQ:MSFT) passed 30 million paid Microsoft 365 Copilot seats, and Azure surpassed $100 billion in fiscal-year revenue, growing 41%.
Alphabet’s (NASDAQ:GOOG, NASDAQ:GOOGL) Gemini app hit 950 million monthly active users, and Google Cloud revenue grew 82% in Q2. Meta (NASDAQ:META) is putting personal agents on top of Family DAP of 3.60 billion.
Apple’s R&D of $11.73 billion a quarter is real spending, but Microsoft alone plans roughly $175 billion in FY27 capex, and all of that buildout has to be powered, cooled, and networked by somebody (we rounded up seven of those infrastructure suppliers in a free report).
Sigalos captured the real risk: “The AI challenge goes well beyond fixing Siri. As agents become the front door to apps and services, Apple has to make sure that the iPhone stays at the center of that experience, even as rivals start experimenting with entirely new AI native devices.” If the agent becomes the interface, the operating system becomes plumbing.
Foldable Would Be Loud But Not Sufficient
Sigalos reported that “A recent operating system leak directly from Apple exposed clues to ten plus still unannounced devices, including a foldable iPhone, potentially the first major change to the phone’s form factor in 20 years, something that we might see as soon as next Wednesday.” Treat that as reported and unconfirmed.
Polymarket puts the probability of an Apple foldable iPhone before 2027 at 0.949, while a broader “new product line” market sits at only 0.305.
A foldable would help Apple close ground on Samsung and reset the upgrade cycle, although the AI question would remain open.
Apple is also in an escalating legal dispute with OpenAI over hardware and trade secrets, per Sigalos, while OpenAI has been buying Macs by the tens of thousands.
Hardware theater buys Ternus time to prove out Siri AI at scale, while the interface question stays open.
Is AAPL Stock a Buy?

Apple trades at a P/E of 37x and a forward P/E of 33x against an analyst target of $324.45, so the average Street target sits at roughly today’s price.

Samsung leads foldables and will not be caught by novelty alone. Alphabet and Microsoft are ahead on models, cloud economics, and the distribution of agents into enterprise workflows.
Meta Platforms is spending $130 to $145 billion in 2026 capex to put personal agents into billions of hands. Apple’s counter is the installed base of more than 2.5 billion active devices, silicon integration, and a services flywheel most rivals cannot replicate.
That mix is enough to hold the position because Apple still monetizes its users better than anyone, though adding on strength should wait until Ternus proves the platform still leads.
The margin squeeze looks likely to pass, as memory cycles always do, and paying 33x forward for a company in the middle of a platform transition reads as fair value, given the unresolved AI question.
The post Apple’s New CEO Has 8 Days to Answer the AI Question That Could Redefine Computing appeared first on 24/7 Wall St..
]]>On Tim Cook’s final day as chief executive, Jim Cramer delivered a verdict that reframes the entire hyperscaler debate. Speaking on Mad Money on August 31, 2026, he called Apple’s balance sheet “pristine…the envy of the industry, maybe any industry” while accusing the AI infrastructure giants of the opposite sin.
“The hyperscalers have wrecked their balance sheets to build these data centers. They’re the ones to worry about, not Apple.”
Apple (NASDAQ:AAPL) closed FY2025 with $112.377 billion in total debt, $73.733 billion in equity, and retained earnings of negative $14.264 billion. Alphabet (NASDAQ:GOOG), the poster child for AI capex excess, closed the same year with $415.265 billion in equity and only $59.291 billion of debt.
Reading the Filings Side by Side
Apple carries nearly twice the total debt Alphabet does, and its debt-to-equity ratio sits at 1.5241 versus Alphabet’s 0.1428. The negative retained earnings are the direct arithmetic of the buybacks Cramer praised in the same breath: Apple has repurchased $62.094 billion of stock in the nine months through June 27, 2026, on top of $90.711 billion in FY2025.
Alphabet’s leverage jumped fast this year. Long-term debt more than doubled from $46.547 billion at year-end 2025 to $98.165 billion by June 30, 2026, funding CapEx guided to $175 billion to $185 billion for 2026. The buyback program was suspended in Q2 2026. Free cash flow flipped to negative $5.86 billion.
Why the Market Isn’t Punishing Apple
Cramer’s framing survives scrutiny for a reason: liquidity. Apple holds $39.544 billion in cash and $84.118 billion in long-term investments, a cushion that dwarfs the near-term maturities. Net debt to EBITDA sits at 0.528, and interest coverage on Alphabet’s side remains at 175.3x. Both companies remain financially sound.
Investors have voted with their wallets. Apple is up 16.87% year to date through September 2, 2026, versus Alphabet’s 8.56% gain. Apple trades at a 42 P/E multiple, roughly triple Alphabet’s 14.
What to Watch as Ternus Takes Over
Bloomberg reports the John Ternus era begins after Cook’s 2,300% stock gain, with CNBC flagging AI challenges and a memory crunch ahead. If Apple accelerates its own AI infrastructure build, the buyback pace will collide with capex needs, and the “pristine” label will face its first real test. All that hyperscaler spending has to be powered, cooled, and networked by someone, and we pulled together seven suppliers doing exactly that in a free AI infrastructure report.
The post Jim Cramer: Hyperscalers ‘Wrecked Their Balance Sheets’, But Apple Carries Twice Alphabet’s Debt appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) has quietly become one of the most compelling AI plays in mega-cap tech, and the market appears to be pricing it as though Search were decelerating, even as growth accelerates.
Our 24/7 Wall St. price target for Alphabet is $435.40, which implies 26.98% upside from the current price of $342.88. We rate GOOG a buy with a 90% confidence level, among the highest we assign in the communication services sector.
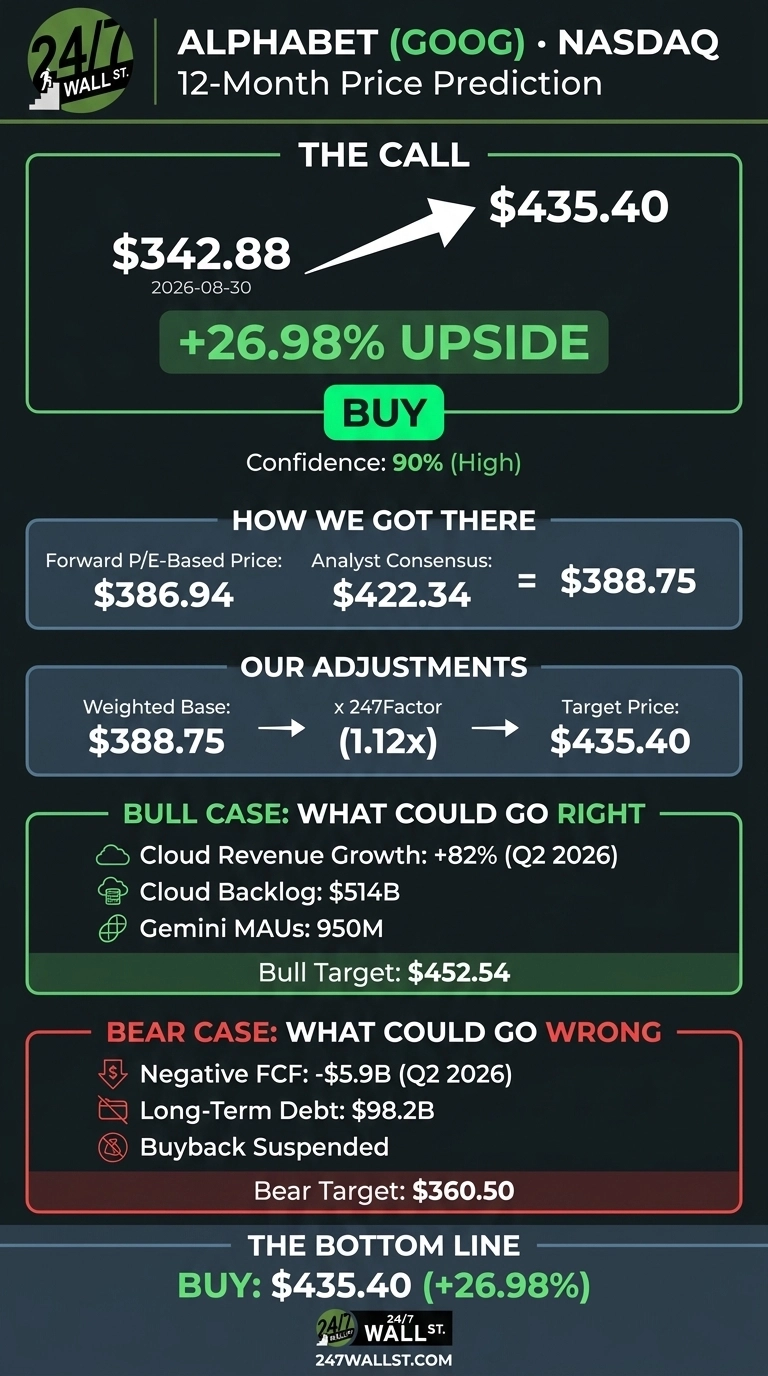
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $342.88 |
| 24/7 Wall St. Price Target | $435.40 |
| Upside | 26.98% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Cloud Business Suddenly Growing Like a Startup
Alphabet shares are up 9.41% year to date and 61.92% over the past year, yet the stock still sits well below the 52-week high of $404.23.
The Q2 FY2026 report was the catalyst that reset the narrative: revenue of $119.8 billion grew 24% year over year, EPS came in at $9.11 versus a $3.0427 estimate, and Google Cloud revenue accelerated to 82% growth. Cloud backlog now stands at $514 billion, and Motley Fool argued in late August that investors are still underestimating Google Cloud. I agree.
Why Bulls See a Breakout Ahead
The bull case rests on three pillars. First, Cloud economics are inflecting: Q2 Cloud operating margin expanded to 35.6% from 20.7% a year earlier.
Second, Gemini is scaling fast, with 950 million monthly active users and API throughput at 22 billion tokens per minute.
Third, Sundar Pichai told analysts “over the past year, we’ve gotten more bullish on the opportunities ahead”. Our bull scenario points to $452.54, and the Street’s high end sits at $422.34 consensus with 13 strong buys and 44 buys.
What Could Go Wrong
Q2 free cash flow was negative $5.855 billion as capex hit $44.9 billion, long-term debt jumped from $46.5 billion to $98.2 billion, and the buyback was suspended. Bears would note that our bear scenario lands at just $360.50.
Counterfactually, bulls would argue this capex reflects genuine supply constraints, with backlog of $514 billion demanding investment now (the same buildout that lifts the power, cooling, and networking names we profiled in a free AI infrastructure report). FCF still totaled $53.3 billion on a trailing basis.
How Alphabet Compares to Microsoft and Meta
Microsoft (NASDAQ:MSFT) trades at a forward P/E of 26 with quarterly revenue growth of 17.7%, meaningfully slower than Alphabet’s 24.2%.
Meta Platforms (NASDAQ:META) sits at a forward P/E of 19, closer to GOOG but with quarterly earnings growth of negative 13.4%. Against this field, Alphabet’s forward P/E of 16 looks conservative, which is why our 24/7 Wall St. price target sits comfortably above current levels.
| Company | Forward P/E | Quarterly Revenue Growth |
|---|---|---|
| Alphabet | 16 | 24.2% |
| Microsoft | 26 | 17.7% |
| Meta | 19 | 28% |
Why the Setup Favors Alphabet
The 24/7 Wall St. price target of $435.40, a buy rating, and 90% confidence reflect a rare setup: hyperscaler growth at a value multiple.
The setup looks compelling if Cloud growth stays north of 60% into Q3. Caution is warranted if capex balloons past guidance without corresponding backlog conversion. On balance, the risk/reward favors ownership.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $374.12 |
| 2027 | $438.19 |
| 2028 | $520.35 |
| 2029 | $580.72 |
| 2030 | $646.72 |
These projections assume Alphabet continues executing on Cloud and Gemini. Significant upside or downside could come from AI infrastructure ROI and regulatory action in the EU and US.
The post The Market May Be Underestimating This Stock appeared first on 24/7 Wall St..
]]>Advanced Micro Devices (NASDAQ:AMD) and Alphabet (NASDAQ:GOOG) both delivered blockbuster Q2 FY2026 results, yet they tell very different AI stories.
AMD is riding a hardware supercycle led by Instinct and EPYC. Alphabet is monetizing AI through Search, Cloud, and Gemini while pouring cash into infrastructure. Comparing them now matters because the market has priced one as an AI hero and the other as a value stock hiding in plain sight.
Instinct Accelerates for AMD, Cloud Explodes for Alphabet
AMD posted revenue of $11.5 billion, up 50% year-over-year, with Data Center revenue growing 107% to a record $6.7 billion. CEO Lisa Su told investors “Customer pull for Helios is very strong and tracking ahead of our initial forecasts.” The Anthropic commitment for up to two gigawatts of MI450 series GPUs in Helios shows the scale of what is coming.

Alphabet countered with revenue growth of 24% year-over-year and Google Cloud revenue of $24.8 billion, up 82%. Sundar Pichai highlighted that nearly 90% of Fortune 100 companies use Gemini Enterprise, while cloud backlog swelled to $514 billion. That backlog is a queue of committed demand AMD simply cannot show on its balance sheet.
| Business Driver | AMD | Alphabet |
| Q2 revenue growth | 50% | 24% |
| AI growth engine | Data Center +107% | Google Cloud +82% |
| Quarterly CapEx | $808M | $44.9B |
Pure Silicon Play vs. Full Stack Empire
AMD’s bet is narrow and deep. Helios rack-scale systems combine EPYC Venice CPUs, MI450 GPUs, Pensando networking, and Rackham software, delivering up to 30% more tokens per dollar than the competition.
Su expects the data center AI accelerator market to grow more than 45% annually to approximately $1.4 trillion by 2030. The risk is concentration. Gaming revenue fell 31% year-over-year, and hardware demand can turn quickly.

Alphabet’s bet is wider. It sells Gemini APIs processing 22 billion tokens per minute, custom TPUs shipped into customer data centers, ad tools where AI Max was adopted by half a million advertisers, and YouTube reach.
Pichai framed it plainly: “The model is just an ingredient in those solutions.” The downside is capital intensity, with free cash flow at negative $5.86B and buybacks suspended.
Valuation Gap Could Decide the Race
The valuation spread between these two names is stark. AMD trades at a P/E of 175 with a forward P/E of 65. Alphabet trades at a P/E of 14. AMD has ripped 117.4% year-to-date. Alphabet is up only 9.41%.
I want to see whether AMD’s server CPU business can hit management’s target of more than 80% year-over-year growth in the second half of 2026, and whether Alphabet can convert its $514 billion backlog into margin without cloud margins slipping.
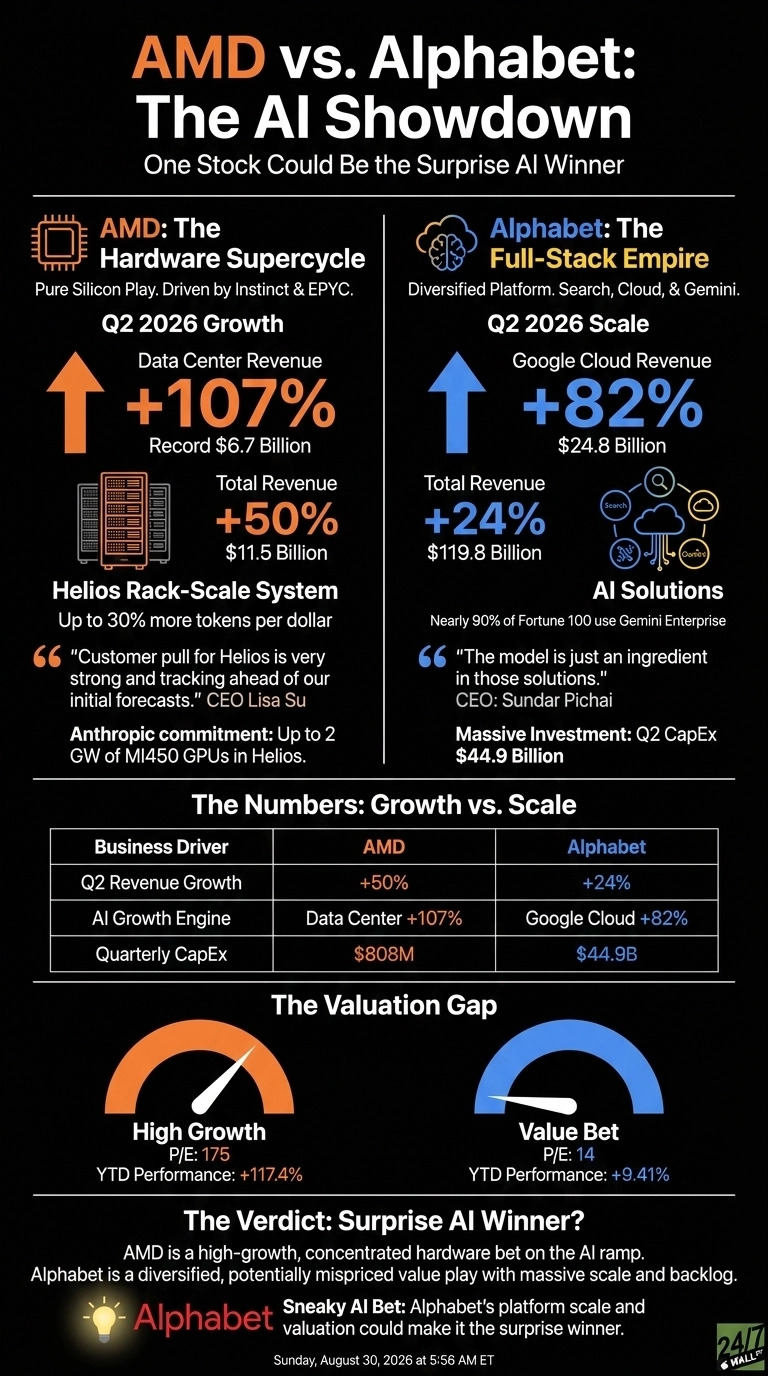
Why Alphabet Looks Like the Sneakier AI Bet to Me
Personally, I lean Alphabet. Paying 14 times earnings for a business growing Cloud at 82%, sitting on a half-trillion-dollar backlog, and monetizing AI in ads today feels mispriced against a semiconductor cycle that has already delivered a 176.18% one-year gain for AMD.
Growth-oriented investors with tolerance for volatility get the sharper upside on the Helios ramp with AMD. For investors seeking AI exposure without paying 65 times forward earnings, Alphabet quietly looks like the surprise winner hiding behind the louder chip narrative. And if the real money in this cycle sits with the power, cooling, and networking suppliers feeding both companies, we pulled seven of them into a free AI infrastructure report.
The post AMD vs. Alphabet: One Stock Could Be the Surprise AI Winner appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) just posted Google Cloud growth of 82% to $24.8 billion and Q2 EPS of $9.11 versus $3.04 estimates. CEO Sundar Pichai told analysts “it feels like we are in very early innings of what feels like secular shift.”
Yet shares sit at $342.88, up just 9.41% YTD. Can GOOG realistically hit $500 by the end of 2027?
Why Alphabet Shares Are Stuck Despite Blowout Growth
Capex fear. Alphabet guided 2026 capex to $175 billion to $185 billion, and Q2 free cash flow swung to negative $5.9 billion. Long-term debt rose $46.5 billion to $98.2 billion, and the buyback was suspended. Investors want to know whether TPU and data center spend will actually earn a return.
Performance shows the skepticism. Shares are up just 0.33% over the past week and 2.12% over the past month. With a beta of 1.24, GOOG should move faster than the broader market. Right now it isn’t.
Some top investors are already saying Google is “a very different company” than it was two years ago (we reverse-engineered what the biggest tech winners looked like this early in a free playbook).
Wall Street Is Bullish, But Consensus Is Still Too Low
Sell-side consensus sits at $422.34, backed by 13 strong buys, 44 buys, and 6 holds. Zero sells. Our model’s base case comes out higher at $435.40, implying 27% upside with a high 0.9 confidence score. Bull case runs to $452.54, bear case to $360.50.
My view: analysts are still pricing Alphabet like a mature ad business. That ignores 90% bullish analyst sentiment and a Google Cloud backlog of $514 billion, roughly half of which converts to revenue over the next 24 months. If Cloud stays anywhere near current growth, these targets get raised.
Path To $500 Per Share
Reaching $500 from today’s price of $342.88 would require a gain of 45.8%.
With forward EPS of $23.49, a price of $500 implies a forward P/E of 21x. Our base case of $435.40 already implies 19x, meaning the bold target requires roughly 3 additional turns of multiple expansion.
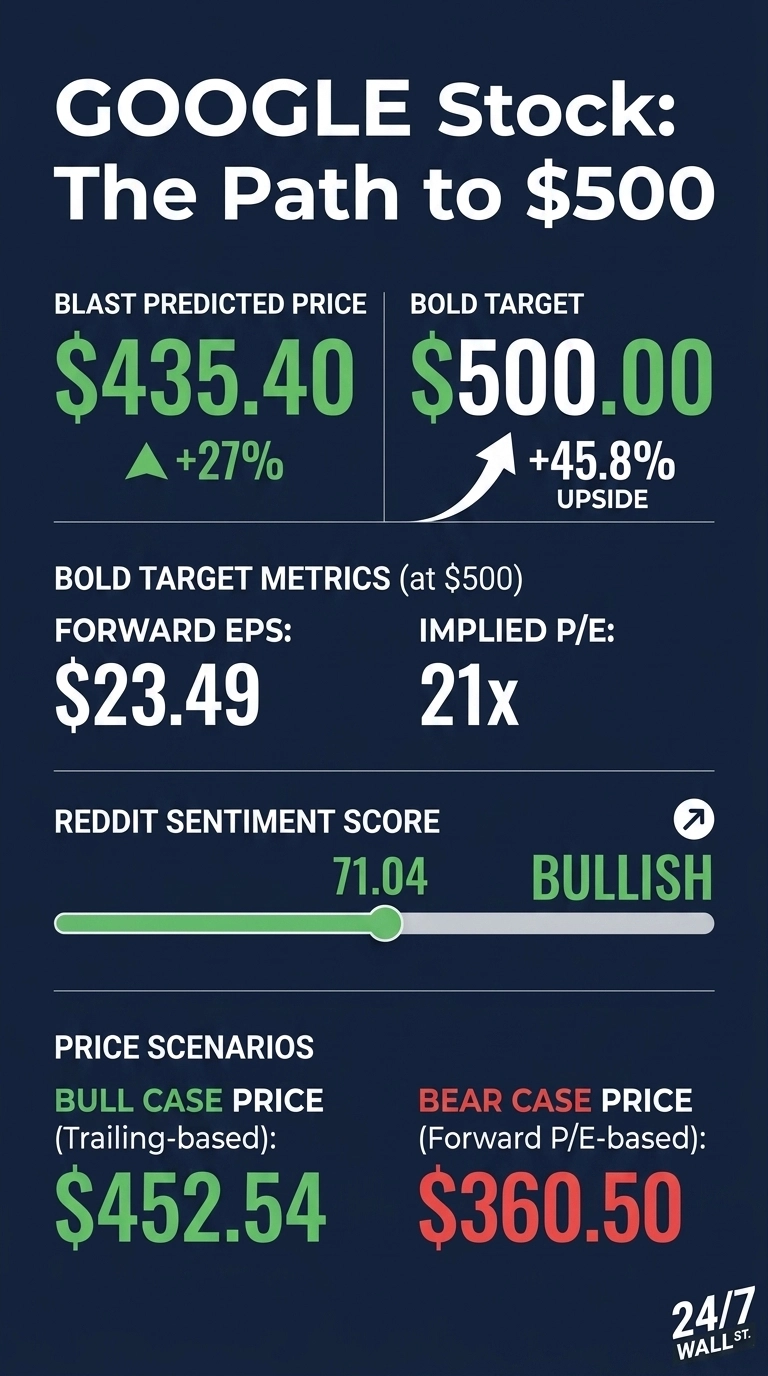
Less demanding than it sounds. GOOG trades at just 16x forward earnings, cheaper than every Mag 7 peer. Pichai says Alphabet is “winning new customers more than doubling our acquisition velocity year over year” in Cloud, while Gemini App reached 950 million monthly active users and AI mode surpassed 1 billion MAU. Antitrust remedies remain the wild card that could compress the multiple.
Where Alphabet Trades Versus Its Earnings Power
Current forward multiple sits at 16x. A hyperscaler growing Cloud 82% with a 35.6% Cloud operating margin typically commands a premium to that.
Shares sit between a $404.23 52-week high and a $206.37 52-week low. GOOG is up 799.56% over the past 10 years. That long-term track record is exactly why I think a mid-20s multiple is reachable if AI monetization scales through 2027.
My Verdict On $500 Alphabet
Hitting $500 requires a 45.8% gain and a rerating to 21x forward. Realistic, but a stretch on a 12-month horizon.
Three things need to go right: Cloud growth stays above 60%, TPU revenue starts hitting the P&L as guided for late 2026 into 2027, and antitrust rulings avoid forced divestitures. Keep an eye on the October 28 Q3 earnings report. A sharp Cloud deceleration would derail the thesis fast. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Alphabet could reach $500 in 2027.
The post One Mag 7 Stock to Watch in the Second Half of 2026 For Solid Gains appeared first on 24/7 Wall St..
]]>Meta Platforms (NASDAQ: META) and Alphabet (NASDAQ: GOOG) both closed the books on Q2 2026 with massive AI ambitions and very different market reactions. Meta reported on July 29, 2026, Alphabet on July 22, 2026.
One quarter drew a fine line under advertising discipline. The other showcased a runaway cloud franchise, and the valuation gap between them is now hard to ignore.
Cloud Powers Google. Legal and Layoffs Weigh on Meta.
Alphabet posted revenue of $119.8 billion, up 24.23%, with Google Cloud accelerating to 82% growth and reaching $24.77 billion. Cloud backlog climbed to $514 billion, a number that reframes how investors should value the segment.
Sundar Pichai told analysts, “Cloud revenue grew 82%, powered by strong demand for AI infrastructure and AI solutions.” Search still grew 17%, and YouTube ads added 13%.
Meta’s top line held up. Revenue hit $60.80 billion, up 27.96%, and advertising climbed 27%. But EPS came in at $6.18, missing expectations by 14.42% and ending a six-quarter beat streak.
Blame $2.40 billion in legal charges and $1.18 billion in severance tied to roughly 8,000 layoffs. Operating margin compressed to 31% from 43%. That kind of margin swing is painful, even when the ad engine is roaring.
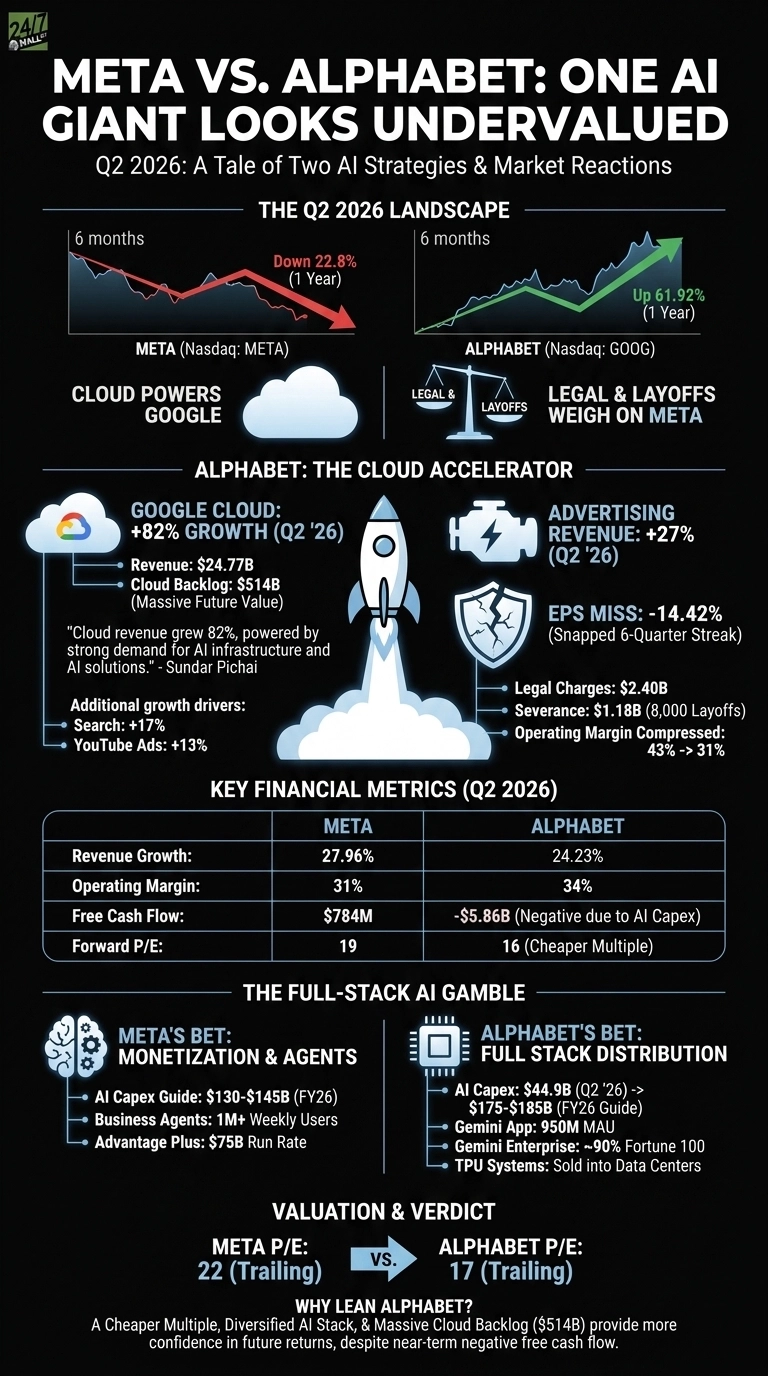
| Q2 2026 Driver | Meta | Alphabet |
| Revenue growth | 27.96% | 24.23% |
| Operating margin | 31% | 34% |
| Free cash flow | $784M | -$5.86B |
| Forward P/E | 19 | 16 |
Full Stack Ambition Meets Full Stack Distribution
Both companies are betting the balance sheet on AI compute. Meta guided full-year capex to $130 to $145 billion and lifted long-term debt to $83.66 billion.
Alphabet went further, raising $49.6 billion in net equity proceeds, issuing $20.3 billion in senior notes, and suspending buybacks. Debt roughly doubled to $98.2 billion. All that capex has to be powered, cooled, and networked by somebody, and we pulled together seven suppliers riding that buildout in a free report on the AI infrastructure names beyond the chipmakers.
Zuckerberg’s pitch is monetization through advertising intelligence, personal agents, and business agents. Meta said more than 1 million businesses already use business agents weekly, and Advantage Plus reached a $75 billion annual run rate.
Pichai’s pitch is broader distribution: Gemini App at 950 million monthly active users, nearly 90% of the Fortune 100 using Gemini Enterprise, and TPU systems now sold into customer data centers.
Valuation Gap Sets Up the Next Six Months
Meta trades at a P/E of 22. Alphabet sits at 17, despite growing cloud four times faster. Meta stock is down 22.8% over the past year. Alphabet is up 61.92%.
I want to see whether Meta’s operating income can clear 2025 levels as management promises, and whether Google Cloud margins hold up as third-party capacity gets rented in Q3.
Why I Lean Toward Alphabet Right Now
If I had to pick one today, I would lean toward Alphabet. A cheaper multiple, a diversified AI stack, and a cloud backlog north of $514 billion give me more confidence in the return on that capex.
Meta’s ad engine is arguably the best in the world, and at 19 times forward earnings the setup for patient investors looks reasonable. But the legal overhang and Reality Labs drag make me want a discount I do not quite see yet.
Meta offers a turnaround profile, while Alphabet offers scale, cash generation on a trailing basis ($53.3 billion TTM free cash flow), and a clearer AI monetization curve.
The post Meta vs. Alphabet: One AI Giant Looks Undervalued appeared first on 24/7 Wall St..
]]>
Artificial intelligence is changing the economics of digital advertising faster than many investors expected. The technology isn’t simply creating new products; it is making existing businesses better at turning attention into dollars. That is important because advertising remains one of the internet’s biggest profit pools. And now, Bernstein says Meta Platforms (NASDAQ:META) could capture a larger share of that pool than Google’s core Search business before the end of 2026.
For investors, the important point isn’t merely that Meta is catching up to Google. It’s that billions of dollars in AI spending are beginning to show up as measurable revenue gains.
Meta’s AI Investment Is Paying Off
Meta entered 2026 spending aggressively on AI infrastructure, but its second-quarter results show why management is willing to make that bet. Revenue climbed 28% year over year to $60.8 billion, while advertising revenue reached roughly $59.4 billion, up 27%. Ad impressions increased 14%, and the average price per ad rose 12%.
The number that matters most for the Google comparison is that Meta captured nearly half of every incremental digital advertising dollar in the second quarter, according to Bernstein. The investment firm says AI is improving recommendations, engagement, targeting, ad delivery, and the journey from discovering a product to purchasing it.
That is AI monetization investors can actually measure.
The $60 Billion Clue
Meta’s Advantage+ automated advertising platform provides another piece of evidence of its search success..
During its second-quarter earnings conference call, Meta said Advantage+ was generating approximately $75 billion in annualized revenue. The company also said advertisers using the system generated an average return of $4.52 for every dollar spent — about 22% more than manually configured campaigns.
That makes the $60 billion figure particularly important. It isn’t an estimate of Meta’s AI spending or a new revenue stream waiting somewhere down the road. It represents the annualized scale of an existing advertising product increasingly powered by automation.
And Meta isn’t finished. CEO Mark Zuckerberg has said the company wants ad creation to become fully automated by the end of 2026.
Google Still Has the Lead — For Now
Alphabet (NASDAQ:GOOG) remains the incumbent and investors shouldn’t underestimate it. Google Search and other advertising revenue reached $63.3 billion in the second quarter, up 17% year-over-year, compared with Meta’s roughly $59.4 billion in Family of Apps advertising revenue. The gap, however, was only about $3.9 billion for the quarter.
More importantly, Google is growing more slowly. Alphabet reported total Google advertising revenue of $81.6 billion, up 14%, while Search grew 17%. Bernstein believes Meta may already be roughly comparable with Google Search on a like-for-like basis, excluding certain Google businesses.
Granted, surpassing Search revenue by year-end isn’t guaranteed. Google is also using AI to strengthen Search, with AI Overviews and AI Mode contributing to a business that still grew 17% in Q2.
Key Takeaway
Meta’s AI strategy is becoming less about futuristic promises and more about advertising economics. The company spent $31.1 billion on capital expenditures in Q2 alone, while free cash flow fell to just $784 million as infrastructure and other costs surged. That’s a real risk if AI spending doesn’t keep producing returns.
But the evidence is moving in Meta’s favor. Advertising revenue is growing 27%, Advantage+ is running at a $60 billion annualized pace, and Bernstein says Meta captured nearly half of incremental digital ad spending. If that trajectory continues, Meta doesn’t need to kill Google Search to win. It only needs to grow faster — and the numbers suggest it may already be doing exactly that.
The post Meta’s $60 Billion AI Machine Could Dethrone Google Search by Year-End appeared first on 24/7 Wall St..
]]>Investors who pick growth ETFs based solely on expense ratio are optimizing the least important variable in 2026. Vanguard Growth ETF (NYSEARCA:VUG) charges an ultra-low 0.03%, while Vanguard S&P 500 Growth ETF (NYSEARCA:VOOG) costs 0.07%, yet VOOG has been the better performer year to date and over the trailing 12 months.
Year to date, VOOG has returned roughly 14%, compared with about 10% for VUG, a gap wider than four basis points of fees could explain. Over the trailing twelve months, VOOG is up about 22%, compared with roughly 16% for VUG. Both funds hold roughly 150 mega-cap growth names, so the divergence stems from how the underlying indexes weight the shared holdings.
Same Universe, Different Rulebooks
VUG tracks the Morningstar US Large Cap Growth Index while VOOG follows the S&P 500 Growth Index, drawing only from S&P 500 constituents classified as growth. The overlap in top holdings is heavy, but individual weights differ meaningfully.
NVIDIA (NASDAQ:NVDA) accounts for 13.3% of VUG and nearly 14.3% of VOOG, while Apple (NASDAQ:AAPL) accounts for 12.3% of VUG and only 6.4% of VOOG. Broadcom (NASDAQ:AVGO) shows up at 5.9% in VOOG versus 4.4% in VUG, and Microsoft (NASDAQ:MSFT) is close to a tie at 9.1% in VUG and 9.3% in VOOG. Those single-digit weighting gaps compound across the largest positions in both portfolios.
Why Apple’s Weight Matters
VUG’s roughly double Apple weight has been a drag in 2026, as Apple has lagged the AI-heavy names that dominate both indexes. VOOG’s lighter Apple exposure freed capacity that its methodology reallocated toward Nvidia and Broadcom, two of this year’s biggest semiconductor winners (we profiled seven companies powering that same AI buildout, beyond the chipmakers, in a free report you can grab here).
The software megacaps sit at similar weights in both funds, with Microsoft effectively tied and Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) exposure broadly comparable. VOOG’s index holds more of what worked and less of what did not, purely because of how S&P’s growth score ranks constituents. That methodological outcome explains why a five-point return gap opens between two Vanguard funds that look nearly identical.
Is VOOG’s Edge Repeatable?
The tempting conclusion is that VOOG will keep winning, but the more defensible answer is that its lead is period-specific. The S&P 500 Growth methodology leans on momentum and earnings signals, which tilt toward whichever megacaps have run the hardest.
In years where Apple leads or a battered software name recovers, VUG’s broader Morningstar universe will likely narrow the gap or reverse it. Over five years, the funds are much closer, with VOOG up roughly 88% and VUG up about 80%, a spread that reflects normal drift rather than a permanent structural advantage. Anyone betting on VOOG to keep beating VUG is really betting that the current AI concentration will continue to pay off, which is a call on the market itself.
Portfolio Fit and the Fee Illusion
VOOG suits an investor who wants US large-cap growth filtered through the S&P 500’s quality screen and is comfortable with heavier semiconductor exposure. VUG fits someone who wants a slightly broader growth net and values the fee savings on large balances, accepting that heavier Apple weight will hurt in years like this one.
Holding both is redundant given the overlap at the top, so most investors should pick one as their core growth sleeve. Scale still favors VUG, which dwarfs VOOG’s $26.5 billion in net assets and continues to gather flows despite recent performance lag. Four basis points of fee savings cannot overcome a five-point return gap driven by index construction.
The post VUG vs. VOOG Is Not a Fee Fight | How the Cheaper Vanguard Growth ETF Is Losing appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) both reported Q2 2026 results in late July. Alphabet extended its EPS-beat streak to 11 consecutive quarters while Cloud lit up. Meta cleared revenue but snapped a six-quarter EPS beat streak as AI spending and legal charges chewed through margins.
Cloud Momentum Powers Google, Ad Costs Weigh on Meta
Alphabet posted $119.8 billion in revenue, up 24.23% year over year, with Google Cloud revenue growing 82% to $24.8 billion and cloud backlog reaching $514 billion. Sundar Pichai said “Q2 was an amazing quarter”, and the numbers back him up. Search still grew 17% even as AI Overviews cannibalized traditional queries, which is a real tell about durability.
Meta grew revenue 27.96% to $60.80 billion, but EPS came in at $6.18 against a $7.221 estimate. Total expenses jumped 55% year over year, weighed down by $2.40 billion in legal charges and $1.18 billion in severance tied to an 8,000-employee reduction. Ad impressions rose 14% and price per ad rose 12%, so the core engine still hums.
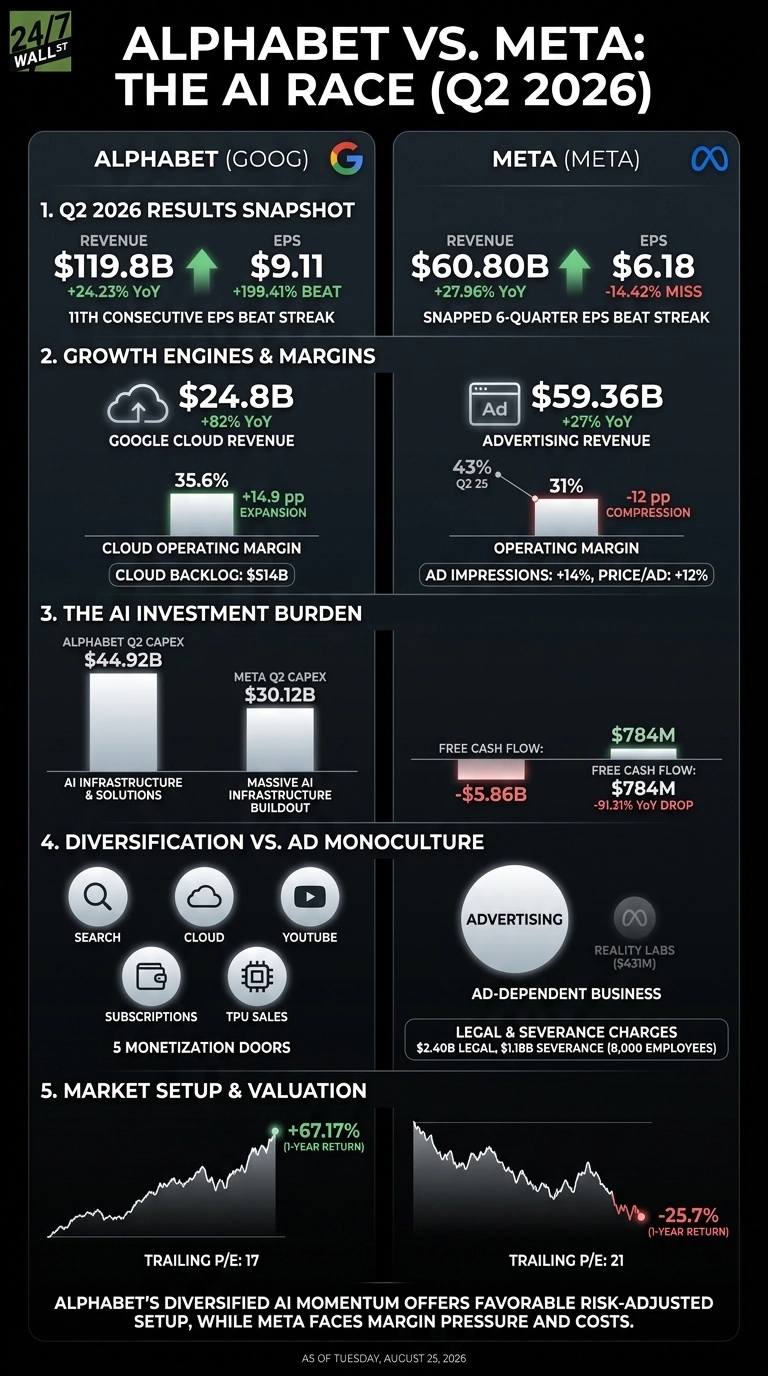
| Business Driver | Alphabet | Meta |
| Main growth engine | Google Cloud + AI infrastructure | AI-optimized ad targeting |
| Operating margin | 34%, expanding | 31%, down from 43% |
| Q2 CapEx | $44.92 billion | $30.12 billion |
Diversified Portfolio vs. Advertising Monoculture
Alphabet is monetizing AI through five distinct doors: Search, YouTube, Cloud, subscriptions, and TPU system sales. Nearly 90% of the Fortune 100 use Gemini Enterprise, and Pichai said Alphabet is “in very early innings” of the shift. Cloud operating margin actually reached 35.6%, versus 20.7% a year ago. That is unusual for a business absorbing this much capacity.
Meta remains overwhelmingly an ads business. Reality Labs contributed only $431 million. Zuckerberg is betting the buildout unlocks personal agents, business agents, and API revenue, saying “we believe that there will continue to be a significantly higher margin on selling intelligence rather than selling compute directly.” Ambitious. Unproven at scale. Free cash flow tells the story: Meta produced just $784 million, down 91.31%.
What Decides the Next Four Quarters
I will be watching whether Alphabet can absorb fiscal 2026 CapEx of $175 billion to $185 billion without cracking Cloud margins, since third-party capacity use will pressure them.
For Meta, the number that matters is full-year 2026 CapEx of $130 to $145 billion paired with $165 to $169 billion in total expenses. Meta needs its ad engine to keep compounding at 27% to fund that arithmetic. All of that CapEx has to be powered, cooled, and networked by somebody, and we pulled together seven of those suppliers in a free AI infrastructure report.
Where the Setup Favors Alphabet After This Quarter
The risk-adjusted setup currently reads more favorably for Alphabet. Cloud is accelerating, Search is proving AI-resilient, and shares are up 67.17% over one year on a 17 trailing P/E.
Meta is down 25.7% over the past year at a 21 P/E, a valuation that turnaround-oriented investors may find worth researching. The variables to watch: whether Meta’s margins stabilize by Q4 and whether the legal overhang clears.
The post Alphabet vs. Meta: One AI Giant Looks More Attractive appeared first on 24/7 Wall St..
]]>
The artificial intelligence boom is entering a different phase. The early winners sold the picks and shovels, but the next leg of the cycle will depend on who can turn enormous AI spending into recurring revenue. That makes 2027 especially interesting.
Alphabet‘s (NASDAQ:GOOG) latest results show why. The company is no longer simply buying AI infrastructure from others and hoping its software catches up. It is designing chips, building data centers, developing models, selling cloud services, and distributing AI through products used by billions of people. That vertical integration could become one of its biggest competitive advantages.
Wall Street Sees a Bigger Cloud Opportunity
Wolfe Research has named Alphabet one of its top picks for 2027, and the numbers explain the enthusiasm. Analyst Shweta Khajuria expects Google Cloud Platform revenue growth of 125% in the third quarter, compared with an 87% consensus estimate. Wolfe also raised its 2027 Alphabet revenue forecast 10% to $595 billion and its earnings-per-share estimate 6% to $15.89.
Those estimates build on a business already accelerating. Alphabet’s second-quarter earnings release showed Google Cloud revenue jumped 82% year over year to $24.8 billion, while its backlog reached $514 billion. Cloud operating margin also expanded to 35.6% from 20.7% a year earlier.
To put that in perspective, cloud is no longer a side business supporting Google’s advertising empire. It is becoming an increasingly important engine for monetizing AI.
Google Is Owning the AI Stack
The more interesting story is how Alphabet gets there. Most companies participating in AI own only pieces of the stack. Alphabet increasingly owns the whole thing.
It designs its own Tensor Processing Units (TPUs), which power Gemini and are now being sold directly into customers’ data centers. Alphabet began recognizing revenue from those external TPU systems in the second quarter, with most of the revenue expected to arrive in 2027. One industry forecast projects TPU shipments could triple from 2.76 million units in 2024 to 8.8 million in 2027.
Then comes the software. Alphabet’s model APIs were processing approximately 22 billion tokens per minute in the second quarter, up from 16 billion just three months earlier. More than 9 million developers were using its models each month, while 950 million people were active on the Gemini app.
That creates a powerful loop: Alphabet builds the chips, uses them to train and run its models, sells the computing capacity through Cloud, and then monetizes those models through enterprise software and consumer products.
In short, Google is not merely participating in the AI economy. It is building much of the machinery that powers it.
The Cost of Winning Is Still High
Granted, vertical integration does not make Alphabet immune to AI’s biggest risk: spending.
Alphabet expects 2026 capital expenditures of $195 billion to $205 billion, while Wolfe estimates 2027 spending could reach $330 billion. The company also generated negative $5.9 billion of free cash flow in the second quarter as infrastructure investment accelerated. That is a lot of money to spend before investors see the payoff.
But there is an important offset. Google’s $514 billion Cloud backlog provides evidence that at least some of this infrastructure is being built against real customer demand rather than speculative capacity. And selling TPUs outside Google’s own data centers creates another revenue stream from infrastructure that previously benefited Alphabet primarily through internal cost savings.
Alphabet’s stock also isn’t priced like an early-stage AI company. Wolfe’s $460 price target represents a substantial premium to its current price, while its latest 2027 earnings forecast implies the potential for meaningful earnings growth to accompany the AI investment cycle.
Key Takeaway
Wolfe may be early in calling Alphabet 2027’s best stock, but the thesis is becoming easier to understand.
Alphabet has Search and YouTube generating enormous cash flows, Cloud growing 82%, Gemini processing 22 billion tokens per minute, and TPUs moving from an internal advantage to an external product. Alphabet can monetize AI at multiple layers instead of depending on a single application or chip.
There are no guarantees that $330 billion of annual capital spending will earn attractive returns. That said, the evidence increasingly suggests Alphabet has something many AI competitors lack: control of the stack from silicon to software to distribution.
For investors looking beyond the next quarter, that could make GOOGL one of the most compelling AI bets heading into 2027.
The post This Analyst Just Called Alphabet 2027’s Best Stock. She Might Be Right appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ: GOOG), especially its Google unit, has had a remarkable year, at least compared to the other Magnificent Seven companies. Its stock price is up 10% this year. That’s not a home run, but it’s better than Meta (NASDAQ: META) (down 15%) and Tesla (NASDAQ: TSLA) (down 22%).
Alphabet ranks third in market cap among the world’s public companies at $4.21 trillion, which is close behind Apple ($4.53 trillion). Founder Sergey Brin owns 3% but has shares that give him control of the company, along with Larry Page, who also owns 3%. Each has a net worth increase of slightly more than $25 billion this year.
Google’s search business is supposed to be crippled by AI, which is often used as a search engine. Alphabet’s overall revenue rose 24% to $119.8 billion in the most recent quarter. Google Search revenue rose 17% to $63.2 billion. Cloud operations were a home run, up 81% to $21.7 billion. Since the cloud industry is nearly as hot as AI among investors, the increase impressed.
YouTube is now the clear leader in video streaming and has moved into the premium streaming sector, threatening companies like Netflix (NASDAQ: NFLX). YouTube revenue rose 13.2% to $11.1 billion in the period. In its most recent quarter, Netflix’s entire revenue was $12.5 billion.
Google’s Gemini AI business has outpaced many estimates for other public companies and trails only OpenAI and Anthropic. The Guardian reports: “The source added, however, that Google still had the benefit of being able to combine its Gemini models with an impressive suite of products, from its all-conquering search product to its cloud platform and YouTube.”
On a much smaller scale, Google’s self-driving car division, Waymo, appears to have taken the lead over rival Tesla, particularly in the cities where it operates. This may matter in the future, but today, financially, it is only a small part of Google’s current success.
Brin and Page are each worth about $280 billion based on the Bloomberg Billionaire Index. Unlike some other people at the top of the list, 2026 has been a good year.
The post Google’s Wins Make Founders Brin And Page $50 Billion Richer appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) has become the billionaire trade of 2026. Recent 13F cycles show Warren Buffett was far from the only billionaire buying Alphabet stock in Q2, joining Bill Ackman and Stanley Druckenmiller rotating into the search giant.
Our 24/7 Wall St. price target for Alphabet is $437.39, implying 27.99% upside from the current $341.75 share price. The model rates GOOG a buy with 90% confidence.
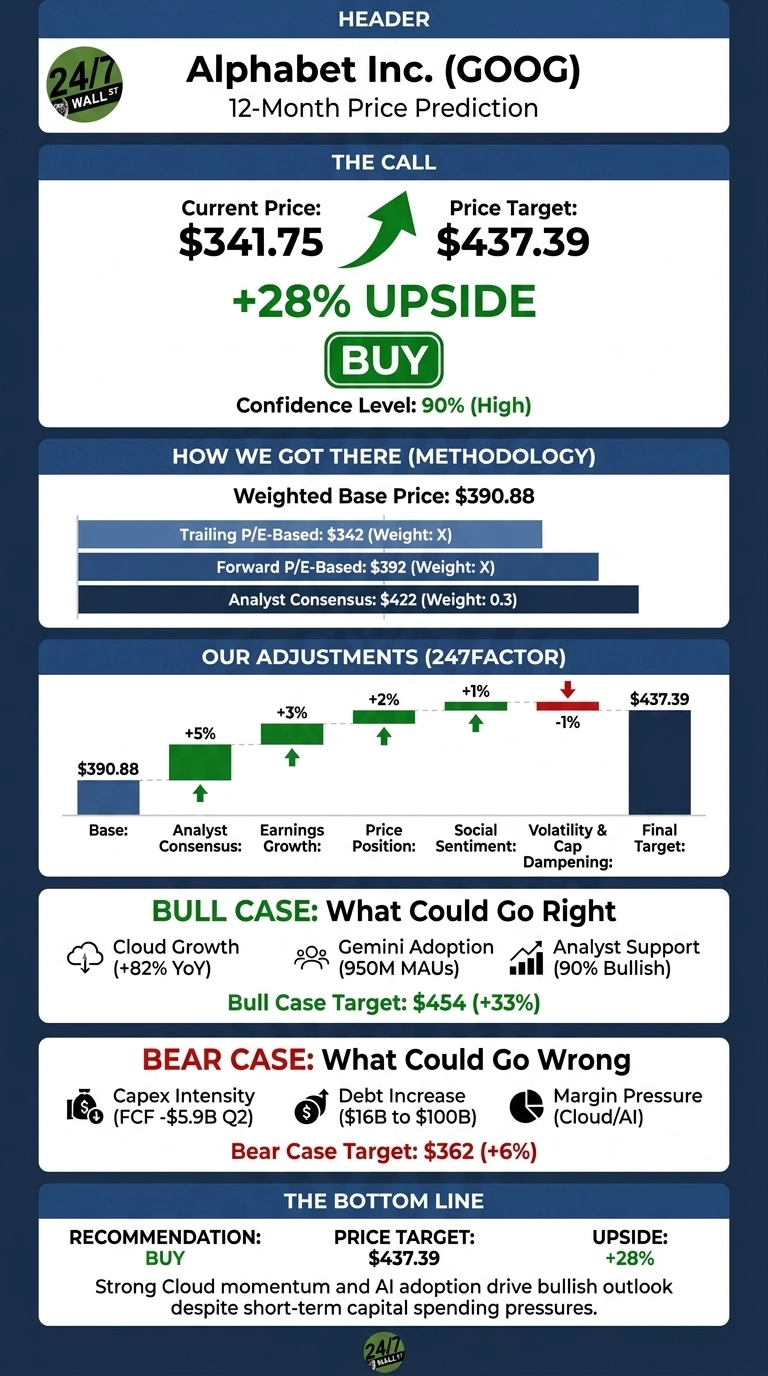
| Metric | Value |
|---|---|
| Current Price | $341.75 |
| 24/7 Wall St. Price Target | $437.39 |
| Upside | 27.99% |
| Recommendation | BUY |
| Confidence Level | 90% |
Cloud Acceleration and Billionaire Buying Set the Backdrop
GOOG gained 70.83% over the trailing year against 9.05% year-to-date, though shares consolidated recently, off 0.52% over the past week.
The Q2 FY2026 report delivered $119.80 billion in revenue, up 24.23% year over year, with EPS of $9.11 against a $3.04 estimate. Google Cloud accelerated to 82% growth with $24.8 billion in revenue and a 35.6% operating margin, while cloud backlog hit $514 billion. This backdrop explains why multiple billionaires are piling in.
Bull Case: A Path Toward $454
Bulls see a $454.48 upside scenario, roughly 33% above spot. Google Cloud is compounding, with nearly 90% of the Fortune 100 using Gemini Enterprise. The Gemini App has 950 million monthly active users, and API traffic scaled to 22 billion tokens per minute, up from 16 billion just a quarter earlier.
TPU system sales, Waymo’s 500,000+ weekly rides, and 350 million paid subscriptions add optionality. On the sell side, 13 strong buys, 44 buys, 6 holds, and zero sells form one of the cleanest analyst books in mega-cap tech.
Bear Case: What Could Drag GOOG to $362
The bear scenario points to $361.62, essentially flat to today. The chief concern is capex intensity. Q2 free cash flow ran to negative $5.855 billion, with capex up 100.14% year over year to $44.92 billion. Long-term debt climbed from roughly $16 billion a year ago to about $100 billion, buybacks were suspended, and CFO Anat Ashkenazi warned third-party capacity will “put some pressure on operating margins for cloud.”
Bulls counter that this spending funds a supply-constrained AI backlog, so the free-cash-flow drop reads as strategic reinvestment (and it is worth remembering the picks-and-shovels names on the other side of that spending, which we broke down in a free report on seven AI infrastructure suppliers that aren’t chipmakers).
How Alphabet Compares to Microsoft and Meta
Alphabet screens cheap against Magnificent Seven peers on trailing earnings. Microsoft (NASDAQ:MSFT) fetches a trailing P/E of roughly 27, backed by Azure crossing $100 billion in annual revenue and a $678 billion commercial RPO backlog. That backlog rivals Alphabet’s $514 billion, yet MSFT trades at nearly double the multiple.
Meta Platforms (NASDAQ:META) sits at P/E near 20, but Q2 EPS missed expectations on a cost surge, and Reality Labs remains a multi-billion drag. Against this set, GOOG’s P/E of 14 makes our 24/7 Wall St. price target look conservative.
| Company | Trailing P/E | Recent Quarter Revenue Growth |
|---|---|---|
| Alphabet | 14 | 24.23% |
| Microsoft | 27 | 17.75% |
| Meta | 20 | 27.96% |
Bottom Line: Why the Billionaire Trade Has Legs
Our 24/7 Wall St. price target of $437.39 offers GOOG one of the cleanest risk/reward setups in mega-cap tech, well above the bear scenario. The constructive path requires free cash flow stabilizing in H2 2026 and cloud margins holding above 30%.
The risk case builds if capex creeps beyond $175 to $185 billion 2026 guidance without a clear TPU revenue ramp in 2027. The buy call carries 90% confidence.
Here is where our model projects GOOG could trade, assuming current growth trajectories and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $437 |
| 2027 | $523 |
| 2028 | $584 |
| 2029 | $660 |
| 2030 | $699 |
These projections assume Alphabet executes on its AI-first strategy. Significant upside or downside could result from Waymo commercialization, antitrust remedies in Search, or a sharper-than-expected step-down in AI capex intensity.
The post 3 Billionaire Investors Just Bought the Same Stock. Should You? appeared first on 24/7 Wall St..
]]>Alphabet (NASDAQ:GOOG) has moved from quietly designing its own AI chips to openly staking its cloud roadmap on them. A recent forecast from GF Securities Brokerage now suggests Google’s next-generation Tensor Processing Units could see shipment volumes more than triple by 2027, a scale-up that would reshape how investors think about the AI compute stack.
Tripling TPU Shipments by 2027
Based on the brokerage’s build, TPU shipments could rise from 2.76 million units in 2024 to 2.854 million in 2025, then accelerate to 4.504 million in 2026 and 8.84 million in 2027. That implies roughly 3.2 times growth over three years, with the steepest jump landing in the final year of the projection.
The curve is driven by a generational transition. v7 (Ghostfish) begins contributing, followed by higher volumes of v8AX (Sunfish/Hellcat) and v8x (Zebrafish/Maddog). The shift from older generations to these nodes is meant to deliver better performance-per-watt and more scalable capacity for both training and inference.
Why Custom Silicon Matters for Google
Running search, ads, YouTube, and Cloud at Alphabet’s scale makes owning the chip design a durable cost lever. On the Q2 call, management said it was “very pleased with our TPU roadmap progress and the value in terms of performance and the edge it gives.” Alphabet began recognizing revenue from TPU system sales delivered to customer data centers for the first time in Q2 2026, with the vast majority of revenue from those agreements expected in 2027. Demand context is already extreme: Google Cloud backlog hit $514 billion, and Gemini models now process 22 billion API tokens per minute.
Capex Is Already Reflecting the Buildout
Q2 2026 capex hit $44.9 billion, up 100.14% year over year, with roughly 60% flowing into servers and 40% into data centers and networking. CEO Sundar Pichai told investors 2026 capex would land at $175 to $185 billion. To fund it, Alphabet raised roughly $70 billion in combined equity and debt, pushed long-term debt from $46.5 billion to $98.2 billion, and suspended the stock buyback.
Risks and What to Watch
This is one analyst’s model and Google has not itself committed to those numbers, though other estimates also point to multi-million-unit growth into 2027 and 2028. Pichai flagged a “supply constrained environment” and said Alphabet will lean on third-party capacity in Q3 2026 while its own capacity comes online. Free cash flow already turned to negative $5.9 billion, and interest expense rose nearly 5x year over year. With GOOG up 67.17% over the last year, the stock is pricing in execution. If Alphabet masters the supply chain, its vertical integration and data center head start could make TPUs a genuine surprise through 2027 (and the power, cooling, and networking suppliers riding the same buildout are the subject of a free report we put together here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
The post Google TPU Volume Could Triple to 8.8 Million by 2027 appeared first on 24/7 Wall St..
]]>Berkshire Hathaway’s roughly $37 billion stake in Alphabet, disclosed as a 48 million share position, has recalibrated how investors view the search giant. Warren Buffett rarely chases mega-cap tech, so his conviction here forces a fresh look at whether Alphabet (NASDAQ:GOOG) still offers meaningful upside from $344.59.
Our 24/7 Wall St. price target for Alphabet is $437.39 over the next 12 months, implying 27.99% upside. We rate GOOG a buy with high (90%) confidence.
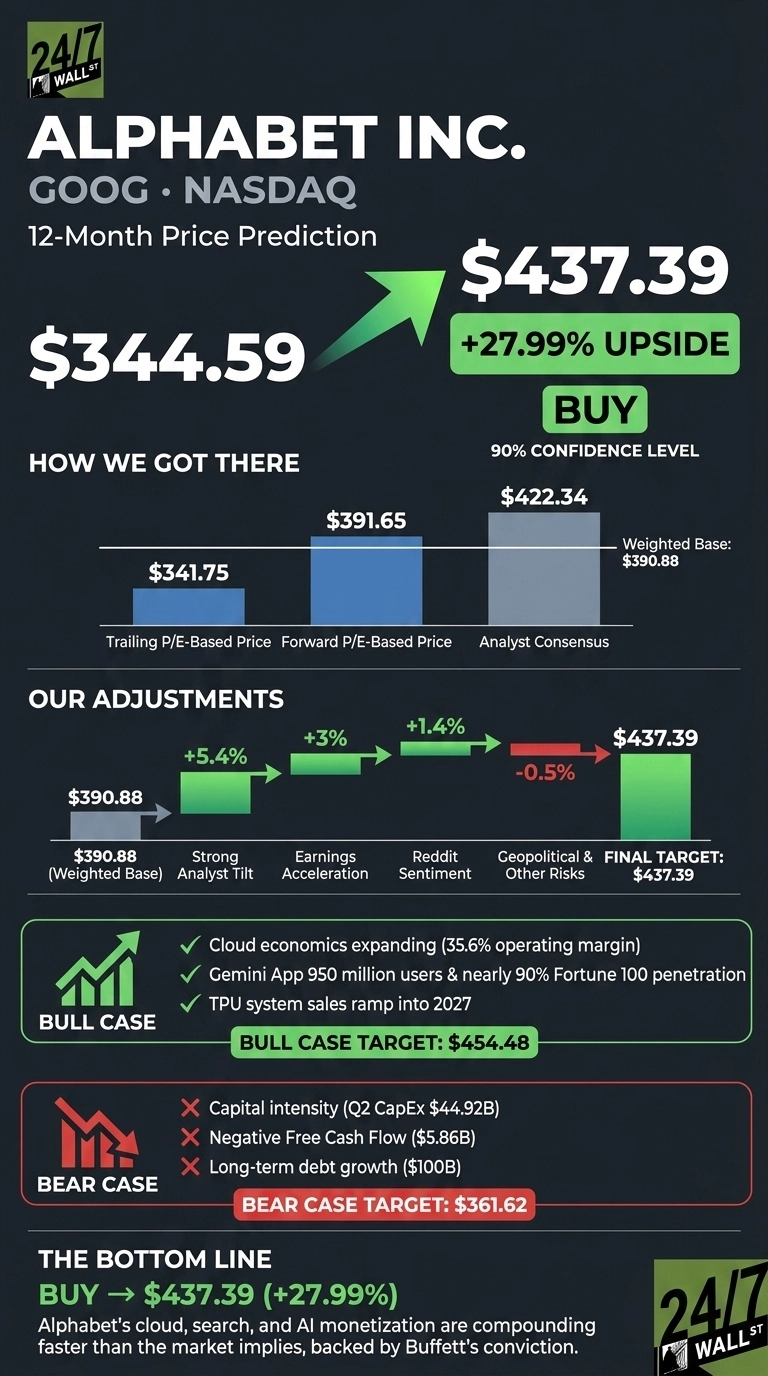
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $344.59 |
| 24/7 Wall St. Price Target | $437.39 |
| Upside | 27.99% |
| Recommendation | BUY |
| Confidence Level | 90% |
What Alphabet’s Post-Earnings Melt-Up Tells Us
GOOG has climbed 7.99% in the past month and 67.17% over the past year, though shares sit below the $404.23 52-week high.
The catalyst was a landmark Q2. Alphabet posted EPS of $9.11 against a $3.042 estimate, and revenue of $119.8 billion, up 24.23% year over year. Google Cloud accelerated to 82% growth and backlog swelled to $514 billion. Buffett’s disclosure validated the view that even at a $4 trillion market cap, GOOG trades at a reasonable multiple relative to its cash-generation engine.
Why Bulls See a Breakout Ahead
The bull case rests on cloud economics. Google Cloud operating margin expanded from 20.7% to 35.6% year over year, and management said just over 50% of that $514 billion backlog converts to revenue within 24 months.
Gemini App’s 950 million monthly users and Fortune 100 penetration of nearly 90% show Alphabet monetizing AI at scale peers cannot yet match. Our bull scenario puts GOOG at $454.48 within 12 months if TPU system sales ramp as guided into 2027.
What Could Go Wrong
The bear thesis centers on capital intensity. Q2 CapEx hit $44.92 billion, free cash flow swung to negative $5.86 billion, long-term debt climbed to roughly $100 billion from $16 billion a year earlier, and the buyback was suspended.
2026 CapEx guidance of $175 billion to $185 billion is substantial, and every dollar of it flows to the power, cooling, and networking suppliers behind the data centers (we profiled seven of them in a free AI infrastructure report). Bulls counter that this reflects a supply-constrained cloud opportunity backed by contracted demand. Our bear scenario points to $361.62 if AI ROI slips.
How Alphabet Compares to Microsoft and Meta
Microsoft (NASDAQ:MSFT) is the natural cloud comparison. MSFT trades at a P/E of 27 with a P/FCF of 54, versus GOOG’s leaner trailing multiple. Azure crossed $100 billion in annual revenue and Copilot passed 30 million paid seats, but investors already pay a premium for that.
Meta Platforms (NASDAQ:META) is the ad-market comparable. META carries a P/E of 20 and Q2 revenue growth of 27.96%, but its Q2 EPS missed by 14.42% and free cash flow collapsed to $784 million. Alphabet’s advertising engine grows at similar rates with cleaner monetization. Against this peer group, our 24/7 Wall St. price target looks reasonable.
| Company | P/E | Q2 Revenue Growth |
|---|---|---|
| Alphabet | 17 | 24.23% |
| Microsoft | 27 | 17.75% |
| Meta | 20 | 27.96% |
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target of $437.39 with 90% confidence reflects a company where cloud, search, and AI monetization compound faster than the multiple implies.
The setup strengthens if Google Cloud sustains 60%-plus growth and TPU revenue ramps in 2027. It weakens if CapEx keeps outpacing operating cash flow into next year. On balance, Buffett’s conviction and the numbers align.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $369 |
| 2027 | $453 |
| 2028 | $548 |
| 2029 | $614 |
| 2030 | $658 |
These projections assume Alphabet continues executing on cloud, search AI integration, and Waymo scaling. Meaningful upside or downside could result from an AI infrastructure ROI shock or a regulatory outcome in the Search antitrust remedy phase.
The post Buffett Just Made a $37 Billion Bet on This Tech Giant. Should You Buy? appeared first on 24/7 Wall St..
]]>
The artificial intelligence boom is turning corporate capital spending into a different kind of arms race. The biggest cloud companies aren’t merely adding data centers as demand grows; they’re building infrastructure years ahead of expected usage.
UBS now estimates hyperscaler capital expenditures could reach about $4.1 trillion from 2026 through 2028. That’s more than three times the $1.292 trillion spent across the previous six years, based on UBS’s hyperscaler spending estimates. For investors, the message is clear: AI is pushing the industry’s long-term spending base into territory that would have looked absurd just a few years ago.
Cloud Revenue Tells The Story
UBS estimates Amazon (NASDAQ:AMZN), Alphabet (NASDAQ:GOOG), and Microsoft (NASDAQ:MSFT) will collectively spend about 102% of their cloud revenue on capital expenditures in 2026.
That doesn’t mean these companies are burning through more cash than they generate. Their businesses are much larger and more diversified than cloud infrastructure alone. Instead, the ratio shows how aggressively cloud revenue is being recycled into AI infrastructure.
UBS expects that ratio to ease to roughly 99% of cloud revenue in 2027 and 94% in 2028. Yet spending keeps rising.
UBS projects total hyperscaler capex at $492 billion in 2025, $1.009 trillion in 2026, $1.447 trillion in 2027, and $1.619 trillion in 2028 — three times more in three years than in the previous six years combined. It shows how the growth rate can slow while the dollar amount continues climbing.
And the composition matters, too. Amazon, Alphabet, Microsoft, and Meta Platforms (NASDAQ:META) account for the largest portions of the buildout, but SpaceX (NASDAQ:SPCX) is making up for lost time, and Oracle (NYSE:ORCL), neocloud providers, and newer entrants are expanding the spending pool.
That means the AI infrastructure opportunity is spreading beyond the handful of companies investors typically associate with the boom.
$4.1 Trillion Is A Bigger Bet Than It Looks
The cumulative UBS estimates for 2026 through 2028 are staggering:
| Company | 2026-2028 Capex |
| Alphabet | ~$938 billion |
| Meta Platforms | ~$683 billion |
| Microsoft | ~$672 billion |
| Amazon | ~$628 billion |
| SpaceX | ~$335 billion |
| Oracle | ~$276 billion |
| CoreWeave (NASDAQ:CRWV) | ~$130 billion |
| Nebius Group (NASDAQ:NBIS) | ~$93 billion |
Together, those figures illustrate why this isn’t simply another upgrade cycle for servers. New demand is coming from traditional hyperscalers, neocloud providers, and SpaceX, creating additional pools of infrastructure spending.
For chipmakers, networking companies, data-center power suppliers, and infrastructure operators, the spending becomes revenue somewhere in the supply chain.
More importantly, the UBS forecast suggests the spending isn’t peaking when the growth rate peaks. Total hyperscaler capex rises from $1.009 trillion in 2026 to $1.619 trillion in 2028. In other words, the industry could be spending more than $1.6 trillion annually even after the initial acceleration begins to moderate.
That’s what makes this different from a normal technology upgrade. AI could reset the industry’s capital requirements at a permanently higher level.
The Risk Is Spending Without Returns
Granted, $1.619 trillion of annual hyperscaler capex by 2028 creates a formidable hurdle. Companies eventually need AI revenue and cash flow to justify those investments.
That’s where investors should remain selective. A data center doesn’t generate attractive returns merely because it contains expensive GPUs. Capacity has to stay utilized, customers have to pay for it, and AI services have to produce enough revenue to cover depreciation, electricity, financing, and operating costs.
There is also a timing risk. Companies can spend billions today on infrastructure that may take years to reach full utilization. If AI demand grows more slowly than expected, depreciation expenses could rise faster than revenue, pressuring margins and free cash flow.
That said, the scale of the commitment from multiple customers reduces the risk that this is simply one company’s speculative bet. Amazon, Alphabet, Microsoft, Meta, SpaceX, Oracle, and the neoclouds are collectively building an ecosystem around AI compute.
In short, the spending itself isn’t the investment thesis. The investment thesis is that AI demand becomes large enough to keep this infrastructure productive for years.
UBS’s numbers suggest the major cloud platforms are betting heavily that it will. Smart investors don’t have to match their conviction blindly. They should follow the money — and favor companies positioned to monetize the buildout rather than simply finance it.
Key Takeaway
The 102% figure is less a warning about reckless spending than a measure of how radically AI is changing the cloud economy. With UBS projecting roughly $4.1 trillion of hyperscaler capex from 2026 through 2028, investors should expect AI infrastructure spending to remain a dominant market theme well beyond the current boom.
The opportunity is strongest where spending translates into recurring revenue, high utilization, and durable free cash flow. In the end, the winners won’t necessarily be the companies spending the most. They’ll be the ones turning that unprecedented spending into the highest returns on capital.
The post AI’s Absurd Spending Boom? Hyperscalers Are Spending 102% of Cloud Revenue on Capex appeared first on 24/7 Wall St..
]]>
Every bull market eventually asks investors to squint past a number they’d rather not look at. In 2000, it was cash burn rates at dot-coms with no revenue. In 2008, it was mortgage-backed securities nobody could quite value. Today, it’s the financing behind the AI buildout — and specifically, how much of it never shows up on a balance sheet at all.
For most of 2026, the story was that Big Tech’s free cash flow couldn’t keep pace with AI capital expenditures. Then it became a story about off-balance-sheet arrangements. Now, thanks to new reporting, the number attached to that second story has nearly doubled.
From $1.65 Trillion to $3 Trillion in Six Weeks
In July, Nikkei estimated that Microsoft (NASDAQ:MSFT), Amazon (NASDAQ:AMZN), Alphabet (NASDAQ:GOOG), Meta Platforms (NASDAQ:META), and Oracle (NYSE:ORCL) were carrying roughly $1.65 trillion in obligations that don’t appear as debt on their balance sheets — mostly future spending tied to data centers, chips, and power. That was startling enough. But a Wall Street Journal analysis published this month found the real figure across nine companies — those five plus Nvidia (NASDAQ:NVDA), Broadcom (NASDAQ:AVGO), Advanced Micro Devices (NASDAQ:AMD), and SpaceX (NASDAQ:SPCX) — sits closer to $3 trillion, based on filings mostly current through June 2026.
That’s not a rounding error. It’s the difference between a concerning trend and a systemic one. The Journal’s breakdown shows roughly $1.9 trillion in purchase commitments — contracts to buy chips, servers, and hardware from suppliers — plus another $1.2 trillion in leases that have been signed but haven’t yet commenced, meaning they still sit outside reported balance-sheet liabilities. Alphabet alone disclosed $811 billion in purchase commitments and contractual obligations as of June 30, up from $322 billion just three months earlier. That’s a 152% jump in a single quarter.
Here’s the number that should give investors pause: this $3 trillion is roughly triple what these same companies currently report as outstanding leases and long-term borrowings on their actual balance sheets. And it’s growing faster than traditional capex, which totaled about $600 billion over the trailing year. In short, the shadow ledger is expanding faster than the visible one.
Where the Debt Is Hiding
It is important to remember none of this is accounting fraud. It’s standard treatment for purchase commitments and unstarted leases, which accounting rules don’t require companies to book as liabilities until the underlying asset or service goes live. The risk isn’t legality — it’s timing and visibility.
Some of it is getting creative. Meta’s Hyperion data-center project in Louisiana carries about $27 billion in debt that never touches Meta’s balance sheet, because funds managed by Blue Owl Capital (NYSE:OBDC) own the majority of the joint venture that owns the campus. Meta is just the tenant and a minority partner.
Vendor financing works similarly — suppliers extend credit, or buy back equipment through repurchase-style arrangements, but a problem at a single counterparty can ripple across several balance sheets at once. It is called “rehypothecated leverage:” the same underlying capacity, financed and re-financed across multiple books.
| Metric | Figure |
| Total off-balance-sheet commitments | ~$3 trillion |
| Purchase commitments | ~$1.9 trillion |
| Unstarted leases | ~$1.2 trillion |
| Reported on-balance-sheet leases/debt | ~$1 trillion |
| Trailing 12-month capex | ~$600 billion |
Disclosure is inconsistent, too. Nvidia quantified $30 billion of cloud-service commitments and Oracle disclosed $10 billion, while Meta declined to quantify the cloud-capacity portion of its $238 billion in commitments. That inconsistency means comparing “true” leverage across companies rests on differing materiality judgments — the aggregate numbers, large as they are, remain uncertain.
What Investors Should Actually Watch
These companies aren’t about to go bankrupt. Instead, it’s a set of timing mismatches. Depreciation on this spending is deferred — construction-in-progress balances at Oracle and Meta are up roughly 200% and 90% year-over-year, respectively — and when it finally lands, cumulative depreciation across Microsoft, Oracle, Meta, and Alphabet could exceed $520 billion over three years. That could push Oracle’s depreciation as a share of revenue from 7% toward 28%, and Meta’s from 9% toward 19%, by fiscal 2028. Margins can only hold up if revenue rises to match — and so far it hasn’t kept pace.
That question gets more complicated, not less, if demand shifts toward cheaper Chinese models delivering roughly 90% of frontier performance at a fraction of the cost. For example, Microsoft holds a stake in OpenAI worth tens of billions of dollars, and Amazon and Alphabet have each committed billions to Anthropic. Nvidia is discussing $3 billion in an Ohio data center as part of its OpenAI agreement, and launched a new $500 billion financing platform with six institutions for AI infrastructure.
A pivot toward discount alternatives doesn’t just threaten hyperscaler revenue from external customers — it undercuts the equity stakes and circular purchasing arrangements that helped justify the spending in the first place. Pull one thread, and the sweater unravels faster than a standalone-demand story alone would suggest.
Key Takeaway
Smart investors shouldn’t panic, but they should stop pricing these stocks as if capex were the whole picture. The $3 trillion figure means real leverage is roughly triple what balance sheets show, concentrated in a handful of long-duration supplier contracts, and inconsistently disclosed enough that no analyst can fully size it.
The key will be free cash flow relative to committed spending, not just reported debt — that’s where the real risk to Microsoft, Amazon, Alphabet, Meta, and Oracle shareholders is actually building.
The post Alphabet, Meta, and Microsoft Are Hiding $3 Trillion in Debt On the AI Boom’s Hidden Ledger appeared first on 24/7 Wall St..
]]>
AI infrastructure spending is moving into a new phase. The first wave centered on buying as many GPUs as possible. Now hyperscalers are designing custom chips, networking systems, and memory architectures to squeeze more performance from every dollar and watt. Alphabet (NASDAQ:GOOG) is one of the companies pushing hardest in that direction. The company spent $80.6 billion on capital expenditures during the first six months of 2026, with servers, networking equipment, and data centers accounting for much of that investment.
That creates an enormous opportunity for Marvell Technology (NASDAQ:MRVL). But its latest deal with Google comes with a twist: Marvell is offering Google a potential 7% stake in the company — but Google has to earn it.
Google Gets The Shares By Spending Money
On Aug. 18, Marvell issued Google a warrant for up to 58.97 million shares at an exercise price of $206.58 per share. If fully exercised, those shares would be worth about $12.2 billion and represent roughly 6.3% to 6.7% of Marvell, depending on the company’s eventual share count. Reuters reported that Google could become Marvell’s fifth-largest shareholder if the warrants fully vest.
Here’s the important part: Google doesn’t receive those shares upfront. Most of the warrant is tied to Google’s future purchases of Marvell’s custom silicon through fiscal 2033. The structure effectively makes the equity compensation contingent on Marvell generating revenue from the partnership. The shares vest in connection with qualifying revenue milestones, including $500 million increments of custom-product revenue.
In other words, Google gets more Marvell stock when Marvell gets more Google business. That’s a clever alignment of incentives.
Marvell Is Expanding Beyond One AI Chip
The arrangement is also significant because it expands Marvell’s role in Google’s AI infrastructure.
The companies are working across AI inference chips, storage controllers, networking hardware, memory controllers, and near-memory compute. Those aren’t side projects. They address the bottlenecks emerging as AI models become larger and inference workloads grow.
Marvell has already been building toward this opportunity. Its Aug. 4 product announcement highlighted PCIe 6.0 storage controllers, CXL memory expansion and pooling, and optical technologies designed to improve AI inference efficiency. The company also said its existing NIC and CXL design wins provide a path to more than $2 billion of revenue by fiscal 2029.
That makes the Google agreement more than a flashy investment headline. It potentially locks Marvell deeper into one of the world’s largest AI infrastructure buildouts.
The Catch Is Actually The Opportunity
Granted, shareholders should recognize the dilution risk. If all 58.97 million warrants vest and Google exercises them, Marvell will have more shares outstanding.
But the company isn’t simply handing Google $12.2 billion worth of stock. Marvell is giving Google an incentive to buy its products for years. Alphabet, meanwhile, gets equity exposure to the supplier helping build its AI infrastructure.
In short, investors should focus less on the headline “7% stake” and more on what Marvell must accomplish to earn it. Google’s capital spending is already enormous, while Marvell’s custom-silicon business is expanding.
Key Takeaway
The warrant creates potential dilution, but it also acts like a revenue-linked customer incentive. For Marvell shareholders, that’s a trade worth watching: if Google earns nearly 7% of the company, Marvell will first have generated a large amount of business from one of the world’s most aggressive AI spenders. That makes the warrant less a giveaway than a bet on Google’s AI spending becoming Marvell revenue.
The post Alphabet Could Own 7% of Marvell — But Here’s What Google Has to Do to Get It appeared first on 24/7 Wall St..
]]>The Invesco QQQ Trust (NASDAQ:QQQ) spent 26 years with a fee structurally locked in. It launched in March 1999 as a unit investment trust, a legal wrapper so rigid the expense ratio could not change without a shareholder vote.
That vote happened, the conversion to a standard open-end ETF went through, and the fee dropped to 0.18%. Invesco estimated the change would return roughly $70 million a year to shareholders in aggregate.
On QQQ’s $385.3 billion in assets, a two-basis-point cut adds up. The complication is that it still leaves QQQ at double the expense of the Vanguard Information Technology Index Fund (NYSEARCA:VGT), which is 0.09%.
On a $250,000 position, that is $450 a year against $225, so the real question is whether QQQ is doing something VGT isn’t and whether it is worth twice the fee.
Why the Fee Sat Frozen for Twenty-Six Years
Most ETFs are open-end funds, and the sponsor can adjust the expense ratio whenever the board approves it. QQQ was not built that way.
The unit investment trust structure fixed the fee at 0.20% from 1999 through last year. Every other major index ETF cut fees repeatedly over that stretch while QQQ remained locked behind a legal fence it could not climb.
Changing that required a proxy solicitation and a shareholder vote, both of which passed in December, clearing the way for the conversion. Once QQQ was a normal open-end ETF, Invesco could finally price it competitively.
0.18% is a real cut on a fund this size, and it is also the smallest move Invesco could make and still call one. Vanguard, Schwab, and iShares have run comparable large-cap index products at or below half that level for years.
Cost Math on a $250,000 Position
QQQ’s 0.18% costs $450 per year on $250,000, and VGT’s 0.09% costs $225 per year on $250,000. The gap looks small over one year but becomes meaningful over a decade of compounding, especially in a tax-advantaged account, where the drag is directly applied to the return.
The comparison only holds if the two funds track the same thing, and they do not. QQQ tracks the Nasdaq-100, the hundred largest non-financial companies listed on the Nasdaq. VGT tracks a technology sector index and holds only companies classified as technology.
QQQ includes Amazon (NASDAQ:AMZN), Costco (NASDAQ:COST), and other names that are not technology under standard sector definitions, and it excludes anything not listed on Nasdaq. VGT excludes Amazon, Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), and Meta (NASDAQ:META) because those sit in consumer discretionary or communication services, and it holds hundreds of smaller tech names QQQ never touches.
The two funds share their mega-cap top and diverge underneath. Owning QQQ because you wanted the Nasdaq-100 is a different bet than owning it because it felt like the obvious way to own tech.
Who Should Swap and Who Shouldn’t
The swap makes sense for one holder: the reader who owns QQQ as a broad technology bet, with little thought about the specific index behind it. VGT delivers cheaper, more tech-pure exposure with a sponsor that can move fees when competition demands it.
For a holder who wants the Nasdaq-100 specifically, meaning they want Amazon and Costco and the exact mix of companies that happen to list on the Nasdaq, VGT is the wrong fund at any price. Paying 0.18% for the index you actually want beats paying 0.09% for one you do not.
Taxes complicate the answer for anyone holding QQQ in a taxable account with a meaningful gain. Selling to save nine basis points a year is a bad trade if the capital gains bill wipes out a decade of fee savings on the way out.
In a retirement account, where the switch is free, the fee math favors making the swap. The fee cut was the right call for Invesco and still isn’t enough to make QQQ the cheapest way to own large-cap technology, which is the job most of its holders think they hired it for.
The post QQQ Cut Its Fee After 26 Years. On $250,000, the VGT ETF Still Saves You $225 Every Year appeared first on 24/7 Wall St..
]]>Among the three tech giants Wall Street is upgrading, Google (NASDAQ:GOOG) at $337.69 screens as the most compelling setup. Apple (NASDAQ:AAPL) at $316.94 and Broadcom (NASDAQ:AVGO) at $364.50 also carry consensus bullish tags, but Alphabet offers the sharpest mix of growth, valuation, and AI leverage.
All three sit inside the AI capex boom from different angles. Apple monetizes AI through hardware and a $30 billion Services engine, unveiling all-new Siri AI at WWDC26. Broadcom supplies custom XPUs and networking silicon powering hyperscalers, including Google itself. Alphabet runs the stack: TPUs, Gemini models, cloud, Search, and YouTube.
Over the past year, GOOG is up 69.23%, AAPL 37.93%, and AVGO 23.81%. Only one still trades like a value stock.
Why Alphabet Wins
Google’s Q2 delivered $119.8 billion in revenue, up 24%, with Cloud accelerating 82% to $24.8 billion and backlog swelling to $514 billion. The Gemini app has 950 million monthly active users, API traffic runs at 22 billion tokens per minute, and nearly 90% of Fortune 100 companies use Gemini Enterprise.
GOOG trades at a trailing P/E of 17 against forward 17, with a PEG of 0.93. Apple sits at 36 trailing, 32 forward. Broadcom trades at 60 trailing. Google’s Q2 EPS of $9.11 against a $2.88 estimate was inflated by equity gains, but core operating income still rose 30% to $40.8 billion.
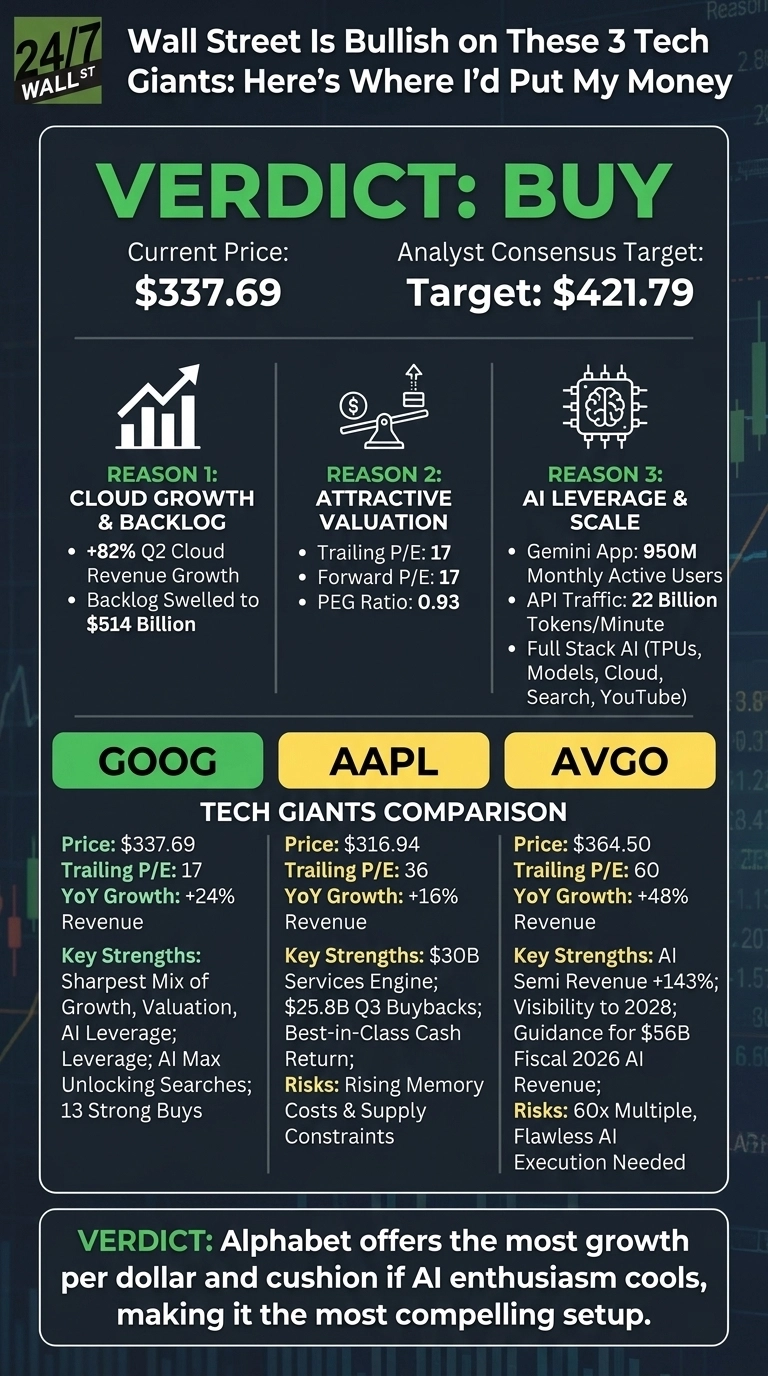
Where Apple and Broadcom Fall Short
Broadcom’s numbers dazzle. AI semiconductor revenue was $10.8 billion, up 143%, with Q2 bookings over $30 billion and guidance for $56 billion in fiscal 2026 AI revenue. The stock fell 12.88% in the past week as investors reassess the 60x multiple.
Apple’s Q3 was solid, with revenue of $109.4 billion, up 16%, and iPhone up 22%. Management flagged a 100-year flood on memory pricing and rising supply constraints. Siri AI remains unproven at scale, and gross margin guidance of 47% to 48% reflects memory pressure.
Why Patience Has a Case
Google’s capex hit $44.9 billion in Q2 alone, free cash flow ran negative $5.9 billion, and the buyback was suspended. Search faces regulatory overhang and generative AI competition.
Apple’s cash return story remains best-in-class with $25.8 billion in Q3 buybacks. Broadcom’s visibility runs all the way to 2028, and all of that spending has to be powered and cooled by somebody (we profiled seven of those suppliers in a free report). Waiting for a pullback across all three is defensible.
What the Numbers Say
Google’s consensus target sits at $421.79, implying roughly 25% upside, with 13 strong buys, 44 buys, 6 holds, and zero sells. Apple’s $325.70 target implies less than 3% upside across 46 analysts. Broadcom’s $527.88 target implies about 45% upside from 44 analysts, but assumes flawless AI execution.
Year to date, GOOG is up 9.03%, AAPL 16.86%, and AVGO 5.12%, versus the S&P 500 at roughly 12%. Google’s outperformance came with the lowest starting multiple, making the setup attractive.
Verdict: Alphabet Is the Best Money on the Table
At $337.69, Google screens as the most attractive of the three on a growth-adjusted basis.
Cloud is compounding at 82% with $514 billion of backlog. Search remains a monetization machine that AI is actively expanding, with AI Max unlocking billions of net new searches. The stock trades at 17x earnings while growing 24%.
Risks are real. Capex is running hot, cash flow has gone negative, and Gemini 4 execution matters. If Cloud growth decelerates below 50%, or if capex fails to translate into backlog conversion in 2027, the thesis weakens.
Apple deserves its premium as a compounder, and Broadcom deserves its multiple if it hits $100 billion in AI sales by 2027. But at these prices, Google offers the most growth per dollar and the most cushion if AI enthusiasm cools.
The post Wall Street Is Bullish on These 3 Tech Giants. Here’s Where I’d Put My Money appeared first on 24/7 Wall St..
]]>