⏳ Reading Time: 5 minutes“Breathing space” was the catchphrase for this year’s Budget, focused on giving UK consumers and businesses more assistance with current inflation shocks. But it was also quite an apt phrase for the wealth and saving industry as a whole. In a ‘post election manifesto’ era where potential (and actual) Budget policy have caused a cacophony […]
The post Budget 2026: the key points for savers and investors appeared first on MoneyFarm Insights.
]]>“Breathing space” was the catchphrase for this year’s Budget, focused on giving UK consumers and businesses more assistance with current inflation shocks. But it was also quite an apt phrase for the wealth and saving industry as a whole.
In a ‘post election manifesto’ era where potential (and actual) Budget policy have caused a cacophony of noise around pension contributions allowances, tax free cash allowances, tax rates and ISA policy, this experience was relatively sanguine. Okay, there was the reversal of that Cash ISA allowance, but that in itself was a reversal of a previous bombshell. But we will go into that in more detail.
While there has been far less of a rush to take pension benefits early, that doesn’t mean this Budget had nothing of significance for savers.
Reinstating the Cash ISA allowance
Perhaps the more sceptical amongst you might speculate that the government just simply wasn’t ready for this policy, too many unanswered questions about what qualified as ‘cash’, nonetheless this is a meaningful U-turn.
The intention behind this original policy to get more investing was a good one. Whilst it’s debatable how much of this money would have fed to UK companies for growth, the population of the UK still holds far too much cash – £1.98tn is sat in cash savings according to Forbes.
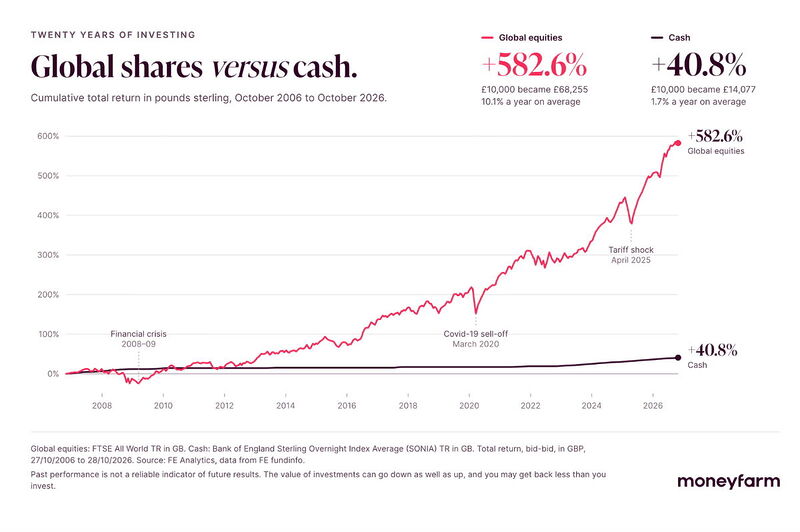
Below you can see the danger of holding too much cash over the long term, looking over the last 20 years. Cash obviously remains a key tool for short term savings and investing comes with risk.
This policy switch seems to have caused uproar around the industry, particularly as something like changing technical restrictions on contributions within a platform and reporting etc, is no small feat. So a lot of time and energy has been spent/wasted on making changes which will no longer come to fruition. It’s also unhelpful for savers, who are constantly having allowances changed and needing to change plans accordingly.
So whilst perhaps a return to something more simple might be welcomed by some, it takes a big step back in the key aim of trying to get more people investing, which is actually fundamental for making sure people are prepared for their futures. Without the tax incentive, I’m dubious about how much impact some adverts with a squirrel will have by themselves.
More ISAs, more choice?
The Help to Buy ISA became the Lifetime ISA (LISA), and which now becomes First Time Buyer ISA, with no major overhaul to the rules. The most common issue with the Lifetime ISA is that the threshold price of a property that you can buy with the money is quite limiting. However, instead of simply raising the price allowed and keeping the LISA, the government has created a new ISA category, which is exactly the same except it simply allows customers to get their money back out of it if they can’t find a home in the price bracket. Not the most revolutionary.
On top of this, there is a new ISA being touted. The new Starter ISA, designed to get people investing, sounds like an attempt to counteract the reversal of the Cash ISA allowance. Whilst we support anything that gets more people investing, as highlighted above, the addition of another ISA has raised some eyebrows. Let’s see what details come out about this, but there is no doubt that there is more complexity.
Taxes
There was a lot of noise in the run up to the Budget about equalising capital gains tax to income tax, or at least increasing it. In the end, this didn’t materialise (with extra reliefs added for entrepreneurs). This is definitely a win for those building wealth through investments outside of their tax wrappers. On top of this, there was actually a small increase in tax on savings and rental income.
This can be quite relevant. Income tax on savings is already quite a lot higher than capital gains and as such is very relevant for people with savings outside of tax wrappers, particularly higher and additional tax rate payers. Whilst, on the surface, a cash product can offer 3.5% to 4%, the reality can be that this in fact is 1.96% or 2.24% once you have then paid tax, which is probably not keeping pace with inflation. It’s not clear in the Budget documentation, but it could well be that this is also relevant for bond-based investments as well.
So it’s very relevant about how to structure your assets outside of tax wrappers. If you want to discuss this with our team, I would highly recommend reaching out to our friendly and accessible Wealth Managers for a discussion about your situation.
But it seems to be a clear signal from the Chancellor that he does want to promote more investment and wealth creation, which in general is certainly positive.
Pensions
This was a mercifully quiet Budget for pensions. No changes to rules on private pensions is very welcome and it still remains a very attractive product. The fact of being able to contribute up to £60,000 a year into a tax-free wrapper, with tax relief provided to boost contributions makes this still a very appealing and crucial tool for building for retirement.
Whilst not in this Budget, the imminent change that it will soon be included as part of the estate for inheritance tax can change its use case quite meaningfully and we will come back to this topic in later pieces.
But for private pensions, this budget was a welcome relief.
Which is good, as there was confirmation of initial rumblings around relaxing the triple lock. Whilst this early step is not a major change, there are still three locks in place, it signals a step down a path that many feel is inevitable. With a rapidly ageing population, the State pension will begin to put some serious pressure on the public coffers and it’s definitely not unlikely that further changes will be made in the future.
This makes it even more important for people to plan ahead, whether through private pensions or other savings vehicles such as ISAs.
So this was very much a Budget of small wins and trying not to make too big a splash. Something you would argue that it achieved. A focus on energy makes sense, not just to help households, but the high cost of energy that the UK faces (compared to other G7 countries) is generally touted as one of its biggest blockers to growth.
So savers and investors were largely left alone in this Budget, some breathing space as promised.
If you would like to discuss any of the points covered in the Budget or this article, we encourage you to get in touch with our team.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Budget 2026: the key points for savers and investors appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 3 minutesIt’s been a particularly busy week in markets. We’ve had earnings reports from tech companies, interest rate policy decisions from central banks, a Budget announcement in the UK and the latest GDP figures in the US and Europe. We’ll have a brief chance to digest all of this over the weekend, before the US midterm […]
The post What the latest market moves are telling us appeared first on MoneyFarm Insights.
]]>It’s been a particularly busy week in markets. We’ve had earnings reports from tech companies, interest rate policy decisions from central banks, a Budget announcement in the UK and the latest GDP figures in the US and Europe. We’ll have a brief chance to digest all of this over the weekend, before the US midterm elections next week and the possibility of a further re-escalation of the conflict in the Middle East. Before that, we wanted to take stock of where we are.
Starting with tech earnings, from the likes of Alphabet (Google) and Amazon. We think the results have been strong in absolute terms but have left investors wanting a bit more. The challenge has come not from the cloud /Artificial Intelligence (AI) part of these businesses, which we think saw very strong growth, but rather from the core businesses – advertising for Alphabet and retail for Amazon.
We think this might tell us more about the health of the consumer (and disruption from AI in the world of advertising) than it does about AI adoption. But hyperscalers are using the cashflow from their core businesses to finance the AI build out. Consistently weaker cashflows could mean more debt or equity issuance to spend on capital investment – which remains high.
On the policy side, both the Federal Reserve and the European Central Bank left rates unchanged this week, even though inflation remains above target. It’s reasonable to ask why Central Banks didn’t raise rates again. Part of the answer could be that financial conditions have tightened already (with higher bond yields) and so they can afford to be patient. It’s also possible that the geopolitical uncertainty, and the potential for further energy shocks, justifies a cautious approach.
Finally, with the US midterms next week, Fed governors might have wanted to avoid any appearance of political engagement. Regardless of the precise timing, we think that the direction of travel is for higher policy rates over the coming months – potentially with another hike in December.
The latest GDP figures pointed to decent growth, despite the impact of higher oil prices. These numbers are preliminary and do get revised. They show that the Eurozone grew 1.3% year on year in the 3rd quarter, even though France saw a slight contraction. On the same basis, the US economy grew around 2.1% in 3Q1. The impact of AI spending was pretty clear in the numbers. Non-residential investment spending in the US was particularly strong, growing over 8% year on year.
So, where does this get us?
In terms of growth, the overall performance of the global economy has been better than we might have feared. Growth has actually been accelerating over the past few months. That said, if high oil prices persist even longer, we’d expect to see some impact in terms of slower growth, particularly around consumer spending.
On the equity side, we’ve seen some weakness in tech names relative to high expectations, but overall earnings growth remains robust. As we’ve noted before, UK equities have been a useful counter-balance recently. We’d also highlight that the correlations within the Mag 7 have been falling over the past few months. The large tech businesses don’t all move in lockstep. Recently we’ve seen Apple, in particular, perform quite differently from the likes of Amazon and Alphabet.
We remain constructive on these tech businesses for now, given the strong growth we’re seeing. We think we’re still in the early stages of AI adoption for both businesses and consumers. That said, we’re focused on keeping our portfolios well-diversified. We have kept our allocations largely unchanged recently, but we’re on the lookout for any opportunities that the recent market volatility could provide.
- For the statisticians, the US Bureau of Economic Analysis usually reports growth as quarter-on-quarter seasonally adjusted annualised figures. That came in at 3.4% in 3Q, but we’ve used the year-on-year figure for the sake of comparison.
↩︎
The post What the latest market moves are telling us appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 6 minutesThis observatory was written before the cyberattack on the crypto firm Binance on 30 October. September is usually Bitcoin’s weakest month, as seasonality cross assets is weak, and this one started with plenty of reasons for caution. The Federal Reserve (Fed) was preparing to raise rates, US government bond yields were at their highest in […]
The post Crypto: what’s driving the market? appeared first on MoneyFarm Insights.
]]>This observatory was written before the cyberattack on the crypto firm Binance on 30 October.
September is usually Bitcoin’s weakest month, as seasonality cross assets is weak, and this one started with plenty of reasons for caution. The Federal Reserve (Fed) was preparing to raise rates, US government bond yields were at their highest in two decades and a crypto bill was heading for a difficult Senate vote.
Bitcoin still closed the month up about 6.4% at around $83,600, ending its best third quarter since 2017. Early October has been less kind. Bitcoin failed to break above $87,000 in the first week, then fell to around $80,000 in mid-month after higher-than-expected inflation figures. It has since settled at $82,000–83,000, about 3% lower for the month and still around 7% down for the year.
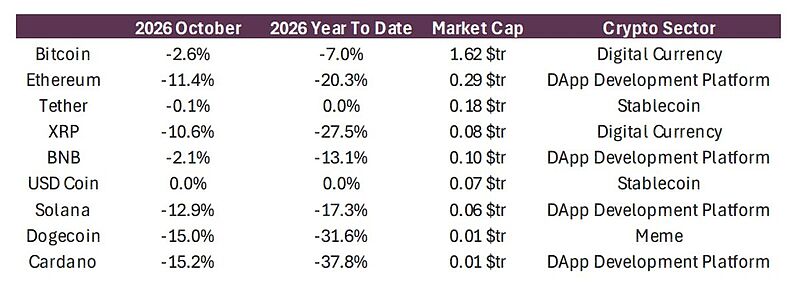
The path through September matters more than where it ended. Bitcoin touched its low for the month, about $74,900, on 15 September, the day the CLARITY Act – a bill aimed at establishing clearer rules for the US crypto market – failed in the Senate and the day before the Fed’s rate hike. Within a week it had reached $87,400. Part of the rise again came from investors who had bet against Bitcoin being forced to close those bets: around $650 million of these “short” positions were liquidated on 21 September alone. Real buying played a part too, with US spot Bitcoin ETFs – funds that invest directly in Bitcoin – taking in money on nine consecutive days between 17 and 29 September.
Within crypto, September favoured the more volatile assets. Ether rose about 9% and climbed above $2,700 for the first time since January, while Solana gained around 15% to a seven-month high. Much of the gain was concentrated in a few specific stories, such as tokens linked to Artificial Intelligence. October has partly reversed this. Ether has lost around 11% so far this month, and Bitcoin’s share of the total crypto market is back near 60%, usually a sign that investors are turning more defensive.
The macro moment
Inflation is still the dominant theme. On 16 September the Fed raised rates by 25 basis points to 3.75-4%, its first increase since 2023, and Fed Chair Kevin Warsh said inflation “is too high, and has been for too long”. The minutes of the meeting showed that most officials expect another rise before the end of the year.
The data since then have pointed both ways. The Fed’s preferred inflation measure for August came in below expectations. September consumer and producer prices, however, rose more than expected, and households’ inflation expectations for the year ahead reached 4.7%. Markets now see a December rise as more likely than a move at the 27–28 October meeting. Oil adds to the pressure, with Brent close to $110 a barrel after renewed tension in the Strait of Hormuz.
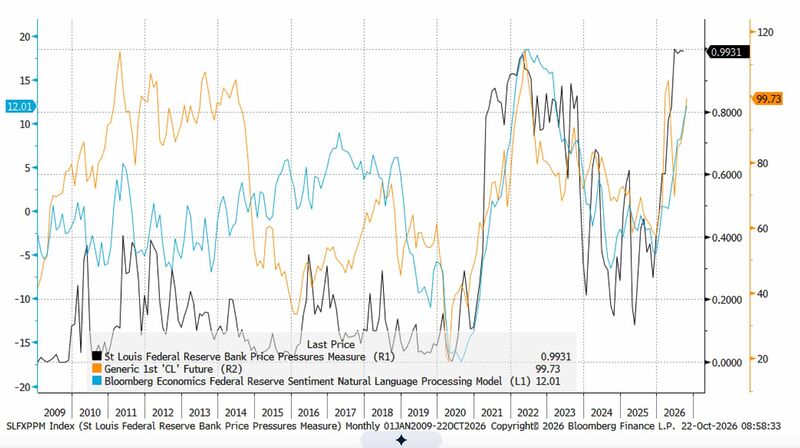
The chart compares three indicators from 2009 to today: the oil price (orange line), the probability estimated by the St. Louis Fed that US inflation will exceed 2.5% over the next twelve months (black line), and the “tone” of Federal Reserve communications as measured by Bloomberg (light blue line; higher values indicate a more restrictive stance).
The three lines tend to move in a similar direction. As in 2021–2022, the rise in oil prices in 2026 – now close to $100 a barrel – has been accompanied by growing price pressures. According to the St. Louis Fed indicator, the probability of inflation remaining above 2.5% is now close to 100%. At the same time, the Fed’s language has become more focused on tackling inflation, although it has not reached the levels seen in 2022.
As in previous months, one of the key factors to watch is how the Fed and the US Treasury work together to contain tensions in the bond market. While the Fed acts mainly through interest rates, the Treasury can intervene directly in the government bond market. Since the beginning of September, it has carried out three larger-than-usual buybacks of long-dated bonds: by purchasing these bonds, it supports demand and can help limit the rise in their yields. Treasury Secretary Scott Bessent has also said that he will intervene if yields continue to rise. Markets have started referring to this kind of “safety net” as the Bessent put. So far the effect has been limited. The 10-year yield reached around 5.37% in early October, its highest since 2002. The Fed’s own minutes noted that uncertainty about the buyback programme had raised the extra return investors demand to hold long-dated bonds.
Meanwhile, the Fed paused its regular purchases of short-term Treasury bills in September. Put together, the Fed is tightening and no longer buying bills, while the Treasury is issuing more bills to pay for its buybacks. That drains some liquidity from the financial system, which does not help Bitcoin. The picture would change if the Treasury used its cash reserves to fund larger buybacks, or if the Fed restarted its bill purchases, since either would add liquidity. On the other hand, another rate rise and a stronger dollar would keep real yields high and increase the cost of holding an asset that pays no income.
Bitcoin’s correlations with other assets have shifted as a result. In August, Bitcoin moved closely with gold as part of a trade against US fiscal risk. In September the two parted ways: gold fell more than 6% while Bitcoin rose. Over the same month, Bitcoin’s correlation with US equities rose from close to zero to around 0.5. In mid-October, Bitcoin slipped towards $80,000 in the same week the Nasdaq fell 4.5% on doubts about how long AI spending can last, although Bitcoin fell much less. The usual caveat applies: macroeconomic factors explain only part of Bitcoin’s behaviour. Still, a closer link with equities is worth watching, because it weakens Bitcoin’s role as a diversifier.
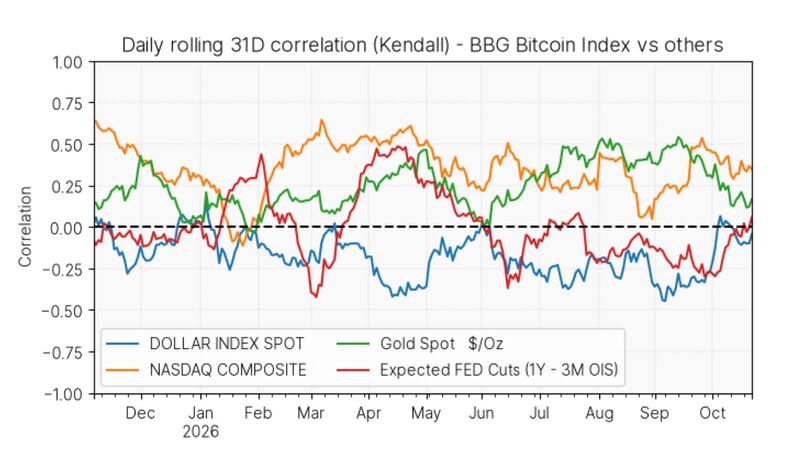
Source: Moneyfarm analysis based on data from Bloomberg. Data as at 27 October 2026
On regulation, the CLARITY Act failed a procedural vote in the Senate on 15 September, well short of the 60 votes it needed. Bitcoin fell about 4% that day but recovered within a week. Congress is in recess until after the 3 November midterm elections, so the bill’s best remaining chance is the short session before the new Congress sits.
In the meantime the regulators have kept moving. The SEC, the US financial markets regulator, has proposed new rules for crypto offerings and custody, plus a five-year exemption for platforms trading tokenised securities.
Outside the US, the UK has opened applications for its new crypto regime and the EU has tightened supervision of stablecoins.
A more immediate risk concerns companies that hold Bitcoin on their balance sheets. Index provider MSCI has finalised rules that could remove companies whose main activity is holding digital assets from its indices, with a list due on 11 November. Strategy, the largest corporate holder, could be affected, with estimates of up to $2.8 billion in outflows from funds that track those indices.
The flows
Flows into US Bitcoin ETFs stayed strong in September at around $2.65 billion, after $3.5 billion in August, and turned positive for the year. Ether ETFs added $832 million. October has been weaker. Bitcoin ETFs are roughly flat for the month after a run of outflows, while Ether ETFs have lost about $1.1 billion, their worst month of the year.
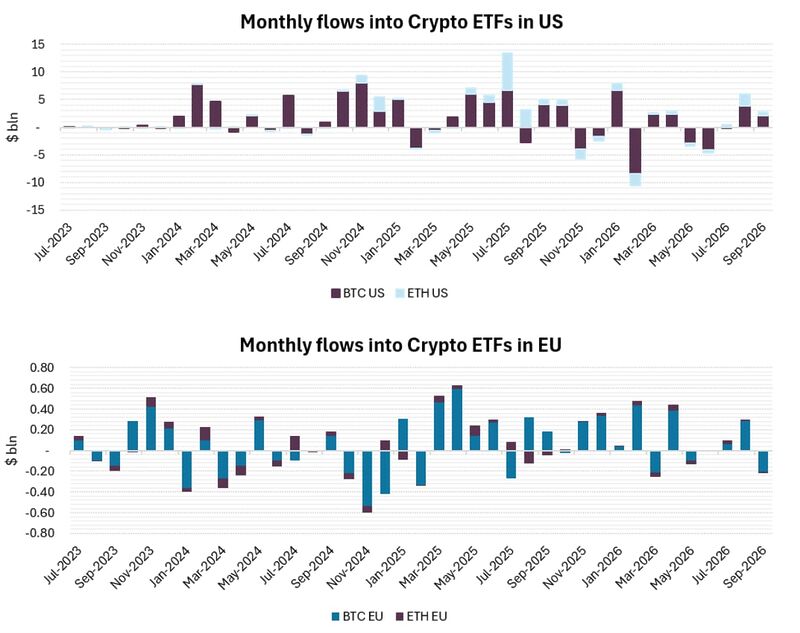
Source: Moneyfarm analysis based on data from Bloomberg. Data as at 27 October 2026
Taken together, the period shows Bitcoin rising through a rate hike, a failed crypto bill and higher yields, helped by steady ETF buying. Early October has shown the limits of that resilience, as the dollar strengthened, inflation surprised and equities wobbled. Some tests now arrive close together, including the US midterms on 3 November and MSCI’s list on 11 November. It is too early to say whether the summer recovery marks a lasting change. How the Fed and the Treasury handle long-term yields is likely to matter most for what comes next.
Investing in Crypto involves a high level of risk. You should not invest unless you are prepared to lose all of the money you invest. The value of your investments can go down as well as up, and you may get back less than you invest. You may not be protected if something goes wrong. Past performance is not a reliable indicator of future results. The views expressed here do not constitute a recommendation, advice or forecast. If you are unsure whether investing is right for you, please seek independent financial advice.
The post Crypto: what’s driving the market? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesDeciding how to invest a windfall can mean weighing up opportunities that once felt out of reach. A lottery win, an inheritance or an unexpected bonus might help you buy a home, support your children or bring retirement closer. Alongside those possibilities, however, comes the responsibility of making the money last. The amount you receive […]
The post How to invest a windfall in the UK appeared first on MoneyFarm Insights.
]]>Deciding how to invest a windfall can mean weighing up opportunities that once felt out of reach. A lottery win, an inheritance or an unexpected bonus might help you buy a home, support your children or bring retirement closer. Alongside those possibilities, however, comes the responsibility of making the money last.
The amount you receive is only part of the picture. Your existing savings, debts and family commitments will influence how much you can invest, while the source of the money may affect its tax treatment. A lump sum can strengthen your finances without providing enough to support a permanently more expensive lifestyle.
The next step is to decide what you want the money to do for you. Let’s look at what to consider before investing, where you could put it and which mistakes to avoid along the way.
What to consider before investing a windfall
Before deciding where to invest, take time to assess how the money fits into your finances. This is particularly important if it arrives during an emotional period, such as a bereavement, when long-term decisions may need to wait.
Work out how much you can use
The starting point is the amount available after any tax. National Lottery winnings are exempt from UK Income Tax, whereas an employment bonus is generally taxable. Even when the original payment is tax-free, interest or investment income earned afterwards may be taxable.
Any tax still due therefore needs to be accounted for before you commit the money. With that amount set aside, you can turn to your existing financial commitments.
Balance debt repayments with accessible savings
Paying off an expensive credit card balance removes an ongoing interest cost, whereas investing the same amount offers an uncertain return. A mortgage requires a closer comparison of its interest rate, any early repayment charges and the cash you would retain.
Alongside repayments, allow for unexpected expenses. MoneyHelper suggests keeping three to six months’ essential outgoings in an accessible savings account, adjusted to your income security and family responsibilities. Planned spending, such as a house deposit, needs a separate allocation so that it does not use up this emergency reserve.
Connect your goals with the risk you can afford
Once these needs are covered, consider what the remaining money is for. Three questions can shape your investment choices:
- When will you need it? A home purchase in two years calls for a different approach from retirement in twenty.
- How much could you afford to lose? A fall in value should not leave you unable to meet essential expenses.
- How would you react to a market downturn? An investment needs to suit both your finances and your willingness to accept fluctuations.
Your answers may point to different uses for different portions of the windfall. Money needed soon should remain accessible; money you can leave untouched for longer can be considered for investment.
Where to invest a windfall in the UK
Choosing where to invest involves both the assets you buy and the account that holds them. Shares and bonds determine much of the investment risk; an ISA, pension or General Investment Account determines how tax and withdrawal rules apply.
Keep short-term money in savings
Money needed soon generally belongs in savings rather than investments whose value could fall before you withdraw. An easy-access account suits unexpected expenses, while a fixed-term deposit may suit a planned purchase if its maturity date matches your needs.
Check withdrawal restrictions and FSCS deposit protection, particularly with a large balance. Cash provides stability, although inflation can erode its purchasing power over time.
Choose investments for longer-term goals
For money you can leave invested, funds and exchange-traded funds (ETFs) offer ways to spread exposure across companies, markets and asset types. Shares provide growth potential but can fluctuate sharply. Bonds can diversify the portfolio, although they also carry risks, including changes in interest rates and borrowers failing to repay.
The balance should reflect your timeframe and capacity for loss. Holding several funds does not necessarily mean greater diversification if they own much the same investments.
Use the right accounts for you and your family
These investments can sit within different accounts. A Stocks and Shares ISA shelters investment income and capital gains from UK tax. For 2026/27, the adult ISA allowance is £20,000, shared across your ISAs, so deduct contributions already made that tax year.
If retirement is your priority, a pension offers potential tax relief in exchange for restrictions on when you can withdraw the money. The relief available depends on your circumstances, including relevant earnings, and annual allowance rules also apply. Receiving a lottery win does not itself increase the earnings used to calculate your entitlement to pension tax relief.
For investment beyond your ISA allowance, a General Investment Account has no annual contribution cap, but income and realised gains may be taxable.
Alternatively, money intended for a child could go into a Junior ISA. The 2026/27 allowance is £9,000 per child, shared across their cash and stocks and shares Junior ISAs and all contributors. The money belongs to the child and is normally locked away until 18, when they can decide how to use it.
The comparison below brings together the main uses and restrictions.
| Option | Potential role | Main consideration |
| Savings account or Cash ISA | Emergency reserve and short-term spending | Check access, interest and deposit protection; Cash ISA contributions use your adult ISA allowance |
| Stocks and Shares ISA | Longer-term investing with UK tax-free income and gains | Investments can fall in value; annual ISA allowance applies |
| Pension | Retirement savings with potential contribution tax relief | Earnings and allowance rules apply; restricted access and potentially taxable withdrawals |
| General Investment Account | Investing beyond ISA allowances | No annual contribution cap; income and gains may be taxable |
| Junior ISA | Money set aside for a child’s future | Separate allowance; the gift belongs to the child, with normal access at 18 |
Pension limits should be checked against HMRC’s contribution rules. Tax benefits depend on individual circumstances, and tax rules can change.
Should you invest a windfall all at once or gradually?
With your accounts and investment mix chosen, the next decision is how to put the money into the market. You can invest the amount earmarked for long-term goals immediately or spread purchases over a defined period.
Investing a lump sum
Investing all at once gives the entire amount exposure to any market growth from the outset. The trade-off is that a downturn soon afterwards affects the whole investment, which can be unsettling when you are managing a large sum for the first time.
This approach therefore calls for a portfolio you could hold through falling markets, without needing to withdraw money or sell because the losses feel unbearable.
Investing gradually
Alternatively, you could invest equal amounts each month over a set period. Buying at different prices spreads your entry points and may make the transition from cash to investments feel more manageable.
The trade-off is that money still held in cash will miss any market gains during that period. Spreading purchases can make the process easier to manage emotionally, but it does not guarantee better returns or protect the invested capital from losses.
If you choose a phased approach, set the amounts and dates in advance. A clear schedule keeps the decision tied to your plan, rather than repeated attempts to guess whether markets will rise or fall next.
How to invest a £100,000 windfall in practice
The decisions become clearer when applied to a household’s circumstances. Suppose a 40-year-old UK resident receives £100,000 after any tax due. They have an eight-year-old child, £5,000 of expensive credit card debt and no emergency savings. Their regular income covers everyday spending, with essential outgoings of £2,500 a month.
They also expect to spend £15,000 on home improvements within two years. Beyond these commitments, they want to invest for at least ten years and set aside something for their child. Assuming neither their adult ISA allowance nor the child’s Junior ISA allowance has been used in 2026/27, one illustrative allocation could be:
| Purpose | Amount | Possible destination |
| Clear expensive borrowing | £5,000 | Repay the credit card balance |
| Cover six months of essential expenses | £15,000 | Easy-access savings account |
| Fund planned home improvements | £15,000 | Savings with access matched to the spending date |
| Invest for longer-term personal goals | £20,000 | Stocks and Shares ISA |
| Invest beyond the ISA allowance | £40,000 | General Investment Account |
| Make a gift for the child’s future | £5,000 | Stocks and Shares Junior ISA |
| Total | £100,000 |
This leaves £30,000 accessible or reserved for planned spending, clears the debt and puts £65,000 towards longer-term goals. Of that invested amount, £5,000 belongs to the child and cannot be treated as the parent’s reserve.
The ISA and General Investment Account could hold complementary funds within one overall portfolio, with the mix of shares and bonds chosen around the parent’s risk profile. The child’s investments need a separate assessment, particularly if the money is likely to be spent at 18.
Keep the plan aligned with your circumstances
The allocation is a starting point, not a recommendation. Someone without children, with a larger mortgage or prioritising retirement could make different choices, including pension contributions where appropriate.
Before investing, compare the total charges for the account, portfolio management, funds and transactions. These costs reduce what you keep from any returns. Once the portfolio is in place, reassess it periodically and whenever your circumstances change. Market movements may also shift the balance between assets, making rebalancing appropriate after considering dealing costs and any tax due.
Common mistakes to avoid after receiving a windfall
Choosing suitable investments is only part of managing the money. Decisions about work, spending and gifts can commit a windfall just as quickly, so consider the longer-term consequences of the following choices:
- making major decisions too quickly: leaving work, buying a property or promising money to relatives can create commitments before you have assessed your own needs. Give yourself time to weigh up the consequences, particularly after a bereavement;
- allowing everyday spending to rise unchecked: a larger home brings maintenance and running costs, and occasional treats can become regular expenses. Consider what your usual income can sustain before drawing repeatedly on the windfall;
- giving away more than you can afford: supporting family or charities may be a priority, but decide on an affordable amount after allowing for your own future needs. Substantial gifts may also require tax and estate-planning advice;
- assuming the headline amount is yours to spend: depending on its source, a windfall may come with tax liabilities or other costs. Making commitments before confirming the net amount can leave a shortfall.
There is still room to enjoy some of the money. Setting a spending budget within the wider plan allows for that without leaving your longer-term goals dependent on whatever remains.
FAQ
A windfall is a substantial sum received outside your usual income, such as an inheritance, lottery win, gift or unexpected bonus. There is no fixed minimum: its significance depends on how much it changes your financial circumstances.
Receiving inherited cash does not usually trigger Income Tax or Capital Gains Tax for the beneficiary. Inheritance Tax may apply separately, and interest earned afterwards can be taxable. The rules for inherited money differ from those for employment bonuses or other sources of wealth.
The amount depends on what remains after taxes, debt repayments, emergency savings and planned spending. Investing a fixed percentage without considering these commitments could leave you needing to sell during a market downturn.
You can use successive tax years’ allowances, subject to eligibility and the rules applying each year. The adult allowance is £20,000 for 2026/27. Selling investments held outside an ISA to fund later contributions may create a Capital Gains Tax liability.
Money paid into a Junior ISA belongs to the child. They can take over management at 16 and normally withdraw it from 18. If you want to decide how the money is spent beyond that age, a Junior ISA may not suit your intentions.
That depends on your spending, other income and how long the money must last. Include inflation, tax, fees and market losses in your calculations, alongside the years before you can access pensions. A financial adviser can assess whether your proposed withdrawals are sustainable.
The post How to invest a windfall in the UK appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 9 minutesThe current savings climate means it’s time to make your money work harder for you, and get you one step closer to achieving your goals.
The post Best Way to Invest 20k & best savings account for £20,000 appeared first on MoneyFarm Insights.
]]>If you have £20,000 sitting in the bank, deciding what to do with it can feel daunting. Working out how to invest 20k starts with your goals, how soon you need the money, and how much risk you can afford to take.
Once those priorities are clear, an ISA can help you save or invest tax-efficiently. The ISA allowance remains £20,000 for 2026/27, shared across your accounts rather than available for each one. However, the tax benefits do not remove investment risk.
If your money is already in a Cash ISA, you can transfer it to a Stocks and Shares ISA through the receiving provider, preserving its ISA status. Whether that move suits you depends on your timeframe and ability to accept losses, so check any transfer charges or restrictions first.
| Can I invest 20K by myself? | You can choose your own investments or use a managed service, depending on your knowledge, confidence and the support you need. |
| Most important thing to keep in mind | Match your investments to when you will need the money and the losses you could afford. A longer timeframe does not guarantee a profit. |
| Key aspect of investing | Diversify across assets, sectors and regions to reduce reliance on individual investments. This cannot eliminate losses. |
| Top 5 tips | Keep an emergency fund accessible. Prioritise expensive debt. Use tax allowances where appropriate. Choose investments that suit your timeframe and risk tolerance. Compare charges and review your plan regularly. |
Should I Save or Invest £20,000?
Deciding whether to save or invest £20,000 depends on your financial needs, goals, time horizon, and attitude to risk.
The key question is how soon you might need to access your money and how much uncertainty you’re willing and financially able to accept for the chance of higher returns. You may find that splitting the money between savings and investments suits different goals better than choosing just one approach.
Saving 20k
Saving is usually more suitable if you expect to use your money within the next two to three years. A high-interest savings account or Cash ISA can help you set money aside without stock market exposure, although access conditions vary. For an emergency fund, choose an easy-access account; fixed-term savings may suit expenses you can plan ahead for.
Advantages of saving £20,000
- Eligible bank deposits have FSCS protection up to £120,000 per person, per authorised institution, including accounts with brands sharing a banking licence.
- Instant or short-notice access to funds where the account permits it.
- A fixed rate provides certainty over interest; variable rates can change.
- Bank deposits do not fluctuate with stock market prices.
For example, if you put £20,000 in a savings account earning a hypothetical 4.5% AER, you’ll earn £900 interest over a full year, assuming the rate stays unchanged and you make no withdrawals. That interest is tax-free if held within a Cash ISA.
However, the interest rate alone does not tell you how much your savings are growing in real terms. Your purchasing power increases only if the interest you earn after tax outpaces inflation.
Understanding your financial habits and approach to investing can also help you decide how much to keep in savings and how much you could invest for longer-term goals.
Investing 20k
Investing may be suitable if you can leave your money untouched for at least five years and afford potential losses. A longer timeframe gives investments more opportunity to recover from market falls, but does not guarantee a profit.
Advantages of investing £20,000:
- Potential for higher long-term growth than cash accounts.
- Opportunity to beat inflation and preserve real purchasing power.
- Access to diversified funds through accounts such as a Stocks and Shares ISA, a SIPP or a GIA, each with different tax and access rules.
- Ability to align investments with personal goals or ethical preferences.
For example, a £20,000 investment growing at a hypothetical 6% a year after fees could reach around £26,800 after five years, assuming returns are reinvested and there are no further contributions or withdrawals. This illustration excludes any tax and inflation. Actual returns vary, and you could get back less than you invest.
Investing can support retirement, education or a future home purchase. However, high return investments in the UK involve greater potential losses, while megatrends can concentrate exposure. Money market funds also carry risk and are not equivalent to protected deposits. Your investment strategy should balance these risks with your goals and access needs.
Choosing What Fits You Best
Your choice need not be all or nothing: keep money for nearer-term needs in accessible savings and consider investing the rest if you can accept losses. The table compares the main differences.
Saving vs Investing £20,000
| Feature | Saving £20,000 | Investing £20,000 |
| Time horizon | Usually shorter-term goals | Usually at least five years, without guaranteed returns |
| Risk level | Eligible deposits benefit from FSCS protection; inflation can erode purchasing power | Varies with the investments; you may lose money |
| Potential return | Depends on the account; variable rates can change | Uncertain and dependent on performance and costs |
| Access to funds | Easy-access, notice or fixed-term conditions | Depends on the investment and account; selling may crystallise losses |
| Inflation protection | Depends on interest after tax relative to inflation | Potential to outpace inflation, without a guarantee |
| Tax treatment | Cash ISA interest is tax-free; other savings may be taxable above available allowances | Stocks and Shares ISA returns are tax-free under current rules; pension withdrawals can be taxable |
| Best for | Emergency fund, short-term goals | Long-term goals where you can accept investment risk |
Should you invest £20,000 yourself or use a managed service?
Choosing between managing investments yourself and using a service such as Moneyfarm depends on your knowledge, available time and the support you need.
Either way, diversification reduces reliance on individual investments, although assets can fall together. A diversified fund can make it easier to spread your money across investments, but check its holdings and costs.
When comparing managed services, consider platform, management and fund charges alongside the support provided. Higher fees do not guarantee better performance.
How to Invest Your £20,000 in 2026
Before investing, consider whether some of your £20,000 would be better used for emergency savings, expensive debts, your mortgage or pension. These priorities will shape how much you can invest and for how long.
Build an Emergency Fund
Before investing, aim to keep three to six months’ essential expenses in an easy-access savings account or Cash ISA, adjusting the amount to your commitments and income stability. This buffer can help you cover unexpected costs without selling investments during a downturn.
Pay Off Expensive Debts
If you have high-interest debt, such as credit cards or personal loans, consider repaying it before investing.
Reducing that balance saves interest, whereas investment returns are uncertain. For example, clearing £2,000 of borrowing charged at 20% a year would avoid £400 in annual interest if the balance otherwise stayed unchanged, excluding fees. Check any early repayment charges and keep your emergency savings accessible.
Once high-cost borrowing is under control, you can focus on growing your wealth.
Overpay on Your Mortgage
If you own a home, making voluntary overpayments can reduce your mortgage interest and potentially shorten the repayment term. Compare that saving with the interest you could earn after tax by keeping the money in savings.
Before proceeding, check your lender’s overpayment allowance and any early repayment charges. Many lenders allow up to 10% a year without a penalty, but the limit and how it is calculated depend on your mortgage terms. Remember that you usually cannot access the money again once it has been repaid.
Contribute to Your Pension
If retirement is your priority, pension contributions can be a tax-efficient use of some of your £20,000.
With relief at source, an eligible £80 contribution becomes £100 after basic-rate tax relief. Depending on your Income Tax rate, you may be able to claim additional relief from HMRC. For 2026/27, the standard annual allowance is £60,000, including employer contributions, although a lower allowance can apply. Tax relief on personal contributions is also normally limited by your relevant UK earnings.
That tax advantage comes with restricted access: you can normally take money from a private pension from age 55, rising to 57 from 6 April 2028, unless an exception applies. Investment growth is not guaranteed, and withdrawals can be taxable.
Diversify Your Investments
Once you have built a diversified portfolio, review it periodically. Market movements can alter its balance, so rebalancing may help keep risk aligned with your goals. Check any costs and potential tax outside an ISA or pension. A managed service can handle this for you.
Consider Ethical and Sustainable Investing
Many investors want their investments to reflect their values alongside their financial goals.
ESG (Environmental, Social and Governance) investments, green bonds, and impact-focused ETFs take different approaches, so check their holdings, selection criteria and stated objectives rather than relying on the label alone.
These choices still carry investment risk, and some focus on a narrow range of sectors. Consider how they fit your wider portfolio, as well as your values.
Make the Most of Your ISA Allowance
An ISA remains one of the UK’s most tax-efficient ways to invest. For 2026/27, you can contribute up to £20,000 across your adult ISAs, less anything already paid in during the tax year. You have until 5 April 2027 to use the allowance; any unused amount cannot be carried forward.
A Stocks & Shares ISA can suit long-term investing, while an easy-access Cash ISA can hold emergency savings. Choose according to your needs rather than rushing to invest simply to use the allowance.
Under the announced ISA reforms, from 6 April 2027 the annual Cash ISA limit will fall to £12,000 for under-65s, within the unchanged £20,000 overall allowance. The £20,000 cash limit will remain available from the tax year in which you turn 65. The reforms also include a 22% charge on interest paid on cash held in non-cash ISAs and a ban on transfers from non-cash ISAs into Cash ISAs for under-65s.
What Could a £20,000 Investment Grow To?
Regular contributions can make a substantial difference alongside investment growth. The tables below start with £20,000 and assume payments at the end of each month, with hypothetical annual returns of 3%, 5%, 7%, and 9%, net of fees, converted into equivalent monthly compound rates. All earnings are reinvested; figures exclude tax and inflation and are rounded to the nearest £100.
£20,000 starting amount + £250 monthly contribution
| Period | 3% return | 5% return | 7% return | 9% return |
| 5 years | £39,300 | £42,500 | £45,800 | £49,500 |
| 10 years | £61,700 | £71,200 | £82,100 | £94,800 |
| 15 years | £87,700 | £107,800 | £133,000 | £164,500 |
| 20 years | £117,800 | £154,500 | £204,300 | £271,800 |
| 30 years | £193,200 | £290,300 | £444,600 | £690,900 |
£20,000 starting amount + £500 monthly contribution
| Period | 3% return | 5% return | 7% return | 9% return |
| 5 years | £55,500 | £59,400 | £63,600 | £68,100 |
| 10 years | £96,600 | £109,800 | £124,900 | £142,200 |
| 15 years | £144,300 | £174,000 | £210,700 | £256,200 |
| 20 years | £199,500 | £256,000 | £331,200 | £431,500 |
| 30 years | £337,900 | £494,100 | £737,000 | £1,116,400 |
£20,000 starting amount + £1,000 monthly contribution
| Period | 3% return | 5% return | 7% return | 9% return |
| 5 years | £87,800 | £93,300 | £99,200 | £105,500 |
| 10 years | £166,300 | £186,900 | £210,400 | £237,100 |
| 15 years | £257,400 | £306,400 | £366,300 | £439,500 |
| 20 years | £363,000 | £458,900 | £584,900 | £750,900 |
| 30 years | £627,300 | £901,800 | £1,321,700 | £1,967,500 |
These are illustrations, not forecasts: returns will fluctuate and you could lose money. The totals include your contributions, not just investment gains. If you pay the full £20,000 into an ISA in 2026/27, further contributions must wait until the next tax year or use another account.
What are the risks of investing £20,000?
Before committing your money, consider what could affect its value and your ability to access it:
- Market risk: prices can fall as economic conditions, interest rates and company prospects change. You could get back less than you invest.
- Liquidity risk: some investments can be difficult to sell quickly or without accepting a lower price.
- Credit risk: a bond issuer could fail to pay interest or repay the amount borrowed.
- Political risk: changes in government policy, regulation or international relations can affect investments in the UK and overseas.
- Currency risk: when investing internationally, exchange rate movements can affect the value of your holdings when converted back to pounds sterling.
- Concentration risk: holding too much of one asset, company, or sector increases exposure to that area’s performance. Diversifying helps reduce this risk.
- Behavioural risk: emotional reactions such as panic-selling during downturns or chasing quick gains can undermine your investment strategy.
- Fraud risk: scams can imitate legitimate firms. Check the FCA Firm Checker for the provider’s permissions and contact details; authorisation does not guarantee returns or mean every product is protected.
When deciding how to invest money, keep your essential savings separate and choose investments you understand. Starting with a smaller amount may help you become familiar with the process, but early gains do not prove that a strategy is safe. If potential losses would jeopardise your plans, reconsider how much risk you take.
Five tips to invest £20,000
Keep these principles in mind as you put your plan into practice:
- Use ISA allowances where appropriate.
- Compare total costs and support, including services such as Moneyfarm.
- Take only risks you can afford.
- Diversify your investments.
- Contribute regularly if affordable, without expecting guaranteed returns.
Key Takeaways
A workable plan brings these choices together:
- Keep emergency savings accessible and prioritise expensive debt.
- Match investments and account access rules to your goals and timeframe.
- Use available tax allowances, compare charges and diversify.
- Check that sustainable investments meet your criteria.
- Review your plan as circumstances change, remembering that investment values can fall as well as rise.
FAQ
Choosing how to invest 20k depends on your goals, timeframe and ability to absorb losses. Once emergency savings and expensive debts are covered, a diversified portfolio may suit longer-term plans. An ISA can make investing tax-efficient, but does not remove investment risk.
Start with what you need the money for. Keep enough accessible for emergencies and planned expenses, then consider whether the remainder could go towards debt repayment, your pension or longer-term investments. You do not have to use the whole amount in the same way.
There is no guaranteed investment return. At a hypothetical 5% annual growth rate after fees, £20,000 would gain £1,000 in the first year, before any tax. Actual investments can fall in value, and an ISA’s tax treatment does not determine its performance.
With no further contributions or withdrawals, £20,000 would reach approximately £26,900 at 3% annual growth, £32,600 at 5%, or £39,300 at 7%. These illustrations assume constant returns after fees and reinvested earnings, excluding tax and inflation. Actual results may be lower, including losses.
You can contribute up to £20,000 across your adult ISAs in 2026/27, provided you are eligible and have not already used any of that year’s allowance. You can split it between Cash and Stocks & Shares ISAs; Lifetime ISA contributions have a £4,000 limit within the total.
Eligible deposits with UK-authorised banks, building societies and credit unions have FSCS protection up to £120,000 per person, per authorised institution. Accounts with brands sharing a banking licence count towards the same limit. Inflation can still reduce your money’s purchasing power.
The post Best Way to Invest 20k & best savings account for £20,000 appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 9 minutesAs your family grows, choosing investments for grandchildren can be a way to help the next generation prepare for university costs, a first home or other milestones. You may also want to support their parents with the high cost of raising a child in the UK. The right approach depends on when the money will […]
The post Savings and Investing for Grandchildren in 2026: ISAS, best investments & bonds appeared first on MoneyFarm Insights.
]]>As your family grows, choosing investments for grandchildren can be a way to help the next generation prepare for university costs, a first home or other milestones. You may also want to support their parents with the high cost of raising a child in the UK. The right approach depends on when the money will be needed and how much you can comfortably afford to contribute.
From Junior ISAs and Premium Bonds to children’s pension schemes, the UK market offers a wide range of solutions. However, these products differ in how the money is taxed, the risks involved and when your grandchild can access it.
In this guide, we explore the main savings and investment options for 2026/27 and what to consider when choosing between them, based on your risk appetite, time horizon, and financial capacity.
| What are the main savings and investment options for grandchildren? | Junior ISAs, children’s savings accounts, Premium Bonds, children’s pensions and trusts. Existing Child Trust Funds can also receive contributions. |
| Can I open a savings account online for my grandchild? | Some providers allow this, but eligibility and documentation requirements vary. For a Junior ISA, grandparents generally need parental responsibility to open an account for a child under 16. |
| How much can a grandparent give a grandchild tax free? | Each grandparent has a £3,000 annual Inheritance Tax gift exemption, shared across all recipients. Larger gifts may also qualify for exemption, depending on the circumstances. |
| Can I buy premium bonds for my grandchildren? | Yes. Grandparents can buy Premium Bonds for a child under 16, but a nominated parent or guardian manages them until the child turns 16. |
Why Saving and Investing for Your Grandchildren Matters
Investing for your grandchildren can help them meet future expenses while giving your contributions time to grow. The main benefits include:
- Financial Security: early contributions can ease future costs such as university tuition or a first home deposit, reducing reliance on debt.
- Compound Growth: the sooner you start, the more time interest and reinvested returns have to generate further growth, although investment returns are not guaranteed.
- Legacy planning: it is a meaningful way to pass on both wealth and financial values, supporting future generations.
- Tax efficiency: products like Junior ISAs allow you to contribute up to £9,000 per child per tax year (2026/27), shared across all contributors and both Junior ISA types, with tax-free interest, dividends and capital gains.
Investing for Grandchildren in the UK: the main options
Below is an overview of the most common options available to UK grandparents, with their main features. Alongside tax benefits, consider when your grandchild can access the money and whether its value could fall.
| Investment Option | Access Age | Tax Treatment | Risk Level | Typical Use Case |
| Junior ISA (JISA) | 18 | Tax-free interest, investment income and gains; £9,000 combined contribution limit for 2026/27 | Cash: inflation risk. Stocks & Shares: risk depends on the investments held | Long-term growth for university fees or first home deposit |
| Child Trust Fund (CTF) | 18 | Tax-free growth; no new accounts since 2011 but existing accounts can be topped up | Depends on whether the account holds cash or investments | Continuing to save in an existing account for an eligible child |
| Premium Bonds (NS&I) | Parent or guardian manages until 16; withdrawals possible before then | Tax-free prize winnings | Government-backed capital; no guaranteed return and inflation risk | Lump sums with chance-based returns |
| Children’s Savings Account | Varies by provider | Interest subject to the child’s available tax allowances | Inflation risk; check deposit protection | Short-term savings and money education |
| Child’s Pension (Stakeholder or SIPP) | Normally 57 from April 2028; rules may change before the child retires | For an eligible child with no earnings, £2,880 net annual contributions can receive £720 tax relief | Depends on the investments held | Very long-term wealth building |
| Trusts | Depends on trust type and applicable law | Depends on structure; tax and reporting obligations may apply | Depends on the assets held | Managing how and when beneficiaries receive money, depending on the trust |
Your choice depends on when you expect the money to be used and your comfort with risk. The account’s withdrawal rules also need to match that timeframe.
- Under 5 years → cash savings may suit nearer-term needs but check access restrictions: a Cash Junior ISA normally cannot be withdrawn before 18. Premium Bonds offer no guaranteed return.
- 5–10 years → a diversified investment portfolio may be worth considering if you can accept losses. Bonds and bond funds can also fall in value.
- 10+ years → a Stocks & Shares JISA gives investments more time to grow, although returns remain uncertain. A child’s pension serves a different purpose, as the money is normally inaccessible until pension age.
As the spending date approaches, review whether the level of risk still suits your grandchild’s needs.
Below is a practical example showing how regular contributions could help you build a fund to invest for your grandchildren’s future.
University Savings Plan. If contributions begin in 2026/27, when your grandchild turns five, paying £100 into a Cash JISA at the end of each month for 13 years could build a tax-free pot of around £19,000 by their 18th birthday, assuming a constant annual interest rate of 3% AER and unchanged tax treatment. Over those 13 years, you would contribute £15,600, with interest adding approximately £3,400.
This is an illustration, not a forecast or a current product rate. It assumes monthly compounding at the equivalent monthly rate, no charges and no withdrawals. Actual interest rates may change, and inflation will affect what the money can buy. At 18, your grandchild can decide how to use it, even if you intended it for university.
How much can you save for grandchildren tax-free?
The limits below cover different things: gift exemptions concern Inheritance Tax, while account limits determine how much you can contribute or hold.
- Annual Gift Allowance: each grandparent can give up to £3,000 per tax year under the annual Inheritance Tax exemption. This total is shared across all recipients, not available separately for each grandchild.
- Carry Forward: unused allowance can be carried forward one tax year (giving a total exemption of up to £6,000 if the previous year’s allowance is entirely unused).
- Junior ISA Allowance: £9,000 per child per tax year (2026/27), shared across Cash and Stocks & Shares Junior ISAs and all contributors.
- Premium Bonds Limit: up to £50,000 per child, held by NS&I. This is a total holding limit, not an annual allowance; prizes are tax-free.
Giving more than £3,000 does not automatically trigger tax. Other exemptions or the seven-year rule may apply, as explained below.
What Type of Accounts Can Grandparents Open for Their Grandchildren?
The accounts you can open yourself depend on the provider’s rules and whether you have parental responsibility. Even where you cannot open an account, you may still be able to contribute.
Your choice will also depend on how much flexibility you need and when you want your grandchild to receive the money. The main arrangements are:
- Children’s regular savings accounts – typically offered by high street banks and building societies, these accounts allow you to make small, regular contributions. Check whether grandparents can open them, alongside deposit limits and withdrawal conditions.
- Junior ISAs (JISAs) – tax-free investment or cash accounts that require a parent or guardian with parental responsibility to open them for a child under 16. Those aged 16 or 17 can open their own. Anyone can contribute within the child’s combined annual allowance.
- Children’s pension schemes – a parent or guardian usually opens the pension, and grandparents can contribute. For an eligible child with no earnings, total annual payments of £2,880 can become £3,600 with tax relief. The normal minimum pension age is 55 in 2026/27, rising to 57 from 6 April 2028, although it may change again before today’s children retire.
- Trusts – grandparents can arrange a trust, but control and access depend on its structure. A discretionary trust gives trustees flexibility over distributions; a bare trust gives the beneficiary an absolute entitlement. Seek advice on the legal requirements, tax and costs.
- NS&I Premium Bonds – grandparents can buy these for children under 16, but a nominated parent or guardian manages them until the child turns 16. While they don’t pay interest, they offer the chance to win tax-free prizes in monthly draws.
What’s the Best Way to Set Up a Savings Account for a Grandchild?
The best savings account for your grandchild will depend on a few key factors:
- Purpose of the savings – is it for general use, education, a house deposit, or long-term wealth?
- Access requirements – will the money be needed during childhood, at 18 or later?
- Contribution frequency – are you planning to make a lump sum deposit, regular payments, or occasional gifts?
Before opening an account, check the provider’s identification requirements, interest rates and withdrawal conditions. For investments, compare platform, management and fund charges, including minimum fees.
A Junior ISA normally gives your grandchild unrestricted access at 18. If you want control beyond that age, seek advice about a discretionary trust. A child’s pension, meanwhile, normally prevents withdrawals until pension age.
Can I Open a Savings Account Online for My Grandchild?
Some UK banks and building societies allow grandparents to apply online, although eligibility and documentation vary. You may need:
- The child’s full name and date of birth
- The child’s birth certificate
- Your own identification as the adult applying for the account
Some providers may require you to be a UK resident or an existing customer to apply online. Check their requirements first, as you may need to apply in a branch instead.
How Much Can a Grandparent Give to a Grandchild Tax-Free?
Under HMRC’s Inheritance Tax rules, each grandparent has a £3,000 annual gift exemption, shared across all recipients.
If unused, this allowance can be carried forward one tax year, meaning you could gift up to £6,000 under this exemption if the previous year’s allowance is entirely unused.
Gifts above this limit may still be exempt if made as regular gifts out of surplus income, without reducing your usual standard of living. Larger outright gifts generally fall outside your estate if you survive seven years; gifts into trusts follow different rules.
When comparing the best ISAs for babies and children, remember that tax-free returns do not automatically make contributions exempt from Inheritance Tax. Seek professional advice if your circumstances are complex.
Can I buy premium bonds for my grandchildren?
Buying premium bonds for grandchildren under 16 allows grandparents to give them a savings gift backed by HM Treasury. Issued by NS&I, these Bonds pay no interest but offer the chance to win tax-free prizes from £25 to £1 million in monthly draws.
Each purchase must be at least £25, and the child’s total holding cannot exceed £50,000. A nominated parent or guardian manages the Bonds until the child turns 16 and can cash them in earlier on the child’s behalf.
As at 12 October 2026, the variable annual prize fund rate is 4.35%, with monthly odds of 21,000 to one per £1 Bond.
For example, £100 buys 100 £1 Bonds, each with a separate chance of winning in every eligible monthly draw. The prize fund rate determines the overall prize pool, not your grandchild’s return: they may win nothing, and inflation can reduce the purchasing power of their savings.
Common mistakes to avoid when investing and saving for your Grandchildren
Even with a suitable account, a few oversights can undermine your plans:
- Choosing the wrong savings or investment account: match access rules, risk and charges to your grandchild’s needs, while keeping enough money for your own.
- Non-diversified investments: spreading investments across assets and markets reduces reliance on any one holding, although it cannot eliminate losses.
- Tax implications: keep records of gifts and coordinate contributions with parents to avoid exceeding account allowances. Seek advice if the tax treatment is unclear.
- Not starting early: starting sooner gives contributions more time to grow, but only commit amounts you can comfortably afford.
- Lack of communication: discuss your intentions with the family and help your grandchild prepare to manage the money when they gain access.
How can you leave money to grandchildren in your will?
Alongside gifts during your lifetime, you may want to leave money to your grandchildren through your will. This can be done directly or through a trust, depending on your wishes and their circumstances. If they may inherit while still children, a solicitor can help you decide who will manage the money and when they can access it.
The amount they receive may depend on your estate’s tax position. Under current Inheritance Tax rules, the standard tax-free threshold is £325,000, with 40% normally charged on the taxable amount above the available threshold. However, leaving a qualifying home to children or grandchildren can increase this to £500,000, subject to conditions. These thresholds apply to your estate rather than separately to each grandchild, while exemptions and allowances transferred from a late spouse or civil partner may also affect the calculation.
Key Takeaways
- Start early where possible, choosing accounts and investments that suit when your grandchild will need the money.
- Use tax-efficient products like JISAs and pensions where their access rules fit your plans.
- Balance growth potential with the risk you are willing and able to take.
- Diversify between different asset types and review your plan regularly.
- Speak to an FCA-authorised financial adviser if you need help assessing whether your choices suit your circumstances.
FAQ
They are government-backed savings products that pay no interest. Instead, each eligible £1 Bond enters monthly draws for tax-free prizes. Winnings are not guaranteed.
The standard threshold is £325,000 per estate. A qualifying home left to direct descendants may increase it to £500,000, subject to conditions. The standard 40% rate applies to the taxable amount above the available threshold.
The annual allowance on Junior ISAs for 2026/27 is £9,000. This covers all contributors and both Cash and Stocks & Shares Junior ISAs combined.
The right choice depends on when the money will be needed and how much risk you can accept. Cash may suit shorter-term needs, while diversified investments offer longer-term growth potential but can lose value. Check access restrictions too.
Only if they have parental responsibility for a child under 16. Otherwise, they can contribute to an existing account. Children aged 16 or 17 can open their own Junior ISA.
The £3,000 figure is an annual Inheritance Tax exemption, not a limit on giving. Larger gifts may qualify for other exemptions or fall outside your estate if you survive seven years, depending on the arrangement.
The post Savings and Investing for Grandchildren in 2026: ISAS, best investments & bonds appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 8 minutesThe cost of living in Scotland can vary considerably depending on where you live, the type of accommodation you choose and your lifestyle. Edinburgh is generally more expensive than cities such as Glasgow or Aberdeen, while smaller towns and rural areas can offer lower housing costs. For most people, rent is likely to be the […]
The post Cost of living in Scotland in 2026: prices and how to afford it appeared first on MoneyFarm Insights.
]]>The cost of living in Scotland can vary considerably depending on where you live, the type of accommodation you choose and your lifestyle. Edinburgh is generally more expensive than cities such as Glasgow or Aberdeen, while smaller towns and rural areas can offer lower housing costs. For most people, rent is likely to be the largest monthly expense.
So, how much does it cost to live in Scotland in 2026? This guide looks at the main living costs, from housing and household bills to transport and food, using the latest available data to help you plan your monthly budget.
| How much do you need to live comfortably in Scotland? | There is no single figure that applies to everyone. The amount you need depends mainly on where you live, your housing costs, household size and lifestyle. |
| Is rent expensive in Scotland? | The average private rent in Scotland was £1,013 per month in August 2026, although costs vary considerably by area and property type. |
| How much does it cost to live in Scotland per month? | Monthly living costs vary significantly across Scotland, particularly because of differences in rent. Edinburgh is generally more expensive than Glasgow and many other parts of the country. |
How much do you need to live comfortably in Scotland?
There is no single income that guarantees a comfortable standard of living in Scotland. The amount you need depends largely on where you live, your housing costs, household size and lifestyle. Someone renting alone in Edinburgh, for example, is likely to need a higher budget than someone sharing accommodation or living in a less expensive part of the country.
According to the latest Scottish Government Labour Market Trends data, median monthly pay for payrolled employees in Scotland was £2,686 in August 2026, up 3.6% compared with the same month in 2025.
However, average or median earnings do not determine how much someone needs to live comfortably. Housing costs, transport, household bills and everyday spending can vary considerably across Scotland, so comparing your take-home income with your own monthly expenses provides a more realistic measure of affordability.
Is rent expensive in Scotland?
According to the Office for National Statistics (ONS), the average monthly private rent in Scotland reached £1,013 in August 2026, up 1.1% from £1,002 a year earlier. For comparison, the average monthly rent in England was £1,459, although rental costs vary considerably depending on location and property size.
For one-bedroom properties, average monthly rents ranged from £1,035 in Lothian and £843 in Greater Glasgow to £601 in Aberdeen and Shire, £571 in Dundee and Angus and £427 in Dumfries and Galloway.
| Rental area | Average monthly rent for a one-bedroom property |
| Lothian | £1,035 |
| Greater Glasgow | £843 |
| Aberdeen and Shire | £601 |
| Dundee and Angus | £571 |
| Dumfries and Galloway | £427 |
These differences show why location is one of the main factors affecting housing costs in Scotland, and why the national average should be considered alongside local rents.
How much does it cost to live in Scotland per month?
Monthly living costs in Scotland vary depending on location, household size and lifestyle. Beyond rent, the main recurring expenses include household bills, groceries and transport, so looking at these costs separately gives a more realistic picture of the budget required.
Utilities
Energy remains an important part of household spending. According to Ofgem, from 1 October to 31 December 2026 the energy price cap for a typical household paying by Direct Debit for gas and electricity is £1,723 a year, equivalent to around £144 per month if that level were sustained over a full year.
The price cap limits the unit rates and standing charges suppliers can apply to default tariffs, rather than setting a maximum household bill. Actual spending therefore depends on energy use, payment method and tariff.
Council Tax and water charges
For most homes in Scotland, Council Tax is billed alongside water and wastewater charges. The amount of Council Tax depends on the property band and the rates set by the local council, while discounts, reductions or exemptions may apply in some circumstances.
According to Scottish Water, unmetered water and wastewater charges for 2026/27 range from £434.88 a year for Band A to £1,304.64 for Band H. For a Band D property, the combined annual charge is £652.32, equivalent to around £54 per month when spread across a year.
Alongside energy and water charges, broadband and mobile services should also be included in a monthly household budget. The latest available Ofcom data provide additional benchmarks for these recurring costs.
| Household cost | Latest monthly benchmark |
| Energy price cap benchmark | Around £144 |
| Water and wastewater, Band D | Around £54 |
| Standalone fixed broadband | Around £31 |
| Post-pay mobile service | Around £15.50 |
The figures are benchmarks rather than fixed bills. Actual household spending depends on usage, property band, provider and contract.
Groceries
Food remains an important part of household spending in Scotland. According to the Scottish Government’s September 2026 economic analysis, food prices were around 39% higher in July 2026 than in January 2021, compared with growth of approximately 33% in mean earnings in Scotland over the same period.
Although annual food price inflation had eased to 1.2% in July 2026, prices remained substantially above pre-cost-of-living-crisis levels. The amount spent on groceries therefore varies considerably depending on household size, shopping habits and the types of products bought.
Transport
Transport costs in Scotland depend on where you live and how often you travel. Since September 2025, ScotRail peak fares have been permanently removed, so passengers pay the same reduced Anytime fare regardless of the time of day. Fares were also frozen for 12 months from April 2026.
Bus costs vary by area and operator. In 2026, Transport Scotland is operating a £2 single-fare cap on participating services in selected areas, while residents aged 5 to 21 can travel free on most buses across Scotland with a National Entitlement Card (NEC).
| Transport cost or scheme | 2026 cost or rule |
| Participating bus services | £2 maximum single fare |
| ScotRail | Peak fares permanently removed; fares depend on the route |
| Bus travel for eligible residents aged 5–21 | Free with NEC |
| Unleaded petrol | Around £1.73 per litre |
For drivers, official UK fuel statistics show that the average price of unleaded petrol was 173.46p per litre in the week beginning 28 September 2026. Actual transport spending therefore depends heavily on location, commuting habits and eligibility for concessionary travel.
Healthcare costs in Scotland
Healthcare costs in Scotland differ from those in some other parts of the UK. NHS prescriptions are free in Scotland, while NHS eye examinations are also free in Scotland for people who usually live in the UK.
Dental examinations are free, but NHS dental treatment may still involve charges. Patients who pay for treatment generally contribute 80% of the cost, with charges capped at £384 per course of treatment. Some people, including certain younger patients and those who qualify for exemptions, may receive treatment free of charge.
Childcare and education
Families with young children may be able to reduce childcare costs through Scotland’s funded early learning and childcare scheme. All 3- and 4-year-olds, as well as eligible 2-year-olds, can receive up to 1,140 hours of funded childcare per year, equivalent to around 30 hours a week during term time or 22 hours when spread across the year.
For school-age children, every child in Scotland has the right to a free place at school, although families may still need to budget for expenses such as uniforms, activities and transport.
Eating out and entertainment
Eating out and leisure can add significantly to discretionary spending. According to Food Standards Scotland research published in 2026, people in Scotland bought food or drink out of home three to four times a week on average, spending around £6.30 per visit in 2025.
Prices have continued to rise since then. ONS data for August 2026 show annual inflation of 4.1% for restaurants and hotels and 1.6% for recreation and culture across the UK. How much you spend will therefore depend largely on how often you eat out, socialise or pay for leisure activities.
Clothing and personal expenses
Clothing and personal spending can vary considerably depending on shopping habits and lifestyle. The latest ONS inflation data provide a useful UK-wide benchmark. In August 2026, clothing and footwear prices were 0.2% higher than a year earlier, compared with overall CPI inflation of 3.1%.
Within the category, clothing prices increased by 0.6%, while footwear prices fell by 1.9% over the year. These figures suggest that clothing costs were relatively stable compared with many other areas of household spending.
Example monthly budget in Scotland
Putting the different living costs together can give a clearer idea of the monthly budget you may need. The example below is based on one person renting a one-bedroom property in Greater Glasgow and combines current 2026 costs with the latest official expenditure benchmarks available.
| Expense | Illustrative monthly cost |
| Monthly rent | £843 |
| Energy price cap benchmark | £144 |
| Water and wastewater | £54 |
| Council Tax | £127 |
| Broadband and mobile | £46.50 |
| Food and non-alcoholic drinks | Around £185 |
| Public transport | Around £42 |
| Total | Around £1,442 |
This is only an illustrative budget. Actual monthly spending can be higher or lower depending on where you live, the property you rent, your energy use, transport needs and lifestyle. The estimate also excludes discretionary expenses such as clothing, eating out and entertainment. Council Tax and water and wastewater charges may also be lower where discounts or reductions apply.
How to reduce the cost of living in Scotland
Reducing living costs in Scotland often starts with the expenses that vary most by location. A few practical choices can help keep monthly spending under control.
- Compare rents across different areas, rather than relying only on national averages;
- check Council Tax bands and commuting costs before deciding where to live;
- review energy, broadband and mobile contracts regularly and compare available deals;
- make use of transport discounts or concessions you qualify for and set a realistic budget for groceries and other everyday spending.
Building an emergency fund can also make it easier to deal with unexpected expenses without affecting your longer-term financial plans.
Financial tips
Once essential living costs are covered, building an emergency fund can help protect your budget from unexpected expenses. If you have money left over that you can afford to invest for the long term, you may consider investing in line with your financial goals, time horizon and attitude to risk.
Moneyfarm offers different ways to invest, including diversified portfolios and a General Investment Account (GIA). A GIA has no annual contribution limit, although any tax due will depend on your individual circumstances. Whatever approach you choose, investing involves risk and the value of your investments can fall as well as rise. It should therefore be considered as part of a broader long-term financial plan, rather than as a way to cover everyday living costs.
FAQs
Living costs vary considerably by area and household circumstances. However, the average private rent reported by the ONS was lower in Scotland than in England in August 2026. The average monthly private rent was £1,013 in Scotland, compared with £1,459 in England. Other costs, including transport and household bills, depend on where you live and your lifestyle.
There is no single income that guarantees a comfortable standard of living. As an indication, the illustrative budget in this guide comes to around £1,442 per month for one person renting a one-bedroom property in Greater Glasgow, before discretionary expenses such as clothing, eating out and entertainment. The amount you need will ultimately depend on housing costs, household size, location and lifestyle.
What counts as a good salary depends on your circumstances and regular expenses. As a benchmark, median monthly pay for payrolled employees in Scotland was £2,686 in August 2026, up 3.6% compared with August 2025. This provides a useful reference point for earnings, but it should not be treated as a fixed threshold for a comfortable lifestyle.
For renters, Greater Glasgow is generally more affordable than Lothian, the rental area that includes Edinburgh. In August 2026, the average monthly rent for a one-bedroom property was £843 in Greater Glasgow, compared with £1,035 in Lothian.
According to the Office for National Statistics, the average monthly private rent in Scotland was £1,013 in August 2026. Actual rents vary considerably depending on the location and size of the property.
Yes. NHS prescriptions are free in Scotland. However, some other healthcare services, including certain NHS dental treatments, may still involve charges.
The post Cost of living in Scotland in 2026: prices and how to afford it appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesSaving for retirement starts with a personal question: what would you like life to look like when work no longer shapes your days? You might picture more time with family, regular travel or simply the freedom to cover everyday expenses without worrying about your next payslip. Turning that picture into a financial plan means considering […]
The post Saving for Retirement in the UK: A Complete Guide appeared first on MoneyFarm Insights.
]]>Saving for retirement starts with a personal question: what would you like life to look like when work no longer shapes your days? You might picture more time with family, regular travel or simply the freedom to cover everyday expenses without worrying about your next payslip.
Turning that picture into a financial plan means considering what your retirement could cost, how much income you can expect and how to make up any shortfall. Let’s look at how the State Pension, workplace pensions and your own savings can fit together, whether you’re starting out or reviewing plans closer to retirement.
Why saving for retirement matters
Those plans need an income that can last throughout retirement. Some expenses, such as commuting, may fall once you stop working, but housing, food and household bills remain. Your budget also needs room for unexpected costs and changing needs over time.
The State Pension provides a foundation, although it may not cover the lifestyle you have in mind. In the 2026/27 tax year, the full new State Pension is £241.30 a week, or around £12,548 over 52 weeks. Your entitlement depends on your National Insurance record, so you should check your own forecast rather than assume you will receive the full rate.
Building additional savings gives you more scope to cover the gap between that income and your spending. It can also make reducing your working hours or retiring before State Pension age more achievable, provided you have money available to bridge the intervening years. That is why retirement planning involves both how much you save and when you will need access to it.
Why you should start saving early
The earlier you start saving for retirement, the more time you have to build your pension pot gradually. This can make the task more manageable in three ways:
- your money has longer to grow: when you invest pension contributions, any returns that stay invested can earn further returns. Over time, growth can therefore come from both the money you pay in and the returns already generated. This is known as compounding, although returns are not guaranteed and investments can fall in value.
- you can spread the cost across more working years: starting with an affordable monthly contribution means you do not have to leave all the saving until later. As your earnings increase, you may be able to raise your contributions too. By contrast, delaying your start leaves fewer years to build the same pension pot, which may require much larger monthly payments.
- you have more time to respond to changes: your income and commitments are unlikely to stay the same throughout your career. If caring responsibilities or a career break interrupt your contributions, starting early gives you more time afterwards to review your savings and address any shortfall. The same applies if your retirement plans change and you decide you will need a higher income.
Starting later is still worthwhile. The next step is to work out what you can realistically contribute and whether your planned retirement date and spending expectations remain achievable. Whatever your starting point, though, your plan also needs to account for inflation: the amount you save today may buy less by the time you retire.
How inflation affects your retirement savings
Having more money saved does not necessarily mean you can afford more. If prices rise faster than your savings grow, your purchasing power falls: the same amount buys fewer goods and services.
For example, assuming inflation stayed at 2% a year, £1,000 held without earning any interest or investment returns would have the purchasing power of around £673 in today’s money after 20 years. This is an illustration, not a forecast, but it shows why your retirement plan needs to account for rising prices in three areas:
- your savings target: a pension pot based only on today’s living costs may fall short of what you need when you retire. Reviewing that target over time allows you to adjust your contributions as your estimated costs change.
- your retirement income: an income that stays fixed will buy less as prices rise. Some annuities provide an increasing income, but others pay a level amount, so check how payments would change over time before choosing a product.
- your everyday budget: food, energy and other essentials will not necessarily rise in price at the same rate. Your spending habits will change too, so reviewing your own budget gives you a more useful picture than relying on a general inflation assumption alone.
How to manage risk in your pension savings
Responding to inflation does not mean taking more investment risk than you can afford. For an invested pension pot, the aim is to balance opportunities for growth with the losses you could withstand.
In practice, this means looking at where your pension is invested, when you will need the money and whether your plan still suits your circumstances:
- spread your investments: holding a mix of assets, sectors and countries reduces reliance on any single investment. Diversified funds can provide this exposure, although diversification cannot prevent all losses.
- match your investments to your withdrawal plans: money you expect to use soon needs different consideration from savings that could remain invested for another decade. Approaching retirement does not necessarily mean withdrawing your whole pension at once, so your investment choices should reflect how you intend to use it.
- review your pension regularly: check your contributions, charges and investment mix at least annually, and after significant changes in your circumstances. As MoneyHelper explains, your choices should reflect both your retirement goals and your attitude to risk.
To assess whether those choices are suitable, you first need an estimate of the income your savings will have to provide.
How much money will I need to retire?
The starting point is your expected spending, rather than a pension pot chosen in isolation. Where you live, whether you still pay rent or a mortgage, and whether you share household costs will all influence how much income you need. Holidays, hobbies and support for family members then add to that budget.
To put those choices into figures, the Retirement Living Standards, developed by Pensions UK with Loughborough University, provide three spending benchmarks. The 2026 figures below show annual costs for a one-person household:
| Living standard | Outside London, per year | London, per year |
| Minimum | £13,900 | £14,600 |
| Moderate | £32,700 | £34,000 |
| Comfortable | £45,400 | £47,200 |
These are spending estimates, not gross income targets. You need enough income after tax to cover them. They include everyday household bills but exclude rent, mortgage payments and social care, which must be budgeted for separately where relevant. Other personal costs, such as supporting dependants, may also increase your total.
Turning a spending target into a savings plan
Use the closest benchmark as a starting point, then adjust it to your circumstances. Once you have an annual budget, compare it with the income you expect from your State Pension and any pensions that pay a guaranteed income. Use after-tax figures throughout so the comparison is consistent.
The remaining gap is what your invested pensions and other savings would need to cover. There is no single pension pot that will suit everyone: the amount required depends on when you retire, how long the money must last, investment returns, charges and how you take withdrawals. If retirement is still some years away, revisit the budget regularly to allow for inflation and changes in your plans.
A practical example of planning your retirement income
Suppose you expect to spend £24,000 a year in retirement, including bills, food, transport and holidays. You own your home outright and have adjusted this budget to your circumstances, using today’s prices.
Your projected State Pension and a workplace pension that pays a guaranteed income would together provide £18,000 a year after tax, also expressed in today’s money. That leaves £6,000 a year, or £500 a month, to fund from other savings.
This gap gives you a clearer planning target, but it does not tell you the pension pot required. That depends on how long you need the additional income and how your savings perform. If you retire before either pension starts, you will also need accessible savings to cover the larger shortfall during those years.
Ways to save for retirement in the UK
Once you know what your savings need to provide, you can consider where to build them. Pensions offer tax advantages and, through a workplace scheme, employer contributions. ISAs can complement them by keeping some money accessible before pension withdrawals are permitted. The right combination depends on your employment, tax position and retirement plans.
| Option | Role in your retirement plan | What to consider |
| Workplace pension | Builds retirement benefits through contributions from you and your employer, with tax relief where eligible. | Check whether your employer will contribute more if you increase your payments. Benefits and investment choices depend on the scheme. |
| Personal pension, including a self-invested personal pension (SIPP) | Provides a pension you arrange yourself, whether alongside a workplace scheme or when self-employed. | Compare charges, investment options and support. Tax relief and access restrictions apply. |
| Stocks and Shares ISA | Holds investments with no UK tax on income or capital gains and allows withdrawals before pension access age. | There is no upfront pension tax relief. Investments can fall in value, making this unsuitable for money you need to rely on in the short term. |
For 2026/27, the standard pension annual allowance is £60,000 across your pensions, including employer contributions and tax relief. Defined benefit pension growth also counts. Lower limits can apply to high earners or after certain flexible withdrawals. Separately, tax relief on personal contributions is generally limited by your relevant UK earnings.
A Moneyfarm personal pension is one option to explore when comparing SIPPs. Pension money is usually accessible from age 55, rising to 57 from 6 April 2028, although exceptions apply.
For savings you may need earlier, a Stocks and Shares ISA offers greater access flexibility. The overall ISA subscription allowance is £20,000 in 2026/27. Keep emergency money separately in accessible cash, so an unexpected bill does not force you to sell investments during a market downturn. Tax treatment depends on individual circumstances and may change.
FAQ
Start with your expected retirement spending and compare it with your projected pension income. A pension calculator can then estimate the monthly contributions needed to cover the gap. Include employer contributions and review the assumptions: investment returns, inflation and your retirement date can change the estimate.
Starting at 40 still gives you time to build savings. Check any pensions from previous jobs before deciding how much to contribute. You may already have more saved than you realise, although reaching your target could require higher contributions than if you had started earlier.
A pension offers tax relief where eligible, and a workplace scheme includes employer contributions. An ISA provides more flexible access. Using both can balance retirement saving with earlier spending needs, but check your workplace benefits before directing additional savings elsewhere.
A personal pension or SIPP allows you to make your own contributions and receive tax relief where eligible. If your income varies, consider an affordable regular payment with additional contributions when cash flow allows, keeping enough accessible money for tax bills and business expenses.
You can usually leave an existing pension invested even if contributions stop. Depending on your eligibility, you may also receive tax relief on limited personal contributions without earnings. Check your provider’s rules and keep your retirement projections under review during the break.
A larger pot gives you more resources, but its purchasing power and how long it lasts depend on inflation, charges, investment performance and withdrawals. Assess it alongside guaranteed income and your spending needs, rather than treating a particular balance as a guarantee.
The post Saving for Retirement in the UK: A Complete Guide appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesThe Autumn Budget lands on Wednesday 28 October 2026 and as usual the weeks before it have been full of headlines about what might change. Speculation is not policy, though. What you can control today is whether you are using the allowances that already exist. In this article we walk through the main tax allowances […]
The post Budget is coming: are you making the most of your allowances? appeared first on MoneyFarm Insights.
]]>The Autumn Budget lands on Wednesday 28 October 2026 and as usual the weeks before it have been full of headlines about what might change. Speculation is not policy, though. What you can control today is whether you are using the allowances that already exist.
In this article we walk through the main tax allowances available to UK investors in the 2026/27 tax year: Individual Savings Accounts (ISAs), pensions, Junior ISAs and the allowances that apply to a General Investment Account (GIA). For each, we set out how it works today, what has already been confirmed for the future, and what has been speculated ahead of the Budget.
ISAs: your £20,000 annual allowance
Every UK adult resident can put up to £20,000 into ISAs in the 2026/27 tax year, which runs to 5 April 2027. Any growth, interest or dividends earned inside an ISA are free of UK income tax and capital gains tax, and you don’t need to declare them on a tax return.
A few things worth knowing:
It’s use it or lose it: unused allowance does not carry forward to the next tax year.
You can split it: the £20,000 can be spread across Stocks & Shares, Cash, Lifetime and Innovative Finance ISAs.
Timing matters: investing earlier in the tax year gives your money longer to potentially grow tax-free, although markets can fall as well as rise.
What’s already confirmed
From 6 April 2027, savers under 65 will only be able to put up to £12,000 a year into Cash ISAs. The overall £20,000 allowance stays the same, so the remaining £8,000 can go into other ISA types such as a Stocks & Shares ISA. Savers aged 65 and over keep the full £20,000 cash limit.
What’s been speculated
Reports in September suggested a new first-time buyer ISA could be announced, possibly replacing the Lifetime ISA and removing its under-40 age limit. Nothing has been confirmed.
We have not seen credible reports of a change to the headline £20,000 allowance, but nothing is certain until the Chancellor speaks.
Pensions: tax relief and the annual allowance
Pensions remain one of the most tax-efficient ways to save for retirement. Contributions receive tax relief at your marginal rate of income tax, so a £100 contribution costs a basic-rate taxpayer £80, and higher and additional-rate taxpayers can claim back more through Self Assessment.
Annual allowance: up to £60,000 a year, or 100% of your relevant UK earnings if lower.
Carry forward: you may be able to use unused annual allowance from the previous three tax years, provided you were a member of a registered pension scheme in those years.
Tapered allowance: if your adjusted income is above £260,000 (and threshold income above £200,000), your allowance can fall to as little as £10,000.
Money Purchase Annual Allowance (MPAA): once you start flexibly drawing from a defined contribution pension, the amount you can pay in with tax relief generally drops to £10,000 a year.
Tax-free cash: most people can take 25% of their pension tax-free, up to a lifetime Lump Sum Allowance of £268,275.
Access age: you can currently access private pensions from 55, rising to 57 from April 2028.
Pension contributions can also reduce your taxable income. That matters if your income sits near a threshold, such as £100,000, where the personal allowance starts to be withdrawn.
What’s already confirmed
Inheritance tax on pensions: from 6 April 2027, most unused pension funds and death benefits will count towards your estate for inheritance tax purposes.
Salary sacrifice: from April 2029, National Insurance relief on pension contributions made through salary sacrifice will only apply to the first £2,000 a year.
Frozen thresholds: income tax thresholds are frozen until 5 April 2031, so more people may drift into higher tax bands over time.
Why pensions still stand out, even with the inheritance tax change
The inheritance tax change has led some people to ask whether pensions are still worth it. For most people saving for their own retirement, the answer is yes. The reason is simple. With a pension, the money that would have gone to the taxman as income tax is invested for you as well. More money invested from day one means more money that can grow and compound over time.
An example
John wants to put £10,000 a year aside for 20 years. He can do one of two things:
Put it in an ISA: £10,000 a year is invested.
Pay it into a Self-invested personal pension (SIPP): the government adds 25% basic-rate tax relief, so £12,500 a year is invested.
Assume both grow at 7% a year after charges for 20 years:
After 20 years, assuming 7% growth a year, John’s SIPP is worth £109,663 more than his ISA. Unlike the ISA, he’ll pay income tax on most of what he takes from his pension.
Paying a higher rate of tax?
If you pay income tax at more than 20%, a pension can be even more valuable. The 25% top-up only covers basic-rate relief, but higher and additional-rate taxpayers can claim back the extra through their Self Assessment tax return or by contacting HMRC.
Higher-rate taxpayers (40%) can claim back a further 20%. On John’s £10,000 a year, that’s an extra £2,500 back each year, so each £12,500 in his SIPP costs him £7,500.
Additional-rate taxpayers (45%) can claim back a further 25%. That’s £3,125 a year, so each £12,500 in his SIPP costs him £6,875.
If John were a higher-rate taxpayer and invested his £2,500 a year rebate in his ISA, it could grow to around £109,663 over 20 years at the same 7%. That’s on top of the figures in the table.
You can only claim the extra relief on income you’ve paid higher or additional-rate tax on, and it isn’t added automatically, so it’s worth checking you’ve claimed it.
What about inheritance tax?
ISAs have always counted towards your estate for inheritance tax. From April 2027, pensions will be treated in a similar way, so the change brings them closer to ISAs rather than putting them behind. If John died with both pots untouched and inheritance tax applied at 40%, his SIPP would leave £328,989 compared with £263,191 from the ISA. Pensions left to a spouse or civil partner will generally remain free of inheritance tax. Beneficiaries may also pay income tax on inherited pensions if the person dies after age 75, so it’s worth getting advice if passing on wealth is a priority.
This example is for illustration only. It ignores National Insurance and charges beyond those built into the growth rate. Investment growth is not guaranteed, the value of investments can fall as well as rise, and tax rules can change.
What’s been speculated
Tax-free cash: there has been talk of cutting the tax-free lump sum, with one figure mentioned being £100,000. Similar rumours came up before the 2024 and 2025 Budgets and tax-free cash was largely left alone both times.
State pension: reports suggest the triple lock could be kept until 2030 and then reviewed.
It’s worth being cautious about acting on rumours. Before a previous Budget, some people withdrew tax-free cash early because of speculation that never came true, leaving money outside a pension wrapper that they could not put back.
Junior ISAs: £9,000 a year for children
A Junior ISA (JISA) lets parents, grandparents and others put up to £9,000 a year in total into a tax-efficient account for a child under 18. This is separate from your own £20,000 ISA allowance.
- Growth and income inside a JISA are free of UK tax.
- The money belongs to the child. They can take control of the account at 16 but cannot withdraw until they turn 18.
- At 18, the JISA becomes an adult ISA in their name.
- Like the adult ISA, the allowance resets each tax year and does not carry forward.
For families, a JISA can sit alongside your own ISA and pension as part of a wider plan, for example to help with university costs or a first home.
What’s been speculated
We haven’t seen specific speculation about Junior ISAs ahead of this Budget, and the £9,000 limit has been unchanged since 2020.
General Investment Accounts: capital gains and dividend tax
A General Investment Account (GIA) has no contribution limit, which makes it useful once your ISA and pension allowances are used. The trade-off is that gains and income can be taxable, so two allowances matter here.
Capital gains tax (CGT)
Annual exempt amount: the first £3,000 of gains you make in a tax year is tax-free.
Rates: gains above that are taxed at 18% for basic-rate taxpayers and 24% for higher and additional-rate taxpayers.
Like ISAs, the exempt amount can’t be carried forward.
Dividend tax
Dividend allowance: the first £500 of dividends each year is tax-free.
Rates (from April 2026): 10.75% for basic-rate taxpayers (up from 8.75%), 35.75% for higher-rate (up from 33.75%) and 39.35% for additional-rate taxpayers.
What’s been speculated
CGT rates: CGT is widely reported as a leading option for raising revenue. One proposal would bring CGT rates in line with income tax rates (20%, 40% and 45%), possibly phased in over several years.
CGT on death: there has been discussion of removing the ‘uplift’ that resets gains on death, which could leave beneficiaries facing CGT on long-held assets.
Dividends: some commentators have suggested further increases to dividend rates or a smaller dividend allowance.
None of these measures has been confirmed.
Making sense of it all
Budget speculation can make it tempting to act quickly. In practice, most tax changes announced at a Budget take effect from the following 6 April and changes are only confirmed on Budget day. Decisions that can’t be undone, such as taking pension tax-free cash early, deserve particular care.
A calmer approach is to focus on what’s within your control:
- Check how much of your £20,000 ISA allowance you’ve used this tax year.
- Review your pension contributions and whether carry forward could apply to you.
- Consider whether a Junior ISA has a place in your family’s plans.
- If you hold investments in a GIA, look at whether your CGT and dividend allowances are being used.
As always, it’s important to remember that these are just rumours and speculation. The media often present such possibilities in ways that can pressure individuals into making hasty financial decisions, potentially undermining sound long-term plans.
Knee-jerk reactions in the short term based on speculation can have unintended consequences later on. The most effective strategy is to stick to your long-term financial plan.
Our team of Wealth Managers is staying up to date on all Budget developments and is available to help you cut through the noise.
Join us live on Budget night to find out what’s changed for your tax, your pension and your portfolio.
Live webinar: Wednesday, 28th October at 6pm
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Budget is coming: are you making the most of your allowances? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesAt the beginning of 2023, Anthropic had not yet launched Claude, its flagship product. Few people could have imagined that, within just a few years, it would become a leading contender for one of the most significant IPOs (initial public offerings, or stock market listings) in the tech sector. Yet that is what could happen: […]
The post Anthropic, the IPO that could reshape the AI market appeared first on MoneyFarm Insights.
]]>At the beginning of 2023, Anthropic had not yet launched Claude, its flagship product. Few people could have imagined that, within just a few years, it would become a leading contender for one of the most significant IPOs (initial public offerings, or stock market listings) in the tech sector. Yet that is what could happen: according to media reports, including those published by CNN, the company is aiming to raise between $60 billion and $100 billion, at a valuation of more than $2 trillion.
To put this into perspective, Apple took 44 years to surpass a market capitalisation of $2 trillion (source: Business Today), while Alphabet, Google’s parent company, took around 26 years (source: Advisor Perspectives). Founded in 2021, Anthropic could get there in just five years. In May, its latest private funding round valued the company at $965 billion; in June, SpaceX went public at a valuation of $1.77 trillion, raising around $86 billion (source: S&P Global) and setting the current record.
If you hadn’t noticed, we live in an era of accelerating change, and market cycles reflect this pace too. Anthropic, a company whose mission is to accelerate humanity’s future, is an emblematic example of this period of rapid, disruptive innovation.
The IPO date has not yet been officially announced, but the latest reports suggest a listing after the US midterm elections on 3 November. The potential listing would nevertheless be a significant moment for markets because, for the first time, generative Artificial Intelligence (AI), until now funded by venture capital and technology giants, would be exposed directly and on a large scale to the judgement of public-market investors. In this article, we explore the potential implications of the IPO for investors’ portfolios.
Born out of OpenAI
Anthropic’s story begins with a split. At the end of 2020, Dario Amodei, OpenAI’s Vice President of Research and one of the key figures behind GPT-2 and GPT-3, left the company alongside his sister Daniela and a group of senior colleagues. The disagreement centred on the direction OpenAI had taken following Microsoft’s 2019 investment: a stronger focus on commercialisation, which would accelerate the development of increasingly powerful models. Anthropic was founded on these principles.
In its early years, the company operated more like a research centre than a commercial business. Significant funding followed in 2021, with a $124 million round led by Jaan Tallinn, Skype’s co-founder, which also included former Google CEO Eric Schmidt. As reported by TechCrunch, one of Anthropic’s early backers was Sam Bankman-Fried, the founder of FTX, the cryptocurrency company that went into liquidation following one of the largest bankruptcies in modern history. He invested around $500 million shortly before his company collapsed. That stake was sold by the liquidators in 2024 for just over $1 billion and would probably be worth tens of billions of dollars today. By the summer of the same year, Anthropic already had a chatbot prototype but chose not to release it; in November, ChatGPT became a global phenomenon.
Claude arrived in March 2023. Amazon subsequently invested up to $8 billion in the company by 2024, followed by Google. Both also became key suppliers of computing power. Another important development came in software development: with Claude Code, launched in 2025, developers began delegating entire blocks of work to AI, and Claude became a go-to tool for businesses. In August 2025, 43.8% of the more than 70,000 US businesses using the multinational fintech company Ramp were paying for Anthropic’s services. The figure comes from the Ramp AI Index, which Ramp compiles using its customers’ transaction data.
What media reports suggest
According to those familiar with it, the approximately 300-page prospectus whose contents were leaked to Reuters is an unusual document. Alongside its growth ambitions, around 80 pages are reportedly devoted to warning about the risks of the technology. The document cited by Reuters warns that AI could have catastrophic, or even existential, consequences for humanity. It is rare for a public offering to describe the dangers of its own product so openly.
The central theme reflects the paradox at the heart of Anthropic’s mission. The company argues that making AI safer requires making it more powerful, because only advanced AI can counter the threats generated by AI itself. Yet more powerful AI is also less predictable. The prospectus describes controlled tests in which more autonomous models sabotaged code, assisted fraud and manipulated information. It even refers to behaviours described as “self-preservation”, such as attempts to resist being switched off or actions resembling blackmail. Despite these findings, the company continues to maintain that its primary goal is to build safe AI.
The second notable aspect of the document concerns the scale of the company’s operations and costs. Anthropic reportedly has commitments totalling $518 billion for cloud services, chips and infrastructure over the coming years, against revenue of around $4.6 billion in 2025. According to Reuters, the company has signed agreements with suppliers that would require it to pay for this capacity even if it did not use it. It ended 2025 with a net loss of $42 billion, although around $34 billion of this was an accounting charge related to convertible instruments rather than a cash outflow. In short, frontier AI is an extremely capital-intensive industry, more akin to railways or energy than traditional software. The sustainability of its business model depends on revenue continuing to grow, and the proceeds from the IPO would also help ease this pressure.
The third point concerns governance. According to reports, following the listing, four of the seven board members would be appointed by the Long-Term Benefit Trust, an independent body whose members do not hold shares in the company. Meanwhile, the seven co-founders, through a single Class F share, would control 50.1% of the votes on key decisions. Anyone buying Anthropic shares would therefore participate in its financial performance, but not in its decision-making. This is not unique: Meta and Alphabet, for example, are also founder-controlled. However, Anthropic’s control structure would be even more tightly entrenched and remains a factor worth considering.
A business model focused more on B2B than B2C
Despite the chatbot’s public profile, Anthropic is primarily a business-to-business provider. Public information about its revenue is still incomplete, however, and the figures below are estimates based on media reports and market data published by third-party sources, including Reuters. In 2025, revenue reportedly rose from $386 million to around $4.6 billion, a twelvefold increase. In the second quarter of 2026, it is said to have reached approximately $11.5 billion in just three months.
| Revenue stream | Estimated 2025 revenue | How it works |
| APIs (model usage) | $3.2bn | Businesses integrate Claude into their products and pay according to usage |
| Consumer subscriptions | $924m | An average of 3.5 million paying subscribers at $22 per month |
| Business subscriptions | $403m | An average of 1.2 million business licences at $28 per month |
The core of the business model is therefore the API: the channel through which other companies integrate Claude into their software and services. In 2025, this reportedly accounted for more than two-thirds of revenue. Subscriptions, taken together, are estimated to have generated around $1.3 billion.
One area of concern is customer concentration: almost a quarter of 2025 revenue reportedly came from just two customers. According to market analysis, these were mainly large technology companies’ cloud services, which resell access to the models and retain a commission. Reuters reports that sales through major technology partners (Amazon, Google, Broadcom and Microsoft) accounted for 47% of 2025 revenue. This is an efficient distribution channel, but it also ties Anthropic to partners that may simultaneously be shareholders, suppliers and, to some extent, competitors.
What to expect from the indices: the mechanics of a listing
When a company of this size enters the market, investors using diversified index-based strategies need to consider technical factors as well as the company’s fundamentals. In the first few weeks, the share price could be driven more by flows than by fundamentals.
If Anthropic listed on Nasdaq, it could enter the Nasdaq-100 relatively quickly. Under the index’s rules, an IPO that ranks among the 40 largest companies by market capitalisation can be included after just 15 trading sessions (fast entry rule). Anthropic would comfortably exceed this threshold. This means that instruments such as ETFs and index funds would need to buy shares to replicate the index.
Anthropic’s initial weighting in the index would not be based on its total market capitalisation alone, but on the shares actually offered to the market, multiplied by three. With $100 billion raised, the relevant value would be $300 billion, equivalent to around 1% of an index worth $31 trillion.
A broad ecosystem of ETFs and other financial instruments is built around the Nasdaq-100. Anthropic’s potential inclusion in the index could therefore trigger purchases by funds that track it, creating additional demand for the shares around the time of its entry. The scale of these flows would depend on the weighting assigned to the company and on the assets directly tracking the index. This demand could support the share price temporarily, but it would not guarantee a lasting advantage.
Markets tend to anticipate such predictable flows and, once they have run their course, the share price returns to being driven by earnings and expectations. This upward pressure could also be partly offset by sales of other Big Tech stocks, which would be needed to make room for the new constituent. For investors, the key point is that any short-term price impact is difficult to predict and may prove temporary. A diversified portfolio can help reduce reliance on any single stock or market event, keeping the focus on longer-term investment objectives.
Long-term implications for investors
In the long term, much will depend on the company’s ability to generate revenue. The broader question is whether we are witnessing the emergence of a new generation of mega-cap companies that could offer greater diversification, even within a concentrated market, and influence market dynamics as we have seen over the past 20 years.
The internet revolution shows that this process is rarely straightforward. The Nasdaq Composite peaked in March 2000 before suffering a sharp decline. Many of the companies at the centre of the dot-com bubble disappeared, while a small number of winners generated much of the value. Yet investors who stayed invested over the long term were able to benefit from some of the most rewarding periods of equity-market growth in history.
From a historical perspective, maintaining a diversified portfolio over the long term is one way to manage the volatility associated with major technological trends. The direction of the global economy may seem clear, but the journey could still hold surprises. The evolution of markets and technology will continue to require careful monitoring of risks.
For investors interested in this IPO, Anthropic shares will be available on the Moneyfarm Do-it-yourself (DIY) platform from the first day of listing*.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. The views expressed here should not be taken as a recommendation, advice or forecast. Investing is usually for the long term, but it depends on the circumstances of each individual. If you are unsure investing is the right choice for you, please seek financial advice.
*The availability of the stock from the first day of listing is subject to operational and market conditions.
The post Anthropic, the IPO that could reshape the AI market appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 2 minutesWhen the clocks go back on Sunday 25 October, we all get an extra hour. Why not use a few minutes of it to get your pensions in order? It’s National Pension Tracing Day, a timely reminder to check in on the pensions you’ve built up throughout your working life. If you’ve changed jobs over […]
The post Got an extra hour? Put it to good use and tidy up your pensions appeared first on MoneyFarm Insights.
]]>When the clocks go back on Sunday 25 October, we all get an extra hour. Why not use a few minutes of it to get your pensions in order?
It’s National Pension Tracing Day, a timely reminder to check in on the pensions you’ve built up throughout your working life. If you’ve changed jobs over the years, you may have pensions with several different providers – and keeping track of them all can be tricky.
Don’t leave your old workplace pensions behind
Changing jobs often means leaving a workplace pension behind. Over time, you can end up with several pension pots, each managed by a different provider. You might know where some of them are, but do you have a clear picture of all your retirement savings?
It’s a common situation across the UK. An estimated 3.3 million pension pots are lost, with a combined value of around £31.1 billion. That’s an average of approximately £9,470 per pot.
You don’t have to spend your whole extra hour tracking down old pensions. Taking a few minutes to get started could help you understand what you’ve already saved and what you might need to do next.
Bring your old pensions together
Having pensions spread across different providers can make it harder to see the bigger picture. Bringing them together could make your retirement savings easier to manage and review, helping you understand what you have and how your pensions fit into your plans for the future.
That’s where Moneyfarm’s Find, Check & Transfer service can help.
We’ll help you find pensions you may have lost track of, check the details and, if transferring is right for you, bring eligible pensions together into a Moneyfarm Pension.
Find, Check & Transfer: how it works
1. Find your pensions
Share a few details about yourself and your previous employers, and we’ll help track down your old pensions.
2. Check what you’ve got
We’ll review the pensions we find, looking at their fees and any benefits they may include, so you can make a more informed decision about what to do next.
3. Transfer, if it’s right for you
If transferring makes sense for your circumstances, you can bring eligible pensions together into a Moneyfarm Pension. Having your pensions in one place can make it easier to keep track of your retirement savings.
A clearer picture of your retirement savings
You don’t need to sort everything out in one go. Start by gathering any pension paperwork you have, making a list of your previous employers and checking whether you have pensions with different providers.
If you’re not sure where to begin, our Find, Check & Transfer service can help you take the next step.
This National Pension Tracing Day, make the most of your extra hour. A few minutes spent getting your pensions in order could help you build a clearer picture of your retirement savings – and make it easier to plan for the future.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Got an extra hour? Put it to good use and tidy up your pensions appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 3 minutesThe dynamics in financial markets continue to shift. In some respects, the long-term themes remain intact – geopolitical uncertainty, rising oil prices and robust corporate earnings growth. But the market reaction, as was the case last week, has differed from what we saw earlier in the year. Government bond yields in the US and UK […]
The post Making sense of shifting market dynamics appeared first on MoneyFarm Insights.
]]>The dynamics in financial markets continue to shift. In some respects, the long-term themes remain intact – geopolitical uncertainty, rising oil prices and robust corporate earnings growth. But the market reaction, as was the case last week, has differed from what we saw earlier in the year. Government bond yields in the US and UK moved lower and tech shares were weaker. We continue to debate what, if anything, these moves mean for longer-term portfolio returns. Is this a start of a new trend, or a bump in the road for Artificial Intelligence (AI) stocks?
Let’s start with the macro backdrop. In general, the outlook remains decent, perhaps surprising given where oil prices are. Economic Surprise indices remain positive, indicating that macro data is coming in a bit better than analysts expected. That said, we’ve seen a bit of a deterioration in Europe over the past few weeks – mostly driven by France, where political and social uncertainty are taking their toll.
In terms of geopolitics, the picture is more challenging. Oil prices have continued to move higher, perhaps reflecting concerns of a re-escalation in the conflict in the Middle East. That’s been a familiar theme, but the reaction from bond markets has been more surprising, as government bond yields moved lower in the US and UK this week. You might have expected higher oil prices to raise inflation expectations and prompt bond yields to rise. Instead US treasuries have been more of a safe haven over the past couple of weeks. Perhaps the move lower is just a normalisation after a strong move higher in yields over the past few months, but it might reflect investors shifting their allocation from equities to bonds, given attractive yields in fixed income.
We are considering if the fall in longer-dated yields is a sign that growth might weaken in the coming quarters. The macro data doesn’t suggest that slower growth is imminent, but it’s something we’ll continue to monitor. A meaningful ceasefire in the Middle East could have a significant impact across financial markets. Lower oil prices could feed into lower bond yields, making capital cheaper for a range of businesses and sovereigns. That’s something investors have been hoping for for some time, and the outlook there remains uncertain.
On the equity side, we’ve seen a range of companies reporting earnings, mostly in the US. The overall picture remains very healthy, with third quarter earnings growth running above 20% year-on-year, albeit with many companies still to report. But strong results haven’t been enough to help tech businesses, a number of whom saw their share prices sell off in the wake of good results. The easy response to that is to suggest that market expectations were higher, but at the same time we’re seeing equity valuations (e.g. the forward price/earnings ratio) move lower.
As we’ve noted before, that’s particularly true in Emerging Market equities, which trade at the largest discount to European equities in the past twenty years. Concerns about the health of the “AI trade” are still very much with us, and we’ve seen that particularly reflected in the credit space, where the cost of debt for certain AI businesses has risen sharply. We remain broadly constructive on the equity side, where we think underlying demand is still strong and the build-out of AI infrastructure continues.
Looking forward, we see a couple of notable events in the next couple of weeks. US mid-term elections have the potential to cause some short-term volatility, given the febrile political environment. While we’ll monitor the situation closely, we typically don’t make portfolio changes in response to elections and we’d expect that to be the case this time as well.
In the UK, we’ve got the Budget announcement – and we’ll say more about that next week. European governments face a number of fiscal challenges, and the UK is no exception. That said, the new Chancellor is aiming to build a reputation for fiscal conservatism, and that could play well with fixed income investors.
Finally, we’ll likely get the kick-off of the long-awaited Anthropic IPO, with the formal release of its prospectus. That should give us more details about the business, and the risks. At a time of uncertainty around AI, the Anthropic IPO is likely to be an important bellwether for investor sentiment at least in the short-term, although it will likely be some time before it becomes a meaningful part of global equity indices.
The post Making sense of shifting market dynamics appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesInheritance can come as a blessing, but it’s also a big responsibility. Whether you inherit £10,000 or £200,000, inherited money can completely change a person’s life. Therefore, you should know how to manage it responsibly and how to invest an inheritance effectively to take full advantage of the opportunity. Inheritance money, if used judiciously, can […]
The post What to do with inheritance in the UK: Inheritance Planning appeared first on MoneyFarm Insights.
]]>Inheritance can come as a blessing, but it’s also a big responsibility. Whether you inherit £10,000 or £200,000, inherited money can completely change a person’s life. Therefore, you should know how to manage it responsibly and how to invest an inheritance effectively to take full advantage of the opportunity.
Inheritance money, if used judiciously, can help you start a new career, complete your education, buy a new home, plan for retirement or save for unexpected expenses. However, if it is not managed carefully, an inheritance may not last as long as expected. Therefore, how the money is used should be carefully planned.
|
Do I need a big inheritance to invest? |
No, you can start even with a small amount |
|
First thing to do with an inheritance |
Review your financial situation and high-interest debt |
|
Save it or invest it |
It depends on your goals, time horizon and financial position |
|
Most important thing to do? |
Plan how to use it |
What to do with inheritance in the UK
You may be wondering what to do with an inheritance when you first receive it, as it may feel like lifelong financial security. However, it needs to be managed carefully if its benefits are to last in the long term. Therefore, people who receive an inheritance should review their financial situation before deciding how to use the money.
Pay off high-interest debts
As much as you might be tempted to make a grand purchase with your inheritance, one of the first steps to consider is paying off high-interest debt. Take stock of your financial situation, including any loans, mortgages, and credit card balances, before deciding which debts to repay first.
The priority of payments should generally reflect the interest rate you are paying. For instance, credit card debt is usually more expensive and carries a much higher interest rate than mortgages. Therefore, inheritance may be better used to pay off credit card debt and personal loans before lower-interest borrowing such as a mortgage.
This way, you can save on monthly interest costs and better manage your finances. Whether it is better to repay debt or save will depend on the interest charged on the debt compared with the return available on savings.
Save or invest
After paying off debts, the next logical step in inheritance planning is to save some of the inheritance money while investing the rest for the future. Instead of giving in to the temptation of spending all of the inheritance on luxuries, you may want to consider saving or investing part of it tax-efficiently.
You can keep a significant part of your inheritance money for rainy days in savings accounts. A tax-efficient way to save or invest is to use an ISA, up to the annual ISA allowance of £20,000 for the 2026/27 tax year. The money can be held in a cash ISA, a stocks and shares ISA, or split across different types of ISAs.
You can also invest the inheritance money with a long-term perspective. You can invest it in various financial instruments, including stocks, bonds, foreign exchange, commodities, or property. Investing your money and having a solid investment strategy may help you work towards long-term returns, for example through dividends, interest payments or rent. Moreover, you can manage investment risk through diversification across various securities, industries, and geographies.
Invest in a pension
Investing part of an inheritance into a pension fund can be a tax-efficient way to save for retirement. For the 2026/27 tax year, the standard annual allowance is £60,000, although a lower allowance may apply in some circumstances and tax relief on personal contributions is subject to individual limits. You can usually take up to 25% of your pension tax-free, subject to the standard lump sum allowance of £268,275.
The tax treatment of pension death benefits is changing. From 6 April 2027, most unused pension funds and pension death benefits will be included in the value of an estate for Inheritance Tax purposes. Overall, using part of an inheritance to contribute to a pension can support long-term retirement planning, but the relevant tax rules and allowances should be considered carefully.
Charity
Many people also consider donating a portion of their inheritance money to charity. It can be a way to share some of the benefits of an inheritance with others. The inheritance then becomes not only a gift to you but also a means for others to benefit.
Keep some for personal enjoyment
If you have inherited a large sum of money, you’re well within your rights to spend some of it on personal luxuries. However, it’s essential to first consider your debts, savings, investments and longer-term financial needs before indulging yourself.
After careful financial planning, you can use any remaining inheritance money for a holiday, luxury purchases, home renovations, or anything that makes you happy. Your inheritance planning doesn’t have to entail penny-pinching
Emotional aspects of dealing with inheritance
Inheritance often brings a complex mix of emotions, ranging from gratitude and excitement to guilt and anxiety. The sudden responsibility of managing a substantial sum of money can be overwhelming, especially when it comes from a loved one who has passed away. The pressure to make the right decisions, coupled with the desire to honour the intentions of the deceased, can create a complex emotional situation.
Investing your inheritance wisely may seem like the obvious goal, but the path to doing so may be complicated by emotional considerations. It’s not just about financial gain; it’s about respecting a legacy, understanding family dynamics, and navigating personal values and goals. Balancing these emotional factors with practical financial planning is essential to make the most of an inheritance, ensuring that it serves as a positive force in your life rather than a source of stress or conflict.
How is inheritance taxed in the UK?
You do not usually pay tax simply because you receive an inheritance in the UK. Any Inheritance Tax due is normally paid by the estate before the assets are distributed. However, tax may become due later if the inherited assets generate income or are sold at a gain.
For the 2026/27 tax year, the standard Inheritance Tax nil-rate band is £325,000. A further residence nil-rate band of up to £175,000 may apply when a qualifying home is passed to direct descendants. The standard Inheritance Tax rate is 40% on the part of the estate above the available thresholds. These thresholds are currently set to remain at the same levels until 5 April 2031.
Transfers to a spouse or civil partner are generally exempt from Inheritance Tax. A reduced rate of 36% may apply if at least 10% of the net estate is left to charity.
|
Tax point |
2026/27 position |
|
Tax when receiving an inheritance |
Usually none for the beneficiary at the point of inheritance |
|
Nil-rate band |
£325,000 |
|
Residence nil-rate band |
Up to £175,000 where the conditions are met |
|
Standard Inheritance Tax rate |
40% above the available thresholds |
|
Spouse or civil partner |
Transfers are generally exempt from Inheritance Tax |
|
Charitable legacies |
A 36% rate may apply if at least 10% of the net estate is left to charity |
|
Tax after inheriting |
Income Tax may apply to income generated by inherited assets and Capital Gains Tax may apply when inherited assets are sold at a gain |
For Capital Gains Tax, the annual exempt amount for individuals is £3,000 in 2026/27. The tax is generally based on the gain made after inheritance rather than on the fact that the asset was inherited.
Tips for investing your inheritance
As discussed, inheritance can provide significant financial opportunities if managed carefully. Unfortunately, without a clear plan, inherited wealth can be spent more quickly than expected. Therefore, careful financial planning is an important part of managing an inheritance.
For larger or more complex inheritances, you may want to consider speaking to a financial planner or financial adviser. An independent financial adviser can help you assess your financial position and consider the options available to you.
A financial adviser can also help you assess possible ways to invest the inheritance based on your risk tolerance, age, short- and long-term goals and current financial position.
If you do not want to hire a financial adviser for your inheritance planning, several financial institutions offer tailored financial services based on your investor profile. This investor profile will match you with an investment portfolio that suits your risk profile.
Practical examples of managing an inheritance
Someone who inherits £20,000 and has £4,000 of high-interest debt could consider clearing that debt first, keeping part of the remaining money as an emergency fund and investing the rest through an ISA, depending on their goals and risk profile.
With a £100,000 inheritance, the options may be broader. For example, part of the money could be kept in accessible savings, up to £20,000 could be invested through an ISA in the 2026/27 tax year, and further amounts could be considered for a pension or a diversified investment portfolio, subject to the relevant rules and the investor’s circumstances.
These examples are illustrative only. The appropriate approach will depend on individual financial circumstances, tax position, objectives and attitude to risk.
Take your time before making financial decisions
It is critical to take your time before spending your inheritance and avoid making rushed financial decisions. It’s natural to be tempted to quit your job as soon as you receive £100,000 in inheritance or use the inheritance money to buy your dream car. However, it’s key to pause, reflect, and make sound financial decisions by learning how to invest £100,000.
To do this, you may want to keep the inheritance in a secure bank account for some time while you consider your options rather than frittering it away. After you’ve reviewed your overall financial position, the money can be withdrawn and put to use. You should take your time and understand the process and the consequences before making major financial decisions.
What happens to an unclaimed inheritance?
Please note that when someone dies without a valid will and without known entitled relatives, their estate may pass to the Crown as bona vacantia. To claim an unclaimed inheritance without a valid will, you must check if the estate is listed with the Crown and find out if you are an entitled relative. If you are an entitled relative, you must make a claim to the appropriate body representing the Crown. Claims are generally accepted within 12 years of the estate being administered, while fully documented claims may be considered up to 30 years from the date of death.
Making the most of your inheritance
The bottom line is that inheritance can bring significant changes to a person’s financial situation. If managed effectively, it can help reduce financial pressure and support greater long-term financial security. Therefore, it is important to have a clear financial plan when you receive an inheritance.
The inheritance money can be used to meet financial obligations, save and invest for the future, plan for a comfortable retirement, create a stable financial future for future generations, and improve your quality of life. It’s important to consider carefully how inherited wealth fits into your wider financial plans.
FAQ
First, consider any high-interest debt and whether you have an adequate emergency fund. You can put the rest of the money in a savings account, spend part of it or consider investing it, depending on your goals and financial circumstances.
The same principles that apply to a £10,000 inheritance can also apply to £20,000. You may choose to divide the money between debt repayment, emergency savings and investments. If you are eligible and have your full allowance available, £20,000 is also the overall ISA allowance for the 2026/27 tax year.
First, review your overall financial position, including any high-interest debts and emergency savings. You can then consider whether to save or invest the money, give part to charity, make pension contributions or spend some of it on yourself.
You do not usually pay tax simply because you receive an inheritance. Any Inheritance Tax due is normally dealt with by the estate, although Income Tax or Capital Gains Tax may apply later if inherited assets generate income or are sold at a gain.
Yes, provided you are eligible and have unused ISA allowance. The overall ISA allowance is £20,000 for the 2026/27 tax year, and it can be split across eligible types of ISA.
Yes, but the usual pension contribution and tax-relief rules still apply. The standard annual allowance is £60,000 for 2026/27, although a lower allowance may apply in some circumstances.
The post What to do with inheritance in the UK: Inheritance Planning appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 6 minutesThe start of a new tax year is the ideal moment to review your investment strategy. With the annual ISA allowance set at £20,000 for the tax year 2026/27, effective planning is essential to maximise your tax efficiency. Individual Savings Accounts (ISAs) allow you to grow your investments free from Income Tax and Capital Gains Tax, […]
The post ISA allowance: Can I put £20.000 in an ISA every year? appeared first on MoneyFarm Insights.
]]>The start of a new tax year is the ideal moment to review your investment strategy. With the annual ISA allowance set at £20,000 for the tax year 2026/27, effective planning is essential to maximise your tax efficiency.
Individual Savings Accounts (ISAs) allow you to grow your investments free from Income Tax and Capital Gains Tax, making full use of the allowance highly beneficial. Whether you choose to invest the entire amount in one ISA or split it across several, understanding the rules is key.
This guide explains how the annual ISA allowance works, your options for using it, and how to make the most of this valuable tax benefit. Alternatively, get in touch with our team to discuss your options.
The Most Important ISA Rule to Remember
Flexibility rules introduced in April 2024 allow you to subscribe to multiple ISAs of the same type within the same tax year (except for Lifetime ISAs), provided you remain within the overall £20,000 limit.
Quick ISA Questions Answered
|
Question |
Answer |
|
Can I put £20,000 in an ISA every year? |
Yes, you can contribute up to the full £20,000 ISA allowance each tax year. |
|
Can I have more than £20,000 in an ISA? |
Yes, your total ISA value can grow beyond £20,000 through investment growth and contributions from previous tax years. However, you cannot contribute more than £20,000 of new money across your ISAs in a single tax year. |
|
Does the ISA allowance accumulate? |
No. Unused ISA allowance does not roll over into the next tax year. It is a “use it or lose it” allowance. |
How does the ISA annual allowance work in practice?
An Individual Savings Account (ISA) is a tax-efficient wrapper available to UK residents. You can set aside money in an ISA each tax year without paying Income Tax or Capital Gains Tax on your returns.
The UK tax year runs from 6 April to 5 April the following year. For the 2026/27 tax year, the total annual ISA allowance is £20,000, unchanged from the previous year.
This means you can contribute up to £20,000 into ISAs each tax year, in any combination of permitted ISA types. Any unused allowance cannot be carried forward — when the new tax year starts on 6 April, you receive a fresh annual ISA allowance.
The Main Types of ISA
There are four main types of ISA available to adults. You can mix and match your contributions across these, provided the total new contributions do not exceed £20,000.
- Cash ISA
- Stocks and Shares ISA
- Lifetime ISA (LISA)
- Innovative Finance ISA (IFISA)
Allocation Examples:
- £12,000 in a Stocks and Shares ISA, £8,000 in a Cash ISA.
- £4,000 in a Lifetime ISA, £10,000 in a Stocks and Shares ISA, and £6,000 in a Cash ISA.
- £20,000 entirely into a Stocks and Shares ISA.
There is also a Junior ISA (JISA) for children. Contributions to a JISA do not affect your own annual ISA allowance.
ISA Allowance Breakdown by Type (2026/27)
|
ISA Type |
Annual Allowance |
Age Restrictions |
Key Rules & Benefits |
|
£20,000 |
18+ |
Invest in shares, funds, and bonds. No tax on capital gains or income. Potential for higher returns over the long term. |
|
|
Cash ISA |
£20,000 |
18+ |
Works like a savings account but interest is tax-free. Generally considered lower risk than investing in the stock market. |
|
Lifetime ISA (LISA) |
£4,000 |
18–39 to open |
25% government bonus (max £1,000/year). Funds must be used for a first home or retirement (age 60+). The £4,000 counts towards the total £20,000 limit. |
|
Junior ISA (JISA) |
£9,000 |
Under 18 |
Separate allowance. Funds legally belong to the child and are locked until age 18. |
ISA Changes from April 2027
From 6 April 2027, the annual Cash ISA subscription limit will fall to £12,000 for individuals under 65, while those aged 65 and over will retain a £20,000 Cash ISA limit. The overall annual ISA allowance will remain at £20,000, with the £4,000 Lifetime ISA allowance and £9,000 Junior ISA allowance also set to remain unchanged until 5 April 2031.
The reform will also introduce anti-circumvention rules. Transfers from Stocks and Shares ISAs and Innovative Finance ISAs into Cash ISAs will no longer be permitted for individuals under 65, although transfers from Cash ISAs to non-Cash ISAs will remain possible. In addition, interest earned on cash held within non-Cash ISAs will be subject to a 22% charge, alongside new rules covering Money Market Funds. From 6 April 2027, investors subscribing to an ISA will also be required to provide their National Insurance number or confirm that they are not eligible for one.
Maximising Your Annual ISA Allowance
Why You Should Use It Before the Tax Year Ends
With any type of ISA, the strategy is straightforward: utilise as much of your annual ISA allowance as you can afford. While not everyone can set aside £20,000, making use of your allowance can help protect more of your savings and investments from Income Tax and Capital Gains Tax.
Timing the Market vs. Time in the Market
There is often a question about when to invest. Rather than trying to identify the perfect moment to enter the market, long-term investing generally focuses on time in the market. Trying to time market movements can lead to missed opportunities, while investing earlier gives your money more time to potentially benefit from long-term market growth.
Consider Multiple Portfolios
A key aspect of effective management is diversification. Moneyfarm ISAs allow you to create multiple portfolios within a single account. This enables you to structure your £20,000 allowance across different risk levels.
Example strategy:
Suppose you have £20,000 available to invest in your ISA and two different financial goals. You could allocate £12,000 to a higher-risk portfolio for a long-term goal that is more than 10 years away, giving your investments more time to ride out short-term market fluctuations.
The remaining £8,000 could be allocated to a lower-risk portfolio for a goal with a shorter time horizon, where limiting volatility may be more important. This way, the same ISA allowance can support different goals while keeping each portfolio aligned with its own time horizon and risk level.
The Power of Compound Interest
Compounding allows your investments to grow not only on the money you contribute, but also on the returns accumulated over time. As those returns are reinvested, they can generate further returns, which is why the effect of compounding becomes more significant over longer investment periods.
For example, if you invested the full £20,000 ISA allowance at the end of every year for 25 years and achieved an average annual return of 5%, you would contribute £500,000 in total. Assuming those returns were reinvested, the portfolio could grow to around £954,000. In this simplified example, roughly £454,000 of the final value would come from investment growth rather than contributions.
The example also shows why time can be an important part of long-term investing: the longer returns remain invested, the more opportunity they have to generate further returns.
These figures are illustrative only and do not account for fees, market fluctuations or changes to the ISA allowance. Investment returns are not guaranteed, and the value of your investments can go down as well as up.
Three Fundamentals for Making the Most of Your ISA
- Think long-term because market fluctuations are normal; stay invested to benefit from long-term growth;
- Diversify to spread investments across assets and regions to reduce risk;
- Consider professional advice to review your progress and adjust your investment plan when needed.
5 Benefits of Using Your ISA Allowance
|
Benefit |
How it works |
Key benefit |
|
Tax efficiency |
Interest, income and capital gains generated within an ISA are sheltered from Income Tax and Capital Gains Tax. |
Returns can grow within the ISA without being reduced by these taxes. |
|
Accessibility |
Minimum contribution requirements vary depending on the ISA type and provider. |
You do not need to use the full £20,000 annual allowance to benefit from an ISA. |
|
Growth potential |
A Stocks and Shares ISA can hold investments such as funds, shares and bonds. |
Long-term investing offers the potential for capital growth, although returns are not guaranteed. |
|
Flexibility |
Flexible ISAs allow withdrawals to be replaced within the same tax year without the replacement counting again towards the annual allowance. |
This can provide access to your money while preserving your available allowance, subject to the provider’s terms. |
|
Transfers |
ISAs can be transferred between providers without the transferred amount counting as a new contribution, provided the official ISA transfer process is followed. |
You can change provider while maintaining the tax-efficient status of your ISA. |
FAQs
You cannot contribute more than £20,000 across your ISAs in the 2026/27 tax year. However, the total value of your ISAs can exceed £20,000 through contributions made in previous tax years and investment growth. ISA transfers completed through the official transfer process do not count as new contributions.
Yes. You can contribute to a Cash ISA each tax year, provided your total ISA contributions remain within the applicable annual limits. For2026/27, the overall ISA allowance is £20,000.
You can make multiple contributions during the tax year, subject to your provider’s terms, provided your total contributions remain within the applicable ISA limits. For 2026/27, the overall annual ISA allowance is £20,000.
No. The ISA allowance operates on a use-it-or-lose-it basis. Any unused allowance at the end of the tax year cannot be carried forward, and a new annual allowance becomes available on 6 April.
Yes. You can contribute to more than one ISA of the same type during the same tax year, provided your total contributions remain within the overall annual ISA allowance. Lifetime ISAs are an exception, as you can only pay into one Lifetime ISA in each tax year.
Transfers completed through the official ISA transfer process do not count as new contributions towards your annual ISA allowance. If you withdraw the money yourself instead, rather than arranging an ISA transfer, different rules may apply, particularly if the ISA is not flexible.
From 6 April 2027, the annual Cash ISA subscription limit will fall to £12,000 for individuals under 65, while those aged 65 and over will retain a £20,000 Cash ISA limit. The overall annual ISA allowance will remain at £20,000. The reform will also introduce restrictions on transfers into Cash ISAs for under-65s, as explained above.
The post ISA allowance: Can I put £20.000 in an ISA every year? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 2 minutesIt has been quite an active week in markets and we wanted to put the moves into context. On balance, we were reassured by the market reaction. AI-related stocks weakened somewhat, but other parts of the equity market held up well. Government bond yields in the US moved lower, despite higher than expected inflation. Portfolio […]
The post What matters most in uncertain markets appeared first on MoneyFarm Insights.
]]>It has been quite an active week in markets and we wanted to put the moves into context. On balance, we were reassured by the market reaction. AI-related stocks weakened somewhat, but other parts of the equity market held up well. Government bond yields in the US moved lower, despite higher than expected inflation. Portfolio diversification proved effective in this environment.
Just to recap, over the past few weeks we’ve seen a couple of key drivers for markets. First, there’s the ongoing debate about Artificial Intelligence: will all the investment we’re seeing pay off? Second, there are the sharp increases in bond yields, which have put the spotlight on countries like France.
These themes feed into a tug-of-war around growth and inflation. Continued AI spending is likely to support global growth and, through the demand for resources, potentially sustain higher inflation as well1. In contrast, sustained higher rates will put pressure on some parts of the economy and potentially slow down growth. So far, AI spending has helped to prop up global growth, but we think some of the moves this week reflect investor concerns about potential risks to growth.
This week there’ve been some quite sharp moves in financial markets. AI was at the forefront, with Korean equities being particularly volatile. On the fixed income side, we’ve seen interest rates initially rise in response to higher than expected inflation data in the US, only to fall quite sharply thereafter.
What should we think about this?
On the equity side, it’s worth noting that the moves down have been quite concentrated in the AI space. Over the past few days (through Thursday), among US and European sectors, only the tech sector and some US industrials have shown declines. Most sectors have moved higher. Obviously the tech sector has a large weighting in global indices, but the differentiation between sectors is notable. On the fixed income side, you might have expected bond yields to rise in the wake of higher than expected inflation in the US, but the move lower suggests that investors had collectively already anticipated the higher inflation print.
In terms of portfolio positioning, diversification remains key, both between equities and fixed income and within equities.
Fixed income yields have moved higher over the past few months and can provide attractive income for investors, even in shorter-dated bonds. We are paying close attention to the credit space, where the interest rates on high-yield corporate bonds have moved higher. High-yield bonds have been pretty resilient in recent months, and we think that reflects the solid economic growth we’ve seen, particularly in the US. If we see high-yield spreads continue to widen, that could be a sign investors are looking for weaker economic growth going forward.
Within equities, the focus has been on AI and AI-adjacent sectors, but we’ve seen our UK and European positions hold up well. While we’re currently positive on the outlook for AI and tech spending more broadly, we continue to maintain a diversified equity exposure.
Overall, we think global growth is so far holding up well, despite higher oil prices. Inflation is proving sticky, and central banks will likely raise rates over the coming months, with another rate hike in the US likely in December. But we think that starting bond yields are attractive, while earnings growth continues to hold up, based on the early reports from the third quarter results in the US. We’ll continue to focus on those company reports and their outlook over the coming weeks.
- There’s much debate about whether AI will be deflationary in the long-term. For now, we think that during the current build-out of infrastructure, AI is more likely to be inflationary than deflationary. ↩︎
The post What matters most in uncertain markets appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: < 1 minuteWelcome to a new episode of A Matter of Interest podcast, your fortnightly reality check on global markets, hosted by Moneyfarm. Every two weeks, Richard Flax (our Chief Investment Officer) and Jack Amy (our Quantitative Trading Analyst) cut through the noise to serve up fresh market trends, data-driven insights, and strategic takeaways, minus the textbook jargon. In this episode, we examine […]
The post Bond yields, French fiscal strain & AI checkpoint appeared first on MoneyFarm Insights.
]]>Welcome to a new episode of A Matter of Interest podcast, your fortnightly reality check on global markets, hosted by Moneyfarm. Every two weeks, Richard Flax (our Chief Investment Officer) and Jack Amy (our Quantitative Trading Analyst) cut through the noise to serve up fresh market trends, data-driven insights, and strategic takeaways, minus the textbook jargon.
In this episode, we examine the fiscal pressures driving the sharp rise in French government bond yields, explore why Moneyfarm maintains a shorter-duration bias in bond portfolios, and evaluate how global equity markets are digesting high expectations amidst shifting valuations, particularly the AI tech complex. Enjoy listening.
Key takeaways
- The recent spike in bond yields – from 0:36
- France in the spotlight – from 2:49
- Corporate earnings and market reaction – from 14:05
You can also listen to the episode on Apple Podcast and YouTube.
The post Bond yields, French fiscal strain & AI checkpoint appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 8 minutesLonger lives don’t always mean healthier ones. Rising healthcare and care costs are changing the way investors should think about retirement planning and long-term wealth. Our special contributor and Daily Telegraph’s columnist David Stevenson explores more. We all know the meta-narrative of our era by now, and no, I’m not talking about Artificial Intelligence but […]
The post The hidden cost of living longer appeared first on MoneyFarm Insights.
]]>Longer lives don’t always mean healthier ones. Rising healthcare and care costs are changing the way investors should think about retirement planning and long-term wealth. Our special contributor and Daily Telegraph’s columnist David Stevenson explores more.
We all know the meta-narrative of our era by now, and no, I’m not talking about Artificial Intelligence but aging. We’re all living longer, and that increases the financial pressure on us to accumulate capital. But the simple fact of living longer is a good news story, isn’t it? Maybe, but there’s a catch. Are we living longer, healthier lives? To which the answer in the UK may be no. The rate of longevity improvement has stalled dramatically since around 2011, and healthy life expectancy has actually fallen in recent years.
Male healthy life expectancy at age 50–54 fell from 19.9 years to 19.4 years between 2015 and 2025. Female healthy life expectancy at the same age fell from 21.1 years to 20.6 years. In England, women are now expected to spend a smaller proportion of their lives in good health than they did in 2011–2013.
Age UK’s 2025 State of Health and Care report put it bluntly: “We are living fewer years in good health”. Two-thirds (68%) of people aged over 80 are now living with two or more long-term conditions such as diabetes, arthritis, or heart disease. About 2 million people aged 65+ have unmet care needs.
Given these numbers, it’s no surprise that more 50- and 60-somethings are turning up at gyms, cycling in tight-fitting Lycra shorts, eating healthier, and, perhaps more importantly, making sure they are healthier by investing in personal medical insurance (PMI). Given that the NHS seems to be in a perma-crisis – although waiting lists are actually going down in aggregate – the option of making sure you are tip-top healthy via regular medical screenings, private GPs and hip replacement operations has become increasingly popular. But as with all the good things in life – red wine, carbon fiber bikes and avocados – this all comes at a cost.
Rocketing health insurance costs
A record 6.2 million people in the UK now have access to private medical insurance, with the LaingBuisson Health Cover report valuing the total UK health cover market at £8.64 billion by the start of 2025, reflecting an extraordinary 13.83% year-on-year growth. For context, the PMI market was worth around £4.83 billion as recently as 2022. That’s the market essentially doubling in a matter of years. The number of people covered by employer-provided PMI hit 4.7 million in 2023, the highest figure in more than 30 years of data collection, with a 7% overall uptick in both individual and workplace policies.
The price is obvious – increasing premiums as insurers and health care providers, increasingly busy, try to ration demand via price. Willis Towers Watson’s Global Medical Trends Survey found that UK private medical inflation was expected to hit 12.6% in 2024 – higher than the global average of 10.4% and more than three percentage points above the European average. Insurer Aon’s equivalent research was even more alarming, forecasting a medical trend rate of 15% for the UK in 2024. By 2025-26, WTW’s updated survey put UK healthcare inflation at 10.6% for the year, with 10% projected for 2026 – still among the highest in Western Europe.
The average cost of private health insurance for a single adult in the UK now sits at around £79.59 a month, with couples paying approximately £145.77 per month and a family of four shelling out around £166.52 monthly in 2026. A decade ago, those figures would have been closer to half that for many policyholders. Bupa’s indicative pricing suggests a non-smoking 25-year-old outside London pays around £50 a month, while a family with two adults in their 50s and two teenagers might pay around £220 a month – and that figure is rising every renewal cycle.
UK Private Medical Insurance: Key Market Metrics, 2004–2024
It would, of course, be easy to blame these rising costs on rampant profiteering by increasingly profitable healthcare providers and insurers, but that wouldn’t really be very accurate. The rapid increase in demand can’t be easily managed by a sudden increase in capacity – it takes years to build new hospitals and train competent, experienced medical staff. And whatever resources private healthcare businesses can deploy, they face a global challenge: healthcare inflation. By the first quarter of 2026 (versus a start date in 2015), the CPI for health products and services stood at 142.4, suggesting that health sector prices have risen by 42.4% since 2015, compared with overall price increases of roughly 35-36%. Healthcare inflation, in other words, has consistently outrun the general cost of living, even though the post-pandemic inflation spike that hit energy and food prices hardest.
Don’t forget care home costs
If the 50-, 60-, and 70-somethings are having a hard time paying for health insurance, pity their older peers in their mid-70s through to their 90s: they face a lottery with care home costs, with costs rising rapidly across the board, including for one-on-one home care.
UK care home costs have increased dramatically over the past two decades, from relatively modest but steady annual rises pre-2020 to double-digit surges in the post-pandemic era. The most authoritative annual dataset comes from LaingBuisson’s Care Homes for Older People report, which tracks weighted average weekly fees across the market.
The average weekly residential care home fee rose 19% in a single year from 2021-22 to 2022-23, compared to a headline CPI peak of 10.1% – care homes were roughly double the general inflation rate. By March 2025, Which magazine and LaingBuisson confirmed average fees had hit nearly £1,400 a week, a rise of more than a quarter since 2021-22 alone. One in seven independent nursing homes was charging over £1,800 a week for new residents by 2025. Three factors explain this sharp increase:
- labour costs (care homes are extremely staff-intensive and have been hit hard by National Living Wage increases and the employer NI rise in 2025),
- energy and food inflation,
- chronic underfunding of local authority rates that forces providers to push higher fees onto self-funders.
The King’s Fund notes that real-terms adult social care expenditure in 2023/24 was still only £4.6 billion more than in 2010/11 in real terms (remarkably little growth for 13 years) which tells you how much cost has been shouldered by individuals rather than the state.
To put the numbers in context: according to Which magazine, a self-funding resident in a standard residential care home now faces costs of roughly £70,000–£80,000 per year, rising to well over £90,000 in London and the South East. In 2005, a typical care home place cost around £20,000–£25,000 a year. That’s a near-tripling in nominal terms over 20 years, and a very significant real-terms increase even after adjusting for general inflation.
A plan of action?
I want to start with what many might consider a controversial statement: invest in a healthier lifestyle rather than conserve every last penny. Building on Seneca’s quote (Not how long, but how well you have lived is the main thing) and the wider Stoic and Epicurean traditions, it strikes me that if you reach your 60s, or even 70s, and are in good health, it’s worth investing to make sure you stay that way.
NHS waiting lists are steadily improving – really, they are, the hard data support that statement – but too many older folk resolutely refuse to spend money to get quicker treatment, even though they can afford it. Everyone is entitled to their views and politics, and clearly, we have all invested our taxes in the NHS and expect to get some payback, but I have lost count of the number of fairly comfortably well-off older folks who spend months in agony as they resolutely refuse to do anything other than wait their turn on the NHS list.
As I said, that is their prerogative, but it strikes me that an investment in private medical cover or, at the very least, private health services might be a sensible investment if you have the money (which many don’t). Until the left of the Labour Party abolishes private medicine – always a risk – it’s a free country, and spending money to keep you healthy is a great investment, arguably the greatest investment you can make. Unfortunately, it comes at a cost, which, as we have seen, is growing by the year. It’s not unreasonable to suppose that a couple in their 60s in decent health might be paying anything from £2 to £5k per annum for private medical cover.
Then there’s the risk that, as you hit your 70s and 80s, you might have to account for care home costs. Again, assuming the state will not underwrite your costs – more than likely, unless you live in Japan – it’s probably not unreasonable to assume you might need to keep anything between £50 and £200k as a reserve for the long term to fund those costs. You might be able to draw down some capital from home via equity release, but it’s best not to rely on that assumption.
So, from an investment perspective, where does this leave us? I would make three observations.
The first is that you might need more money than you pencilled into your wealth plan because of additional insurance costs or lump sums to cover care home costs.
That might prompt you to do one of two things: work later or stay invested in risky assets like equities longer, or even both. In many of my recent articles for Moneyfarm, I’ve noted that conventional asset allocation advice might no longer be quite fit for purpose. Traditional theory amongst financial planners argued that from your mid-50s, investors should dial down risk, do everything to conserve capital and then switch to de-accumulation (spend the money) by your mid-60s. This was predicated on actuarial data, which probably assumed retirement at 65 and living until 75, i.e., ten years of post-retirement. Those assumptions are no longer valid, and one could argue that the old, risk-reducing mid-50s have now become the mid-60s.
Given the costs of staying healthy longer and the increased longevity, more financial professionals suggest investing in riskier assets until you are older, and maybe not giving up work so early. This observation won’t work for everyone, and you should always seek professional advice, but I’d cordially suggest that taking on a bit more investment risk in your 60s might be worth exploring.
That leads me to the last suggestion: planning ahead for the care home hit. There’s a very decent chance you might never need to budget for care home costs, possibly because you’ve kept yourself healthy and addressed medical issues early on. You may not, though, be so lucky, and you may need, at the very least, to have a plan to pay for those costs – and relying on the local authority to pay for it does not constitute a plan. Again, this is where professional advice comes in handy, as they can walk you through various options, ranging from building buckets for different anticipated costs and associated investment strategies to less mainstream ideas like equity release. Every reader will have their own solution, but in all cases, by your late 60s, you need a plan.
I’ll finish with a more upbeat suggestion: why not capitalise on the trends I’ve discussed and build them into your investment strategy? By this, I mean considering investing in funds (or even stocks) that benefit from the durable, long-term trends I’ve discussed. Two ideas jump out: healthcare property funds and general healthcare funds. Healthcare property funds invest in everything from care homes for the elderly to GP surgeries. They are part of the wider infrastructure sector and tend to be income-oriented whilst also taking a conservative view of capital appreciation, in part by focusing on the quality of their property tenants and keeping leverage low.
More generally, there’s a growing number of funds that invest widely in an ageing society – across sectors from wealth management to healthcare – and, more specifically, in healthcare firms. That latter category tends to comprise two niches: much riskier biotechnology funds, which are better suited to really adventurous types, and lower-risk healthcare funds that invest in drug companies, hospitals and medical services firms. These funds haven’t shot the lights out compared with, say, AI and pure tech funds, but they do appeal to more defensive investors, especially if they pay out a decent income via dividends.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. The views expressed here should not be taken as a recommendation, advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post The hidden cost of living longer appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 5 minutesWe live in a society where news is much more accessible than it used to be. This is generally a good thing, however this news can also be a big driver in people’s decision making, particularly when it comes to money. Money is something that comes with a lot of emotion, particularly savings. People work […]
The post Should investors tune out the news for better outcomes? appeared first on MoneyFarm Insights.
]]>We live in a society where news is much more accessible than it used to be. This is generally a good thing, however this news can also be a big driver in people’s decision making, particularly when it comes to money.
Money is something that comes with a lot of emotion, particularly savings. People work hard for their savings and investments and it’s not just a number on a screen, it’s a path to a better retirement, a new house or just general better financial wellbeing. So, often, people acutely follow what is going on, trying to understand what it means for their money.
But with a high volume of news always swirling around, is this a good thing?
What’s in the news?
Very helpfully, the Federal Reserve Bank of San Francisco has developed an index, the Daily news sentiment index, which assesses the sentiment, positive or negative, across the 25 major news outlets (admittedly of the United States, however I think we can safely assume the tone was the same on our side of the pond) and gives a score between +1 and -1 for the day, ranking the positivity or negativity of the sentiment about economics and markets.
To show an example, here is the monthly average over the last 10 years (since January 2016 to be precise):
Over a long period of time, sometimes there’s positive news, sometimes there’s negative news, as you would expect.
However, what is striking, is if we look at the period since 2020, the picture looks very different:
Whether this is due to a structural change of the media landscape or something else, I will leave you to speculate, but it’s clear to see that the vast majority of news has been negative over the last (nearly) 7 years.
Most interesting is the consistency of negative news since the beginning of 2025.
How has this matched to market performance?
I have used our P6 portfolio as a proxy for financial markets as it gives a multi-asset view, but with a risk on sentiment:
Here you can see that, despite most months reporting negative news (line below 0), the portfolio (market proxy) has continued upwards. It’s not a straight line of course, there is (and always will be) some volatility along the way.
To show this in a more pronounced way, here is the daily news sentiment as a cumulative number which reflects both the direction but also the momentum of the news sentiment:
And for the more sceptical amongst you, below is the same chart but removing 2020 Covid news, which was understandably negative, although arguably a perfect example of what we are talking about given the market reaction:
The story is still the same, negative news sentiment, but positive market performance.
Again, the most striking part is the big divergence since the start of 2025, although there are many periods where the news is negative and performance is positive.
What does this mean for investors?
As mentioned at the beginning, people are often looking to the news for guidance about what is going to happen to their money. Negative news (often incessant as shown by the direction charts) can really take its toll on people’s confidence. This doesn’t always translate to investments being liquidated, but it may lead someone to perhaps not continue investing for their future, perhaps “this part will go into cash for now until things improve”.
This is perfectly understandable. Behavioural biases, particularly loss aversion, are well documented. People don’t like the idea of losing money. So negative news can often drive defensive decision making.
But whilst defending against downside risk feels more prudent, actually missing out on opportunities and not letting your money grow to its full potential can arguably be more detrimental in the long run.
Below I have picked out a handful (among many) of the most relevant negative news months, mostly because of the ‘size’ of the negativity. There will no doubt have been people in that month who decided not to invest, given the swirl of negativity around them. But here (again using P6 portfolio as a proxy for general investing) we look at the impact of the decision not to invest:
| Month | News sentiment (monthly avg) | Missed P6 performance to latest date | Annualised missed performance |
| Mar-20 | -0.38 | +108% | +11.9% |
| Apr-20 | -0.60 | +98% | +11.2% |
| May-20 | -0.63 | +91.3% | +10.8% |
| Jun-20 | -0.60 | +87.4% | +10.6% |
| Oct-22 | -0.22 | +66.8% | +13.9% |
| May-23 | -0.34 | +62.6% | +15.7% |
| Apr-25 | -0.14 | +37.9% | +25.3% |
| Mar-26 | -0.16 | +14.7% | +31% |
The numbers speak for themselves. Obviously the 2020 months are a well trodden conversation path about lessons learned, but the reason that I included four was to show that, whilst March was actually the bottom of the market, the main negativity came later whilst markets were actually really rallying.
The more recent ones reflect that, despite a high volume of negative news in 2025 and 2026, markets have looked right through this and delivered very strong performance.
Sadly, I am not able to promise that markets will always go up, but history shows that things are often not as bad as the media is making out, at least in terms of markets and economics. I have referenced the period since 2025 a few times as this has really been a period in which the news has been consistently negative, yet markets have been incredibly resilient and positive.
There is a lot of negative news around Artificial Intelligence, for example, which is capturing the imagination most in this period. But the lessons of history show that this shouldn’t deter investors from continuing to invest in their future and stick to their investment plans.
Bad news sells newspapers, but be careful letting it inform your investment decisions.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Should investors tune out the news for better outcomes? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 3 minutesEuropean government bonds have been in the spotlight over the past couple of weeks – with France a particular focus of attention. The chart below shows the rise in the yield on government debt over the past year. The pick up in rates has accelerated over the past three months. The story is a familiar […]
The post What Europe’s bond markets are telling us appeared first on MoneyFarm Insights.
]]>European government bonds have been in the spotlight over the past couple of weeks – with France a particular focus of attention. The chart below shows the rise in the yield on government debt over the past year. The pick up in rates has accelerated over the past three months.
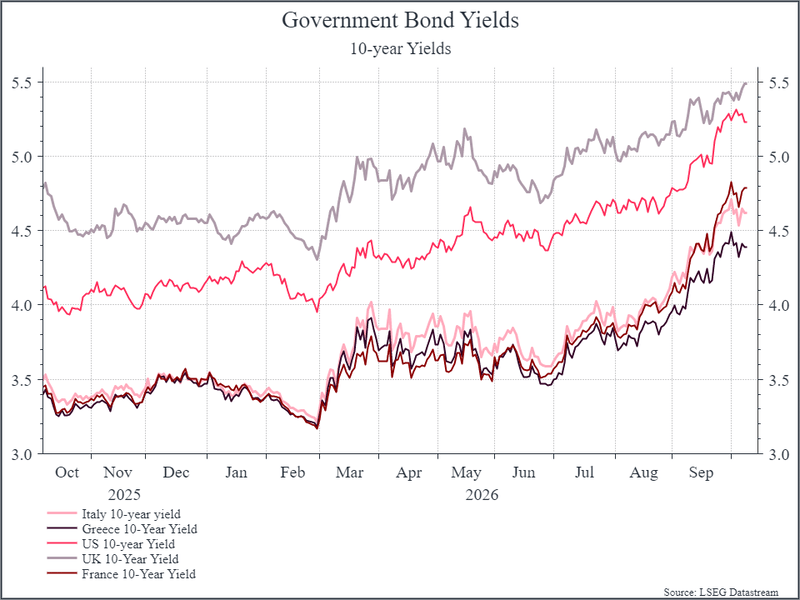
The story is a familiar one: fiscal deficits, rising debt to GDP and ageing populations are a tricky equation for politicians across Europe and the US. If there were easy solutions to this, then they would have already happened. Politics is polarised across much of Europe and there has so far been little appetite for the traditional prescription of lowering government spending and potential tax increases.
A rising cost of debt is a challenge for many governments running fiscal deficits, but investors have focused on France in recent weeks. The chart below shows how much the cost of debt for France has increased compared to Germany. It’s almost back to where we were in the Eurozone crisis of 2012.
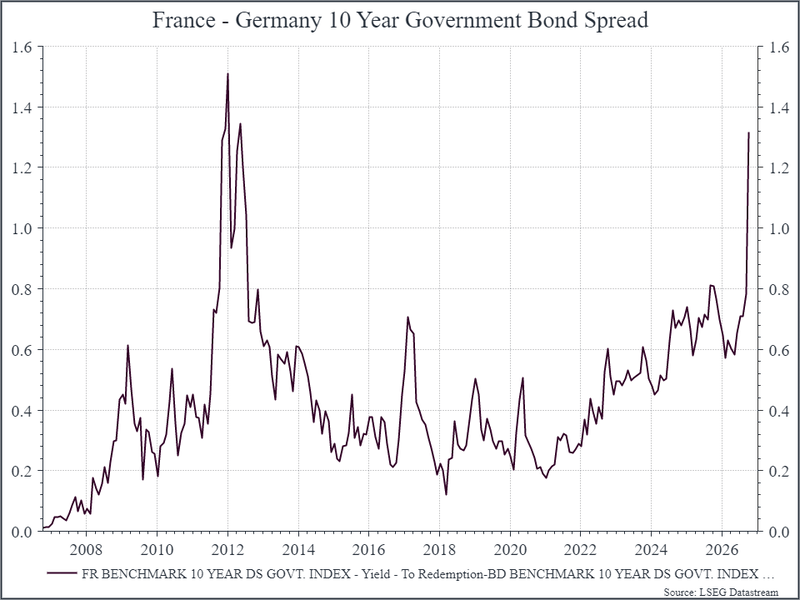
It’s also notable that investors now demand a higher return to lend to France than to Greece.
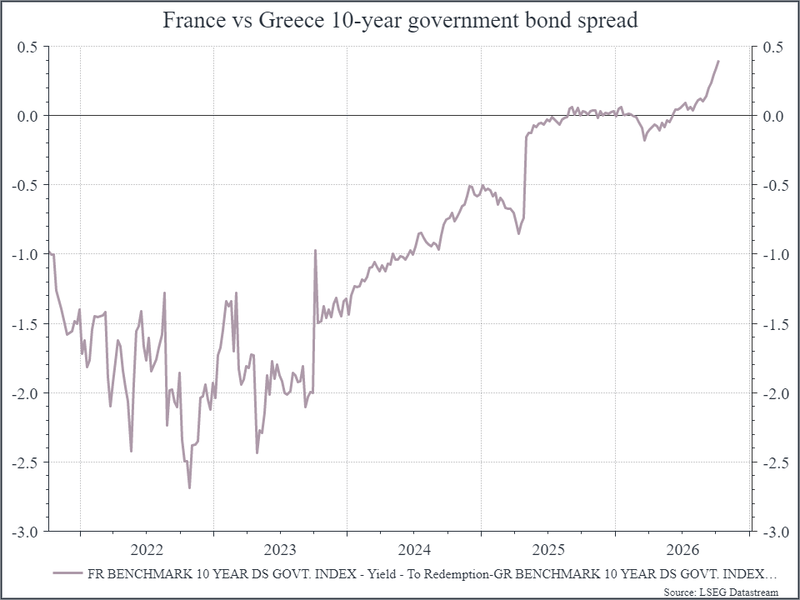
This is interesting because it should remind us that the situation can be resolved. On some metrics, the fiscal situation in Greece is moving in the right direction, albeit from high levels. The chart below shows government debt as a percentage of GDP – including a forecast from the International Monetary Fund. It shows a sharp improvement in Greek debt to GDP, in contrast to the other countries, where debt to GDP is moving higher. There’s lots of debate about the costs of making that change to the Greek economy, but from an investor perspective, the improvement has been notable.
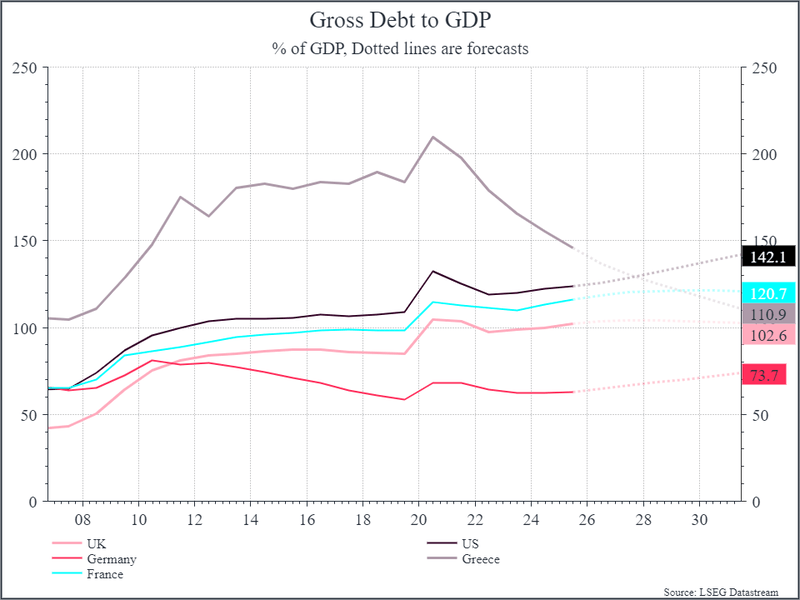
Uncertainty around government finances has spilled into the equity market. The chart below shows the relative underperformance of French equities compared to the rest of Europe since the 2024 French legislative election.
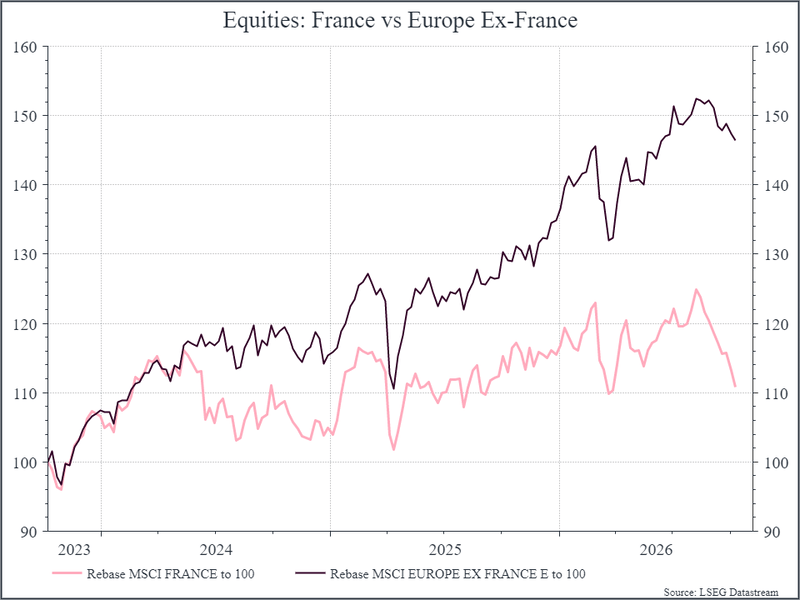
Looking forward, there are a few things to keep an eye on. We’ll have negotiations over the French budget coming up next week. Those are likely to be challenging, but that should be well understood. Oil prices have driven some of the rise in yields, and any improvement in oil supply could prompt some relief in European rates. In terms of policy, the European Central Bank has a range of tools to stabilise bond markets, should the need arise, but for now we think we’re still a bit away from that.
In terms of portfolios, we think we’ve kept the portfolios well-diversified and that has provided some protection during a period of interest rate volatility. We’ve generally kept the duration of our fixed income exposure quite low – favouring short-dated bonds. We’re conscious that yields have risen, so we’re evaluating if there’s an opportunity to buy some longer-dated bonds. We think that volatility in fixed income might stay with us for some time, but higher yields are looking more appealing.
The post What Europe’s bond markets are telling us appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: < 1 minuteWe are proud to have been included in the ranking of the UK’s 150 fastest-growing companies by the Financial Times, in partnership with Statista. The ranking recognises companies that achieved the highest compound annual revenue growth between 2022 and 2025, a period in which the country was still emerging from the Covid-19 pandemic while also […]
The post We are one of the Financial Times’ fastest-growing UK companies appeared first on MoneyFarm Insights.
]]>We are proud to have been included in the ranking of the UK’s 150 fastest-growing companies by the Financial Times, in partnership with Statista.
The ranking recognises companies that achieved the highest compound annual revenue growth between 2022 and 2025, a period in which the country was still emerging from the Covid-19 pandemic while also dealing with the energy crisis following the outbreak of the full-scale war in Ukraine.
This recognition provides further confirmation of Moneyfarm’s sustained growth since its foundation, with continued progress in total assets, net inflows and our active client base, alongside further advances in product innovation.
The post We are one of the Financial Times’ fastest-growing UK companies appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 3 minutesIn recent years, the link between money and happiness has been widely debated. But research is going beyond clichés. A study published in Studies of Applied Economics1 offers a clear perspective: across 37 researches published between 2001 and 2019, the evidence shows that financial wellbeing and mental health are closely connected. Beyond income: what financial […]
The post Financial wellbeing can benefit your mental health appeared first on MoneyFarm Insights.
]]>In recent years, the link between money and happiness has been widely debated. But research is going beyond clichés. A study published in Studies of Applied Economics1 offers a clear perspective: across 37 researches published between 2001 and 2019, the evidence shows that financial wellbeing and mental health are closely connected.
Beyond income: what financial wellbeing really means
Financial wellbeing is often equated with income or net worth. But the review shows it’s much broader: it includes the ability to plan for future expenses, manage debt, feel financially secure, and build confidence in facing unexpected shocks. In other words, it’s not just “how much you have,” but how you feel about your finances.
This perspective leads directly to three essential pillars of personal finance: having a defined time horizon (thinking both short- and long-term), so you don’t get swayed by momentary fluctuations; managing risk to prevent unexpected events from becoming financial crises; and diversifying your income sources and investments, so you’re not overly reliant on just one.
Financial stress: the key factor
The study highlights financial stress as the key mediator between money and mental health. Worries about bills, mortgages, medical expenses, or debt often fuel anxiety and depression more than absolute income levels. It’s the psychological burden of insecurity – not just the financial condition itself – that drives mental distress.
This is where a clear time perspective, risk management, and diversification prove vital: an emergency fund spread across liquid assets, a clear debt strategy, and a diversified portfolio can all reduce the intensity of financial stress.
The first steps in financial planning
In this context, it is useful to outline the key steps of a sound financial planning process – an approach that not only strengthens long-term outcomes, but also supports peace of mind.
- Understanding your investor profile: this is shaped by a combination of factors, including your level of financial knowledge, past investment experience, and your capacity to tolerate market risk in terms of volatility and potential losses.
- Defining a clear investment objective: rather than focusing solely on “making a return”, it is essential to identify concrete goals, future needs, upcoming expenses, and potential unforeseen events over the coming years – or even decades – both for yourself and for those who depend on you.
- Establishing your time horizon and determining the optimal asset allocation: this involves choosing the right mix across asset classes, as well as selecting the most appropriate instruments. Here, diversification and cost control play a critical role.
Once these foundations are in place, it is vital to test and monitor each element over time. This means regularly reassessing your financial plan in light of life goals and periodically re-evaluating your investor profile. Combined with an awareness of macroeconomic trends, this ongoing self-assessment ensures that your investments and objectives remain aligned – both in terms of timing and expected returns.
Not having the right investment approach – combined with a lack of emotional control during challenging market phases – can often be more dangerous than investing at the “wrong” time with a well-structured plan.
As highlighted by Morningstar’s Mind the Gap research, being aware of behavioural biases when facing difficult situations can help investors guard against impulsive decisions.
Financial education as prevention
One of the central recommendations is the role of financial education. Budgeting, building emergency savings, and structured debt management are not only economic skills but also preventive health tools. Individuals who practice these habits consistently show lower levels of anxiety and depression.
Here again, the long-term horizon matters: saving for retirement or setting aside funds for the future is a way of taking care of your future self. Risk management – through insurance or portfolio diversification – makes it easier to face uncertainty.
Perhaps the most important message is this: financial wellbeing is a public health issue. Reducing financial stress means lowering the prevalence of anxiety and depression in society, easing pressure on healthcare systems and improving productivity.
Conclusion: managing money, protecting mind
The systematic review leaves us with a clear takeaway: taking care of your finances is also taking care of your mental health. It’s not about absolute wealth, but about perceived security, planning, and reducing financial stress.
For individuals, that means concrete steps: tracking spending, building an emergency fund, managing debt – and applying the three key principles of long-term thinking, risk management, and diversification.
- Hassan, M. F., Mohd Hassan, N., Kassim, E. S., & Utoh Said, Y. M. (2021). Financial Wellbeing and Mental Health: A Systematic Review. Studies of Applied Economics, 39(4). ↩︎
The post Financial wellbeing can benefit your mental health appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 3 minutesThe global economy remains as complex as ever given all the cross-currents of geopolitical conflict, rising inflation and increased investment in technology. We wanted to highlight some of the data points we’ve been looking at over the past week. They show some of the strength in the global economy, while also highlighting the challenges that […]
The post The global economy is holding up: here’s why appeared first on MoneyFarm Insights.
]]>The global economy remains as complex as ever given all the cross-currents of geopolitical conflict, rising inflation and increased investment in technology. We wanted to highlight some of the data points we’ve been looking at over the past week. They show some of the strength in the global economy, while also highlighting the challenges that are weighing on households.
It’s been a theme for some time, but this week we got another reminder about the differences between sentiment indicators and actual macro data. Consumers say they are nervous, but they continue to spend. The Conference Board, a US economic research organisation, released its consumer sentiment survey, showing the lowest level of consumer confidence in a decade (see chart below).
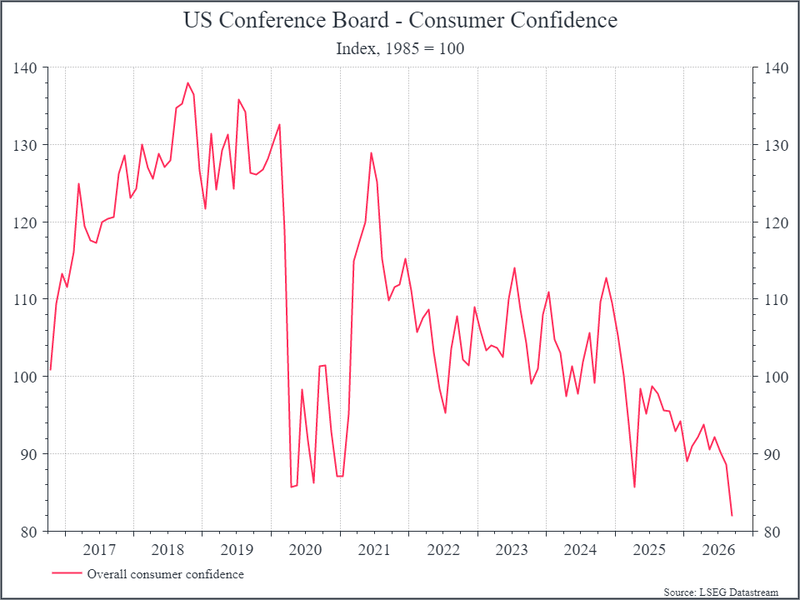
At the same time, personal consumption growth in the US is pretty robust, rising over 6% year-on-year (including inflation).
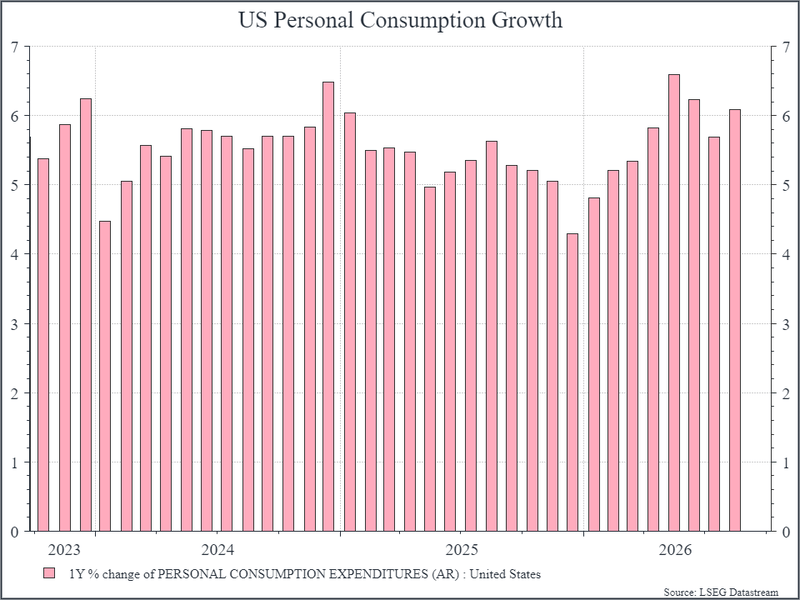
Decent economic news isn’t limited to the US. The latest surveys for business activity in Europe point to pretty decent growth (see chart below, a reading above 50 typically indicates growth). Even manufacturing surveys have shown an improvement despite the well-documented challenges.
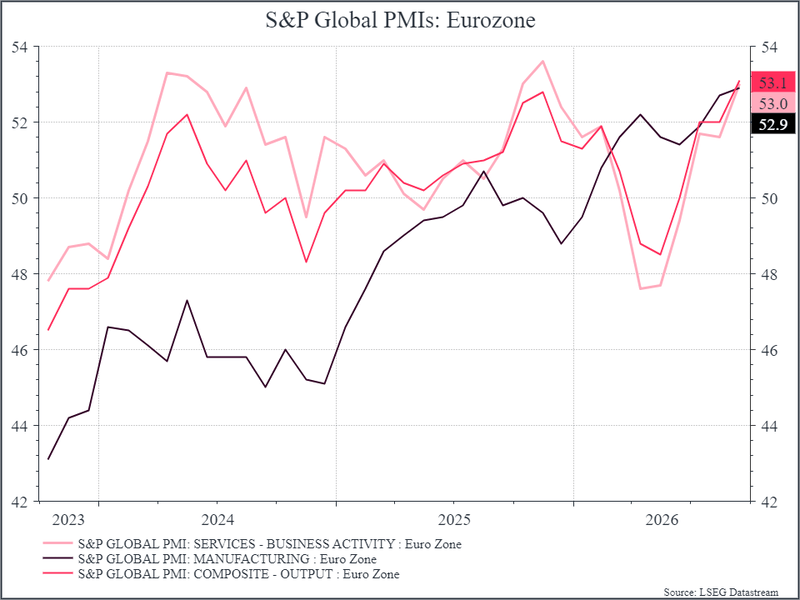
In China, the picture is a bit mixed. Manufacturing surveys suggest fairly tepid growth, at least by historical standards, although Chinese industrial profit growth has accelerated from low levels. On the consumer side retail sales growth has been pretty muted.
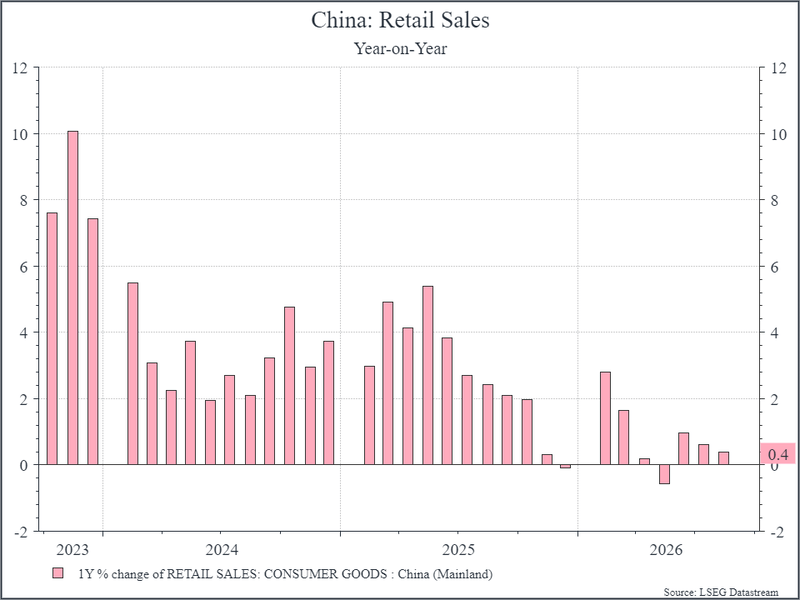
The trade picture in Asia is more positive. Chinese exports have picked up over the past few months, even to the United States (see chart below).
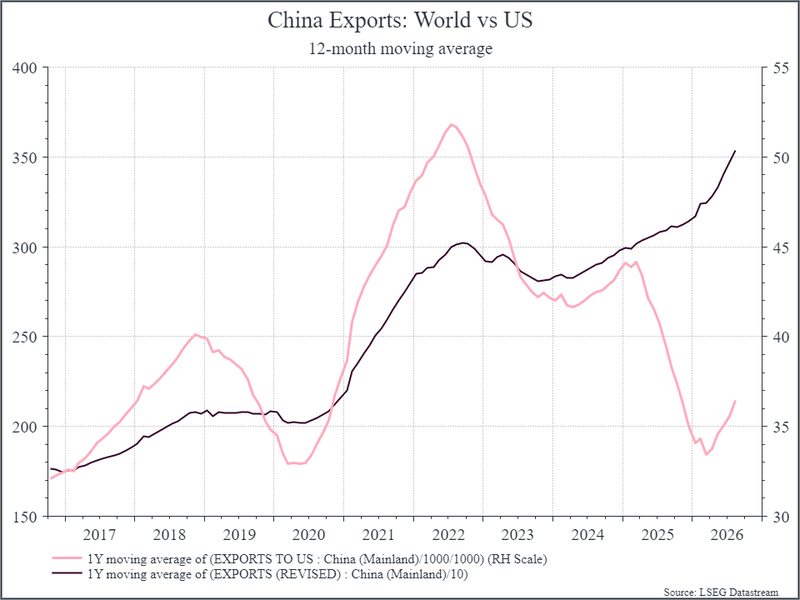
The picture is more pronounced in Korea, with export growth currently running at close to 80% year-on-year – a macro indicator of the demand for Korean tech products. Historically, robust Korean exports have pointed to solid earnings growth for global equities (see chart below).
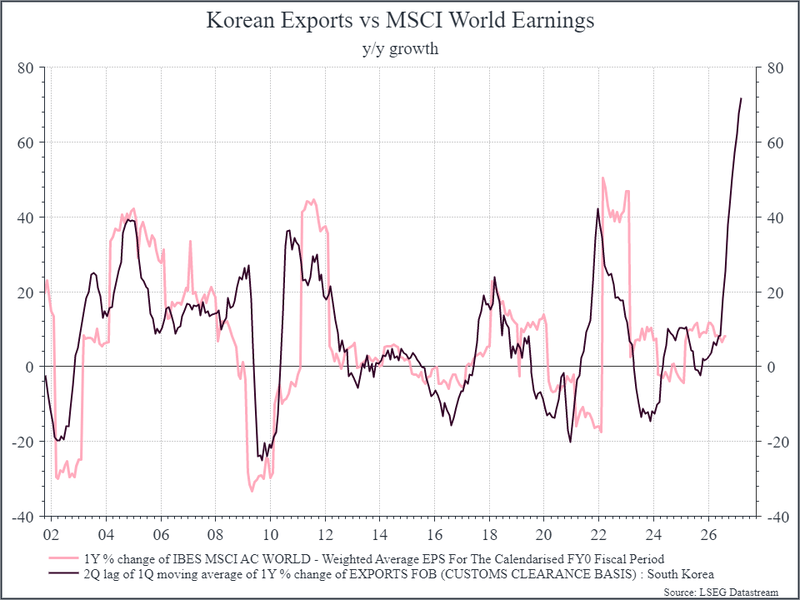
Finally, there’s inflation. The outlook here is more challenging and that should bring higher policy rates in the coming quarters. Eurozone inflation hit its highest level in three years in September – with annual inflation in Spain reaching 4.9%.
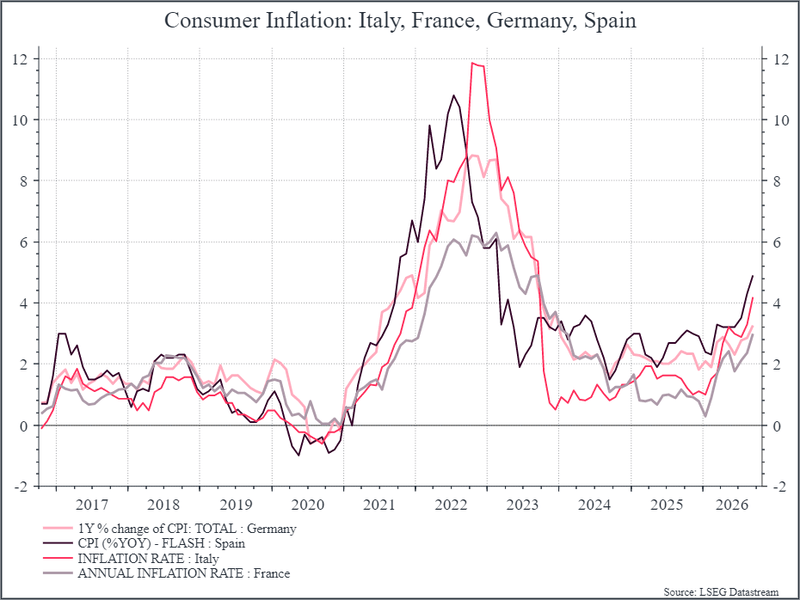
The picture is similar in the US, although the pick-up in inflation has so far been less pronounced (through August). The Personal Consumption Expenditures (PCE) deflator – the preferred metric of the US Central bank – rose 3.4% year-on-year, although the figure was lower if you exclude food and energy.
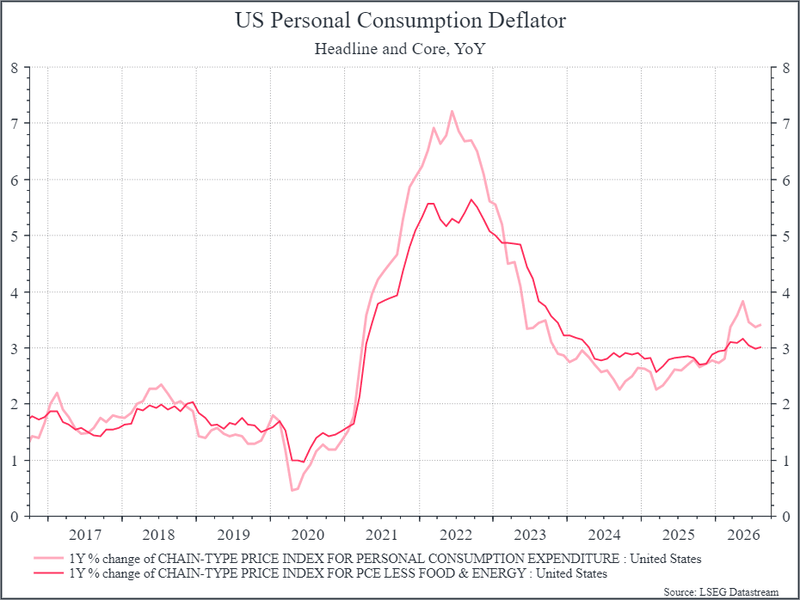
So where does this get us? Despite the long list of challenges, the global economy has held up better than we might have expected. Spending on Artificial Intelligence, and tech more broadly, has had a significant impact. In some respects it has helped to offset the potential slowdown from higher energy prices, and led to stronger growth. In other ways it has exacerbated some macro challenges, increasing demand for power generation, construction materials and certain commodities. That’s helped to push interest rates higher, making life tougher for borrowers.
It remains quite a delicate balance, but we are wary of focusing only on the negative scenarios. It’s fair to say that higher interest rates could slow down growth and impact corporate earnings. But on a more positive note, geopolitical de-escalation could produce lower energy prices, lower inflation and relief for many households and businesses – allowing for a further acceleration in economic activity. We’ll continue to monitor the global environment carefully, ready to shift our positioning as our outlook adjusts.
The post The global economy is holding up: here’s why appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 6 minutesEvery now and then, most of us set goals for ourselves. Run a marathon. Learn a language. Save more money. But sooner or later, they quietly fade away. Not because we did not mean them, but because we never worked out how we would get there. Money works in the same way. Most of us […]
The post Turn your financial goals into a plan appeared first on MoneyFarm Insights.
]]>Every now and then, most of us set goals for ourselves. Run a marathon. Learn a language. Save more money. But sooner or later, they quietly fade away. Not because we did not mean them, but because we never worked out how we would get there.
Money works in the same way. Most of us know what we want: a comfortable retirement, a home of our own, a child’s university fees covered, or simply the freedom to choose how we spend our time. Far fewer of us have a clear route for getting there. A goal without a plan is just a wish.
The good news is that a financial plan does not need to be complicated, and you do not need to be an expert to create one. What matters most is having one in the first place and then having the discipline to stick to it when life and markets get noisy. This may sound simple at first glance, but the latter part is where most plans fail.
In this article, we look at what a financial plan really involves, why having one makes such a difference, and most importantly, how to stay on course when it feels tempting to change direction.
What is a financial plan?
A financial plan is like using GPS while driving. It shows where you are now, where you want to be, and the route that leads you to your destination. It compares different paths and provides you with the most straightforward option.
Simply put, a financial plan turns vague ambitions like “I’d like to retire comfortably” into specific targets, each with an amount and a date attached.
A good plan is built on four foundations.
- Your goals: what are you saving for, how much will you need, and when will you need it? A house deposit in five years, a wedding in two, and retirement in thirty are three very different goals, and each needs its own approach.
- Your cashflow: what comes in each month, what goes out, and what is realistically left over? This is where many people get a pleasant surprise. Once you track your spending properly, it often becomes clear that there is more room to save than you thought.
- Your safety net: before investing for the future, you need a cushion for the present. An emergency fund of around three to six months of essential expenses means an unexpected bill, like a broken boiler, does not force you into debt or into selling your investments at a bad time.
- Your attitude towards risk: How comfortable are you with the value of your investments rising and falling? And how much risk can each goal afford? Money you need in two years should usually be treated very differently from money you will not touch for twenty years.
Finally, a good plan makes the most of the options available to you. Stocks and Shares ISAs, Cash ISAs, Junior ISAs, pensions, and GIAs all have a role to play, and using them in the right order helps more of your money keep working for you.
Why having a plan helps
A plan gives every pound a job. By utilising a plan, saving becomes a deliberate choice rather than an afterthought. There are multiple ways a plan can help you:
Provides clarity: saying “I want to buy a house one day” is a wish. Saying “I want a £30,000 deposit in five years” is a goal. Once you have a number and a date, you can work out what you need to put aside each month, roughly £500 in this example, before any investment growth. Suddenly the goal feels achievable, because you know exactly what it takes.
Helps you prioritise: most of us are juggling several goals at once. Should you overpay the mortgage, build up your pension, or save for the family holiday? A plan helps you decide what comes first. It also stops short-term wants from quietly crowding out long-term needs, which is one of the easiest traps to fall into.
Builds confidence: when you can see that you are on track, money becomes a source of reassurance rather than worry. And if you are off track, a plan tells you early, while there is still time to make small adjustments rather than drastic ones.
Leads to better decisions: a plan also acts as a filter. When you are faced with a big financial decision, whether that is a new car, a career change or an unexpected windfall, you can ask a simple question: does this move me closer to my goals, or further away?
Why sticking to it matters
Now we understand the importance of building a financial plan, and why it is helpful. The real challenge is sticking to it. Creating a plan is the easy part. Following it, month after month and year after year, is where the real results come from.
It is very important to understand that compounding needs time. When your investments grow, that growth can go on to earn growth of its own. The effect is modest in the early years and increasingly powerful in the later ones, but only if your money stays invested long enough for it to build.
Let’s put some numbers to it. Imagine you invest £200 a month, and your investments grow by 5% a year. After 20 years, you would have paid in £48,000 and your pot would be worth around £80,000. Keep going for another five years, and you would have paid in £60,000 in total, but your pot would be worth around £115,000. Those final five years add roughly £35,000 to your pot, even though you only contributed £12,000 of it. That is compounding at work, and it rewards those who stay the course.
This example is for illustration only, assumes a constant rate of growth and does not take account of fees. Returns are not guaranteed.
Novice investors should also be aware that ultimately time in the market beats timing the market. It is tempting to think you can sell before markets fall and buy back before they recover. Even professional investors struggle to do this consistently. Some of the strongest days in markets have historically come shortly after some of the weakest, so investors who sell during a downturn and wait for things to “feel better” often miss part of the recovery. What would have been a temporary fall becomes a permanent loss.
Behavioural finance tells us that we tend to feel the pain of a loss more sharply than the pleasure of an equivalent gain. Fear tempts us to sell when prices fall. Excitement tempts us to chase whatever has recently done well. Both can knock a sensible plan off course. Therefore, a plan agreed in calmer times acts as a steady reference point when emotions run high.
Simply put, sticking to a plan does not mean ignoring the world around you. It means responding to changes in your circumstances, not to the day’s headlines.
How to stay on track
So how do you stick to a plan when life gets busy and markets get bumpy? A few simple habits make a big difference:
Pay yourself first. Set up a regular monthly contribution that leaves your account on payday, before you have had a chance to spend it. Once it is automated, saving becomes a habit rather than a decision you must make every month.
Review regularly, not constantly. Check in on your plan once or twice a year, or whenever something significant changes. Checking your portfolio every day tends to magnify short-term swings and makes it harder to stay calm.
Revisit your plan when life changes. A new job, a pay rise, getting married, having children or receiving an inheritance may all mean your goals, timelines or attitude to risk need updating.
Keep your emergency fund topped up. If you do need to dip into your cash cushion, make rebuilding it a priority. It is what allows your long-term investments to stay invested.
Use your allowances each year. Your ISA allowance works on a “use it or lose it” basis each tax year, and pension contributions benefit from tax relief. Making the most of both helps your plan work harder for you.
Talk to a professional. A conversation with a professional can help you test your assumptions, spot gaps and keep things in perspective when markets are unsettled. At Moneyfarm, you can always book a call with us to discuss your options in detail to find assistance with building a financial plan.
Conclusion: consistency is the key to success
Reaching your financial goals is less about finding the perfect investment and more about consistency. Set clear goals, build a plan that fits your circumstances, and then give it the time it needs to work. There will be months when markets fall and moments when it feels tempting to change course. That is exactly when your plan earns its keep.
So, ask yourself: do I have a plan for my money, and am I sticking to it?
At Moneyfarm, we make it simple to turn your goals into a plan, with ISAs, pensions and diversified portfolios managed by our experts.
If you would like help putting a plan together, or checking that your current one is still on track, our team is here to talk it through with you.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Turn your financial goals into a plan appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 5 minutesFor years, keeping money in cash came with an obvious trade-off: stability in exchange for very little return. Higher interest rates have changed that calculation. Cash and short-dated government debt can now generate meaningful income, while longer-dated bonds offer investors the opportunity to lock in relatively attractive yields. At the same time, gold remains elevated […]
The post Cash, bonds or gold: what should your ‘safe’ money be doing? appeared first on MoneyFarm Insights.
]]>For years, keeping money in cash came with an obvious trade-off: stability in exchange for very little return. Higher interest rates have changed that calculation.
Cash and short-dated government debt can now generate meaningful income, while longer-dated bonds offer investors the opportunity to lock in relatively attractive yields. At the same time, gold remains elevated after a period in which geopolitical uncertainty and concerns around inflation and currencies have increased demand for traditional defensive assets.
That leaves investors with what sounds like a simple question: where should the safer part of your wealth sit today?
The answer depends less on which asset currently offers the highest yield and more on what you need that money to do.
Cash: stability, accessibility and a return
Cash has become an increasingly attractive part of the financial toolkit.
With interest rates still relatively high, savers can earn a meaningful return while keeping their money stable and accessible. For an emergency fund, a house deposit, planned spending or simply money you want to keep readily available, that combination can be particularly valuable. And when cash is held within an Individual Savings Account (ISA), the interest earned is tax-free.
The key is understanding the role cash plays alongside other investments. Cash rates tend to move with monetary policy, so the return available today may change as interest rates change. Inflation also matters: over longer periods, preserving purchasing power becomes increasingly important alongside protecting the nominal value of your savings.
That doesn’t make cash simply a short-term stopgap. It can be a useful and deliberate part of a broader financial plan, particularly for money where accessibility and stability are the priority.
For capital with a longer time horizon, investors may then consider whether other assets can complement their cash holdings by offering different sources of income or potential growth.
Ultimately, the right role for cash depends on what you need that part of your money to do.
Bonds: locking in income for longer
Bonds can play an important role for investors looking for a combination of income, diversification and greater stability than equities.
While cash rates can change relatively quickly as monetary policy evolves, bonds offer the opportunity to lock in yields for longer periods. High-quality government and corporate bonds can therefore provide a more predictable stream of income over a medium-term horizon, while also helping to balance the risk of other assets within a diversified portfolio.
Bond prices can still fluctuate. Changes in interest rates affect the value of existing bonds, with longer-dated bonds generally more sensitive to rate movements. At the same time, those movements can create opportunities for actively managed portfolios to adjust their positioning across different maturities and types of bonds as market conditions evolve.
This makes bonds particularly useful as part of a broader defensive strategy: investors can access different sources of income and diversify across issuers, maturities and markets rather than relying on a single rate or instrument.
The role bonds play ultimately depends on the investor’s timeframe and risk profile, and on how they fit alongside cash and other assets within the wider portfolio.
Gold: a different kind of diversifier
Gold plays a different role from cash and bonds. It does not pay interest, but it can behave differently from traditional financial assets during periods of inflation concerns, geopolitical stress or market uncertainty.
That can make it a useful diversifier within a broader portfolio. But gold prices can also be volatile, so it should not be confused with cash or other assets whose primary role is to provide stability and accessibility.
Perhaps the real question isn’t cash vs bonds vs gold
Putting the three side by side reveals the problem with asking which is “best”. They are designed to do different jobs.
Cash prioritises accessibility and short-term stability. Bonds can provide income and allow investors to lock in yields for longer. Gold can offer diversification against risks that may affect conventional financial assets differently.
And for money with a genuinely long investment horizon, there is another consideration altogether: growth.
Holding too much wealth in defensive assets can reduce volatility, but it can also mean giving up some of the potential returns associated with assets such as equities. Over long periods, that opportunity cost can become significant.
So rather than asking where all your money should go, it can be more useful to divide wealth according to its purpose.
Money you might need soon has a different job from money intended for five years’ time. And both have a different job from money you’re putting aside for retirement decades from now.
From choosing an asset to building a portfolio
The more useful question, then, is not which defensive asset looks most attractive today, but what each part of your wealth is there to achieve.
That starts with your goals. Money set aside for an emergency, a house purchase or a planned expense needs a different approach from money you will not need for many years. The shorter the time horizon, the more important stability and accessibility tend to become. With a longer horizon, investors generally have more time to ride out periods of market volatility and can consider allocating more towards assets with greater long-term growth potential.
This is where diversification becomes more useful than trying to predict which individual asset will perform best next. Cash, bonds, equities and other assets respond differently to changes in interest rates, inflation, economic growth and investor sentiment. Combining them can help spread risk rather than relying on a single source of return or protection.
Time horizon matters here too. A diversified portfolio designed for a long-term goal does not necessarily need to avoid volatility altogether. If the money will not be needed for decades, short-term fluctuations may be less important than the ability to grow purchasing power over time. As the goal approaches, however, it can make sense to gradually reduce exposure to assets where short-term movements could have a larger impact on the amount available when the money is needed.
This is one reason why investing for a goal is different from simply choosing an asset. The objective is not to find the asset that will perform best in the next few months, but to build an approach that gives your money a reasonable chance of being there, in the right amount, when you need it.
At Moneyfarm, our Managed Portfolios combine different asset classes, including equities and bonds, within globally diversified portfolios designed around different levels of risk. Our investment team monitors the portfolios and, through our actively managed strategy, adjusts their positioning as market conditions change.
For capital with a shorter horizon, Moneyfarm also offers Smart Yield, our low-risk money-market investment solution. And for money that genuinely needs to remain in cash, a Cash ISA can provide easy access while earning interest tax-free.
The point isn’t that every pound should be invested in the same way. It’s almost the opposite.
Different parts of your wealth can have different jobs – and your investment strategy should reflect that.
So gold may be an interesting way into the conversation, particularly when markets are focused on inflation, geopolitics or uncertainty. But it is only one piece of the puzzle. The more important questions are what you are investing for, when you will need the money, how much volatility you can accept along the way and how different assets can work together to help you reach that goal.
Rather than chasing whichever asset currently offers the most attractive headline return, a long-term approach starts with the goal and works backwards: how much do you need, when will you need it, and what combination of investments gives you a suitable balance between growth, risk and stability.
Please remember that when investing, your capital is at risk. The value of your portfolio with Moneyfarm can go down as well as up and you may get back less than you invest. Past performance is not a reliable indicator of future performance. Tax treatment depends on your individual circumstances and may be subject to change in the future. The views expressed here should not be taken as a recommendation, tax advice or forecast. If you are unsure investing is the right choice for you, please seek financial advice.
The post Cash, bonds or gold: what should your ‘safe’ money be doing? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 8 minutesInvesting is not only about financial returns. You may also want your money to reflect your personal values, if these relate to the environment, society, ethical principles or faith. Today, you have a growing number of ways to invest with your values in mind. From ESG and sustainable funds to impact, ethical and faith-based investing, […]
The post Sustainable Investments: From ESG to Faith-Based, What Options Are Available? appeared first on MoneyFarm Insights.
]]>Investing is not only about financial returns. You may also want your money to reflect your personal values, if these relate to the environment, society, ethical principles or faith.
Today, you have a growing number of ways to invest with your values in mind. From ESG and sustainable funds to impact, ethical and faith-based investing, you can choose the approach that best reflects what matters to you.
This guide gives you a simple overview of the main options available, explains how they differ, and highlights some key points to consider when choosing a sustainable investment strategy.
| What are sustainable investments? | They are investments in companies or projects that try to protect the environment, support society, and act responsibly |
| What is ESG? | ESG stands for Environmental, Social and Governance |
| How to invest in sustainable investments? | You can invest in ESG funds, green bonds, or shares of sustainable companies |
| Is it risky? | Yes, all investments involve some risk |
What Are Sustainable Investments?
Sustainable investing allows you to consider more than just financial returns when deciding where to invest your money. It gives you the opportunity to take environmental, social and ethical factors into account alongside your financial goals.
There are different approaches you can choose from, depending on the values and priorities that matter most to you. Here are some things to know.
- Sustainable investments integrate environmental, social and governance (ESG) factors into investment decisions alongside financial considerations.
- Common approaches include ethical investing, impact investing, socially responsible investing (SRI) and green-themed strategies.
- Investors can choose portfolios focused on ESG leaders, companies in the process of transitioning towards sustainability, those pursuing measurable impact, or a combination of these.
- Although sustainable investments are increasingly accessible and competitive, they may not be suitable for every financial objective or risk profile.
- Consulting a regulated financial adviser can help align your values with a long-term investment strategy tailored to your needs.
Example: A UK-based investor seeking to avoid fossil fuels could select a socially responsible fund that excludes oil and gas companies. Another might choose an “improvers” fund focusing on energy utilities actively transitioning to renewables.
Sustainable investing enables you to support the causes you care about — from environmental protection to human rights or faith-based values — without necessarily compromising returns.
What is ESG (Environmental, Social and Governance)
Sustainable investing refers to strategies that aim to generate financial returns whilst also delivering positive outcomes for society and the environment.
| ESG factor | What does it mean? | Examples |
| Environmental | Looks at how a company affects the environment | Climate change, carbon emissions, energy use, waste and biodiversity |
| Social | Looks at how a company treats people and society | Working conditions, human rights, diversity and people’s safety |
| Governance | Looks at how a company is managed and governed | Focuses on structure, organisation, business ethics, transparency and anti-corruption |
Sustainable investing does not mean sacrificing returns; you can still choose investments with long-term growth potential. For instance, a fund manager might sell shares in a company linked to deforestation, even if profitable in the short term, to reduce long-term environmental risk.
By considering environmental, social and governance factors, you can support businesses that focus on issues such as reducing their environmental impact, treating people better and following responsible business practices.
Avoiding Greenwashing
Greenwashing happens when an investment or a company is presented as more sustainable or environmentally friendly than it really is. A company may use words such as “green”, “ESG” or “sustainable”, but these words alone do not tell how the company actually invests.
When choosing an ESG or sustainable fund, look beyond the name and marketing. Ask yourself:
- What does the fund actually invest in? Check its main companies and the sectors it invests in. A fund described as sustainable may still invest in companies with activities that do not match your values.
- What are the fund’s sustainability goals? Look for clear objectives and measurable information, such as carbon emissions, climate targets or other ESG indicators.
- How does the fund select its investments? Read the fund’s investment approach and check if it uses exclusions, ESG ratings, engagement with companies, or other sustainability criteria.
- Can the claims be supported by evidence? Look for regular reports, data and clear explanations of how the fund is progressing towards its sustainability objectives. Independent labels or certifications can also provide additional information.
In 2026, rules in both the EU and UK are placing emphasis on making sustainability claims clear and more closely linked to how funds actually invest. For example, the FCA’s Sustainability Disclosure Requirements (SDR) include rules on sustainability-related names and marketing, as well as an anti-greenwashing rule.
How to Identify High-Quality Sustainable Investments
Not all sustainable investments follow the same principles. They are often categorised by their investment philosophy and sustainability objectives. Here are some examples.
| Category | Description | Example |
| ESG leaders | Invest in companies already strong on ESG metrics | Ørsted is a renewable energy company that completed its transition and now generates 99% of its energy from renewables |
| Transitioning companies (ESG improvers) | Focus on firms improving ESG practices | Unilever has clear sustainability goals and works to reduce its environmental and social impact |
| Impact investments | Aim for measurable social or environmental outcomes | Groupe SOS is a French social enterprise focused on social and environmental challenges, working in areas such as healthcare, social inclusion, education and sustainable development |
| Blended objective strategies | Combine ESG criteria with traditional financial goals | A diversified fund that combines ESG screening with investments across different sectors and regions |
Example scenario: An “impact” fund could support microfinance programmes in emerging markets, while an “ESG leader” fund might hold established clean energy companies.
In the UK, the SDR (Sustainability Disclosure Requirements) will soon label funds to help investors distinguish authentic ESG strategies from those with minimal sustainability focus. Similar standards are already in place in the EU under the SFDR.
Sustainable vs Traditional Investing
Traditional strategies focus primarily on financial return, often ignoring social or environmental consequences. Sustainable investing, by contrast, integrates ethical, environmental and governance factors. This might mean excluding sectors such as fossil fuels or tobacco, or actively engaging with companies to improve their practices.
A sustainable fund, for example, might exclude coal mining but invest in electric vehicle manufacturers to benefit from the long-term growth of clean transport. For instance, an ESG-screened UK equity fund might underweight oil majors like BP and overweight renewable energy developers such as SSE.
While some high-yield sectors may be excluded, sustainable strategies are increasingly competitive and align more closely with long-term economic and regulatory trends.
| Traditional investing | Sustainable investing |
| Mainly focuses on financial returns | Considers financial returns and sustainability factors |
| May invest in any sector, including fossil fuels or tobacco | May exclude certain sectors based on ethical or sustainability criteria |
| Usually focuses on a company’s financial performance | Also considers environmental, social and governance (ESG) factors |
| Does not necessarily consider a company’s social or environmental impact | Looks at how a company affects people, society and the environment |
Common Types of Sustainable Investment
There are several distinct approaches, each with its own philosophy and objectives:
1. Socially Responsible Investing (SRI)
An SRI equity fund uses negative screening to avoid sectors considered harmful (e.g. tobacco, weapons, fossil fuels) thus might exclude all companies involved in tobacco production, arms manufacturing or gambling. For example, it might remove British American Tobacco and BAE Systems from its portfolio, focusing instead on consumer staples and technology companies with cleaner ESG profiles.
For example, the iShares MSCI Europe SRI UCITS ETF applies exclusions to areas including controversial weapons, tobacco, civilian firearms and fossil-fuel extraction.
2. Ethical Investing
Those are investments based on personal or shared moral values (e.g. animal welfare, fair labour). What is considered “ethical” is subjective. One investor may exclude companies conducting animal testing, while another may prioritise climate impact.
An ethical fund might avoid fast fashion retailers linked to labour rights controversies and prioritise brands with Fairtrade or B-Corp certifications. For example, it might underweight companies such as Shein or Primark and increase allocations to Patagonia or other certified ethical brands.
For example, VanEck Sustainable Future of Food UCITS ETF invests in companies helping to make food production more sustainable, from alternative proteins and organic food to precision agriculture and innovative food technologies.
3. ESG Investing
Data-driven investments that use scoring systems for environmental, social and governance performance.
An example of UK-based ESG-integrated global equity fund could overweight Unilever for its high supply chain standards and carbon reduction targets, while underweighting companies with weak governance structures or excessive executive compensation.
4. Impact Investing
This type of investing goes beyond risk analysis and scoring, seeking to generate direct, measurable positive outcomes alongside financial returns.
An impact investment fund could allocate capital to micro-solar grid projects in sub-Saharan Africa, measuring outcomes such as the number of households gaining access to electricity for the first time. Another example could be investing in microfinance institutions such as FINCA to support small business creation.
5. Faith-Based Investing
It aligns portfolios with religious teachings or spiritual values. A Sharia-compliant fund will exclude banks that derive significant income from interest-based lending and companies involved in the alcohol or gambling industry. For example, it could invest in halal-certified pharmaceutical companies or businesses operating in the clean energy sector instead of conventional banks.
6. Green-Themed Strategies
These investments focus specifically on environmental sustainability and target sectors such as clean energy, sustainable agriculture and low-emission transport.
A green bond fund could finance the construction of offshore wind farms in the North Sea or sustainable transport infrastructure such as low-emission rail networks across Europe.
While green investing shares objectives with broader ESG or impact frameworks, it is best understood as a thematic focus rather than a standalone methodology.
For example, the iShares Global Clean Energy Transition UCITS ETF invests in companies involved in clean energy and tracks the S&P Global Clean Energy Transition Index. As of September 2026, it held 106 companies.
Comparison of Common Sustainable Investment Types
| Type | Investment Methodology | Main Focus | Example Sector or Project |
| SRI | Exclusionary screening | Avoiding harmful industries | Tobacco, weapons, fossil fuels |
| Ethical investing | Values-based selection | Alignment with moral beliefs | Animal welfare, fair labour |
| ESG investing | Scoring and integration | Risk management & ESG factors | Companies with high ESG ratings |
| Impact investing | Intentional, outcome-based investments | Measurable social/environmental outcomes | Microfinance, renewable energy |
| Faith-based investing | Exclusion/inclusion aligned with religious values | Alignment with spiritual beliefs | Avoiding alcohol, gambling, high-interest lending |
| Green-themed strategies | Thematic allocation | Environmental sustainability | Clean energy, sustainable agriculture |
Is Sustainable Investing Right for You?
Sustainable investing may be suitable for you if you want your investment choices to reflect your personal values. In special way if you:
- Care about the wider impact of your investments
- Wish to avoid industries you consider harmful
- Value transparency and accountability from the companies you invest in
- Focus on long-term value and responsible risk management
You also have to consider that suistainable funds may have slightly higher fees and that short-term performance can deviate (positively or negatively) from traditional benchmarks.
In the UK, advisers must take account of your sustainability preferences when constructing your portfolio.
Example: if you are opposed to animal testing, you can request funds that exclude pharmaceutical companies engaged in such practices.
How to invest
Now that you have a clearer understanding of the different approaches to sustainable investing, take the time to review your current portfolio and your long-term investment objectives.
Here are the next steps you may wish to consider:
- Explore and evaluate the sustainability options offered by your investment platform (for example, ESG-screened funds, impact-focused portfolios or green-themed investments). If it doesn’t currently offer funds that match your values, you might consider switching provider or discussing custom ESG screens with your adviser.
- Compare these options with your ethical values, financial goals and risk appetite to determine whether any adjustments are appropriate.
- If you are unsure where to begin or would prefer advice tailored to your personal circumstances, seek the support of an independent financial adviser. A regulated professional will be able to help you define your sustainability preferences, explain the potential implications for costs and performance, and develop a long-term investment strategy that reflects both your ethical priorities and your financial objectives.
Moneyfarm can help you find an approach that suits your goals, with access to a wide range of ETFs for building your own investment portfolio.
Frequently Asked Questions
Sustainable investments are investments that consider financial returns only after environmental, social and governance factors and, in some cases, ethical or faith-based values.
Some examples can be ESG funds, renewable energy investments, green bonds and funds that invest in companies working towards positive environmental or social outcomes.
Sustainable investments are financial products that aim to combine financial objectives with environmental, social, ethical or other sustainability considerations. For example, you can choose an ESG ETF, exchange-traded funds that invest in companies selected based on Environmental, Social and Governance criteria.
You can start by identifying the issues that matter to you, checking different sustainable funds or ETFs, and comparing their objectives, costs, risks and investment strategies.
Not necessarily, your choice should depend on your financial goals, risk tolerance, investment timeframe and sustainability preferences. Remember that everyone has different values and priorities: one person may want to avoid fossil fuels, while another may focus on climate change, animal welfare, social impact or faith-based principles.
Yes, sustainable investments can generate financial returns, but their performance can vary and, like all investments, they involve risk.
The post Sustainable Investments: From ESG to Faith-Based, What Options Are Available? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: < 1 minuteWelcome to a new episode of A Matter of Interest podcast, your fortnightly reality check on global markets, hosted by Moneyfarm. Every two weeks, Richard Flax (our Chief Investment Officer) and Jack Amy (our Quantitative Trading Analyst) cut through the noise to serve up fresh market trends, data-driven insights, and strategic takeaways, minus the textbook jargon. In this episode, we take […]
The post Behind the scenes: our latest investment decisions appeared first on MoneyFarm Insights.
]]>Welcome to a new episode of A Matter of Interest podcast, your fortnightly reality check on global markets, hosted by Moneyfarm. Every two weeks, Richard Flax (our Chief Investment Officer) and Jack Amy (our Quantitative Trading Analyst) cut through the noise to serve up fresh market trends, data-driven insights, and strategic takeaways, minus the textbook jargon.
In this episode, we take you inside our Investment Committee and behind the scenes of our latest multi-asset portfolio rebalance. Richard Flax and Jack Amy weigh the bull vs bear arguments around global tech exposure, navigate the complex interaction between energy costs and government bond yields, and explain how spillover effects from the hardware buildout are shaping the broader macroeconomic landscape. Enjoy listening.
Key takeaways
- Our portfolio rebalancing – from 0:50
- The AI supply chain – from 2:49
- The macro resilience – from 14:08
- Fixed income and productivity – from 25:00
You can also listen to the episode on Apple Podcast and YouTube.
The post Behind the scenes: our latest investment decisions appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesWhen you start investing in funds, one of the first choices you may make is whether to invest in an active or passive fund. So you have to decide which one fits your investment goals, risk tolerance and time horizon. Active funds are managed by professional fund managers who aim to outperform the market, while […]
The post Active vs Passive Funds: Which Strategy Works Best for You? appeared first on MoneyFarm Insights.
]]>When you start investing in funds, one of the first choices you may make is whether to invest in an active or passive fund. So you have to decide which one fits your investment goals, risk tolerance and time horizon.
Active funds are managed by professional fund managers who aim to outperform the market, while passive funds aim to track a specific market index, usually at a lower cost. Both approaches have different features that you should consider before investing.
In this article, you’ll learn how active and passive funds work, how they differ, and which factors you should consider when deciding which approach may be right for you.
| What is an active fund? | A fund managed to try to outperform the market |
| What is a passive fund? | A fund that aims to track a market index |
| What is the difference? | Active funds are managed by a professional fund manager, aim to beat the market, passive funds aim to follow it |
| How to choose? | Consider your goals, risk profile, time horizon and investment costs |
What are investment funds?
Before looking at the difference between active and passive funds, it is useful to understand what an investment fund is. An investment fund is a way of investing your money together with other investors. The fund manages this money and uses it to buy a range of assets, such as shares, bonds, ETFs and other securities.
Instead of choosing and buying individual investments yourself, you buy units or shares in the fund. This gives you access to a diversified portfolio, which can help spread your money across different investments and reduce the impact of negative performance from a single asset. Funds can also give you access to professional management, making them a convenient option if you do not want to manage every investment by yourself.
Investment funds can follow different strategies, but two of the main approaches are active and passive investing. Understanding how these strategies work is the first step to decide which approach may suit your investment goals.
Active vs Passive Funds: the differences
Active and passive funds use two different approaches to investing:
- Active fund: a professional fund manager selects investments with the aim of outperforming a particular market or benchmark. The manager may buy and sell investments based on their analysis of companies, economic conditions and market opportunities. This approach can offer more flexibility, but it usually comes with higher management fees.
- Passive funds: aim to track the performance of a specific market index, such as the FTSE 100 or the S&P 500, rather than trying to outperform it. Because there is generally less buying and selling and less active management involved, passive funds tend to have lower fees. They have also become increasingly popular in the UK as people have gained easier access to low-cost index funds and ETFs.
The right approach for you will depend on factors such as your investment goals, time horizon, risk profile and the costs you want to pay. Discover here how to invest in index funds in the UK in 2026.
| Characteristic | Active funds | Passive funds |
| Investment approach | A fund manager actively selects investments to try to outperform a benchmark | The fund aims to track a specific market index |
| Fund manager | Plays an active role in selecting and changing investments | Has a more limited role, mainly ensuring the fund tracks its chosen index |
| Goal | To outperform a particular market | To match the performance of a particular market or index, before fees |
| Fees | Generally higher due to active management and research costs | Generally lower due to the simpler investment approach |
| Flexibility | The manager can adjust the portfolio in response to market conditions and opportunities | The portfolio generally follows the composition of the chosen index |
| Anticipated returns | Potentially higher than the market, but also with the risk of underperformance | Performance in line with the market, without excesses or disappointments |
| Effectiveness in volatile markets | Can be more effective due to their capacity to respond to market changes | Less effective: they follow the index even when it is falling |
| Ideal context | Volatile markets or sectors with scarce or difficult to interpret information | Long-term investments in markets considered efficient |
Active funds: what they are and how they work
Active funds are managed by professional investment managers who decide which assets to buy, hold or sell in an effort to outperform a market benchmark (such as the FTSE All-Share Index).
Main characteristics are:
- Active portfolio management: managers rely on research, forecasts and market analysis to identify the most profitable investment opportunities.
- Objective to outperform the market: managers aim to deliver returns above the market average.
- High degree of flexibility: active managers can respond swiftly to market developments.
- Higher fees: reflecting the cost of ongoing active management.
Active funds may perform better during periods of high volatility or in sectors where information is limited. However, they also carry the risk of underperformance due to poor decision-making or higher fees that can erode returns.
Passive funds: what they are and how they work
Passive funds – including index funds and ETFs (Exchange-Traded Funds) – aim to track the performance of a specific index rather than beat it.
Main characteristics are:
- Automated management: there is no active manager making frequent investment decisions.
- Transparency: the fund’s holdings are clearly disclosed from the outset and remain consistent over time.
- Market-level returns: while you won’t exceed the market average, you are also less likely to underperform.
- Lower charges: the absence of active management results in lower ongoing fees compared to active funds.
Passive funds are valued for their simplicity and cost efficiency, especially by long-term investors who believe that markets are efficient over time.
Active or Passive Funds: Which Should You Choose?
There is no single answer when it comes to choosing between active and passive funds. The right approach for you will depend on your investment goals, how involved you want to be in your investments and how much you can pay in fees.
If you prefer to rely on the expertise of a professional fund manager and believe they can identify good opportunities, an active fund could be an option to consider. Active funds can also give you access to niche markets or specific sectors that may be less well represented in broad market indices. You should know that this approach generally comes with higher fees, which can reduce your returns over time, and there is no guarantee that the fund manager will outperform the relevant benchmark after costs.
If you prefer a simpler and lower-cost approach, a passive fund may be more suitable. Passive funds are designed to follow a particular market index, giving you broad exposure to the market without relying on a manager to select individual investments.
This can make them relatively transparent, particularly if you are investing for the medium to long term. Remember that a passive fund will generally fall when the market falls. It also gives you less flexibility to move away from the index during periods of market volatility.
Active vs Passive Funds: Costs and Fees
One of the main differences between active and passive funds is the cost of managing them. Active funds generally have higher fees because you are paying for professional management, research and the ongoing decisions made by the fund manager. Passive funds usually have lower charges because they follow an index rather than relying on a manager to select investments.
While the difference in fees may seem small, it can become more significant over the long term. This is why you should look at the total costs of a fund before investing and consider how they could affect your overall returns.
Active vs Passive Funds: Trends for 2026
In 2026, the investment fund market continues to move towards lower-cost and more accessible investment products, with passive funds and ETFs attracting strong demand. Passive funds are the principal choice, but at the same time, active investing is not disappearing.
Some of the main trends to watch in 2026 include:
- Continued growth of passive investing: investors are still attracted by the relatively low costs, diversification and simplicity offered by index-tracking funds.
- Growing interest in active ETFs: these combine the flexibility and accessibility of an ETF with an actively managed investment strategy, creating more choice for investors.
- More selective active investing: active strategies continue to have a role in areas where fund managers may have greater opportunities to add value, although their performance varies significantly between markets and investment sectors.
You should consider that the difference between active and passive investing is becoming less separate. Rather than choosing between two completely different approaches, people now have access to a wider range of products that combine elements of both strategies.
How to choose
When choosing between active and passive funds, you should look at how each strategy fits your objectives, investment time horizon, attitude to risk and level of involvement. Costs should also be an important consideration, as fees can have a significant impact on your returns over the long term.
When comparing the two approaches, you should consider:
- Your investment goals: if you are looking for a fund that aims to outperform a particular market, you may consider an active strategy. If your priority is to follow the performance of a broad market at a lower cost, a passive fund may be more appropriate.
- Your investment time horizon: both active and passive funds can be used for long-term investing, but your time horizon can influence how much importance you place on costs, market fluctuations and the fund’s investment strategy.
- Costs and fees: active funds generally have higher fees because they involve professional management and research. Passive funds typically have lower costs, which can be particularly relevant when investing over many years.
- How involved you want to be: active funds rely on a manager making decisions about which investments to buy and sell. Passive funds follow a defined index, making the investment approach more straightforward and predictable.
- Diversification: look at what the fund actually invests in, rather than focusing only on if it is active or passive. A well-diversified fund can give you exposure to a range of companies, sectors or markets.
- Combining both approaches: you do not necessarily have to choose between active and passive funds. Depending on your objectives and portfolio, you may decide to use a combination of both approaches.
If you are unsure which option is suitable for your circumstances, you can ask Moneyfarm, we can help you assess your objectives, risk profile and investment time horizon before choosing a strategy.
Frequently Asked Questions
Active funds aim to outperform their benchmark, but their performance depends on the fund manager and can vary significantly. Passive funds aim to match the performance of their chosen index.
Active funds are managed by a professional fund manager who selects investments, while passive funds aim to track a market index. Active funds generally have higher fees.
Yes, active funds generally have higher fees because they involve professional management and specific operations. Passive funds typically have lower costs because they aim to track an index rather than actively select investments. Some fund managers also use technologies such as AI and data analysis to support their research and investment decisions.
Not necessarily. Both types of funds carry investment risk: the level of risk depends mainly on the assets and markets the fund invests in.
Yes, you can combine active and passive funds within the same portfolio, depending on your investment goals, risk profile and time horizon.
There is no single option that is suitable for every investor. Active funds may appeal to you if you value professional management and are willing to pay higher fees for the potential to outperform the market. Passive funds may be more suitable if you prefer a simpler, lower-cost approach that aims to track a market index.
The post Active vs Passive Funds: Which Strategy Works Best for You? appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 7 minutesSaving money for your child can be a simple way to help them get a stronger financial start in life. If you want to build a nest egg for their education, help with future expenses or simply give them a financial safety net, starting early can make a difference. There are several ways to save […]
The post Best way to save money for kids – Best tips on saving for kids appeared first on MoneyFarm Insights.
]]>Saving money for your child can be a simple way to help them get a stronger financial start in life. If you want to build a nest egg for their education, help with future expenses or simply give them a financial safety net, starting early can make a difference.
There are several ways to save and invest for your children, from children’s savings accounts to longer-term investment options. The right choice will depend on your goals, how much you can afford to put aside and when you expect your child to need the money.
In this guide, you’ll explore some of the main ways to save for your children and discover practical tips to help you get started.
| Is there a best way to save for a child in the UK? | Several factors affect a parent’s choice, such as financial circumstances and risk tolerance. But, a tax-efficient option is a Junior ISA (Individual Savings Account). |
| How much can I save in a Junior ISA? | £9,000 for the 2026/2027tax year |
| When can the child access the funds in a Junior ISA? | At age 18 |
| Are there any alternatives to a Junior ISA for saving money for children? | Other options include child trust funds, savings accounts, premium bonds, children’s pensions, and investment accounts |
How do I save for my children’s future?
Starting off by saving a little or a lot doesn’t matter. The most important thing is to begin saving for your child’s or children’s future at the earliest opportunity. However, the cost of raising a child in the UK is taxing, so it may be difficult to set money aside for your child’s future.
First, you must ensure you have enough money to provide your family with a good lifestyle, cover the cost of living, have some money set aside for emergencies, and save for your own future, thinking ahead to your retirement. There are many demands, so you need to do some careful financial planning because the best way to save money for kids is to save regularly.
Before deciding how to invest for your children, there are a few important factors to consider. Thinking about these points can help you choose an approach that fits your family’s finances and your child’s future needs.
- Your financial situation: make sure you can cover your everyday expenses and have enough savings for emergencies before putting money aside for your child.
- Your investment goal: think about what you are saving for, such as education, a first home, a car or simply giving your child a financial head start.
- How long you can invest: the longer your money can stay invested, the more time it has to potentially grow. Consider this when your child is likely to need the money.
- How much you can afford to invest: you do not need to invest a large amount. Regular contributions, even small ones, can add up over time.
- Your attitude to risk: investments can go up and down in value. Consider how comfortable you are with fluctuations and how much you could afford to lose. Think about your risk profile.
- Where the money will be held: look at the different savings and investment options available for children and consider how each one works, including who controls the money and when your child can access it.
- Tax and allowances: check if the account or investment has any tax benefits or allowances and how these may affect your savings.
Best ways to save money for children
The best way to save money for kids is with an account that offers a good interest rate. With the right sort of savings account, the interest will be compounded every year, and this will help the savings to grow exponentially. The sooner you start, the better. It allows a longer time for compound interest to get to work, and you’ll be amazed at the difference it can make.
There is no one best way to save money for a child. Our incomes, lifestyles, commitments, and life goals are all different. Some of us are totally risk averse when it comes to finance, and some have a wider tolerance to taking risks. All these things will have a bearing on the best way to save money for children’s future.
Let’s take a look at the options open to you.
|
Option |
How it works |
|
Child savings account with a bank |
Cash savings account. The bank pays interest on the money saved |
|
Premium bonds for children |
Money is held by NS&I. No interest; instead, there are monthly prize draws |
|
Junior Cash ISA |
Tax-free cash savings account for children. Pays interest |
|
Junior Stocks and Shares ISA |
Money is invested in shares, funds or other investments. Value can go up or down |
|
General Investment Account (GIA) |
Investment account with no special child tax wrapper. Investments can grow or fall in value |
1. Children’s savings account options with banks and building societies
One option is to open a child savings account with a bank or building society. They are available in different formats, including easy-access accounts. These are useful for actively involving the child in saving, as both you and your child can contribute. However, easy access flexibility means you get a lower rate of interest.
Children’s savings accounts can offer competitive interest rates, although the rates available vary depending on the type of account and provider. In September 2026, some of the best children’s savings accounts offer up to 5% AER, while some fixed-rate options offer rates of around 4% AER.
2. Buying Premium Bonds for Children
Buying premium bonds for children is quite popular. As a parent, grandparent or legal guardian, you can buy them on behalf of your child, and they can be cashed in by the child when they reach age 16.
The downside is that they don’t earn interest, so their real money value depreciates through inflation.
The upside is that the bonds are entered into a monthly prize draw, although the odds for winning per £1 bond are 21,000 to 1. On their own, they are probably not the best way to save money for kids, but as part of a wider savings strategy – why not?
NS&I’s Children’s Bonds are no longer available to new savers. They were closed to new sales in 2017, and the last five-year Children’s Bonds matured in April 2023.
3. Junior Cash ISA
A Junior ISA (JISA) is another option. There are two types – the junior cash ISA and the junior stocks and shares ISA. A Junior Cash ISA is a tax-free savings account where the money earns interest. The interest rate is an important factor when choosing an account, as rates can vary between providers.
You can open a Junior Cash ISA for your child if you are their parent or legal guardian. Once the account is open, other family members and friends can also contribute, up to the annual Junior ISA allowance.
The money in a Junior Cash ISA grows free from UK income tax and capital gains tax. But the money is locked away until the child turns 18. When the child turns 18, the Junior Cash ISA automatically becomes an adult Cash ISA, and the child can access the money. In the 2026/27 tax year, the total amount that can be paid into a Junior ISA is £9,000 per child.
4. Junior Stocks and Shares ISA
A Junior Stocks and Shares ISA allows you to invest money for a child in a tax-efficient account. You can invest in assets such as funds and shares, and any investment growth or income is free from UK Income Tax and Capital Gains Tax.
The total amount that can be paid into all Junior ISAs for a child is £9,000 per tax year. The money belongs to the child, and they can take control of the account when they turn 16, but they cannot withdraw the money until they turn 18.
The main difference from a Junior Cash ISA is how the money is held. A Junior Cash ISA keeps your child’s money in cash and pays interest, while a Junior Stocks & Shares ISA invests the money in assets such as funds and shares. A Cash ISA has lower risk, while a Stocks & Shares ISA can offer higher growth over the long term, but the value can also go down.
5. General Investment Account (GIA)
A General Investment Account (GIA) is a flexible way to invest money for your child without the restrictions of an ISA. You can invest in different assets and there is no annual contribution limit.
But, unlike an ISA, investments held in a GIA are not tax-free, so you may have to pay tax on investment income or capital gains. The money also remains under your control, which can be useful if you want to decide when and how to give it to your child.
Should I start investing for my child?
Yes, investing for children is a wise thing to do, and the sooner you start saving, the better. Opening a JISA for a baby as soon as possible after birth is the best. The longer the interest has to work, the more growth you’ll get.
Of course, you’ll be faced with the question, what is the best ISA for a baby – cash or stocks and shares – which is the best way to save money for your children’s future?
That is a decision only you can make. Investing money nearly always carries an element of risk. A cash ISA is safer, and although a stocks and shares ISA is potentially more risky, it usually offers a much superior rate of interest.
A child’s investment portfolio can combine different types of savings and investments, depending on the goal and how long the money can remain invested. The following is a simple example of how a portfolio could be structured:
|
Investment |
Example allocation |
Goal |
|
Junior Cash ISA |
30% |
Lower-risk savings for education or other expenses at age 18 |
|
Junior Stocks & Shares ISA |
50% |
Long-term investment growth for university or a first home |
|
General Investment Account (GIA) |
20% |
Flexible investments that can be used before age 18 |
Can I set up a pension for my child?
Yes, you can set up a children’s pension for your child using a SIPP of Stakeholder pension formats. Whether it’s the best way to save money for kids is arguable.
On the one hand, you will be helping to ensure your child is comfortable in their retirement years, but of course, that seems so far away. On the other hand, the money will be untouchable, at least until the child reaches 55 in adulthood, so it can’t be used for university fees, buying a first car or property etc. The best way to save money for your children’s future would be to do both, of course – a JISA and a pension.
Frequently Asked Questions
No, you can only open one junior cash ISA and Junior stocks and shares ISA for each child, although you can switch providers if you’d like.
The fees are dependent on the ISA provider. Generally, management fees and transfer charges are associated with a Junior ISA.
The main benefits of a Junior ISA are that savings and investment returns are tax-free. A Junior Cash ISA can earn tax-free interest, while a Junior Stocks & Shares ISA can benefit from investment growth over the long term.
Yes, a child can have one Junior Cash ISA and one Junior Stocks & Shares ISA. The combined contributions across both accounts cannot exceed £9,000 in the 2026/27 tax year.
Anyone can contribute to a Junior ISA, including parents, grandparents and other family members.
Generally, no. The money belongs to the child and cannot normally be withdrawn until they turn 18. At 18, the Junior ISA automatically becomes an adult ISA.
The post Best way to save money for kids – Best tips on saving for kids appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 4 minutesThis week we wanted to highlight some changes we recently made in some of our multi-asset portfolios. We slightly increased our equity exposure and generally reduced our short-dated bond positions. At first glance, this might seem like a contrarian trade. There’s a lot of uncertainty in markets at present. Oil prices are high and that’s […]
The post A stronger economy and the role of AI appeared first on MoneyFarm Insights.
]]>This week we wanted to highlight some changes we recently made in some of our multi-asset portfolios. We slightly increased our equity exposure and generally reduced our short-dated bond positions.
At first glance, this might seem like a contrarian trade. There’s a lot of uncertainty in markets at present. Oil prices are high and that’s impacted gasoline and diesel prices around the world. Investors expect central banks to hike rates in the coming quarters. Geopolitical risk seems elevated, with the conflict in the Middle East still unresolved. Government bond yields have continued to rise, putting pressure on mortgage rates and government finances.
We are taking a more optimistic view and we think Artificial Intelligence (AI) has an important role here. We’ve seen strong demand as a result of AI spending across a range of industries and there’s an ongoing debate about whether it’s warranted and sustainable.
Our current view is that we are still relatively early in a phase of expansion and adoption, and that the strong demand we’ve seen for things like semiconductors, gas turbines and construction equipment can continue. Demand is outstripping supply in a number of AI value chain industries, with company order books in sectors like power supply fully committed for the next couple of years. As an example, the cost of renting older computer chips has risen sharply in recent months, reflecting limited supply. We’ve seen rapid adoption of AI tools across households and businesses. As the cost of token continues to fall, we observe an acceleration in demand, particularly with the growing adoption of AI agents. For all the strong growth we’ve seen, it could have been faster without these constraints.
In this context, we see that expectations are not overly-exuberant and are moving higher. The chart below shows how many analysts are moving their earnings forecasts higher versus lower. Over the past couple of months, we’ve seen more upgrades than downgrades across the US, Europe and even the UK.
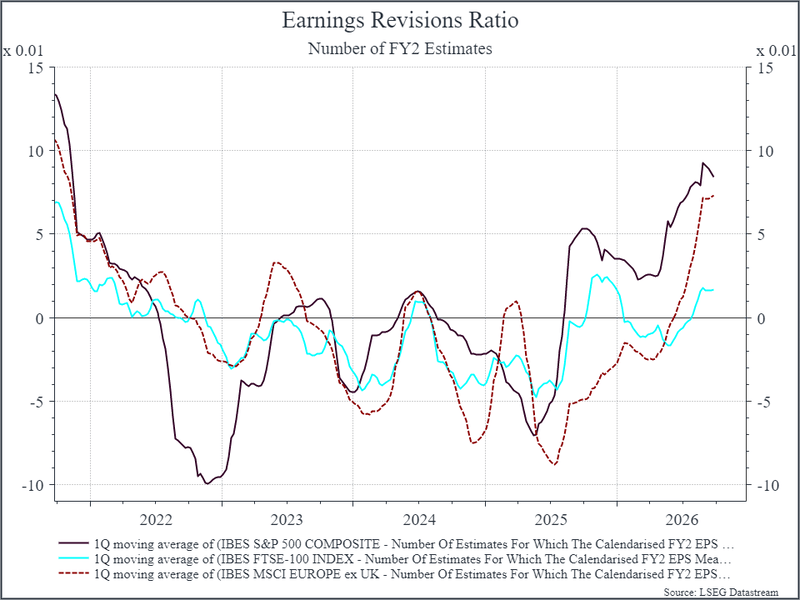
Looking at equity valuations, we think that the key point of focus at the moment should be less on the headline valuation and more on the earnings forecasts. For instance, the chart below shows the historical Forward Price/Earnings ratio for Emerging Market equities. It shows the lowest headline valuations in a decade. We think it highlights a couple of points. First, that earnings growth has been strong in Emerging Markets, particularly in the tech space. Second, that investors are not generally extrapolating that strong growth far into the future. They see these earnings as cyclical and expect some normalisation over time.
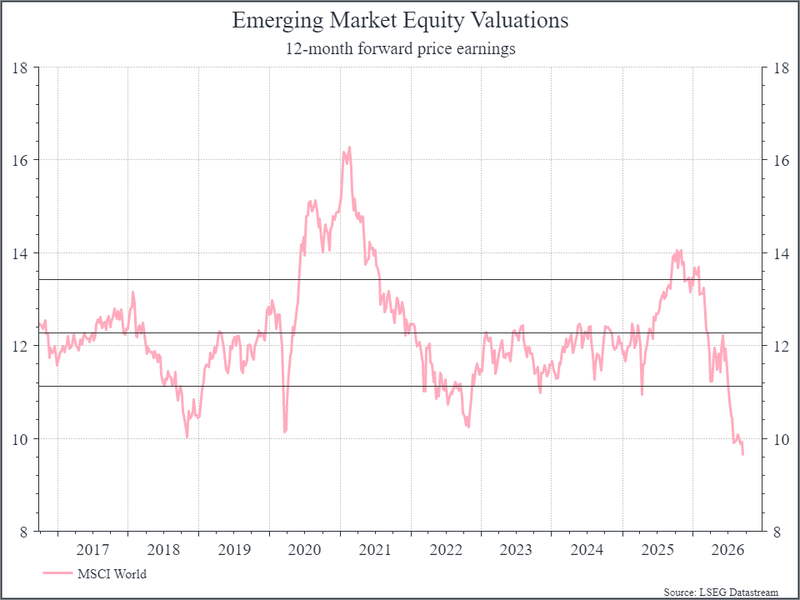
We think that’s a reassuring perspective. It suggests that investors haven’t forgotten that these are cyclical businesses and are mindful of past periods of over-enthusiasm. But if the cycle does last longer than many believe, we think earnings over the next couple of years could prove stronger than what’s embedded in these estimates.
In terms of the macro outlook, the global economy has generally held up better than expected, despite the geopolitical headwinds. We think AI spending has had a lot to do with that. The chart below shows an index of economic surprises. It measures how actual economic data has compared with the forecasts from a range of economists. At present, macro data across the US, Europe and Emerging Markets is generally coming in better than expected.
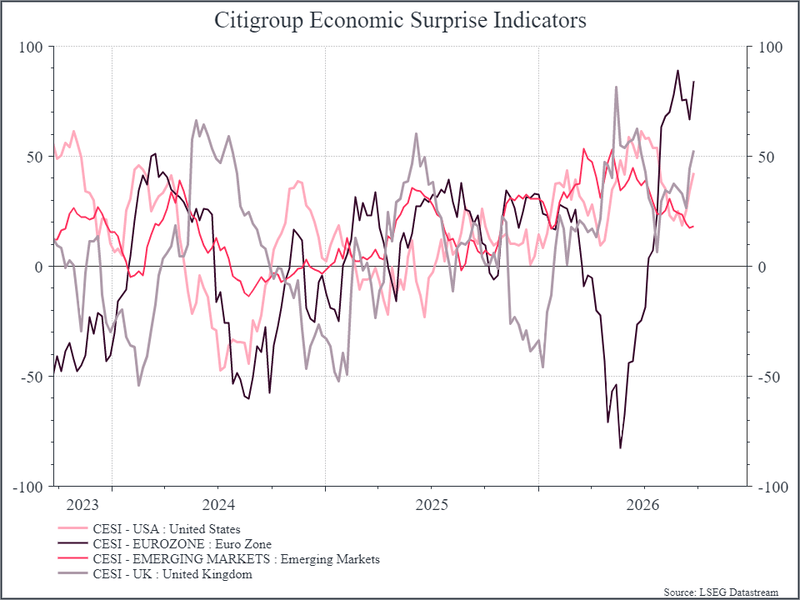
Drilling down a bit deeper, we can see that Purchasing Manager surveys (so-called PMIs) have also held up well. The chart below shows PMIs for the Eurozone – with a reading above 50 generally signalling a growing economy. The recent data looks pretty healthy even in Europe, generally regarded as having weaker growth. PMIs in the US showed a similar picture.
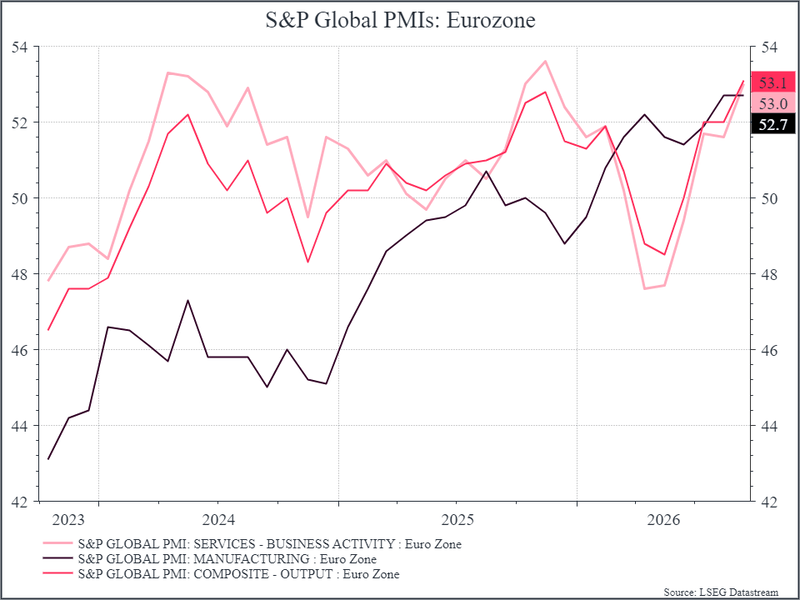
A couple of final points. First, we manage diversified portfolios and continue to look for a broad range of exposures across different asset classes.
Second, we remain mindful of the risks and the alternative scenarios. The outlook for the global economy is still uncertain, and higher energy prices or interest rates could weigh on demand. AI may also prove to be less transformative than the optimists expect, with fewer benefits and higher costs. We are therefore monitoring a clear set of variables – from energy prices and interest rates to the trajectory of earnings and AI investment – that could change our view.
For now, however, we remain constructive on markets and the outlook for earnings growth in the short to medium term, and that’s what has prompted us to increase our equity exposure.
The post A stronger economy and the role of AI appeared first on MoneyFarm Insights.
]]>⏳ Reading Time: 5 minutesBy mid-August, Bitcoin looked like an asset nobody wanted. It was trading at around $63,500, about 49% below its October 2025 peak, after ten months of decline. Thirty-day realised volatility had fallen to an annualised 27%, far below its long-term average, while direct Bitcoin trading volumes were among the lowest on record. Trading was thin […]
The post Bitcoin’s rebound: what drove the rally? appeared first on MoneyFarm Insights.
]]>By mid-August, Bitcoin looked like an asset nobody wanted. It was trading at around $63,500, about 49% below its October 2025 peak, after ten months of decline. Thirty-day realised volatility had fallen to an annualised 27%, far below its long-term average, while direct Bitcoin trading volumes were among the lowest on record. Trading was thin and volatility unusually low. Investors were paying up to protect against further falls rather than betting on a rebound, and some long-standing holders were selling.
That positioning explains the violence of what came next. In four sessions from 17 August, Bitcoin went from about $62,800 to a high of $79,241. Roughly $3 billion of short positions were liquidated across crypto, around $1.7 billion of them in bitcoin. The key detail is that open interest – the total value of outstanding positions in Bitcoin derivatives – fell by almost 9% during the move. The rise was driven by investors who had bet against Bitcoin being forced to close their positions, rather than by new bets made with borrowed money. At the same time, genuine demand emerged from investors buying Bitcoin directly. US spot bitcoin ETFs took in $517 million on 19 August and $606 million the next day, then posted nine straight days of inflows to 27 August.
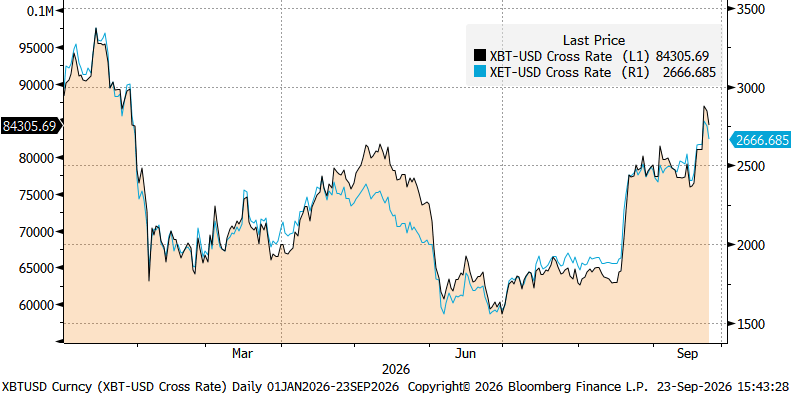
Within crypto, the rebound followed the usual pattern: it began with Bitcoin and then spread to more volatile cryptocurrencies, which recorded even larger gains. Ether rose about a third in August and outpaced bitcoin. Solana gained around 61.8% by late September, with August being its first positive month after ten consecutive declines. XRP was up more than 45% over the month to late September.
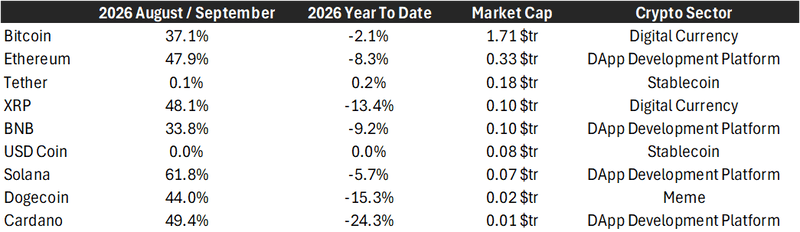
The macro moment
The macro conditions also helped. The macro backdrop is an inflation problem the Federal Reserve (Fed) now owns. Summer inflationary prints provided little clarity, keeping risks decidedly biased to the upside. Fed staff attributed the pressure to tariffs, higher energy costs from the Middle East conflict and the AI capex boom.
At its July monetary policy meeting (FOMC), the Fed kept interest rates unchanged at 3.50–3.75%, but three members (Hammack, Kashkari and Logan) dissented in favour of a hike. Meanwhile 10- and 30-year Treasury yields reached roughly twenty-year highs, with the 30-year above 5.25%.
Speaking at Jackson Hole on 28 August, Chair Warsh called interest rates the Fed’s “predominant tool” and said it must be confident inflation is moving to target “clearly and at sufficient speed. Otherwise, we have work to do.”
On 16 September the Fed delivered its first hike in more than three years, 25bp to 3.75–4.00%, unanimously, with projections pointing to one more. Bitcoin barely moved, edging from about $75,400 to $76,300, because the hike had been largely priced for two weeks.
Fed communications have turned distinctly more hawkish than at any point since 2023, edging steadily upward even as employment figures and price pressures only partially warrant the shift. The chart below illustrates the tone of public FOMC statements alongside macroeconomic surprises in labor and inflation. The relationship typically holds, with central bankers leaning hawkish during periods of tight employment and elevated inflation; but the latest surge in hawkish rhetoric stands out sharply.
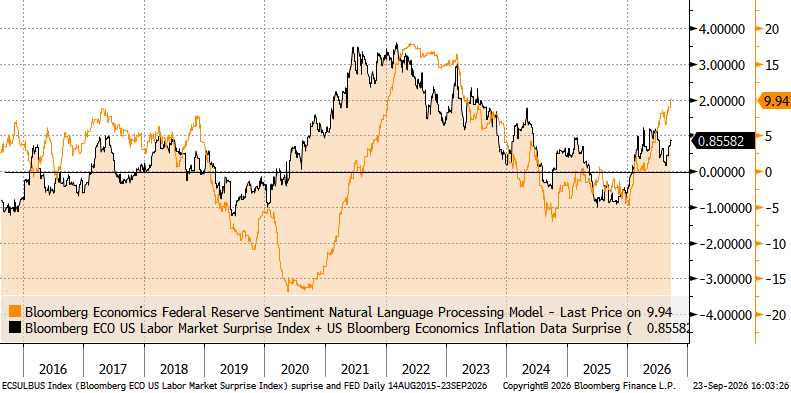
The Fed is only half of the story. The most interesting variable is the interaction between the Fed and the Treasury, not the Fed alone. On 19 August, Treasury said it would at least double its buybacks of 10–30-year bonds, from $2 billion to $4 billion per operation, between 9 September and 4 November. Secretary Bessent said yields “do not reflect underlying fundamentals” and pointed to a broader toolkit. Crypto reacted at once: the announcement coincided with the start of the ETF inflow run. The result is an unusual policy mix. The Fed is tightening at the short end, and Warsh has signalled that balance-sheet expansion is unlikely except as a one-off response to market failure. The Treasury, meanwhile, is trying to cap the long end with its own tools.
Asset correlations further underline this backdrop. Bitcoin’s co-movement with gold has surged to year-to-date highs, whereas its link to the US dollar remains skewed to the downside. Meanwhile, the relationship with expected Federal Reserve policy shifts has inverted; fewer anticipated rate reductions now serve as a constructive signal for bitcoin. Together, these dynamics reinforce a positive response function to growing macroeconomic anxieties surrounding the US fiscal balance.
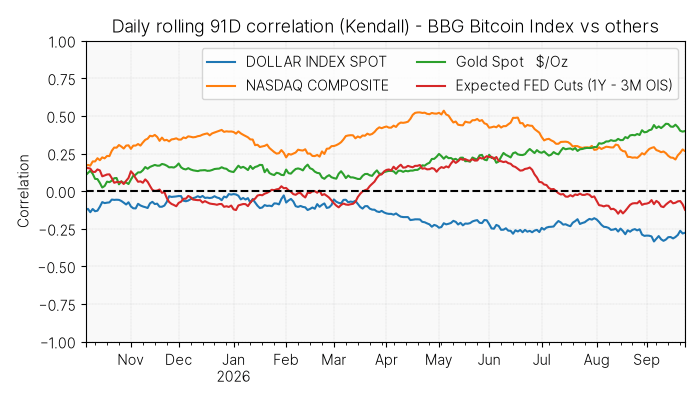
The customary caveat applies: macroeconomic drivers capture only a fraction of bitcoin’s trajectory, given that overarching co-movement measures stay subdued. As a result, factors specific to Bitcoin continue to drive much of its market performance.
On the regulatory side, the legislative route has closed for this year. When the Senate returned from recess, the CLARITY market-structure bill came to a procedural vote on 15 September and failed cloture 50-49, well short of the 60 votes needed. Negotiations ran right up to the vote. Republicans had released a revised 630-page text that took in some Democratic provisions, but many Democrats still judged the ethics language on officials’ personal crypto interests, including the President’s, to be too weak. The stablecoin-yield dispute between banks and crypto platforms was never fully settled either.
The failure matters more for the medium term than for this month’s prices. Without a statute, the US framework rests on agency action. That includes the SEC–CFTC joint interpretation from March, which says most crypto assets are not securities, the SEC’s proposed Regulation Crypto Assets offering regime, and continued ETF approvals. Both agencies have said they will keep going without Congress. Agency rules can move faster than legislation, but they are less durable, because a future administration can rewrite them far more easily than it can repeal a law. With control of Congress likely to be split after November, the next realistic window is the new Congress, and consequences for digital asset prices are uncertain.
The flows
As highlighted earlier, capital flows shifted sharply into positive territory throughout August, establishing the month as the strongest for US allocations since January. European investors similarly displayed renewed appetite, although aggregate volumes within the region continue to represent a minor fraction of overall activity.
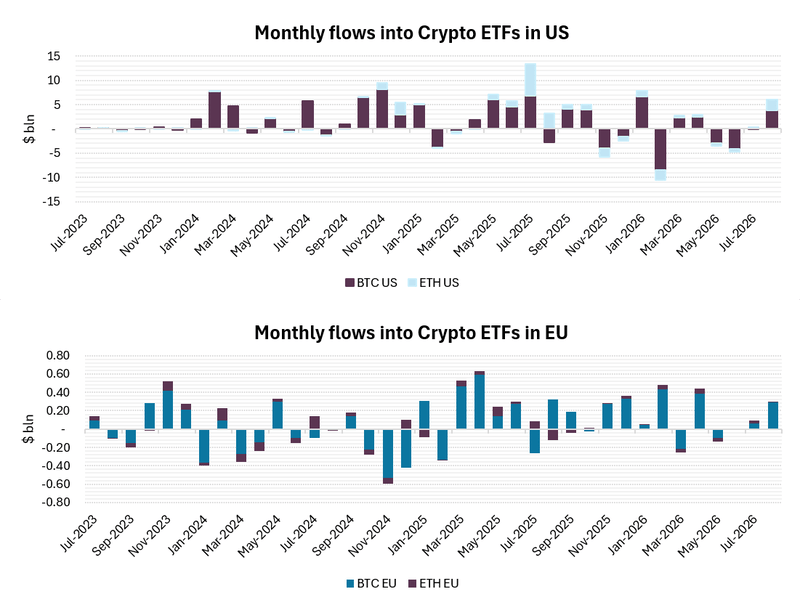
Taken together, the period illustrates a sharp shift where suppressed positioning intersected with macroeconomic catalysts, namely Treasury intervention and dollar softness, helped by genuine spot inflows through ETFs rather than speculative leverage.
While it is too early to call this a lasting shift, crypto continues to be driven largely by its own market dynamics. Bitcoin continues to function as a largely uncorrelated asset at a time when macro risk concentrates heavily in the equity market’s ongoing reliance on the Artificial Intelligence trade, providing a compelling vector for portfolio construction.
Investing in Crypto involves a high level of risk. You should not invest unless you are prepared to lose all of the money you invest. The value of your Moneyfarm portfolio can go down as well as up, and you may get back less than you invest. You may not be protected if something goes wrong. Past performance is not a reliable indicator of future results. The views expressed here do not constitute a recommendation, advice or forecast. If you are unsure whether investing is right for you, please seek independent financial advice.
The post Bitcoin’s rebound: what drove the rally? appeared first on MoneyFarm Insights.
]]>