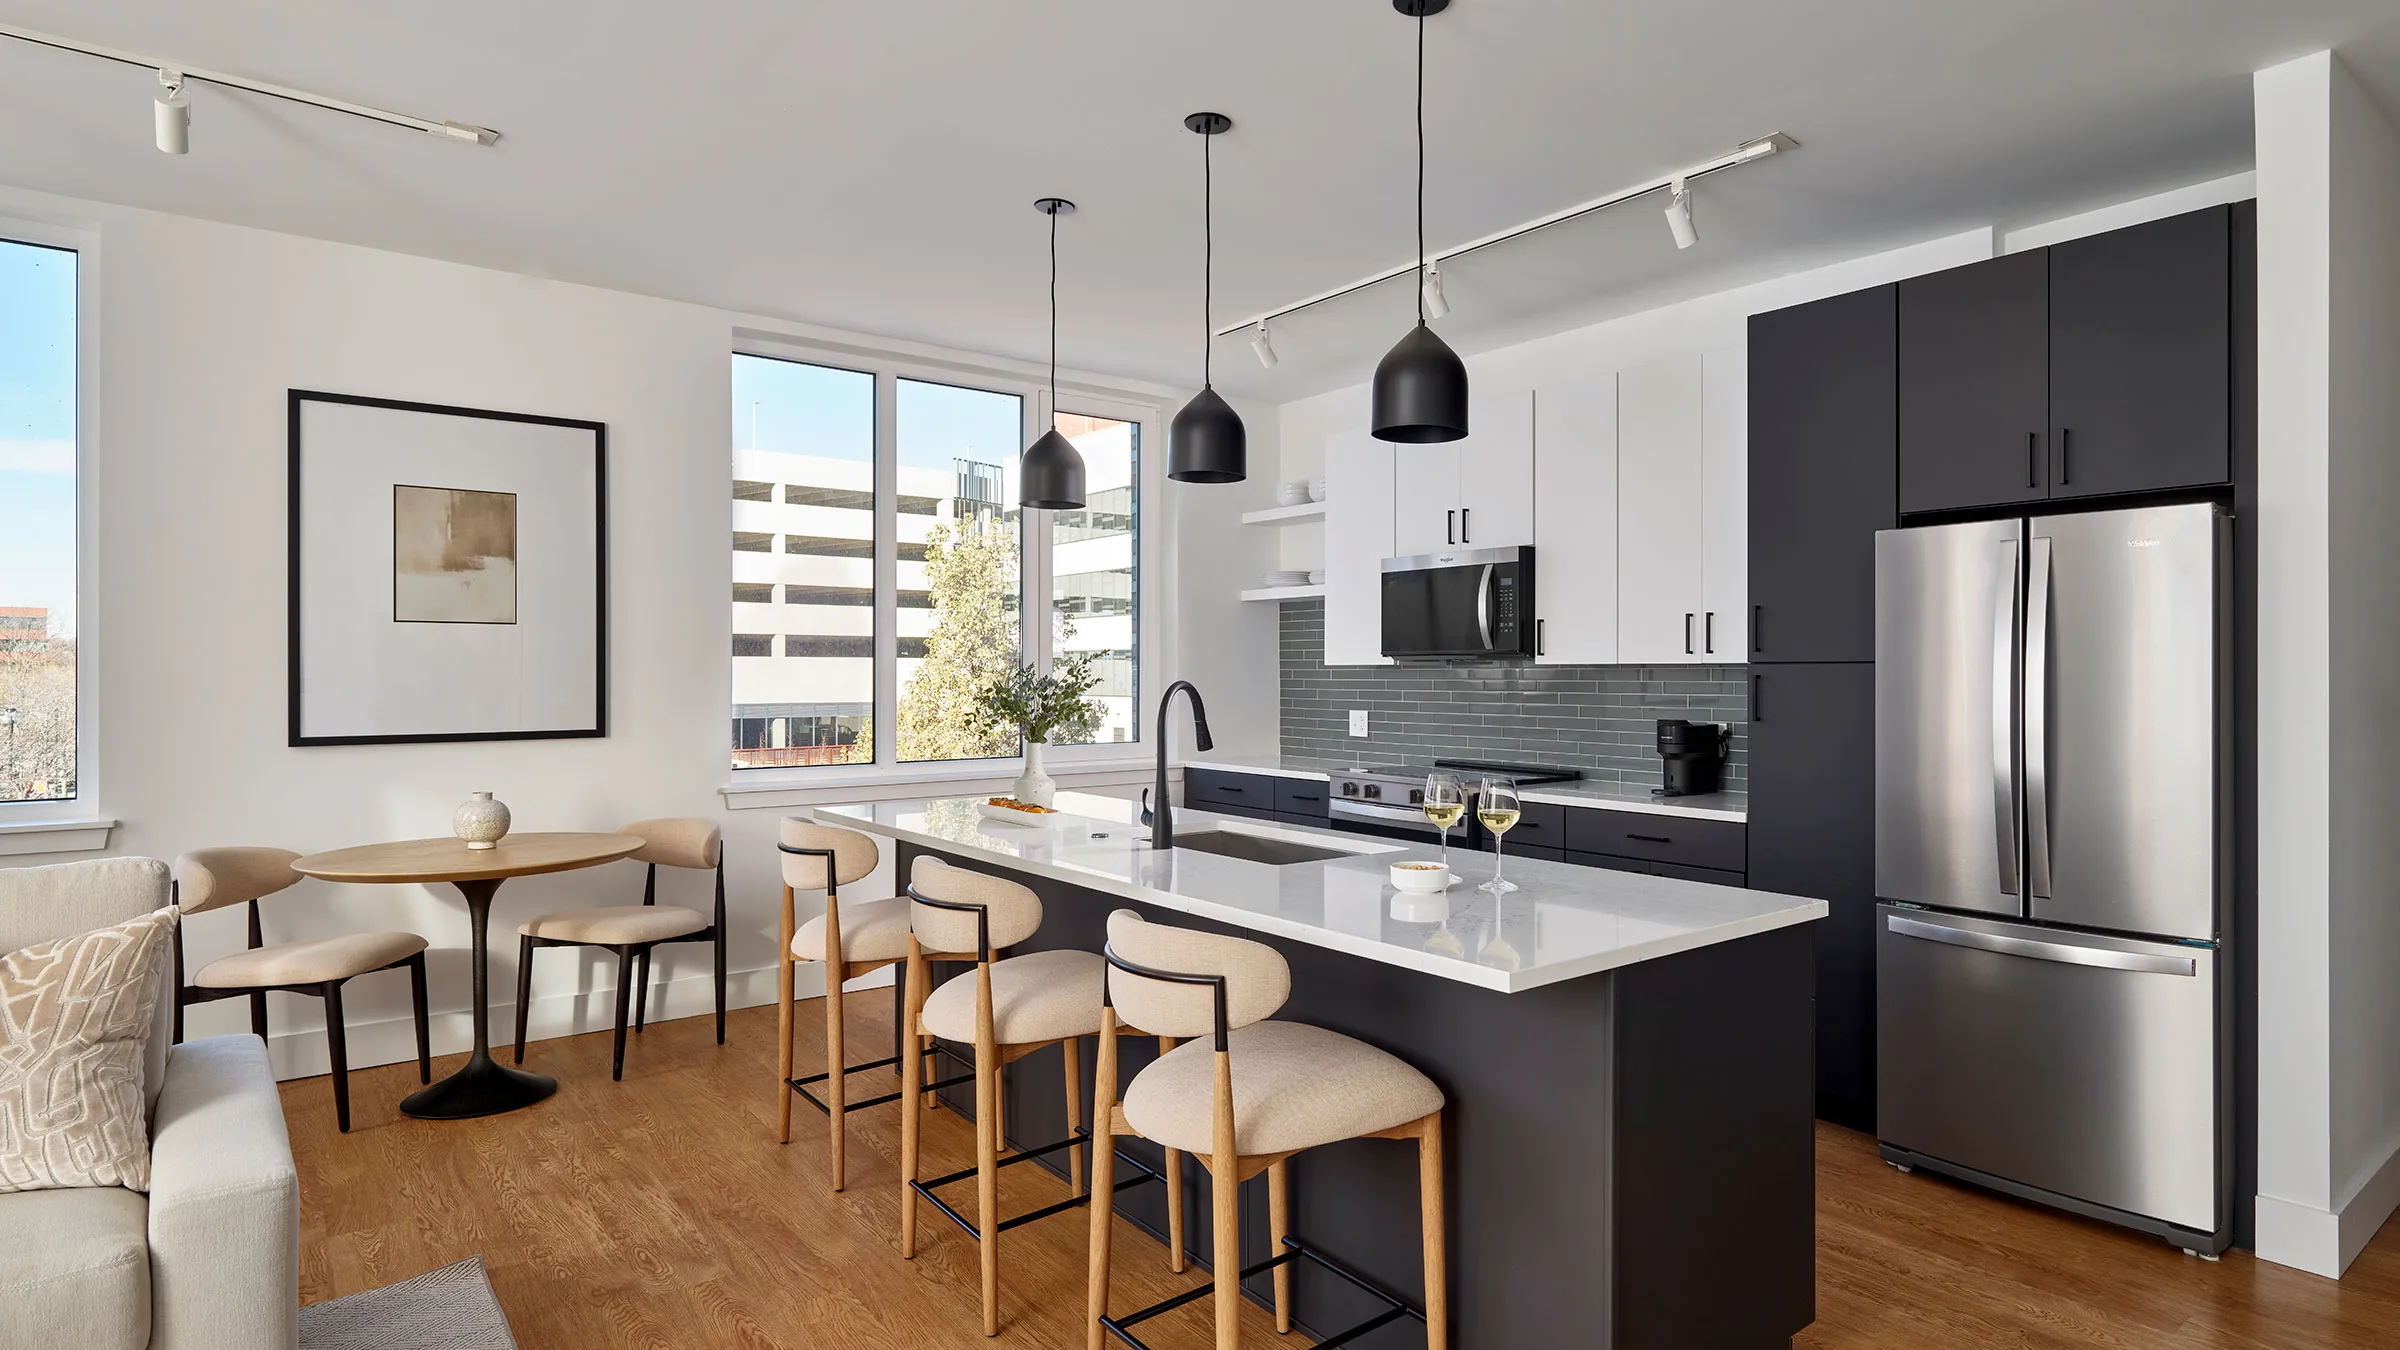
Move-in ready furnished apartments eliminate the financial stress, physical strain, and time consumption of moving into a new living space. Selecting a fully equipped rental allows tenants to unlock a turnkey lifestyle where essential furniture, kitchen appliances, and home decor are already thoughtfully curated and installed. Instead of spending thousands of dollars upfront on couches, mattresses, and dining sets, renters can simply pack their personal clothing and walk directly into a fully functional home on day one.
Instant Convenience and Zero Setup Friction
The primary advantage of choosing a move-in ready home is the immediate elimination of relocation logistics. Traditional moves require coordinating movers, renting large trucks, assembling flat-pack furniture, and spending weekends shopping for household items. A turn-key apartment bypasses these exhausting steps entirely, giving you back valuable hours and energy from the moment you receive your keys.
Living spaces in these properties come pre-arranged by interior design professionals who maximize layout efficiency and aesthetic appeal. From ergonomic office desks to cozy living room seating and plush bedding, every room is prepared for immediate daily use. You can focus on settling into your new job, exploring your neighborhood, or relaxing without surrounded cardboard boxes.
Substantial Upfront Financial Savings
Outfitting a vacant apartment from scratch demands significant capital expenditure that quickly adds up to thousands of dollars. Purchasing quality bedroom sets, living room seating, dining tables, and kitchenware creates a heavy initial financial burden. Furnished rentals convert these high upfront costs into a predictable monthly rent payment that easily fits into a standard monthly budget.
Eliminating professional moving services, truck rentals, and delivery fees generates immediate savings during lease sign-up. Tenants avoid taking on high-interest credit card debt or draining emergency savings accounts just to make a new apartment feel livable. For short-term residents or traveling professionals, avoiding furniture purchases protects capital for other investments.
Unrivaled Lease Flexibility and Geographic Mobility
Houston Latitude Med Center apartments offer flexible lease terms tailored to modern, mobile lifestyles. Traditional leases lock tenants into rigid twelve-month agreements that are costly to break if career opportunities or lifestyle changes arise. Fully equipped units frequently offer flexible month-to-month, quarterly or customized lease lengths that adapt to your schedule.
This inherent flexibility makes turnkey living ideal for corporate relocations, temporary assignments, digital nomads, and life transitions. Moving across the city or across the country becomes as simple as packing a couple of suitcases and booking a flight. You retain complete freedom to explore new neighborhoods or relocate for work without the hassle of selling or storing bulky household items.
Conclusion
Choosing a move-in ready furnished apartment offers a modern, efficient, and cost-effective approach to residential renting. By combining immediate convenience, flexible lease terms, and substantial upfront savings, turnkey living eliminates the traditional headaches associated with moving. Whether you are relocating for a career move, seeking flexible short-term housing, or simply looking to streamline your daily life, fully outfitted units deliver an elevated living experience from day one. Investing in a turnkey apartment allows you to skip the logistical chaos and step directly into a comfortable, stylish home designed around your mobile lifestyle.
]]>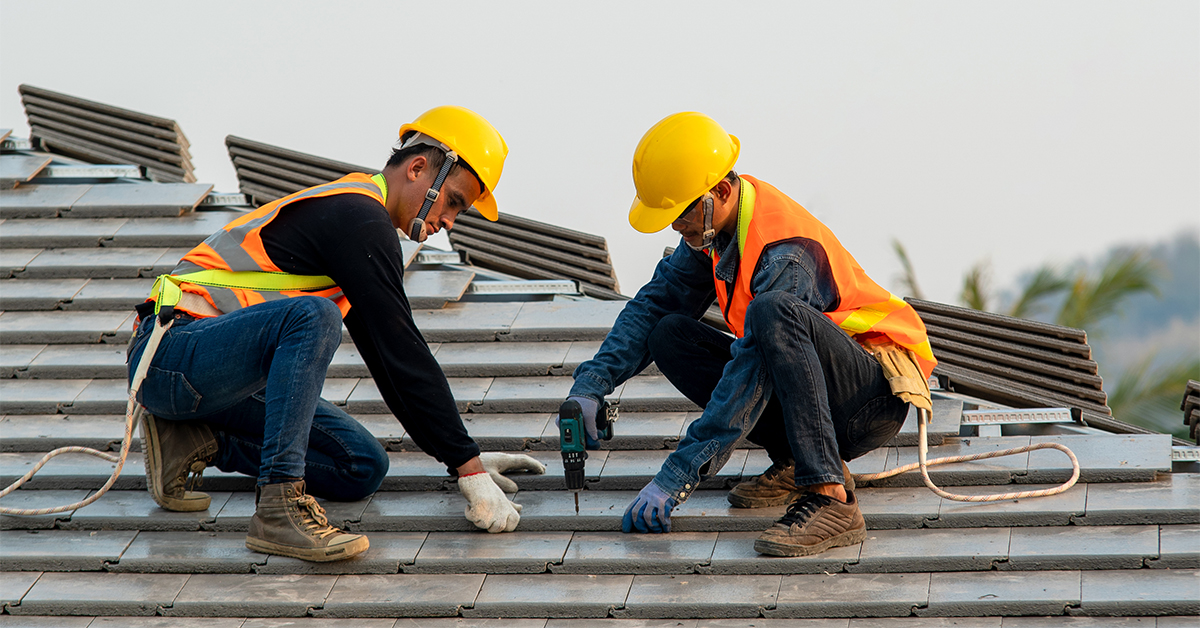
Missed phone calls mean missed revenue for roofing contractors. Homeowners dealing with active roof leaks, storm damage, or urgent replacement needs will not leave a voicemail and wait. They hang up and call the next contractor on the search results page. Selecting a dedicated specialized answering service for roofers ensures every inbound call converts into a qualified sales lead, keeping your crews working and your pipeline full around the clock.
24/7 Availability Captures Emergency Roof Repair Leads
Unexpected storms and extreme weather frequently result in serious leaks outside of regular work hours. Homeowners facing sudden water intrusion need immediate reassurance and scheduled inspection appointments. A general voicemail system fails to provide the human touch necessary to calm an anxious caller, driving them straight into the arms of your local competitors.
A professional answering service provides continuous round-the-clock coverage, ensuring trained receptionists answer every call live. These representatives intake critical details regarding the nature of the damage, emergency severity, and property address. By dispatching emergency repair requests immediately to your on-call technicians while scheduling routine inspection requests for normal working hours, an answering service keeps your operations organized while locking in high-value emergency contracts.
Industry-Specific Knowledge and Script Customization
A generic call center agent who handles retail orders or medical appointments during the same shift will struggle to represent your roofing brand professionally. Roofing requires specific terminology, accurate lead qualification, and precise intake details. When evaluating potential answering partners, prioritize providers that specialize in trade contractors and offer fully custom call scripts tailored directly to your business.
Custom call scripts allow virtual receptionists to ask targeted questions about roof age, roofing material, insurance claim status, and visible interior damage. Qualified receptionists can distinguish between a minor tile repair and a full commercial replacement, prioritizing high-ticket opportunities for your sales team. This tailored approach projects professionalism, builds trust with potential clients, and prevents your office staff from wasting time following up on unqualified leads.
Direct Integration with Roofing CRM and Scheduling Software
Seamless data transfer between your virtual receptionist service and your field service management software eliminates manual entry errors and speeds up response times. Modern roofing companies rely on platforms to run their daily scheduling, dispatching, and customer tracking. Your chosen answering service must integrate directly into these systems without requiring clunky workaround processes.
When a virtual assistant fields a call, they should enter client details, appointment times, and call logs directly into your existing CRM interface. Instant appointment booking during the initial inbound phone call prevents lead leakage and secures the customer before competitors even review their missed calls. Real-time notifications sent via text or email keep your project managers updated instantaneously on new leads and calendar changes.
Essential Factors to Consider Before Signing a Contract
Before choosing a virtual receptionist partner, analyze their pricing models, call handling capacity, and caller escalation protocols. Pricing models vary widely across the industry, ranging from flat monthly plans to per-minute or per-call billing structures. For roofing contractors, per-minute billing often proves most cost-effective during dry seasons, while flat-rate or tiered plans protect budgets during high-volume storm seasons.
Additionally, evaluate bilingual capabilities to ensure your company captures market share across diverse demographics within your service territory. Fluent English and Spanish phone representatives ensure clear communication with all homeowners and property managers. Finally, verify that the provider maintains robust call recording and quality assurance standards so you can review call quality, script adherence, and client interaction standards periodically.
Conclusion
Choosing the right answering service is a strategic decision that directly impacts your roofing company’s bottom line and market reputation. By providing round-the-clock live availability, leveraging customized roofing scripts, and integrating directly into your CRM, a specialized answering service transforms unexpected caller inquiries into signed contracts. Eliminating missed calls keeps your sales pipeline moving predictably while freeing your field crews to focus on quality installations and jobsite safety. Investing in a professional answering partner gives your roofing business a distinct competitive edge, ensuring you capture every lead, win more emergency repair jobs, and build lasting customer loyalty in your local market.
]]>Introduction & Background
As industries across the globe continue to evolve at an unprecedented pace, understanding the emerging trends that will shape the future has become essential for businesses, innovators, and professionals alike. The convergence of technology, sustainability, and shifting consumer behaviors is creating a dynamic landscape where adaptability and foresight are key. This transformation is not merely about keeping up with change. It is about recognizing the forces that will define the next decade and positioning oneself to seize the opportunities they present. Whether it is the rise of artificial intelligence, the acceleration of green energy adoption, or the reshaping of global supply chains, these trends are redefining what it means to operate in modern markets.
The significance of these developments cannot be overstated. They influence investment decisions, workforce development, policy formulation, and even societal structures. Organizations that fail to recognize and respond to these shifts risk falling behind, while those that embrace them stand to gain a competitive edge. This article explores the emerging industry trends that are shaping the future, providing clarity on their implications and offering guidance on how to navigate this complex terrain.
Concept & Overview
Emerging industry trends refer to the patterns of change that are gaining momentum across various sectors. These trends often stem from technological advancements, regulatory shifts, or evolving consumer preferences. At their core, they represent the direction in which industries are headed, driven by innovation and necessity. For instance, the digital transformation sweeping through traditional industries is not just a passing phase but a fundamental shift in how businesses operate and deliver value.
What sets these trends apart is their potential to disrupt existing norms and create new paradigms. Unlike incremental improvements, emerging trends often introduce entirely new ways of thinking and operating. They challenge established players to innovate or risk obsolescence. Understanding these trends requires a blend of curiosity, analytical thinking, and a willingness to embrace change. From the integration of blockchain in supply chains to the growing emphasis on circular economies, these trends are reshaping industries in profound ways.
Key Features & Highlights
- Acceleration of Digital Transformation: Businesses are rapidly adopting digital tools such as cloud computing, automation, and data analytics to enhance efficiency and customer experience. The COVID-19 pandemic served as a catalyst, accelerating digital adoption across sectors that were previously slow to change.
- Sustainability as a Core Business Strategy: Companies are increasingly prioritizing environmental, social, and governance (ESG) factors in their operations. This includes adopting renewable energy sources, reducing carbon footprints, and implementing sustainable supply chain practices.
- Rise of Artificial Intelligence and Machine Learning: AI is no longer a futuristic concept but a present-day tool transforming industries. From predictive analytics in healthcare to personalized marketing in retail, AI is driving innovation and efficiency.
- Shift Toward Remote and Hybrid Work Models: The traditional office-centric model is evolving into more flexible arrangements. Remote work technologies, collaboration tools, and digital nomad policies are becoming standard in many industries.
- Expansion of the Gig Economy: More professionals are opting for freelance and contract-based work, leading to the growth of platforms that connect businesses with independent talent. This trend is reshaping traditional employment structures and workforce dynamics.
- Focus on Health and Wellness: Consumer demand for products and services that promote physical and mental well-being is surging. This includes everything from organic food and fitness apps to mental health support services.
- Integration of Augmented and Virtual Reality: AR and VR technologies are finding applications beyond gaming, including virtual training, remote assistance, and immersive shopping experiences. These technologies are redefining how users interact with digital content.
Frequently Asked Questions / Pros & Cons
How do emerging trends impact traditional industries?
Emerging trends often disrupt traditional industries by introducing new technologies, business models, or consumer expectations. While this can pose challenges for established players, it also creates opportunities for innovation and growth. For example, the rise of e-commerce forced traditional retailers to adapt or risk losing market share. Similarly, the shift toward remote work has prompted companies to rethink their office space strategies and invest in digital infrastructure.
What role does technology play in shaping these trends?
Technology is a primary driver of emerging trends. Innovations such as artificial intelligence, blockchain, and the Internet of Things (IoT) are enabling businesses to operate more efficiently, create new products, and deliver personalized experiences. For instance, AI-powered chatbots are revolutionizing customer service, while blockchain is enhancing transparency in supply chains. The rapid pace of technological advancement means that staying informed is crucial for leveraging these tools effectively.
What are the benefits of adopting emerging trends early?
Organizations that adopt emerging trends early often gain a competitive advantage. They can position themselves as industry leaders, attract top talent, and build customer loyalty. Early adopters also have the opportunity to influence the direction of these trends, shaping industry standards and best practices. Additionally, embracing change can lead to cost savings, improved operational efficiency, and new revenue streams.
What are the potential risks of following emerging trends?
While there are significant benefits to adopting emerging trends, there are also risks involved. Early adoption can be costly, especially if the trend does not gain widespread acceptance. There is also the challenge of integrating new technologies or processes into existing systems, which can lead to operational disruptions. Moreover, trends that are not fully understood or regulated may pose legal or ethical dilemmas. Businesses must conduct thorough research and risk assessments before committing to any new trend.
How can small businesses keep up with emerging trends on a limited budget?
Small businesses can stay competitive by focusing on trends that align with their core competencies and customer needs. Leveraging free or low-cost digital tools, such as social media platforms and cloud-based software, can help them adopt new technologies without significant investment. Collaborating with industry peers, attending webinars, and joining professional networks are also effective ways to stay informed. Additionally, prioritizing trends that offer immediate value, such as customer experience enhancements, can provide a quick return on investment.
Practical Guidance & Solutions
Navigating emerging industry trends requires a strategic and proactive approach. Here are some actionable steps to help businesses and professionals stay ahead of the curve:
Conduct a Trend Analysis: Regularly assess the market landscape to identify trends that are gaining traction. Use tools like Google Trends, industry reports, and competitor analysis to stay informed. Prioritize trends that align with your business goals and have the potential to deliver tangible benefits.
Invest in Continuous Learning: The pace of change means that ongoing education is essential. Encourage employees to participate in training programs, attend industry conferences, and pursue certifications relevant to emerging trends. Platforms like Coursera, Udemy, and LinkedIn Learning offer affordable options for skill development.
Foster a Culture of Innovation: Create an environment where experimentation and creativity are encouraged. Establish cross-functional teams to explore new ideas and test innovative solutions. Recognize and reward employees who contribute to the adoption of emerging trends, fostering a sense of ownership and engagement.
Leverage Technology Wisely: Before investing in new technologies, evaluate their compatibility with your existing systems and their long-term viability. Start with pilot projects to test the effectiveness of innovations before scaling up. Partnering with tech providers or consultants can also provide valuable insights and support.
Focus on Customer-Centric Trends: Trends that directly benefit customers are more likely to have a lasting impact. Gather feedback through surveys, focus groups, and social media to understand evolving customer needs. Use this data to guide your innovation efforts and tailor your offerings accordingly.
Build Strategic Partnerships: Collaborating with other businesses, startups, or research institutions can provide access to new technologies, expertise, and resources. Partnerships can also help share the risks and costs associated with adopting emerging trends.
Monitor Regulatory Changes: Emerging trends often come with new regulations or compliance requirements. Stay updated on legal developments in your industry to ensure that your business remains compliant and avoids potential penalties.
Conclusion
The future of industries will be shaped by the trends we choose to embrace today. From digital transformation to sustainability, these shifts are not just about technological progress. They are about reimagining how we work, live, and interact with the world. For businesses and professionals, the key to success lies in staying informed, being adaptable, and taking calculated risks. By understanding the forces driving these changes and proactively integrating them into their strategies, organizations can not only survive but thrive in the rapidly evolving landscape. The next wave of industry trends presents both challenges and opportunities. Those who navigate it with foresight and agility will be the ones to lead the way into the future.
]]> ]]>

Introduction & Background
In a world where technology evolves at an unprecedented pace, the boundaries of possibility continue to expand. From artificial intelligence to quantum computing, innovations are reshaping industries, societies, and daily life in ways previously unimaginable. The future is not just approaching; it is already here, and it is being driven by groundbreaking applications that challenge the limits of human ingenuity. These advancements are not merely tools but transformative forces that redefine how we work, communicate, and even perceive reality. As we stand on the brink of a new technological era, it is essential to explore the top five mind-blowing applications that are set to revolutionize our world in the coming years.
Concept & Overview
At the heart of this technological revolution lies the convergence of cutting-edge research and real-world application. These innovations are built on principles such as artificial intelligence, biotechnology, nanotechnology, and advanced robotics, each contributing to a future where the impossible becomes possible. The core idea is to harness these technologies not just for efficiency or convenience but to solve some of humanity’s most pressing challenges. Whether it is revolutionizing healthcare, transforming transportation, or reimagining how we interact with the digital world, these applications are designed to push the boundaries of what is achievable. By understanding their underlying concepts, we can better appreciate their potential impact on society and the global economy.
Key Features & Highlights
The top five mind-blowing tech applications redefining our world share several remarkable features that set them apart:
- Artificial Intelligence in Healthcare: AI-powered diagnostics and personalized treatment plans are revolutionizing patient care. Machine learning algorithms can analyze vast amounts of medical data to detect diseases like cancer at early stages, often with greater accuracy than human doctors. Additionally, AI-driven robotic surgery systems enable precision operations with minimal invasiveness, reducing recovery times and improving outcomes.
- Quantum Computing: Unlike classical computers, quantum computers leverage the principles of quantum mechanics to perform complex calculations at speeds unattainable by traditional systems. This technology has the potential to crack encryption codes, optimize large-scale logistics, and accelerate drug discovery by simulating molecular interactions with unparalleled precision.
- Neural Interface Technology: Brain-computer interfaces (BCIs) are bridging the gap between the human mind and machines. These devices allow users to control computers, prosthetics, or even household appliances using thought alone. Companies like Neuralink are pioneering non-invasive BCIs that could restore mobility to paralyzed individuals and enhance cognitive functions, opening new frontiers in human-machine collaboration.
- Autonomous Vehicles: Self-driving cars and trucks are no longer science fiction but a rapidly advancing reality. Powered by AI, sensors, and real-time data processing, these vehicles promise to reduce traffic accidents, ease congestion, and transform urban mobility. The integration of 5G networks and edge computing further enhances their ability to navigate complex environments safely and efficiently.
- Gene Editing and CRISPR Technology: CRISPR-Cas9 and other gene-editing tools are enabling scientists to rewrite the genetic code of living organisms. From correcting genetic disorders to engineering crops that resist pests and climate change, these technologies hold the key to solving food security issues and eradicating hereditary diseases. The ethical implications are vast, but the potential benefits are transformative for global health and sustainability.
Frequently Asked Questions / Pros & Cons
What are the biggest challenges facing the adoption of these technologies?
One of the primary hurdles is ethical concerns, particularly with gene editing and neural interfaces. Questions about privacy, consent, and the potential for misuse remain unresolved. Additionally, high development costs, regulatory hurdles, and public skepticism can delay widespread adoption. For instance, autonomous vehicles face scrutiny over safety in mixed-traffic environments, while quantum computing requires massive investments in infrastructure and talent.
How will these technologies impact employment and the job market?
While automation and AI may displace certain jobs, they are also expected to create new roles that focus on technology management, maintenance, and innovation. Sectors like healthcare, logistics, and education are likely to see a shift rather than a decline in employment opportunities. However, reskilling and upskilling initiatives will be crucial to prepare the workforce for these changes. Governments and educational institutions must collaborate to ensure that workers can transition into emerging fields.
What are the potential risks associated with these advancements?
Risks include data privacy breaches, especially with AI and neural interfaces that handle sensitive information. Cybersecurity threats could escalate as interconnected devices become more prevalent. In the case of gene editing, unintended consequences such as off-target effects in CRISPR applications could lead to unforeseen health issues. Furthermore, the reliance on technology may reduce human skills in critical thinking and problem-solving, which could have long-term societal impacts.
Which industries stand to benefit the most from these technologies?
Healthcare is poised for a massive transformation, with AI diagnostics, robotic surgery, and personalized medicine leading the way. The transportation sector will see significant changes with autonomous vehicles reducing accidents and improving efficiency. Agriculture could benefit immensely from gene-edited crops that are more resilient to climate change. The finance industry may leverage quantum computing for faster risk assessments and fraud detection, while entertainment and education could be revolutionized by immersive technologies like virtual and augmented reality.
How can individuals prepare for the changes these technologies will bring?
Staying informed and adaptable is key. Individuals should focus on developing digital literacy and learning about emerging technologies through online courses and workshops. Embracing lifelong learning will help them stay relevant in a rapidly changing job market. Additionally, advocating for ethical frameworks and regulations can ensure these technologies are developed and deployed responsibly. Supporting policies that promote equitable access to technology will help prevent a digital divide.
Practical Guidance & Solutions
Steps to Embrace AI in Daily Life
Start by identifying areas where AI can streamline tasks, such as using smart assistants for scheduling or AI-powered apps for fitness tracking. Explore AI-driven healthcare platforms that offer preliminary diagnoses or personalized health insights. Businesses can integrate AI tools for customer service, data analysis, and operational efficiency. Always ensure that the AI systems you use are transparent, fair, and respect user privacy.
Navigating the Quantum Computing Landscape
For businesses and researchers interested in quantum computing, begin by understanding its potential applications in your field. Collaborate with universities or tech companies that specialize in quantum research. Invest in training programs to build expertise in quantum algorithms and programming languages like Qiskit or Cirq. Governments and private sectors should also work together to establish standards and infrastructure to support this technology.
Integrating Neural Interfaces Safely
If considering neural interface technology, prioritize devices that have undergone rigorous testing and received regulatory approval. For healthcare applications, consult with medical professionals to ensure the technology is suitable for your needs. Advocate for strong ethical guidelines to protect user data and prevent misuse. Public awareness campaigns can help demystify these technologies and address concerns about their safety and effectiveness.
Adopting Autonomous Vehicles Responsibly
For individuals, stay updated on the latest advancements in autonomous vehicle technology and understand how these systems operate. Support infrastructure development, such as smart roads and 5G networks, that enable safe autonomous driving. Policymakers should implement comprehensive regulations to ensure safety, accountability, and equitable access. Test drives and pilot programs can help build public trust in these vehicles.
Engaging with Gene Editing Technologies Ethically
Educate yourself on the science behind gene editing and its implications. Support research institutions that prioritize ethical considerations and transparency. If considering gene-editing therapies, consult with genetic counselors and healthcare providers to understand the risks and benefits. Advocate for global regulatory frameworks that balance innovation with safety. Public discussions and debates can help shape policies that reflect societal values and concerns.
Conclusion
The future is not a distant dream but a rapidly unfolding reality shaped by these extraordinary technologies. From AI revolutionizing healthcare to quantum computing unlocking new scientific frontiers, each innovation offers a glimpse into a world where the boundaries of human potential are continually expanded. While challenges such as ethical dilemmas, job displacement, and security risks persist, proactive measures can mitigate these concerns and ensure that progress benefits all of humanity. By staying informed, adaptable, and ethically conscious, we can collectively navigate this transformative era. The key lies in embracing these technologies not as passive consumers but as active participants in shaping a future that is inclusive, sustainable, and boundlessly innovative. The journey ahead is as exciting as it is daunting, and it is ours to explore, refine, and ultimately, redefine.
]]>
Introduction & Background
In today’s rapidly changing financial landscape, few elements affect individuals as directly as insurance laws. These laws do more than regulate policies. They shape how people plan for the future, protect their assets, and secure their families. Every year, governments refine regulations to address new risks, from climate change to digital fraud. Understanding these changes is no longer optional. It has become essential for anyone who wants to make informed decisions about their financial well-being. Whether you are buying a new policy or reviewing an existing one, the fine print in insurance contracts can hold surprising implications. This article explores how modern insurance laws are reshaping the way you think about your financial future.
Concept & Overview
Insurance laws form the legal backbone of the insurance industry. They define the rights and obligations of both policyholders and insurers. At their core, these laws aim to balance fairness, transparency, and financial stability. Modern insurance laws have evolved far beyond traditional risk transfer models. Today, they address complex issues such as data privacy, climate resilience, and digital identity theft. Regulators now require insurers to disclose more information to consumers. They also mandate clearer language in contracts. These changes help reduce disputes and build trust between parties. In many jurisdictions, laws now require insurers to justify premium hikes or deny claims based on transparent criteria. Such reforms reflect a shift toward consumer empowerment and market fairness.
Key Features & Highlights
- Mandatory Disclosure Requirements. Insurers must now provide detailed explanations of coverage limits, exclusions, and claim procedures. This transparency helps policyholders understand exactly what they are purchasing.
- Enhanced Consumer Protections. New laws give consumers stronger rights to challenge unfair claim denials. Regulators can intervene when insurers act in bad faith or delay payments without valid reasons.
- Climate-Related Adjustments. Insurance laws increasingly consider environmental risks. Some regions now require insurers to disclose how climate change may affect future premiums or coverage availability.
- Data Privacy Safeguards. With the rise of digital insurance platforms, laws now protect consumers’ personal and financial data. Insurers must implement robust cybersecurity measures and obtain explicit consent before sharing data.
- Simplified Policy Language. Regulators promote the use of plain language in contracts. This reduces confusion and ensures that policyholders fully grasp their rights and responsibilities.
Frequently Asked Questions / Pros & Cons
What is the main purpose of recent insurance law reforms?
Recent reforms aim to enhance transparency, fairness, and consumer protection. They push insurers to communicate clearly, justify pricing, and handle claims responsibly. The goal is to rebuild trust in a system where policyholders often feel vulnerable.
How do new disclosure rules benefit consumers?
Disclosure rules force insurers to reveal critical details upfront. This allows consumers to compare policies accurately and avoid hidden pitfalls. It also reduces the likelihood of disputes after a claim is filed.
What challenges do insurers face under new laws?
Insurers must invest in compliance systems, legal reviews, and staff training. Some smaller firms struggle with the cost of implementing stricter data security measures. Additionally, frequent regulatory updates create operational uncertainty.
Are climate-related insurance laws fair to all regions?
Climate laws can create inequities between high-risk and low-risk areas. Some regions may face higher premiums or reduced coverage due to increased risks like wildfires or flooding. Policymakers are working to balance affordability with sustainability.
How can consumers stay updated on changing insurance laws?
Consumers should follow updates from regulatory bodies, insurance ombudsmen, and consumer advocacy groups. Annual policy reviews also help identify changes that may affect coverage or cost.
Practical Guidance & Solutions
Start by reviewing your current policies in light of new legal standards. Look for clearer language and check whether exclusions or premiums have changed. If a claim was denied recently, review the insurer’s reasoning against the updated laws. Consider consulting an insurance broker or legal advisor familiar with recent reforms.
When shopping for new coverage, ask direct questions about climate risks, data handling, and claim timelines. Compare at least three quotes while focusing on policy details rather than just price. Keep records of all communications with insurers, as these may be crucial if a dispute arises.
For long-term financial planning, factor in potential regulatory changes. Set aside an emergency fund to cover gaps in coverage during transition periods. Finally, join consumer forums or subscribe to newsletters that track insurance law updates in your region.
Conclusion
Modern insurance laws are rewriting the rules of financial security. They are empowering consumers, holding insurers accountable, and addressing emerging risks with greater urgency. While challenges remain, especially for smaller providers and high-risk areas, the overall trend points toward a more equitable and transparent system. By staying informed and proactive, you can turn these legal changes into opportunities. Your financial future no longer has to be shaped by confusion or hidden clauses. Instead, it can be built on clarity, choice, and confidence. Take the time to understand the fine print today. It will define the security of your tomorrow.
]]>
What’s Changing in 2024 for Policyholders
Introduction & Background
The insurance landscape in 2024 is evolving rapidly, shaped by technological advancements, shifting customer expectations, and global economic changes. As policyholders seek better coverage options and more personalized solutions, insurers are responding with innovative products and services. This year, the focus is on enhancing flexibility, accessibility, and transparency in insurance offerings. For individuals and businesses alike, staying informed about these trends is crucial to making well-informed decisions that protect their financial well-being.
Concept & Overview
Insurance trends in 2024 are largely driven by digital transformation and data analytics. Insurers are leveraging artificial intelligence and machine learning to streamline underwriting processes, reduce costs, and improve risk assessment. Additionally, the rise of parametric insurance is reshaping how people think about coverage, particularly in areas affected by climate change. These advancements are making insurance more responsive to real-time events and less reliant on traditional claims processes. At the same time, regulatory changes and consumer demand for sustainability are pushing insurers to adopt greener practices and offer products that align with environmental, social, and governance (ESG) goals.
Key Features & Highlights
- AI-Powered Underwriting: Insurers are using artificial intelligence to analyze vast amounts of data, leading to faster approvals and more accurate risk evaluations for policyholders.
- Parametric Insurance Expansion: This type of coverage pays out based on predefined triggers, such as natural disasters or travel disruptions, offering quicker payouts without lengthy claims assessments.
- Personalized Policies: With the help of data analytics, insurers are creating customized policies tailored to individual lifestyles, health metrics, and financial goals.
- Sustainability-Focused Products: More insurers are introducing policies that reward eco-friendly behaviors, such as reduced premiums for electric vehicle owners or those with energy-efficient homes.
- Digital-First Platforms: The shift toward online portals and mobile apps allows policyholders to manage their coverage, file claims, and receive assistance more conveniently.
- Cyber Insurance Growth: As cyber threats continue to rise, businesses and individuals are increasingly investing in cyber liability insurance to protect against data breaches and ransomware attacks.
Frequently Asked Questions / Pros & Cons
What is parametric insurance and how does it benefit policyholders?
Parametric insurance pays out a predetermined amount when specific events occur, such as a hurricane or earthquake of a certain magnitude. Unlike traditional insurance, which requires detailed claims assessments, parametric policies provide quick financial relief without lengthy processes. For policyholders, this means faster access to funds during emergencies, reducing financial strain when time is critical.
How are insurers using AI to improve the policyholder experience?
Insurers are integrating AI into underwriting, claims processing, and customer service. AI algorithms can analyze data from various sources to assess risk more accurately, approve policies faster, and detect fraudulent claims. For policyholders, this translates to lower premiums, reduced wait times for claims, and more personalized policy recommendations based on their unique profiles.
Are personalized insurance policies more expensive than traditional ones?
Personalized policies can sometimes be more cost-effective because they are tailored to the individual’s actual risk profile. For example, a healthy individual may qualify for lower health insurance premiums based on lifestyle data, while a low-risk driver might pay less for auto insurance. However, the cost depends on the level of customization and the data used. It’s important for policyholders to compare options to ensure they are getting the best value.
What should I look for when choosing a sustainable insurance product?
When selecting a sustainable insurance product, consider the insurer’s commitment to environmental and social responsibility. Look for policies that offer incentives for sustainable practices, such as discounts for green home improvements or electric vehicle ownership. Additionally, review the insurer’s ESG reporting to ensure their values align with yours. Transparency in how premiums are invested is also a key factor to evaluate.
Is cyber insurance necessary for small businesses?
Cyber insurance is becoming essential for businesses of all sizes, including small enterprises. Cyberattacks can result in significant financial losses, reputational damage, and legal liabilities. Small businesses, which often have fewer resources to recover from such incidents, can benefit greatly from cyber insurance coverage. It typically includes expenses related to data recovery, legal fees, and customer notification, providing a safety net against unforeseen cyber risks.
Practical Guidance & Solutions
To navigate the evolving insurance landscape in 2024, policyholders should take a proactive approach. Start by reviewing your current coverage to identify gaps or outdated policies that no longer meet your needs. Consider leveraging digital tools and AI-driven platforms to compare quotes and find the best deals. If you’re interested in parametric or personalized policies, consult with an insurance advisor who can explain the terms and help you assess whether these options suit your situation.
For those prioritizing sustainability, research insurers that offer green incentives and verify their ESG credentials. When it comes to cyber insurance, even small businesses should evaluate their digital vulnerabilities and opt for policies that cover a broad range of cyber threats. Lastly, stay informed about regulatory changes in your region, as these can impact insurance costs and availability. By taking these steps, you can ensure your coverage remains relevant, affordable, and aligned with your long-term goals.
Conclusion
2024 is a pivotal year for the insurance industry, marked by innovation, personalization, and a stronger focus on sustainability. As policyholders, the key to maximizing these changes lies in awareness and adaptability. Whether it’s embracing AI-driven underwriting, exploring parametric insurance, or prioritizing eco-friendly policies, staying ahead of trends can lead to better protection and savings. By making informed decisions and leveraging the latest tools, you can secure coverage that not only meets your needs today but also adapts to the challenges of tomorrow. The future of insurance is dynamic, and those who engage with these trends will be best positioned to thrive in an ever-changing world.
]]>
Navigating Tomorrow: Unveiling Hidden Market Trends Before They Emerge
Introduction & Background
The world of business and investment thrives on foresight, where the ability to anticipate change often separates success from stagnation. Markets are no longer static landscapes but dynamic ecosystems influenced by technology, consumer behavior, and global events. In this climate, recognizing emerging trends before they fully materialize is not just advantageous. It is essential for staying ahead of the curve. Pioneers in various industries have long relied on data-driven insights and predictive analytics to gain an edge. Yet, the challenge remains in separating signal from noise. This article explores how businesses and investors can decode the subtle signals of tomorrow’s markets and position themselves strategically for what lies ahead.
Concept & Overview
Unveiling hidden market trends involves a proactive approach to identifying patterns and shifts that are not yet visible to the majority. At its core, it is about understanding the underlying forces driving change before they manifest in mainstream indicators. This concept blends elements of predictive analytics, behavioral economics, and real-time data monitoring. It requires not just technological tools but also a mindset that values curiosity and adaptability. Traditionally, trend analysis relied heavily on historical data and linear projections. However, modern methodologies incorporate machine learning, social listening, and scenario modeling to capture nuanced shifts in consumer preferences, technological adoption, and regulatory landscapes. The goal is to transform uncertainty into opportunity by acting on insights that others have not yet recognized.
Key Features & Highlights
- Data-Driven Insight Gathering: Utilizing advanced analytics platforms to process large volumes of structured and unstructured data from multiple sources. This includes social media sentiment, search trends, and transactional records.
- Behavioral Pattern Recognition: Monitoring shifts in consumer behavior through purchasing history, engagement metrics, and interaction patterns across digital platforms.
- Predictive Modeling: Employing algorithms to simulate future scenarios based on current trends and external factors. This helps in forecasting demand, identifying niche markets, and anticipating disruptions.
- Cross-Industry Correlation Analysis: Identifying connections between seemingly unrelated sectors. For example, how advancements in renewable energy might influence automotive manufacturing trends.
- Real-Time Alert Systems: Implementing dashboards and notifications that flag anomalies or emerging patterns as they occur, allowing for swift strategic adjustments.
- Scenario Planning Tools: Developing multiple future narratives based on different variables to prepare for various outcomes and reduce risk exposure.
Frequently Asked Questions / Pros & Cons
What are the primary benefits of identifying hidden market trends early?
Early identification allows businesses to capitalize on first-mover advantages, optimize resource allocation, and respond proactively to changing customer needs. It also enables organizations to mitigate risks by anticipating shifts in the competitive landscape or regulatory environments. For investors, it provides the opportunity to allocate capital to high-growth sectors before they become widely recognized, potentially yielding superior returns.
What are the main challenges in uncovering these hidden trends?
One of the primary challenges is the sheer volume of data available, which can overwhelm even the most sophisticated analytical systems. Another difficulty lies in distinguishing meaningful signals from random noise. Additionally, biases in data collection or interpretation can lead to incorrect conclusions. External shocks such as geopolitical events or technological breakthroughs can also disrupt even the most carefully constructed predictions.
How do companies typically fund and implement trend forecasting initiatives?
Companies often invest in dedicated research teams, partnerships with data analytics firms, or acquisition of specialized software platforms. Budget allocation depends on the organization’s size and sector, with larger enterprises typically dedicating more resources to dedicated innovation labs. Smaller firms may leverage open-source tools and freelance expertise to gain insights without significant upfront investment.
Can hidden trends be reliably quantified, or are they inherently subjective?
While many trends begin as qualitative shifts in perception or behavior, they can often be quantified using proxy metrics. For instance, early adoption of a new product feature can be measured through beta testing feedback and pre-order data. However, the interpretation of these metrics requires a blend of quantitative analysis and qualitative judgment. Subjectivity remains a factor in assessing long-term cultural or societal trends.
Practical Guidance & Solutions
To effectively navigate the landscape of emerging market trends, organizations should adopt a structured yet flexible approach. Begin by establishing a dedicated trend monitoring unit or task force that combines data science, market research, and domain expertise. Leverage a mix of internal and external data sources, ensuring diversity in perspectives and methodologies. Regularly update forecasting models with real-world feedback to refine predictions.
Invest in training teams to interpret data within broader industry and societal contexts. Encourage a culture of experimentation where small-scale pilots can test hypotheses about future trends without excessive risk. Collaboration with startups, academic institutions, and industry consortia can provide fresh insights and access to cutting-edge tools.
Finally, maintain agility in decision-making. The most successful trend forecasters are those who can pivot quickly when new information emerges. Establish clear evaluation criteria for trend signals, so teams know when to act, scale, or pivot. By combining analytical rigor with intuitive judgment, businesses can turn uncertainty into a competitive advantage.
Conclusion
The future of market leadership belongs to those who can see beyond the horizon today. In an era defined by rapid transformation, the ability to uncover hidden trends before they become mainstream is not just a strategic asset. It is a necessity for survival and growth. While the tools and techniques for trend forecasting continue to evolve, the core principle remains unchanged. Success depends on a relentless pursuit of knowledge, an openness to change, and the courage to act on insights that others may overlook. As we stand on the brink of tomorrow, the question is not whether we can predict the future. It is whether we are willing to prepare for it today. By embracing a proactive mindset and leveraging the power of data and human insight, organizations can not only navigate tomorrow but shape it.
]]>Introduction & Background
The global economy operates like a vast, interconnected ocean where financial trends rise and fall with the tides of innovation, policy shifts, and unforeseen disruptions. In today’s fast-paced world, understanding these movements is not just for economists or policymakers, but for anyone aiming to secure their financial future. Whether you’re an entrepreneur, investor, or simply a curious observer, grasping the “Economic Pulse” can mean the difference between riding the waves of prosperity and being swept away by unexpected currents. This article dives into the essence of global financial trends, exploring their origins, impacts, and how individuals and businesses can navigate them effectively.
Concept & Overview
The term “Economic Pulse” refers to the rhythmic fluctuations in economic activity that reflect the health and direction of a nation’s or the world’s financial system. These pulses are influenced by a multitude of factors, including technological advancements, geopolitical events, consumer behavior, and central bank policies. At its core, the concept revolves around identifying patterns in economic data such as GDP growth, inflation rates, employment figures, and market indices.
One of the foundational principles of the Economic Pulse is the business cycle, which describes the natural rise and fall in economic activity over time. These cycles typically consist of expansion, peak, contraction, and trough phases. Recognizing where the economy stands within this cycle can provide valuable insights into future trends, helping stakeholders make informed decisions. Additionally, the interconnected nature of global markets means that economic shocks in one region can quickly ripple across the world, underscoring the need for a holistic view of financial trends.
Key Features & Highlights
- Global Interconnectedness: Modern economies are deeply linked through trade, investment, and technology. A slowdown in one major economy, such as China or the United States, can have cascading effects on smaller economies worldwide.
- Central Bank Policies: Decisions made by central banks, like the Federal Reserve or the European Central Bank, play a pivotal role in shaping economic trends. Interest rate adjustments and quantitative easing measures directly impact borrowing costs, inflation, and consumer spending.
- Technological Disruption: Innovations such as artificial intelligence, blockchain, and renewable energy are reshaping industries and creating new economic opportunities. However, they also pose challenges by rendering traditional business models obsolete.
- Inflation and Deflation: Inflation erodes purchasing power, while deflation can signal economic stagnation. Monitoring these trends helps individuals and businesses adjust their strategies accordingly, whether by investing in inflation-resistant assets or adjusting pricing models.
- Geopolitical Risks: Trade tensions, sanctions, and political instability can disrupt supply chains and financial markets. Events like Brexit or the Russia-Ukraine conflict have demonstrated how quickly economic conditions can change due to geopolitical factors.
- Consumer Sentiment: The confidence levels of consumers and businesses influence spending and investment patterns. High optimism can fuel economic growth, while pessimism can lead to reduced activity and slower growth.
Frequently Asked Questions / Pros & Cons
What are the main drivers of global financial trends?
Global financial trends are primarily driven by a combination of macroeconomic policies, technological advancements, geopolitical events, and market sentiment. For instance, central banks’ monetary policies often set the tone for interest rates and liquidity, which in turn affect investment flows. Meanwhile, breakthroughs in technology can create new industries while disrupting old ones, and geopolitical conflicts can introduce uncertainty that shakes investor confidence. Market sentiment, influenced by news and perceptions, also plays a critical role in shaping short-term trends.
How can individuals protect their finances during economic downturns?
During economic downturns, individuals can take several steps to safeguard their finances. Diversifying investments across different asset classes, such as stocks, bonds, and real estate, can reduce risk. Building an emergency fund with three to six months’ worth of living expenses provides a financial cushion against job loss or unexpected expenses. Paying down high-interest debt is another prudent strategy, as it reduces financial strain when interest rates rise. Additionally, staying informed about economic indicators and adjusting spending habits can help navigate challenging times more effectively.
What role do governments play in managing economic trends?
Governments play a multifaceted role in managing economic trends through fiscal and monetary policies. Fiscal policy involves government spending and taxation, which can stimulate or cool down the economy as needed. For example, during a recession, increased government spending on infrastructure projects can create jobs and boost demand. Monetary policy, managed by central banks, focuses on controlling the money supply and interest rates to achieve price stability and full employment. Governments also implement regulations to protect consumers and ensure fair competition, which can foster long-term economic stability.
Are emerging markets more vulnerable to global financial trends than developed markets?
Emerging markets often exhibit greater vulnerability to global financial trends due to their reliance on foreign investment, volatile currencies, and less diversified economies. While they may offer high growth potential, they are also more susceptible to capital flight during periods of global uncertainty. Factors such as commodity price fluctuations, political instability, and weaker institutional frameworks can exacerbate their exposure to external shocks. However, with prudent economic management and structural reforms, emerging markets can build resilience and even outperform developed markets over the long term.
How can businesses adapt to rapidly changing economic conditions?
Businesses can adapt to rapidly changing economic conditions by adopting agile strategies that emphasize flexibility and innovation. Diversifying revenue streams and customer bases can reduce dependence on a single market or product. Investing in technology and workforce training can enhance productivity and competitiveness. Maintaining strong financial reserves allows businesses to weather downturns without resorting to drastic measures like layoffs or closures. Additionally, closely monitoring economic indicators and industry trends enables businesses to pivot quickly in response to new opportunities or threats.
Practical Guidance & Solutions
Navigating the Economic Pulse requires a blend of awareness, preparation, and adaptability. Here are actionable steps to help individuals and businesses stay ahead of the curve:
For Individuals:
Start by conducting a thorough financial assessment to understand your income, expenses, savings, and debt. Prioritize building a diversified investment portfolio that aligns with your risk tolerance and long-term goals. If the economy shows signs of overheating or inflationary pressures, consider allocating a portion of your portfolio to assets like gold, real estate, or inflation-protected securities. Keep an eye on central bank announcements and adjust your borrowing and saving strategies accordingly. For those nearing retirement, a conservative approach may be prudent, while younger individuals can afford to take on more risk for higher potential returns.
Staying informed is equally important. Subscribe to reputable financial news outlets and follow economic reports from organizations like the International Monetary Fund (IMF) or the World Bank. Joining investment clubs or seeking advice from a certified financial planner can provide additional insights tailored to your situation. Finally, cultivate a mindset of lifelong learning to keep pace with evolving economic landscapes.
For Businesses:
Businesses should adopt a forward-looking approach by scenario planning for various economic conditions. Identify key risk factors that could impact your industry and develop contingency plans to mitigate them. For example, if your supply chain relies heavily on imported goods, explore alternative suppliers or local sourcing options to reduce dependency on foreign markets.
Technology adoption is another critical area. Invest in digital tools that enhance operational efficiency, customer engagement, and data analytics. Automation can reduce labor costs and improve accuracy, while e-commerce platforms can expand your market reach. Additionally, fostering a culture of innovation within your organization can lead to the development of new products or services that address emerging consumer needs.
Financial prudence is essential, especially during periods of economic uncertainty. Maintain a healthy balance sheet with adequate liquidity to cover operational expenses without relying on external financing. Regularly review your pricing strategies to ensure they remain competitive while preserving profit margins. Engage with customers to understand their evolving preferences and adapt your offerings to meet changing demands.
Conclusion
The Economic Pulse is a dynamic force that shapes the fortunes of individuals, businesses, and nations alike. By understanding the underlying drivers of global financial trends and adopting proactive strategies, it is possible to turn volatility into opportunity. Whether through diversifying investments, embracing technological innovation, or preparing for economic downturns, informed decision-making is the key to riding the waves of change.
As we look to the future, the ability to anticipate and adapt to economic shifts will become even more critical. The global financial landscape will continue to evolve, presenting new challenges and possibilities. By staying vigilant, adaptable, and informed, we can navigate these changes with confidence and resilience. Ultimately, the Economic Pulse is not something to fear, but a rhythm to be understood, harnessed, and mastered for a prosperous tomorrow.
]]>
Introduction & Background
In an era defined by rapid technological advancement and shifting consumer behaviors, businesses must adapt or risk falling behind. Data-driven market analysis has emerged as a cornerstone for modern decision-making, offering leaders the clarity they need to navigate uncertainty and seize opportunities. Gone are the days when intuition alone dictated strategy. Today, tomorrow’s leaders rely on robust, real-time insights to forecast trends, understand customer preferences, and optimize operations. This transformation is not merely a trend but a fundamental shift in how organizations operate, compete, and grow. By harnessing the power of data, businesses can unlock growth that is both sustainable and scalable, positioning themselves at the forefront of their industries.
Concept & Overview
Data-driven market analysis refers to the systematic process of collecting, processing, and interpreting data to inform strategic business decisions. At its core, it combines traditional market research with advanced analytics, artificial intelligence, and machine learning to uncover patterns, predict outcomes, and guide action. Unlike conventional approaches that rely heavily on historical data or gut feeling, this method emphasizes agility and precision. It enables organizations to move beyond reactive strategies and instead adopt a proactive stance, anticipating changes before they occur. The principles of data-driven analysis rest on three pillars: accuracy, relevance, and actionability. Leaders must ensure that the data they use is reliable, that it addresses the right questions, and that it leads to clear, executable insights. When implemented effectively, this approach transforms raw data into a strategic asset, empowering businesses to make informed choices that drive measurable growth.
Key Features & Highlights
- Predictive Analytics: The ability to forecast future market trends using historical data and statistical algorithms. This feature allows businesses to stay ahead of shifts in demand, pricing, or competition.
- Customer Segmentation: Grouping customers based on shared characteristics such as demographics, purchasing behavior, or preferences. This enables tailored marketing strategies and improved customer engagement.
- Real-Time Data Monitoring: Access to live data streams that provide up-to-the-minute insights into market conditions, sales performance, or consumer sentiment. This agility is crucial in fast-moving industries.
- Competitive Intelligence: Systematic tracking of competitors’ activities, from pricing changes to product launches. This intelligence helps businesses identify gaps, threats, and opportunities in the market landscape.
- Automated Reporting: Generation of customized reports on key performance indicators (KPIs) without manual intervention. This saves time and ensures consistency in decision-making across teams.
- Integration Capabilities: Seamless compatibility with existing tools such as CRM systems, ERP software, or business intelligence platforms. This ensures that data flows smoothly across departments and functions.
Frequently Asked Questions / Pros & Cons
What are the main benefits of using data-driven market analysis?
Data-driven market analysis offers several advantages, including improved decision-making accuracy, enhanced customer understanding, and increased operational efficiency. By relying on empirical evidence rather than assumptions, businesses can reduce risks and allocate resources more effectively. It also fosters innovation by identifying emerging trends and unmet customer needs. Additionally, it provides a measurable way to track the success of strategies and campaigns over time.
Are there any challenges in implementing this approach?
Yes, challenges include data quality issues, such as incomplete or inconsistent datasets, which can skew results. There is also the complexity of integrating multiple data sources and tools, which may require significant technical expertise. Privacy and compliance concerns, especially with regulations like GDPR, add another layer of difficulty. Furthermore, the initial investment in technology and talent can be substantial, and organizations may face resistance to change from employees accustomed to traditional methods.
How can small businesses adopt data-driven strategies without large budgets?
Small businesses can start by leveraging free or low-cost analytics tools such as Google Analytics, social media insights, or open-source software. Focusing on high-impact, low-effort data points, like customer purchase history or website traffic, can yield immediate benefits. Partnering with local universities or freelance data analysts can also provide access to expertise without the overhead of a full-time team. Prioritizing one or two key areas of analysis, rather than attempting a full-scale transformation, can help build momentum and demonstrate value quickly.
What role does artificial intelligence play in modern market analysis?
Artificial intelligence enhances market analysis by automating data processing, identifying complex patterns, and generating predictive models at scale. AI-powered tools can analyze vast datasets in real time, detect anomalies, and provide personalized recommendations. They also enable sentiment analysis of customer reviews or social media posts, offering deeper insights into public perception. By reducing manual labor and human error, AI allows analysts to focus on strategic interpretation rather than data crunching.
Practical Guidance & Solutions
Adopting a data-driven approach begins with a clear understanding of your business objectives. Start by defining what success looks like, whether it’s increasing market share, improving customer retention, or launching a new product. Next, assess your current data capabilities. Identify gaps in your data collection processes and invest in tools or platforms that align with your needs and budget. Training your team is equally important; ensure they understand how to interpret data and apply insights to their roles.
Focus on building a data culture within your organization. Encourage collaboration between departments, such as marketing, sales, and operations, to share insights and align strategies. Regularly review and refine your data sources to maintain accuracy and relevance. For example, if customer feedback reveals a shift in preferences, adjust your product offerings or messaging accordingly. Finally, measure the impact of your data-driven decisions by tracking KPIs and adjusting tactics as needed. This iterative process ensures continuous improvement and long-term growth.
Conclusion
In a world where information is abundant but wisdom is scarce, data-driven market analysis provides the compass that tomorrow’s leaders need to navigate the complexities of business. It transforms uncertainty into opportunity, intuition into insight, and potential into performance. While the journey requires commitment, the rewards are undeniable: sharper strategies, stronger customer relationships, and sustainable growth. The future belongs to those who can not only collect data but also interpret it meaningfully. By embracing this approach today, businesses can unlock the growth they envision for tomorrow, and lead with confidence in an ever-evolving landscape.
]]>
Introduction & Background
The modern workplace is evolving faster than ever before, driven by rapid technological advancements and shifting professional demands. As industries adapt to digital transformation, the tools we use to create, collaborate, and innovate must also evolve. Future-proofing your workflow isn’t just about keeping up with trends; it’s about ensuring that your creative process remains efficient, flexible, and resilient in the face of constant change.
Creative professionals, from designers and developers to marketers and writers, face unique challenges in maintaining productivity while embracing new methodologies. The right software tools can bridge the gap between traditional workflows and future-ready solutions. By integrating adaptable, intelligent, and scalable tools, you can safeguard your work against obsolescence and position yourself for long-term success.
Concept & Overview
Future-proofing your workflow involves selecting and adopting software tools that are designed to grow with your needs. These tools prioritize flexibility, interoperability, and forward-thinking features that anticipate technological shifts. At its core, future-proofing is about reducing friction in your creative process while maximizing output and quality.
Modern creative software is no longer just about individual tasks. Instead, it emphasizes seamless integration, real-time collaboration, and automation to handle repetitive processes. Tools that leverage artificial intelligence, cloud computing, and open-source frameworks are becoming essential for professionals who want to stay ahead. The goal is to create a workflow that is not only efficient today but also adaptable to the unknown challenges of tomorrow.
A key principle in future-proofing is modularity. Instead of relying on monolithic software suites that lock you into a specific ecosystem, modular tools allow you to mix and match solutions that best fit your workflow. This approach ensures that as new tools emerge, you can integrate them without disrupting your entire system.
Key Features & Highlights
- Cloud-Based Collaboration: Tools that offer real-time cloud syncing and multi-user editing enable teams to work together from anywhere. This feature ensures continuity and reduces dependency on local hardware or specific locations.
- Artificial Intelligence Integration: AI-powered tools can automate repetitive tasks, such as image cropping, color correction, or content generation. This allows creative professionals to focus on higher-level creative work while the software handles the mundane.
- Cross-Platform Compatibility: Software that works seamlessly across different operating systems and devices ensures accessibility. Whether you’re using a desktop, tablet, or smartphone, your tools should adapt to your workflow, not limit it.
- Open API and Plugin Support: Tools with open APIs and extensive plugin ecosystems allow for customization and extension. This flexibility means you can tailor the software to your specific needs rather than adapting your workflow to the software’s limitations.
- Automated Workflows: Features like macros, templates, and scripting reduce manual effort by automating repetitive processes. For example, automated file organization or batch processing can save hours of work each week.
- Data Security and Compliance: As digital workflows expand, protecting sensitive data becomes crucial. Tools that offer robust encryption, two-factor authentication, and compliance with industry standards ensure your workflow remains secure.
- Scalability: Future-proof tools can scale with your business or project size. Whether you’re a freelancer handling a single client or a large team managing multiple projects, the software should grow alongside your needs without performance degradation.
Frequently Asked Questions / Pros & Cons
What are the main advantages of using future-proof creative software?
Future-proof creative software offers several key advantages. Firstly, it reduces the need for frequent software updates or migrations, saving time and resources. Secondly, it enhances collaboration by enabling real-time teamwork across different locations. Thirdly, it improves efficiency through automation and AI-driven features, allowing professionals to focus on creativity rather than repetitive tasks. Finally, these tools future-proof your skill set, making you more adaptable in a rapidly changing job market.
Are there any downsides to adopting such tools?
While the benefits are substantial, there are potential downsides to consider. One challenge is the learning curve associated with new software. Transitioning to advanced tools often requires time and training, which can temporarily slow down productivity. Additionally, some future-proof tools come with subscription models that may become costly over time. There is also the risk of over-reliance on technology, which might reduce hands-on creative control in certain scenarios. Lastly, not all tools integrate seamlessly with existing workflows, so careful evaluation is necessary.
How do I know if a software tool is truly future-proof?
Assessing whether a software tool is future-proof involves evaluating several factors. Start by checking the company’s track record in software development and updates. Look for tools that are actively maintained and have a roadmap for future features. Additionally, consider the tool’s compatibility with emerging technologies, such as AI, blockchain, or augmented reality. User reviews and industry endorsements can also provide insight into the tool’s longevity and reliability.
Can small businesses or freelancers benefit from future-proof software?
Absolutely. Future-proof software is particularly beneficial for small businesses and freelancers because it allows them to compete with larger organizations without significant upfront investments. Cloud-based tools, for instance, eliminate the need for expensive hardware, while subscription models spread costs over time. Automation and AI features also level the playing field by increasing efficiency and output quality. For freelancers, future-proof tools can help build a scalable and professional workflow that attracts high-paying clients.
Practical Guidance & Solutions
To future-proof your workflow effectively, start by auditing your current tools and processes. Identify bottlenecks, repetitive tasks, and areas where collaboration could be improved. Next, research software solutions that address these pain points while offering scalability and flexibility. Prioritize tools that align with your long-term goals rather than short-term convenience.
When selecting software, consider the following steps:
- Prioritize Integration: Choose tools that integrate well with your existing ecosystem. For example, if you use a specific project management platform, select creative software that syncs with it seamlessly.
- Test Before Committing: Many software providers offer free trials or demos. Use these opportunities to evaluate the tool’s ease of use, performance, and compatibility with your workflow.
- Invest in Training: Allocate time and resources for training your team or yourself on new tools. This investment pays off by reducing errors and increasing efficiency in the long run.
- Plan for Migration: If transitioning from legacy software, plan the migration process carefully. Back up your data, communicate changes to your team, and gradually phase out old tools to minimize disruption.
- Monitor Industry Trends: Stay informed about emerging technologies and tools that could enhance your workflow. Subscribe to industry newsletters, attend webinars, and participate in online communities to keep your knowledge current.
Another practical approach is to adopt a modular workflow. Instead of relying on a single software suite, combine specialized tools that best fit each task. For example, use a cloud-based design tool for visuals, a separate platform for project management, and an AI assistant for content creation. This modular approach ensures that you’re not locked into a single vendor and can easily swap out tools as better alternatives emerge.
Conclusion
The tools we use today shape the creative output of tomorrow. Future-proofing your workflow is not just a strategic move; it’s a necessity in an era defined by rapid change and relentless innovation. By embracing adaptable, intelligent, and scalable software tools, you position yourself to thrive in an unpredictable landscape.
Start by evaluating your current workflow and identifying areas for improvement. Invest in tools that prioritize collaboration, automation, and flexibility. Stay curious and proactive, keeping an eye on emerging technologies that could revolutionize your process. Remember, the goal isn’t to predict the future but to build a workflow that can evolve with it.
In the end, future-proofing is about more than just technology. It’s about cultivating a mindset of continuous improvement and adaptability. Equip yourself with the right tools, refine your processes, and remain open to change. With the right foundation, your creative workflow will not only survive the future but flourish in it.
]]>
Introduction & Background
Technology has always been a driving force behind human progress, but today, its influence is more profound than ever. From the way we communicate to how we manage our health, technology is quietly reshaping the fabric of our daily routines. The modern world is experiencing a technological revolution that goes beyond smartphones and laptops. Innovations like artificial intelligence, the Internet of Things (IoT), and wearable devices are transforming everyday activities in ways that were once unimaginable. These changes are not just about convenience. They represent a fundamental shift in how we interact with the world around us, making our lives safer, healthier, and more connected. Understanding these transformations is crucial because they affect every aspect of society, from education and work to entertainment and healthcare. As we stand on the brink of this new era, it is essential to recognize how technology is not only improving our present but also shaping the future in unexpected and extraordinary ways.
Concept & Overview
The concept of technology transforming everyday lives revolves around the integration of digital and physical systems to enhance human experiences. At its core, this transformation is driven by connectivity, automation, and data-driven decision-making. Technology is no longer confined to standalone devices. Instead, it is woven into the very fabric of daily routines through smart systems that anticipate needs and respond intelligently. For instance, smart home devices adjust lighting and temperature based on our preferences, while health-tracking wearables monitor vital signs in real time. This seamless integration is made possible by advances in artificial intelligence, which enables systems to learn and adapt to individual behaviors. The Internet of Things (IoT) further bridges the gap between devices, allowing them to communicate and collaborate without human intervention. Beyond convenience, these technologies aim to improve efficiency, sustainability, and personal well-being. The overarching goal is to create a more intuitive and responsive environment where technology acts as a silent partner, enhancing human potential without overshadowing it.
Key Features & Highlights
- Smart Home Automation: Devices like smart thermostats, lights, and security cameras allow homeowners to control their environment remotely. These systems learn from user habits and optimize energy usage, reducing costs while increasing comfort. Integration with voice assistants like Alexa or Google Assistant makes interaction effortless and hands-free.
- Health Monitoring Wearables: Fitness trackers and smartwatches monitor heart rate, sleep patterns, and physical activity. Some advanced devices even detect early signs of health issues like atrial fibrillation, providing users with critical insights before symptoms appear. This real-time data empowers individuals to take proactive steps toward better health.
- AI-Powered Personal Assistants: Virtual assistants such as Siri, Cortana, and Bixby use natural language processing to help users manage schedules, send messages, or search for information. They continuously improve their responses by analyzing user interactions, making them more personalized over time.
- Augmented Reality (AR) in Retail & Education: AR technology overlays digital information onto the physical world, enhancing shopping experiences by allowing customers to virtually try on clothes or visualize furniture in their homes. In education, AR brings textbooks to life, making complex subjects like anatomy or history more engaging and interactive.
- Autonomous Vehicles & Smart Transportation: Self-driving cars and AI-powered traffic systems aim to reduce accidents and congestion. These technologies use sensors and machine learning to navigate roads safely, while ride-sharing apps optimize routes to minimize travel time and fuel consumption.
- Blockchain for Secure Transactions: Beyond cryptocurrencies, blockchain technology is being used to secure digital identities, streamline supply chains, and verify the authenticity of products. Its decentralized nature ensures transparency and reduces the risk of fraud in financial and legal transactions.
- 5G Networks & Ultra-Fast Connectivity: The rollout of 5G technology enables faster internet speeds and lower latency, which is critical for innovations like remote surgery, augmented reality gaming, and real-time IoT device communication. This connectivity forms the backbone of a more interconnected world.
- Personalized Learning Platforms: AI-driven educational tools adapt to individual learning styles, providing customized lessons and feedback. Platforms like Duolingo and Khan Academy use algorithms to identify strengths and weaknesses, helping students progress at their own pace.
- Sustainable Tech Solutions: From solar-powered chargers to AI-driven energy grids, technology is playing a pivotal role in sustainability. Smart grids balance energy supply and demand, while IoT sensors monitor environmental conditions, helping cities reduce waste and carbon footprints.
- Virtual Reality (VR) in Therapy & Training: VR is being used in mental health therapy to treat phobias and PTSD by simulating controlled environments. In professional training, VR allows pilots, surgeons, and soldiers to practice complex scenarios in a risk-free setting, improving skills and reducing errors.
Frequently Asked Questions / Pros & Cons
What are the biggest benefits of integrating technology into daily life?
Technology enhances convenience, efficiency, and safety by automating routine tasks and providing real-time insights. For example, smart home devices save time and energy, while health wearables help users stay on top of their well-being. Connectivity through 5G and IoT ensures that people remain connected and informed, regardless of location. Additionally, personalized services powered by AI improve user experiences by tailoring recommendations to individual needs.
Are there any downsides to relying too much on technology?
Excessive reliance on technology can lead to issues such as reduced social interaction, privacy concerns, and increased screen time. For instance, excessive use of social media has been linked to feelings of isolation and anxiety. Moreover, the rapid pace of technological change can make it difficult for some individuals to keep up, leading to a digital divide. Cybersecurity risks, such as data breaches and identity theft, also pose significant challenges to individuals and organizations alike.
How does artificial intelligence (AI) impact job markets?
AI is transforming job markets by automating repetitive tasks, which can lead to job displacement in certain sectors. However, it also creates new opportunities in fields like data science, AI ethics, and robotics maintenance. The key to navigating this shift lies in upskilling and adapting to roles that require creativity, emotional intelligence, and complex problem-solving, skills that AI currently cannot replicate. Governments and educational institutions play a crucial role in providing training programs to bridge the skills gap.
What role does 5G play in the future of technology?
5G technology is a game-changer because it offers ultra-fast speeds, low latency, and the ability to connect a massive number of devices simultaneously. This makes it possible to support innovations like autonomous vehicles, remote surgery, and immersive augmented reality experiences. For industries, 5G enables real-time data processing, which enhances decision-making and operational efficiency. As the technology becomes more widespread, it will unlock new possibilities that were previously constrained by slower networks.
Can technology help address environmental challenges?
Yes, technology is a powerful tool for tackling environmental issues. Smart grids optimize energy distribution, reducing waste and dependence on fossil fuels. IoT sensors monitor air and water quality, providing data that helps policymakers take targeted actions. Renewable energy technologies, such as solar and wind power, are becoming more efficient and affordable. Additionally, AI is being used to model climate change scenarios and develop sustainable solutions for agriculture and urban planning.
Practical Guidance & Solutions
Adopting technology into daily life doesn’t have to be overwhelming. Start by identifying areas where technology can simplify tasks or enhance well-being. For example, if managing household chores feels time-consuming, consider investing in smart home devices like robotic vacuums or automated lighting systems. These tools can free up time for more meaningful activities. For health-conscious individuals, wearable devices offer a practical way to monitor progress and set goals. Choose devices that align with personal needs and integrate easily with existing systems.
When it comes to privacy and security, always prioritize solutions that offer robust encryption and transparent data policies. Use strong, unique passwords for accounts and enable two-factor authentication wherever possible. Stay informed about common cybersecurity threats, such as phishing scams, and educate family members about safe online practices. If concerns about job displacement arise due to automation, explore online courses or certifications in high-demand fields like coding, digital marketing, or cybersecurity. Many platforms offer affordable and flexible learning options to help bridge the skills gap.
For businesses, leveraging technology can drive growth and customer satisfaction. Implementing AI-powered chatbots can improve customer service by providing instant responses to inquiries. Using data analytics tools can help identify trends and optimize operations. Consider adopting cloud-based solutions to enhance collaboration and scalability. When integrating new technologies, start with a pilot program to test effectiveness before scaling up. Collaboration with tech experts or consultants can also ensure smooth implementation and minimize disruptions.
Finally, embrace a balanced approach to technology use. While it offers incredible benefits, it’s important to set boundaries to avoid over-reliance. Designate tech-free times, such as during meals or before bedtime, to foster real-world connections and mental well-being. Encourage children to engage in offline activities that promote creativity and physical health. By thoughtfully integrating technology into daily routines, individuals and communities can harness its full potential while maintaining a healthy and balanced lifestyle.
Conclusion
The technological revolution is not a distant future. It is happening right now, reshaping the way we live, work, and interact with the world. From smart homes that adapt to our needs to healthcare systems that predict illness before it strikes, technology is quietly empowering us to live healthier, safer, and more fulfilling lives. While challenges like privacy concerns and job displacement remain, the benefits far outweigh the risks when used responsibly. The key to unlocking technology’s full potential lies in thoughtful integration, continuous learning, and a commitment to using innovation for the greater good. As we look ahead, one thing is clear. The future will be defined by our ability to embrace these changes, adapt to new realities, and harness the power of technology to create a better tomorrow for everyone.
]]>
Introduction & Background
The regulatory landscape in 2024 is undergoing a transformation, driven by rapid technological advancements, geopolitical shifts, and evolving societal expectations. Organizations across industries are facing a wave of new compliance requirements that demand agility and foresight. These changes are not merely administrative updates but pivotal shifts that can redefine how businesses operate, manage risk, and maintain stakeholder trust. Understanding the forces behind these regulatory updates is essential for compliance professionals and business leaders alike.
The significance of staying ahead of regulatory changes cannot be overstated. Non-compliance can lead to severe financial penalties, reputational damage, and operational disruptions. Conversely, proactive adaptation can unlock opportunities for innovation, competitive advantage, and stronger governance. As we navigate these shifting tides, it is crucial to examine the key regulatory updates reshaping compliance in 2024 and their broader implications.
Concept & Overview
Regulatory updates in 2024 span a wide array of domains, from data privacy and environmental sustainability to financial integrity and corporate accountability. These changes are rooted in a growing recognition that traditional compliance frameworks must evolve to address modern challenges. Governments and regulatory bodies worldwide are introducing stricter rules to enhance transparency, protect consumers, and foster sustainable growth.
The core principle underlying these updates is the shift from reactive to proactive compliance. Organizations are expected to anticipate risks, embed ethical considerations into their operations, and demonstrate continuous adherence to evolving standards. This evolution reflects a broader trend toward integrated compliance, where regulatory adherence is no longer siloed but integrated into strategic decision-making processes.
Key Features & Highlights
- Data Privacy and Cybersecurity Enhancements: New regulations such as the Digital Operational Resilience Act (DORA) in the EU and state-level privacy laws in the U.S. are tightening requirements for data protection and incident reporting. Organizations must implement robust cybersecurity measures and ensure timely breach notifications.
- Sustainability and ESG Reporting Requirements: Mandatory Environmental, Social, and Governance (ESG) reporting frameworks, such as the Corporate Sustainability Reporting Directive (CSRD) in the EU, are compelling companies to disclose detailed sustainability metrics. Investors and consumers are increasingly prioritizing environmental and social responsibility.
- Financial Regulation Reforms: Updates to anti-money laundering (AML) and Know Your Customer (KYC) regulations are expanding the scope of due diligence. Financial institutions must enhance their monitoring systems to detect and prevent financial crimes effectively.
- Corporate Governance and Accountability: Stricter rules on executive accountability and whistleblower protections are being introduced. Companies are required to establish clearer governance structures and ensure that leaders are held responsible for compliance failures.
- Cross-Border Compliance Challenges: With globalization, organizations must navigate a complex web of international regulations. Harmonizing compliance efforts across jurisdictions is becoming a critical priority to avoid conflicting obligations and penalties.
Frequently Asked Questions / Pros & Cons
What are the main drivers behind the regulatory updates in 2024?
The primary drivers include technological advancements such as artificial intelligence and big data, which necessitate updated rules for privacy and security. Additionally, global challenges like climate change and financial instability are pushing regulators to implement stricter oversight. Societal demand for transparency and ethical business practices is also a significant factor.
How can organizations prepare for these regulatory changes?
Organizations should start by conducting a comprehensive compliance audit to identify gaps in current practices. Investing in employee training, leveraging technology for regulatory monitoring, and fostering a culture of compliance are essential steps. Collaboration with legal and industry experts can also provide valuable insights into specific requirements.
What are the potential benefits of adapting to new regulations?
Adapting to new regulations can enhance an organization’s reputation, build customer trust, and improve operational efficiency. It can also open doors to new markets and partnerships that prioritize compliance and ethical practices. Moreover, proactive compliance can reduce long-term costs associated with penalties and legal disputes.
What are the challenges organizations might face?
One major challenge is the complexity and volume of regulatory changes, which can overwhelm compliance teams. Resource constraints, particularly for small and medium-sized enterprises, may hinder effective implementation. Additionally, interpreting and applying regulations consistently across different jurisdictions can be difficult.
Practical Guidance & Solutions
To navigate the regulatory landscape successfully, organizations should prioritize a structured approach to compliance. Begin by mapping out the regulatory changes that directly impact your industry and operations. Assign dedicated teams to monitor updates and interpret their implications for your business.
Technology can play a pivotal role in streamlining compliance efforts. Implementing regulatory technology (RegTech) solutions can automate monitoring, reporting, and risk assessment. These tools can help organizations stay ahead of deadlines and reduce human error. Additionally, fostering a culture of compliance from the top down ensures that ethical standards are upheld at every level.
Engaging with industry associations and regulatory bodies can provide early warnings about upcoming changes. Participating in forums and workshops can also offer practical insights and best practices. For global organizations, establishing regional compliance hubs can help centralize efforts and ensure consistent application of rules.
Finally, continuously reviewing and updating compliance policies is crucial. Regulations are not static, and neither should be your approach to adhering to them. Regular audits and feedback loops can help identify areas for improvement and ensure that your organization remains resilient in the face of evolving requirements.
Conclusion
The regulatory environment in 2024 is characterized by unprecedented complexity and dynamism. As governments and organizations grapple with technological, environmental, and ethical challenges, compliance has taken center stage. The updates reshaping the landscape are not just about avoiding penalties but about building resilient, future-ready businesses.
Adapting to these changes requires more than just checkbox compliance; it demands a strategic, proactive mindset. Organizations that embrace these shifts will not only mitigate risks but also uncover new opportunities for growth and innovation. By staying informed, leveraging technology, and fostering a culture of compliance, businesses can navigate the shifting tides with confidence and emerge stronger in the years ahead.
]]>
Decoding the Fine Print: Navigating Policy Insights for Tomorrow’s Leaders
Introduction & Background
In an era where decisions shape the future of industries, economies, and societies, understanding the fine print in policies has become a critical skill for emerging leaders. Policies, whether in business, government, or technology, often contain layers of complexity that can influence outcomes in ways that are not immediately obvious. For tomorrow’s leaders, the ability to decode these nuances is not just advantageous, it is essential for making informed, strategic choices. The significance of policy insights lies in their power to reveal hidden risks, unlock opportunities, and ensure compliance while fostering innovation. Without this understanding, leaders risk overlooking critical details that could lead to costly mistakes or missed advantages. This article explores the importance of navigating policy insights effectively, offering a roadmap for those who aim to lead with clarity and confidence.
Concept & Overview
The concept of “decoding the fine print” refers to the process of carefully analyzing and interpreting the detailed terms, conditions, and clauses within policies. These policies can range from corporate contracts and regulatory frameworks to international trade agreements and digital privacy laws. At its core, this practice is about peeling back the layers of legal and technical language to uncover the true implications for stakeholders. Key principles include attention to detail, cross-disciplinary knowledge, and a proactive approach to risk assessment. Leaders who master this skill can anticipate challenges, align their strategies with regulatory expectations, and position themselves advantageously in competitive landscapes. The overview of this topic highlights its relevance across sectors, emphasizing that policy insights are not confined to legal experts but are vital for anyone with leadership aspirations.
Key Features & Highlights
- Precision in Language: Policies often use specific terminology that can drastically alter meaning. Leaders must pay attention to words like “shall,” “may,” or “unless,” as they define obligations, permissions, and exceptions.
- Hidden Clauses: Some policies contain clauses buried in lengthy documents that can have significant consequences, such as termination rights, liability limits, or data-sharing requirements.
- Regulatory Context: Policies do not exist in isolation. Understanding the broader regulatory environment helps leaders interpret how policies interact with laws and industry standards.
- Stakeholder Impact: Fine print often outlines responsibilities and benefits for different parties. Leaders must assess how these provisions affect employees, customers, partners, and investors.
- Compliance Pitfalls: Failure to recognize policy nuances can lead to non-compliance, resulting in fines, reputational damage, or legal disputes. Awareness of these risks is crucial for proactive management.
Frequently Asked Questions / Pros & Cons
What are the most common challenges leaders face when interpreting policy fine print?
One of the primary challenges is the complexity of legal and technical language, which can be difficult to understand without specialized knowledge. Additionally, policies often evolve, requiring leaders to stay updated on amendments and new interpretations. Another hurdle is the sheer volume of information, which can make it hard to identify the most critical clauses. Finally, conflicting policies or ambiguous terms can create confusion, making it difficult to determine the correct course of action.
How can leaders improve their ability to decode policy details?
Leaders can enhance their skills by investing in training programs focused on policy analysis, legal literacy, and risk management. Building relationships with legal and compliance experts can also provide valuable insights. Practicing active reading, where one breaks down complex sentences and cross-references terms, is another effective strategy. Finally, leveraging technology, such as policy management software, can help organize and simplify the review process.
Pros of mastering policy insights:
- Enhanced decision-making with a deeper understanding of potential risks and rewards.
- Improved negotiation power by identifying favorable terms and avoiding unfavorable ones.
- Stronger compliance, reducing the likelihood of legal or financial penalties.
- Increased trust from stakeholders due to transparent and well-informed leadership.
Cons of overlooking policy details:
- Exposure to unexpected liabilities or financial losses due to unnoticed clauses.
- Damage to reputation from non-compliance or unethical practices uncovered in policies.
- Missed opportunities for partnerships or growth due to misaligned strategies.
- Increased operational inefficiencies from reactive problem-solving instead of proactive planning.
Practical Guidance & Solutions
For leaders seeking to navigate policy insights effectively, the following actionable steps can serve as a starting point:
- Conduct a Policy Audit: Regularly review existing policies to identify outdated or ambiguous terms. This ensures that leadership strategies remain aligned with current requirements.
- Engage Cross-Functional Teams: Collaborate with legal, finance, and operational teams to gain diverse perspectives. This holistic approach helps uncover hidden implications that might otherwise be overlooked.
- Prioritize Transparency: When drafting or reviewing policies, use clear and concise language to minimize misinterpretation. This is especially important for policies that affect multiple stakeholders.
- Leverage Technology Tools: Utilize policy management software to streamline the review process. These tools can flag critical clauses, track changes, and provide alerts for updates or deadlines.
- Stay Informed on Regulatory Trends: Follow industry publications, attend webinars, and participate in professional networks to stay ahead of policy changes. Proactive learning reduces the risk of being caught off guard by new regulations.
- Develop a Risk Mitigation Plan: Create contingency strategies for identified risks within policies. This includes setting aside resources for potential liabilities and establishing clear communication protocols in case of non-compliance.
By implementing these practices, leaders can transform policy insights from a daunting challenge into a strategic advantage. The goal is not just to understand the fine print but to use it as a foundation for building resilient, forward-thinking organizations.
Conclusion
The ability to decode the fine print in policies is more than a skill, it is a necessity for the leaders of tomorrow. In a world where policies govern everything from data privacy to trade agreements, the details matter. Leaders who invest time and effort into understanding these nuances will not only avoid pitfalls but also uncover opportunities that others might miss. The journey to mastering policy insights begins with curiosity, discipline, and a commitment to continuous learning. As industries evolve and new challenges emerge, the leaders who thrive will be those who can navigate complexity with clarity and confidence. By embracing this challenge, tomorrow’s leaders can shape a future where informed decisions drive progress, innovation, and sustainable success.
]]>
Introduction & Background
In 2024, global policy trends are evolving at an unprecedented pace, reshaping the way nations, businesses, and individuals interact with one another. The shifting sands of international relations, economic priorities, and technological advancements are creating hidden currents that influence everything from trade agreements to environmental regulations. Understanding these trends is not just an academic exercise; it is a necessity for policymakers, corporate leaders, and citizens alike. The significance of this topic lies in its ability to illuminate the forces driving change and prepare stakeholders for the challenges and opportunities ahead. As geopolitical tensions rise and new alliances form, the landscape of global policy is becoming more complex, demanding a deeper examination of the underlying currents that shape our world.
Concept & Overview
Global policy trends refer to the collective shifts in regulatory, economic, and diplomatic approaches adopted by nations and international organizations. These trends are influenced by a variety of factors, including technological innovation, climate change, demographic changes, and shifting power dynamics among global actors. At their core, these trends reflect the evolving priorities of governments and societies as they respond to both internal pressures and external challenges. The concept of navigating these trends involves recognizing the interconnected nature of policy decisions and anticipating their ripple effects across different sectors. For instance, a policy aimed at reducing carbon emissions in one country can have far-reaching consequences for global supply chains and energy markets. By understanding the principles behind these trends, stakeholders can better position themselves to adapt and thrive in an ever-changing environment.
Key Features & Highlights
- Geopolitical Fragmentation: The world is witnessing a rise in regional blocs and bilateral agreements, as multilateral institutions struggle to maintain cohesion. Countries are increasingly prioritizing strategic autonomy over collective decision-making, leading to a more fragmented global order.
- Climate Policy Integration: Environmental considerations are becoming a central pillar of economic and foreign policies. Nations are adopting stricter regulations on emissions, investing in green technologies, and integrating sustainability into trade agreements to address the urgent threat of climate change.
- Digital Sovereignty & Regulation: The rapid expansion of digital economies has prompted governments to assert control over data flows and technological infrastructure. Policies such as the EU’s Digital Services Act and China’s data localization laws are reshaping how businesses operate across borders.
- Economic Security & Industrial Policy: Governments are increasingly adopting protectionist measures to safeguard critical industries and supply chains. Subsidies, export controls, and investment screening are being used to enhance national economic resilience in the face of global uncertainties.
- Demographic Shifts & Labor Policies: Aging populations in developed nations and youth bulges in developing countries are driving changes in immigration, education, and workforce policies. Governments are revisiting labor laws to attract talent and address skills shortages in key sectors.
Frequently Asked Questions / Pros & Cons
What are the primary drivers behind the current global policy shifts?
Several key drivers are fueling the changes in global policy trends. First, the rise of economic nationalism has led countries to prioritize domestic industries and reduce reliance on foreign supply chains. Second, technological advancements, particularly in artificial intelligence and digital infrastructure, are prompting governments to implement regulations that balance innovation with security. Third, climate change has become an existential threat, forcing policymakers to integrate environmental goals into economic and trade policies. Finally, the redistribution of global power, marked by the rise of emerging economies, is challenging the dominance of traditional Western-led institutions.
What are the potential risks associated with these policy trends?
While the shifts in global policy trends offer opportunities, they also present significant risks. One major concern is the potential for increased protectionism, which could disrupt global trade and lead to higher costs for consumers. Another risk is the fragmentation of international standards, which may create barriers for businesses operating across multiple jurisdictions. Additionally, the focus on economic security could escalate geopolitical tensions, particularly in sectors such as technology and energy. Finally, the rapid pace of technological change may outpace regulatory frameworks, leaving societies vulnerable to new forms of exploitation, such as cyber threats and misinformation.
How can businesses adapt to these evolving policy trends?
Businesses must adopt a proactive approach to navigate the changing policy landscape. This involves closely monitoring regulatory developments in key markets and diversifying supply chains to mitigate risks. Companies should also invest in compliance programs to ensure adherence to new laws, particularly in areas such as data privacy and environmental sustainability. Collaborating with industry associations and policymakers can provide businesses with insights into future trends and opportunities for advocacy. Additionally, fostering innovation and flexibility in operations will enable businesses to respond swiftly to policy changes and maintain a competitive edge.
Practical Guidance & Solutions
To successfully navigate the shifting sands of global policy trends in 2024, stakeholders must adopt a strategic and forward-thinking approach. For policymakers, this means fostering dialogue and cooperation to address shared challenges, such as climate change and cybersecurity. International organizations can play a pivotal role in mediating disputes and promoting inclusive policy frameworks that accommodate diverse perspectives. Businesses, on the other hand, should prioritize resilience by diversifying their operations and supply chains to reduce dependence on any single market or supplier. Investing in research and development will also enable companies to stay ahead of regulatory changes and capitalize on emerging opportunities.
For individuals, staying informed about global policy trends is essential for making educated decisions in an increasingly interconnected world. Engaging with local and international news sources, participating in public consultations, and supporting policies that align with long-term sustainability goals can contribute to a more stable and equitable global order. Additionally, advocating for transparent and accountable governance can help ensure that policy decisions reflect the needs and values of citizens.
Conclusion
The hidden currents of global policy trends in 2024 are reshaping the world in profound ways, offering both challenges and opportunities for those willing to adapt. From the rise of economic nationalism to the integration of climate policies, these trends reflect the complex interplay of power, innovation, and necessity. While the path forward may seem uncertain, understanding the forces at play empowers stakeholders to make informed decisions and drive positive change. By embracing collaboration, innovation, and resilience, we can navigate the shifting sands of global policy and build a more sustainable and prosperous future for all. The journey ahead is not without its obstacles, but with vigilance and determination, we can turn these challenges into catalysts for progress.
]]>Introduction & Background
In today’s fast-paced financial and business environments, understanding market shifts is no longer optional for investors, entrepreneurs, and policymakers. Markets are constantly evolving due to technological advancements, geopolitical events, and shifting consumer behaviors. The ability to read these changes accurately can mean the difference between seizing opportunities and facing unexpected setbacks. This article explores the intricate nature of market dynamics, offering readers the tools they need to navigate volatility and uncertainty with confidence.
Concept & Overview
Market shifts refer to significant changes in supply, demand, pricing, or economic indicators that alter the competitive landscape. These shifts can be triggered by internal factors such as innovation or mismanagement, or external forces like regulatory changes, natural disasters, or global crises. Recognizing the early signs of these transitions allows businesses and investors to adapt strategies proactively rather than reactively. Whether it’s a sudden drop in commodity prices or the rise of a new industry leader, understanding the undercurrents of change is essential for making informed decisions.
Strategic insights, on the other hand, are distilled interpretations of market data that guide decision-making. They combine quantitative analysis with qualitative judgment to reveal patterns that are not immediately obvious. In a world where information overload is common, the ability to filter noise and focus on actionable intelligence is a competitive advantage. This synergy between market awareness and strategic thinking forms the foundation of sustainable growth in any sector.
Key Features & Highlights
- Real-Time Data Accessibility: Modern tools and platforms provide instant access to global market indicators, enabling timely responses to emerging trends.
- Predictive Analytics: Advanced algorithms and AI-driven models help forecast future movements based on historical patterns and current signals.
- Regulatory Awareness: Keeping up with policy changes across industries ensures compliance and uncovers potential advantages or risks.
- Consumer Behavior Tracking: Monitoring purchasing trends and sentiment shifts helps businesses tailor products and marketing strategies effectively.
- Risk Management Frameworks: Implementing structured approaches to assess and mitigate risks minimizes exposure to market volatility.
- Interdisciplinary Approach: Combining insights from economics, technology, and social sciences leads to a more holistic understanding of market behavior.
Frequently Asked Questions / Pros & Cons
What are the most common signs of an impending market shift?
Early indicators often include unusual trading volumes, price divergence in related assets, or sudden shifts in sector performance. Media sentiment and insider activity can also serve as precursors. Monitoring these signals requires a combination of technical analysis and awareness of broader economic narratives.
How reliable are market forecasts and predictive models?
While no model is perfect, high-quality forecasts based on comprehensive data and robust methodologies tend to offer valuable directional insights. The reliability depends on the quality of input data, model assumptions, and the speed of adaptation to new information. Over-reliance on any single forecast can be risky, so diversifying sources is recommended.
What are the pros and cons of using AI in market analysis?
Pros: AI can process vast datasets quickly, detect subtle patterns, and operate continuously without fatigue. It reduces human bias and enables real-time decision support.
Cons: AI systems may misinterpret noise as signal, lack contextual understanding of geopolitical events, and require substantial investment in technology and expertise. Over-automation can also reduce the role of human judgment in complex scenarios.
How can small businesses stay competitive during market disruptions?
Small businesses benefit from agility and customer intimacy. Focusing on niche markets, building strong community relationships, and maintaining lean operations allows them to pivot faster than larger competitors. Leveraging digital tools for customer engagement and data collection also levels the playing field.
Practical Guidance & Solutions
To effectively navigate market shifts, start by establishing a robust monitoring system that tracks key performance indicators relevant to your industry. Use a combination of automated alerts and periodic manual reviews to stay updated. Next, build a flexible strategic framework that allows for quick adjustments in response to new data. This might include diversifying revenue streams, investing in employee training, or forming strategic partnerships to share risk.
When making decisions, prioritize scenarios over single outcomes. Develop contingency plans for both optimistic and pessimistic projections, ensuring your business can withstand sudden changes. Additionally, foster a culture of continuous learning within your organization. Encourage teams to attend industry webinars, subscribe to thought leadership publications, and participate in peer networks that discuss emerging trends.
For investors, consider adopting a long-term perspective while maintaining liquidity for short-term opportunities. Dollar-cost averaging and periodic rebalancing can help manage risk without requiring perfect timing. Always validate new strategies with real-world testing before full-scale implementation.
Conclusion
Navigating the pulse of the market is less about predicting the future and more about building resilience to change. By combining sharp analytical skills with adaptive strategies, individuals and organizations can transform uncertainty into opportunity. The key lies in staying informed, remaining flexible, and acting decisively when the moment is right. In a world where markets never stand still, those who learn to read the signals and respond with purpose will not just survive but thrive.
]]>
Introduction & Background
Investing wisely has always been a cornerstone of building wealth, but in 2024, the landscape is evolving faster than ever before. With rapid technological advancements, shifting global markets, and emerging economic trends, knowing where to put your money can feel overwhelming. The difference between financial stagnation and significant wealth growth often comes down to making the right investment moves at the right time. Whether you are a seasoned investor or just starting, understanding the top opportunities available this year could set you on a path to financial success.
This guide will explore ten powerful investment strategies that have the potential to make you rich in 2024. These moves are not just about chasing quick profits but about positioning yourself for sustainable growth in a dynamic world. From cutting-edge technologies to resilient asset classes, the options are diverse and promising for those ready to act strategically.
Concept & Overview
Investing for wealth creation in 2024 requires a blend of foresight, adaptability, and informed decision-making. The core idea is to identify sectors and assets that are poised for growth while managing risk effectively. This involves understanding macroeconomic trends, technological disruptions, and consumer behavior shifts that shape market opportunities.
The investment moves highlighted here are based on current market data, expert forecasts, and historical performance patterns. They are designed to help you diversify your portfolio, capitalize on emerging trends, and build long-term wealth. Whether through stocks, real estate, digital assets, or innovative financial instruments, the goal remains consistent: maximize returns while minimizing unnecessary risk.
Key Features & Highlights
- Artificial Intelligence and Machine Learning: Investing in companies at the forefront of AI development offers high growth potential. These technologies are transforming industries from healthcare to finance, creating lucrative opportunities for early investors.
- Renewable Energy and Green Technology: As global focus shifts toward sustainability, renewable energy stocks and clean technology firms are experiencing rapid expansion. Governments and corporations are investing heavily in this sector, driving up valuations.
- Cryptocurrency and Blockchain: Despite volatility, cryptocurrencies and blockchain-based assets continue to attract attention. Innovations like decentralized finance (DeFi) and non-fungible tokens (NFTs) are opening new investment avenues with high reward potential.
- Real Estate Investment Trusts (REITs): REITs provide a way to invest in real estate without owning physical property. They offer steady dividends and the potential for capital appreciation, making them a solid choice for income-focused investors.
- Emerging Market Stocks: Countries with fast-growing economies, such as India, Vietnam, and Nigeria, present opportunities for outsized returns. These markets are often underrepresented in traditional portfolios but can deliver strong performance.
- Healthcare Innovation: Advances in biotechnology, genomics, and pharmaceuticals are creating high-value investment opportunities. Companies developing breakthrough treatments or medical devices are particularly attractive.
- E-commerce and Digital Platforms: The shift toward online shopping continues to accelerate, benefiting companies that dominate e-commerce, digital payments, and cloud computing. These platforms are capturing market share globally.
- Precious Metals and Commodities: Gold, silver, and other commodities serve as hedges against inflation and economic uncertainty. In times of market volatility, they can preserve and grow wealth.
- Private Equity and Venture Capital: Investing in private companies or startups through venture capital funds can yield substantial returns. While risky, the potential rewards for backing the next big innovator are significant.
- Dividend Growth Stocks: Companies with a history of increasing dividends over time provide both income and capital appreciation. These stocks are ideal for investors seeking steady, reliable returns.
Frequently Asked Questions / Pros & Cons
What are the risks associated with investing in AI and machine learning stocks?
While AI stocks offer high growth potential, they also come with significant risks. These companies often operate in highly competitive markets with rapid technological changes. Valuations can be inflated based on future expectations rather than current earnings, making them vulnerable to market corrections. Additionally, regulatory challenges and ethical concerns about AI deployment can impact stock performance.
Are renewable energy investments a safe bet for long-term wealth?
Renewable energy investments can be profitable and align with global sustainability goals, but they are not without risks. Government policies and subsidies play a crucial role in this sector, and changes in regulations can affect profitability. Market volatility and technological disruptions may also impact long-term returns. However, as the world transitions to cleaner energy, the sector is likely to remain resilient and growth-oriented.
How can I start investing in cryptocurrency without losing all my money?
Cryptocurrency investments are highly speculative and volatile, so it is essential to approach them with caution. Start by educating yourself about blockchain technology and the specific cryptocurrencies you are interested in. Only invest money you can afford to lose, and consider dollar-cost averaging to spread your risk over time. Diversifying across multiple assets and using secure wallets can help protect your investments.
What makes REITs a good investment option?
REITs allow investors to gain exposure to real estate markets without the challenges of property ownership. They typically offer high dividend yields, making them attractive for income investors. Additionally, REITs are required to distribute at least 90 percent of their taxable income to shareholders, providing regular cash flow. However, they are sensitive to interest rate changes and economic downturns, which can affect their performance.
Is it wise to invest in emerging markets during economic uncertainty?
Emerging markets can offer high growth potential but come with elevated risks, including political instability, currency fluctuations, and weaker regulatory frameworks. During periods of global economic uncertainty, these markets may experience greater volatility. However, they also provide diversification benefits and the chance to capitalize on rapid economic expansion. Thorough research and a long-term perspective are crucial when investing in these regions.
Practical Guidance & Solutions
To make the most of these investment opportunities in 2024, start by assessing your financial goals, risk tolerance, and investment horizon. Diversification is key, so consider spreading your investments across multiple asset classes to reduce risk. Keep a close eye on market trends and economic indicators that may influence your choices.
For those new to investing, consider using low-cost index funds or robo-advisors to build a diversified portfolio with minimal effort. If you are more experienced, explore thematic investing in sectors like AI or renewable energy through exchange-traded funds (ETFs) or individual stocks. Always conduct thorough due diligence before committing capital, and consider consulting a financial advisor to tailor your strategy to your specific needs.
Stay informed about global events, technological advancements, and policy changes that could impact your investments. Regularly review and rebalance your portfolio to ensure it aligns with your financial objectives. Remember, patience and discipline are essential traits for successful investing.
Conclusion
Building wealth through smart investing is not about luck; it is about making informed, strategic decisions that align with your financial aspirations. The top ten investment moves outlined here offer a roadmap to potentially lucrative opportunities in 2024. From cutting-edge technologies to traditional asset classes, each option presents unique advantages for those willing to take calculated risks.
As you navigate the investment landscape this year, focus on diversification, continuous learning, and long-term planning. The financial world is full of possibilities, and by staying proactive and adaptable, you can position yourself for significant wealth growth. Start today, stay disciplined, and let your investments work for you over time.
]]>
Introduction & Background
In the past decade, artificial intelligence (AI) has shifted from being a futuristic concept to an everyday reality. Technologies that once seemed confined to science fiction are now embedded in the devices we use, the services we access, and the systems we rely on. From smartphones that predict our next word to smart home devices that adjust lighting based on our habits, AI is no longer a luxury but a standard feature. This transformation is not just about convenience, it is reshaping industries, redefining user experiences, and opening doors to possibilities previously unimaginable. The significance of this shift lies in how AI bridges the gap between human needs and technological capabilities, making systems more intuitive, responsive, and personalized than ever before.
Concept & Overview
At its core, artificial intelligence refers to the simulation of human intelligence in machines designed to think and learn like humans. These intelligent systems process vast amounts of data, identify patterns, and make decisions with minimal human intervention. Modern AI leverages advanced algorithms, machine learning, and deep learning to evolve over time, improving accuracy and efficiency with each interaction. Unlike traditional software that follows rigid instructions, AI adapts to new information, enabling it to perform complex tasks such as image recognition, natural language understanding, and predictive analysis. This dynamic nature makes AI a versatile tool across sectors like healthcare, finance, retail, and transportation, where real-time decision-making and personalization are critical.
Key Features & Highlights
- Adaptive Learning: AI systems continuously learn from user interactions and data inputs, enhancing their performance without manual updates. This ability to self-improve is foundational to applications like recommendation engines on streaming platforms and voice assistants that understand accents and dialects.
- Real-Time Processing: The ability to analyze and respond to data instantly enables applications such as fraud detection in banking, autonomous navigation in vehicles, and dynamic pricing in e-commerce. Real-time intelligence reduces delays and increases reliability in critical decision-making processes.
- Natural Language Understanding: AI-powered chatbots and virtual assistants now interpret and generate human-like language with high accuracy. This technology powers customer service automation, language translation tools, and accessibility features for users with disabilities.
- Personalization at Scale: AI tailors experiences by analyzing individual preferences, behaviors, and histories. Whether suggesting playlists, curating news feeds, or optimizing search results, personalization increases user engagement and satisfaction across digital platforms.
- Predictive Analytics: By identifying trends in historical data, AI forecasts future outcomes with remarkable precision. Industries such as supply chain management, healthcare diagnostics, and marketing use predictive models to anticipate demand, detect anomalies, and optimize resource allocation.
Frequently Asked Questions / Pros & Cons
What are the main benefits of integrating AI into everyday technologies?
AI enhances efficiency by automating repetitive tasks, reduces human error through data-driven decisions, and provides 24/7 availability. It enables personalized experiences that cater to individual needs, increases accessibility for people with disabilities, and helps businesses scale operations without proportional increases in labor costs.
Are there any privacy concerns with AI technologies?
Yes, AI systems often rely on vast datasets that may include sensitive personal information. Concerns arise over data collection practices, consent management, and potential misuse of biometric or behavioral data. Ensuring transparency, robust encryption, and adherence to privacy regulations like GDPR is essential to mitigate these risks.
How does AI impact job markets?
While AI automates routine and repetitive jobs, it also creates new roles focused on AI development, data analysis, and system oversight. The net effect varies by industry, with some sectors experiencing job displacement and others seeing growth in tech-driven employment opportunities. Continuous upskilling and reskilling initiatives are crucial to help workers adapt to the changing landscape.
Can AI systems be biased, and if so, how?
Yes, AI systems can inherit biases present in their training data or algorithms, leading to unfair outcomes in areas like hiring, lending, and law enforcement. These biases often reflect historical inequalities and can be unintentionally amplified by machine learning models. Addressing this requires diverse training datasets, algorithmic transparency, and regular audits to detect and correct discriminatory patterns.
Is AI technology accessible to small businesses?
Absolutely. Many AI tools are now offered as cloud-based services with affordable subscription models, making them accessible even to small enterprises. Platforms like chatbots, automated marketing tools, and inventory management systems empower smaller businesses to compete with larger players by improving customer engagement and operational efficiency.
Practical Guidance & Solutions
For individuals looking to leverage AI in daily life, start by identifying tasks that are time-consuming or repetitive. Tools like virtual assistants can help manage schedules, while AI-powered language models assist with writing and research. In the workplace, explore AI-driven software for data analysis, customer support, or project management to enhance productivity.
Businesses should begin with a clear objective: whether it is improving customer experience, optimizing supply chains, or enhancing product recommendations. Partnering with reputable AI vendors and investing in employee training ensures a smoother transition. Implementing strong data governance policies and conducting regular ethical reviews of AI systems helps maintain trust and compliance.
To address privacy concerns, prioritize platforms that offer end-to-end encryption and allow users to control data sharing. Transparency in how AI models operate builds user confidence. Finally, stay informed about emerging regulations and industry standards to ensure ongoing alignment with best practices in AI ethics and security.
Conclusion
AI is no longer a distant innovation on the horizon, it is here, reshaping the foundation of everyday technologies. By making systems smarter, faster, and more personalized, it brings unprecedented convenience and efficiency into our lives. While challenges such as privacy, bias, and job displacement remain, proactive strategies and ethical frameworks can guide us toward responsible AI adoption. As we move forward, the collaboration between humans and intelligent machines will define the next era of technological progress. The future is not just about what AI can do for us, it is about how we shape it to work for everyone, creating a more inclusive, efficient, and innovative world.
]]>
Introduction & Background
In today’s fast-paced regulatory landscape, businesses and individuals alike face an ever-growing maze of compliance rules. These rules, designed to ensure transparency, accountability, and fairness, often come with their own set of complexities. Whether you’re a corporate leader, a legal professional, or a small business owner, understanding and navigating these regulations is no longer optional but essential for sustainable success. The consequences of non-compliance can range from hefty fines to reputational damage, making it critical to stay ahead of the curve. This article explores creative strategies to decode and master compliance rules, transforming what often feels like a labyrinth into a structured path toward clarity and efficiency.
Concept & Overview
Compliance rules encompass a broad set of legal, ethical, and industry-specific requirements that organizations must follow to operate within legal boundaries. These rules can stem from government regulations, industry standards, or internal policies. At their core, compliance rules aim to mitigate risks, protect stakeholders, and maintain trust in business practices. However, their sheer volume and frequent updates often create confusion, leading to a need for systematic approaches to interpretation and implementation. The challenge lies not just in knowing the rules but in applying them effectively in dynamic environments.
Key Features & Highlights
- Dynamic Nature: Compliance rules are not static. They evolve with technological advancements, societal changes, and legislative updates, requiring continuous vigilance.
- Cross-Jurisdictional Complexity: Global businesses must comply with regulations across multiple regions, each with its own legal frameworks and expectations.
- Documentation and Reporting: Many compliance rules mandate detailed record-keeping and periodic reporting, adding administrative burdens to organizations.
- Risk-Based Approach: Modern compliance strategies often prioritize high-risk areas, allowing businesses to allocate resources more efficiently.
- Technology Integration: Tools like AI, automation, and data analytics are increasingly used to streamline compliance processes and reduce human error.
Frequently Asked Questions / Pros & Cons
What are the biggest challenges in understanding compliance rules?
One of the primary challenges is the sheer volume and complexity of rules, which can be overwhelming even for experts. Additionally, the language used in legal texts is often technical and ambiguous, making interpretation difficult. Another issue is the rapid pace of regulatory changes, which requires constant updating of knowledge and processes.
How can small businesses stay compliant without dedicated legal teams?
Small businesses can leverage affordable compliance software, consult industry associations for guidance, and stay informed through online resources provided by regulatory bodies. Outsourcing to compliance consultants or using pre-built compliance frameworks can also help manage the workload efficiently.
What are the pros and cons of outsourcing compliance management?
Pros:
- Access to specialized expertise without the need for in-house hiring.
- Reduced risk of non-compliance due to professional oversight.
- Time savings, allowing businesses to focus on core operations.
Cons:
- High costs associated with outsourcing, especially for long-term engagements.
- Potential loss of control over sensitive compliance processes.
- Dependence on third-party providers, which may not fully align with the business’s unique needs.
Is technology a reliable solution for compliance management?
Technology can significantly enhance compliance efforts by automating routine tasks, identifying risks, and ensuring timely reporting. However, it is not a standalone solution. Human oversight is still essential to interpret complex rules, handle exceptions, and ensure the technology is used correctly. A balanced approach combining technology and expert judgment is often the most effective strategy.
Practical Guidance & Solutions
To navigate compliance rules effectively, start by conducting a thorough assessment of your organization’s current compliance status. Identify gaps by reviewing existing processes against relevant regulations. Next, prioritize these gaps based on risk levels and resource availability. Implement a compliance management system that includes clear policies, regular training, and automated monitoring tools. Collaboration between departments is key, as compliance is not solely the responsibility of the legal or compliance team but a shared commitment across the organization.
Staying updated is another critical aspect. Subscribe to regulatory newsletters, attend industry webinars, and participate in professional networks to remain informed about changes. Consider forming a compliance committee that meets regularly to review updates and adjust strategies accordingly. Finally, foster a culture of compliance within your organization by promoting transparency and accountability at all levels.
Conclusion
Decoding compliance rules may feel like navigating a labyrinth, but with the right strategies and mindset, it becomes a manageable and even empowering process. By understanding the core principles, leveraging technology, and fostering a culture of compliance, businesses can turn regulatory challenges into opportunities for growth and innovation. Remember, compliance is not just about avoiding penalties. It is about building trust, ensuring sustainability, and creating a foundation for long-term success. As regulations continue to evolve, those who adapt proactively will not only survive but thrive in an ever-changing landscape.
]]>
Introduction & Background
The modern business landscape is evolving at an unprecedented pace, driven by technological advancements, shifting consumer behaviors, and global economic changes. Understanding the latest industry trends is no longer optional for businesses aiming to stay competitive. Companies that fail to adapt risk falling behind, while those that embrace innovation and flexibility can unlock new opportunities and sustainable growth. This article explores the pivotal trends reshaping industries today, offering insights into how businesses can navigate these changes effectively.
Concept & Overview
The concept of industry trends refers to the emerging patterns, technologies, and practices that influence how businesses operate and interact with their markets. These trends are shaped by various factors, including digital transformation, sustainability demands, and evolving workforce dynamics. At their core, these trends represent shifts in the ways companies produce, deliver, and consume goods and services. By recognizing and responding to these trends, businesses can position themselves for long-term success and resilience in an increasingly complex environment.
Key Features & Highlights
- Digital Transformation: The integration of digital technology into all areas of business is revolutionizing operations, customer experiences, and value creation. Companies are leveraging artificial intelligence, cloud computing, and data analytics to enhance decision-making and streamline processes.
- Sustainability & ESG Initiatives: Environmental, Social, and Governance (ESG) criteria are becoming central to business strategies. Consumers and investors increasingly prioritize companies that demonstrate commitment to sustainability, ethical practices, and social responsibility.
- Remote & Hybrid Work Models: The rise of remote work, accelerated by the global pandemic, has transformed workplace dynamics. Businesses are adopting flexible work arrangements to attract talent and improve employee satisfaction.
- Customer-Centric Approaches: Personalization and hyper-targeted marketing are key differentiators in today’s market. Companies are using advanced analytics to understand customer preferences and deliver tailored experiences.
- Supply Chain Resilience: Disruptions in global supply chains have highlighted the need for agility and diversification. Businesses are investing in technologies like blockchain and IoT to enhance transparency and responsiveness.
- Emerging Technologies: Innovations such as the Internet of Things (IoT), 5G connectivity, and automation are creating new opportunities for efficiency and growth across industries.
Frequently Asked Questions / Pros & Cons
What are the most significant trends impacting businesses in 2024?
In 2024, businesses are primarily influenced by digital acceleration, sustainability mandates, and the adoption of AI-driven solutions. The demand for remote work flexibility and personalized customer experiences also continues to shape industry strategies. Additionally, supply chain optimization and cybersecurity resilience are critical areas of focus.
How can small businesses adapt to these trends without large investments?
Small businesses can start by leveraging affordable digital tools, such as cloud-based software and social media platforms, to enhance productivity and reach. Collaborating with local partners or adopting modular technologies can also help minimize costs while staying competitive.
Pros & Cons: Adopting New Technologies
Pros: Increased efficiency, improved customer engagement, and access to real-time data for better decision-making.
Cons: High initial costs, potential resistance to change within teams, and the need for continuous training to keep up with rapid advancements.
Why is sustainability becoming a key driver for business success?
Sustainability is no longer just a moral obligation but a business imperative. Consumers are increasingly making purchasing decisions based on a company’s environmental impact. Investors are also prioritizing ESG-compliant businesses, as they are perceived to be lower risk and more future-proof. Moreover, sustainable practices can lead to cost savings through energy efficiency and waste reduction.
What challenges do companies face when implementing remote work policies?
Common challenges include maintaining team cohesion, ensuring data security, and managing productivity across distributed teams. Companies must invest in robust communication tools and establish clear policies to address these issues effectively.
Practical Guidance & Solutions
Navigating industry trends requires a proactive and strategic approach. Businesses should start by conducting a thorough assessment of their current operations to identify areas that need improvement or innovation. Investing in employee training programs can ensure that teams are equipped with the skills required to leverage new technologies. Additionally, fostering a culture of agility and continuous learning can help organizations adapt more quickly to changes.
For businesses looking to enhance sustainability, setting measurable ESG goals and integrating them into corporate strategies is essential. This could involve transitioning to renewable energy sources, reducing carbon footprints, or implementing ethical sourcing practices. Leveraging partnerships with sustainability-focused organizations can also provide valuable guidance and resources.
To optimize supply chains, companies should consider diversifying suppliers and adopting technologies that offer real-time visibility into logistics operations. Implementing predictive analytics can help anticipate disruptions and mitigate risks before they escalate. Furthermore, prioritizing cybersecurity measures is crucial to protect sensitive data and maintain customer trust.
Conclusion
The business landscape of today is defined by rapid change and unprecedented challenges. However, within these challenges lie immense opportunities for growth and innovation. By staying informed about industry trends and adopting a forward-thinking mindset, businesses can not only survive but thrive in this dynamic environment. The key to success lies in embracing change, investing in the right technologies, and aligning business practices with the evolving expectations of consumers, employees, and stakeholders. As we move forward, the ability to adapt and innovate will remain the cornerstone of enduring success.
]]>