At $4.08 per share against $5.85 in trailing 12-month EPS, Exxon runs a 69.74% earnings payout ratio. Fiscal year 2025 free cash flow of $26.13 billion easily covered the dividend, and interest coverage of 56.28x is extraordinary by any measure. CEO Darren Woods highlighted “an industry-leading balance sheet that gives us unmatched flexibility.” Rating: Very Safe.
Once the paychecks stop, most retirees judge a portfolio by one number: how much cash shows up each quarter without selling a share. Blue-chip companies with long dividend records answer that question in up markets and down markets alike, because their payouts come from operating cash flow and not from the stock price.
Here’s what a $50,000 investment in these four dividend names would produce. The total commitment is $200,000, and at forward yields, it produces more than $5,400 in annual passive income. All four pay quarterly, so the checks arrive on a predictable schedule.
Coca-Cola
- Stock #4: Coca-Cola (NYSE:KO)
- Forward Yield: 2.30%
- Shares for $50,000: 541.95
- Annual Passive Income: ~$1,148.93
Coca-Cola sells concentrate to bottling partners in more than 200 countries and territories. That capital-light model produced a 32.9% comparable operating margin in today’s third-quarter results. Adjusted EPS of $0.91 beat the $0.88 estimate, and revenue rose 7.4% to $13.38 billion.
The yield is the lowest of the four because investors pay a premium for that stability. The stock trades at a P/E of 30 and has gained 34.54% year to date. On safety, management raised its 2026 free cash flow outlook to at least $13.0 billion, well above the about $9.1 billion the $2.12 annual dividend requires. Coca-Cola is a Dividend King with 60+ consecutive years of increases.
Merck
- Stock #3: Merck (NYSE:MRK)
- Forward Yield: 2.43%
- Shares for $50,000: 356.66
- Annual Passive Income: ~$1,212.64
Merck develops medicines, vaccines, and animal health products. KEYTRUDA and KEYTRUDA QLEX brought in $8.37 billion in the second quarter, when total revenue rose 5.1% to $16.61 billion. The yield shows patent risk, since KEYTRUDA loses exclusivity late this decade. On the August call, chief executive Robert Davis called that period “more of a hill than a cliff.”
At first glance, the dividend looks stretched: 2026 non-GAAP EPS guidance of $2.66 to $2.76 falls below the $3.40 annual payout. That guidance, however, includes one-time charges of $3.62 per share for Cidara and $2.31 per share for Terns. Adding those back, the dividend uses about 39% of underlying earnings. The quarterly rate rose to $0.85 from $0.81. One risk to keep an eye on: the shares fell after leaked cancer data disappointed investors on October 22.
Chevron
- Stock #2: Chevron (NYSE:CVX)
- Forward Yield: 3.08%
- Shares for $50,000: 216.13
- Annual Passive Income: ~$1,538.86
An integrated major, Chevron spans production, refining, and chemicals. The Hess acquisition raised worldwide output 20% to 4,070 MBOED. Energy stocks yield more because commodity swings make earnings volatile. That said, Chevron’s yield has fallen as the stock climbed 56.01% year to date, with Brent at $104 versus $68 a year earlier.
Coverage is strong. Second-quarter free cash flow of $18.10 billion topped the about $13.96 billion the dividend costs over a full year. Chevron also cut debt by $8.41 billion and covers interest 13.7x. Wirth said Hess cash flow has been “roughly double the incremental dividends.” The main exposure is oil prices, because affiliate distribution guidance assumes $70 Brent.
McDonald’s
- Stock #1: McDonald’s (NYSE:MCD)
- Forward Yield: 3.10%
- Shares for $50,000: 200.87
- Annual Passive Income: ~$1,550.70
Franchisees run about 95% of McDonald’s 46,028 restaurants, so the company collects rent and royalties. Its year-to-date adjusted operating margin is 46.9%. McDonald’s has the top yield in this group mostly because the stock has dropped 16.96% year-to-date while a squeezed consumer held global comparable sales growth to 1.3%.
The payout still looks well covered. Second-quarter adjusted EPS of $3.38 covered the $1.86 quarterly dividend about 1.8 times, and interest coverage is 7.8x. The board then raised the dividend to $1.93, payable December 15, 2026.
Income Breakdown for a $200,000 Portfolio
| Name | Forward Yield | Annual Dividend Income |
|---|---|---|
| Coca-Cola | 2.30% | $1,148.93 |
| Merck | 2.43% | $1,212.64 |
| Chevron | 3.08% | $1,538.86 |
| McDonald’s | 3.10% | $1,550.70 |
| Total | 2.73% | $5,451.13 |
Together, the four positions generate $5,451.13 in annual passive income on a $200,000 investment, a combined yield of 2.73%. McDonald’s contributes $1,550.70, Chevron adds $1,538.86, Merck adds $1,212.64, and Coca-Cola rounds out the group with $1,148.93.
All four companies have raised their quarterly payouts over the past year, so income grows without adding new money. Reinvesting each quarterly check buys more shares, and those shares earn the next, larger dividend. Over a long holding period, that compounding is what turns a modest starting yield into a much bigger stream of retirement cash (we laid out the full mix, payout calendar, and withdrawal order for turning savings into a paycheck in a free guide here).
The post 4 Blue-Chip Dividend Stocks That Could Turn $200,000 Into Annual Retirement Income appeared first on 24/7 Wall St..
]]>America’s emergency oil stockpile and its gasoline bill each crossed a political line on October 26, 2026. The Energy Department reported that Strategic Petroleum Reserve crude stocks fell to 282.6 million barrels, the lowest since October 1982. AAA data showed regular gasoline has averaged $3.472 a gallon during Trump’s current term, compared with $3.471 under Biden.
Crude moved little, as Brent settled down 91 cents, or 0.8%, at $115.81 a barrel, and WTI fell $1.51, or 1.46%, to $101.76.
United States Oil Fund (NYSEARCA:USO) slid 1.97% to $166.19. State Street Energy Select Sector SPDR ETF (NYSEARCA:XLE) rose 0.43% to $69.63.
The Finland-based Center for Research on Energy and Clean Air, an advocacy nonprofit that wants countries to move off fossil fuels, estimates US consumers have paid an extra $471 each for fuel since the Iran war began February 28. The worldwide figure is about $60 per person. Americans account for $160 billion of the $468 billion in extra spending across the 169 countries studied.
How Fast the Emergency Cushion Is Draining
The reserve is there to cover supply shocks, so its size tells traders how much buffer Washington has left. The drop comes from a committed withdrawal of 172 million barrels. On top of that, the department approved an emergency exchange of up to 400,000 barrels to cover a disruption at Phillips 66 (NYSE:PSX) in Lake Charles, Louisiana.
The reserve held 415.442 million barrels in the week ending March 6 and 282.683 million barrels in the week ending October 16. That is a drop of about 133 million barrels, or roughly 32%, in about seven months. The last time the level was lower was the week ending October 15, 1982, at 280.802 million barrels.
The reserve actually grew under Trump at first, from 394.566 million barrels in January 2025, until the war release began. Because less oil is left to soften the next shock, traders are likely to keep paying extra for crude.
Diesel Carries the Real Gap at the Pump
The gap in gasoline averages between the two terms is small, while diesel’s is wider: it has averaged $4.343 under Trump against $4.078 under Biden, and it set a record of $6.5276 on September 22.
Regular averaged $4.2858 on October 26. That is up about 40% from $3.0532 a year earlier. It is also down from $4.4874 a month earlier and well below the $5.0165 record set June 14, 2022.
White House spokeswoman Taylor Rogers said, “Once this conflict comes to an end, gas prices will drop drastically.” Voters have shown less patience, and Trump’s approval hit 31% in a Reuters/Ipsos poll published October 19, with 23% approving of his handling of the country. Year-ahead inflation expectations rose to 4.7% from 3.4% in February.
At an October 24 rally in Perry, Georgia, Trump said the U.S. profits from the war even though drivers struggle at the pump: “I don’t give a damn, I’m gonna say it: We’re making a frickin fortune.”
Reality Check on the Two Funds
USO holds near-month WTI futures contracts. That means it takes on roll risk each time it replaces expiring contracts, and it would drop fastest on a ceasefire or a policy-driven fall in crude. It trades near the top of its $65.99 to $169.96 yearly range after a 127.15% one-year return.
XLE sits just under its $69.86 high. Its biggest holdings as of June 30 were Exxon Mobil (NYSE:XOM) at 22.67% and Chevron (NYSE:CVX) at 16.09%. Those companies produce cash flow and shareholder returns regardless of what the futures curve does, although they still fall when oil does.
What Could Pull USO Lower Before the Midterms
Brent is roughly double its late-2025 spot range of $61 to $63, so USO already reflects the war. The White House is promising lower prices ahead of the November 3 midterms, and the Fed announces its rate decision on October 28.
Diesel near $6.3492 is likely weighing on demand. A ceasefire would take the war premium out of the front-month contracts USO holds faster than anything else could.
XLE carries less of that risk. Producers can likely handle lower crude prices, so a peace deal would cut their earnings without hitting the fund the way it would hit a futures fund.
If USO closes above its $169.96 high before November 3, the market would be pricing in a longer war than this analysis assumes.
The post America’s Emergency Oil Reserve Is at a 1982 Low, and Gas Is Costlier Than Under Biden appeared first on 24/7 Wall St..
]]>Retirees seeking double-digit income usually have to choose between a high yield and a dividend they can trust. The four ultra-high-yield names below close some of that gap. Core earnings, long distribution records, or both back their payouts. Even the group’s lowest yielder pays about 10.22% on its latest quarterly payout at today’s price. The list runs from the strongest dividend coverage to the weakest, so you see how safe each payout is before you see the yield.
Hercules Capital: An 11% Yield With Coverage to Spare
Hercules Capital (NYSE:HTGC) lends to venture-backed technology and life sciences companies. It pays $0.47 per quarter, split into a $0.40 base and a $0.07 supplemental. At $16.42, that works out to a yield of about 11.45%.
Hercules has the best coverage in this group. Net investment income covered the base distribution by 125% last quarter and 120% the quarter before. Second-quarter EPS of $0.50 exceeded the full payout, including supplemental. The portfolio is 97.8% floating rate and 86.8% first-lien senior secured, so Hercules gets paid first if a borrower runs into trouble.
Net asset value per share rose to $12.15. Hercules also locked in longer-term funding by issuing $325 million of 6.300% notes due July 2031. The regular distribution has been $0.47 at every ex-dividend date since early 2025.
For income investors, growth is the draw. First-half originations hit a record $2.74 billion (+35.6% year over year), and management expects its core yield to stay between 12.0% and 12.5% through year-end. The stock trades at a trailing price-to-earnings (P/E) of about 8.
The concern is credit drift. The weighted average credit grade fell to 2.17 from 2.11, and non-accruals ticked up. If losses keep building, the variable supplemental is the first payout piece that could shrink.
Ares Capital: 68 Straight Quarters of Stable or Rising Payouts
Ares Capital (NASDAQ:ARCC) is a business development company that lends to middle-market firms. It pays $0.48 per quarter, for a yield of about 10.28% at $18.68.
Coverage is tight but well protected. Core EPS was $0.47 in each of the last two quarters, just short of the payout. Behind that sits roughly $988 million, or $1.38 per share, of spillover income that can be paid out later. Over the past 12 months, core earnings exceeded the regular dividend, and $0.15 per share of net realized profits added further support. Leverage is 1.12x net of cash, inside the company’s target range of 0.9x to 1.25x, and liquidity is about $6 billion. Ares has paid stable or rising regular dividends for 68 consecutive quarters. CEO Kort Schnabel said on the second-quarter call, “We continue to believe ARCC’s current regular dividend appropriately reflects our long-run underlying earnings power.”
The portfolio is spread across 619 companies, and no single investment is more than 1.3% of the total. The stock trades at a price-to-book ratio of 0.99 and a forward P/E of about 10, so buyers are paying roughly book value for a lender that, according to management, has grown net asset value (NAV) per share by more than 30% since inception.
The concern is credit. Non-accruals rose to 2.4% at cost from 1.8% at the end of last year, and $183 million of net unrealized losses cut GAAP EPS to $0.24. Management notes that non-accruals are still below the company’s historical average of about 3%.


Hess Midstream: A Payout Raised Every Quarter Since 2017
The latest Hess Midstream (NYSE:HESM) quarterly distribution was $0.7888. That payout has risen in every quarter from 2017 through the most recent one, up from $0.2703 at the start of that run. The partnership earns fees on pipelines and processing plants and generated trailing EBITDA of $1.2255 billion. It trades at an EV/EBITDA multiple of 6.96.
Trailing distributions of $3.087 are higher than GAAP EPS of $2.90. That is common for asset-heavy midstream partnerships, where large depreciation charges make GAAP earnings look smaller than the cash the business brings in. The bigger change came in October. Chevron (NYSE:CVX) agreed to a restructuring in which Hess Midstream buys Chevron’s DJ Basin gathering and storage assets, Chevron returns its stake in Hess Midstream, and in exchange receives lower Bakken tariffs starting in 2027.
In return, the deal extends its contracts well into the next decade (per the deal terms). The payout will keep rising through year-end and then hold flat through 2027. The units fell 21.16% over the past month on the news.
The bull case is that fewer units outstanding make a frozen payout cheaper to fund in total. Longer contracts make the cash flow more predictable, and the company is set to become independent with a fully elected board by 2028 (per the restructuring announcement). At $30.88, the yield is about 10.22%.
The concern is that the adjustment lowers the company’s 2027 earnings outlook. That puts the distribution growth story on hold until the new contracts prove what they can earn.


Starwood Property Trust: A 15% Yield Held at $0.48 Since 2014
Starwood Property Trust (NYSE:STWD), a commercial mortgage real estate investment trust (REIT), has paid $0.48 every quarter from 2014 through the latest declaration. At a price of $12.52, the yield is about 15.34%, the highest of the four.
Coverage is the weak spot. Distributable earnings were $0.40 per share last quarter and $0.39 the quarter before, and GAAP EPS was just $0.01. The balance sheet gives management time to fix that. $2.1 billion of corporate debt deals drove the weighted average maturity out to 3.7 years, and total assets reached a record $31.8 billion.
The bull case is a deep discount. The stock trades at 0.837 times book value of $17.54 and is down 23.84% this year. Starwood deployed $6.7 billion through July, generating double-digit returns on equity. It also plans to resolve about $900 million of underperforming assets by year-end, freeing up capital to lend again. CEO Barry Sternlicht has pointed to improving real estate fundamentals.
The concern is that the dividend depends on those workouts. Until distributable earnings reach the payout, keep an eye on the third-quarter earnings report for progress on the problem loans.
Double-Digit Yields, Different Levels of Safety
All four pay more than 10% at current prices, but safety varies widely across the group. Hercules and Ares back their payouts with earnings coverage, spillover income, and diversified loan books. Hess Midstream brings a long record of increases that is now heading into a planned freeze. Starwood offers the biggest check and the deepest discount to book, and it needs its loan workouts to succeed to keep that dividend covered. Double-digit yields always come with a shortlist of things that could go wrong, and we outlined the seven warning signs that a big payout is about to be cut in a free report here.
The post 4 Safe-Money Stocks Yielding 10% That Savvy Boomer Investors Are Quietly Buying appeared first on 24/7 Wall St..
]]>Retirees who live off a portfolio watch one number more than any other: the cash that lands in the account each quarter. Split $100,000 equally across three large-cap dividend payers, about $33,333.33 in each, and forward dividend rates would produce about $3,973.89 in annual passive income. That is more than $3,950 a year from a single six-figure investment, a combined yield of 3.97%.
The three companies work in pharmaceuticals, energy, and tobacco. Each answers to a different set of forces (drug patents, crude prices, and nicotine demand), so the income rests on cash flows that have little to do with one another. None of these payouts is guaranteed. Boards set dividends, and business results can change them. Below is what a $33,333.33 stake in each name would generate, using forward yields based on share prices from the October 26, 2026 session.
Chevron
- Stock #3: Chevron (NYSE:CVX)
- Forward Yield: 3.06%
- Shares for $33,333.33: 143.49
- Annual Passive Income: ~$1,021.62
Chevron is an integrated supermajor. It produces oil and gas in the Permian Basin, the Gulf of America, Guyana, and Kazakhstan, then refines and sells fuels, lubricants, and chemicals. Its yield comes from a mature, cash-rich business that returns capital through a steady dividend plus buybacks. The forward payout is $7.12 per share. The yield has fallen because shares are up 56.66% year to date.
Coverage looks solid. Second-quarter adjusted EPS came in at $6.06 against a $1.78 quarterly dividend, and the quarter produced $18.1 billion of free cash flow. Chevron also paid down $8.4 billion of debt and bought back $3.1 billion of stock. Its payout rose from $1.71 to $1.78 per quarter in 2026. Risk: oil prices drive much of that cash flow. Brent averaged $104 per barrel versus $68 a year earlier, and a reversal would squeeze free cash flow.
Philip Morris International
- Stock #2: Philip Morris International (NYSE:PM)
- Forward Yield: 3.18%
- Shares for $33,333.33: 165.44
- Annual Passive Income: ~$1,058.83
Philip Morris sells Marlboro outside the U.S. and runs a fast-growing smoke-free business built on IQOS, ZYN, and VEEV. Smoke-free products made up more than 40% of third-quarter net revenue. The yield reflects the tobacco discount investors apply to the stock, combined with a policy of raising the dividend every year. The latest increase lifted the quarterly payout to $1.60 from $1.47.
Against 2026 adjusted EPS guidance of $8.29 to $8.44, the $6.40 forward dividend works out to a payout ratio of about 77% at the midpoint. Expected operating cash flow of about $13.5 billion is well above planned capex of $1.4 to $1.6 billion. Net debt to adjusted EBITDA fell to 2.17x from 2.53x. Risk: management expects operating income growth to land toward the middle or lower half of its range because of geopolitical cost impacts and the U.S. investment ramp-up.
Pfizer
- Stock #1: Pfizer (NYSE:PFE)
- Forward Yield: 5.68%
- Shares for $33,333.33: 1,100.84
- Annual Passive Income: ~$1,893.44
Pfizer develops and sells prescription medicines and vaccines, including Eliquis, Prevnar, Vyndaqel, and Padcev. Its high yield reflects years of pressure: COVID product sales collapsed, with Paxlovid down 95% operationally, and the company faces patent expirations. Even after a 27.92% year-to-date rise, the stock still yields well above the other two.
The $1.72 annual dividend equals about 59% of the midpoint of confirmed 2026 adjusted EPS guidance of $2.80 to $3.00. Pfizer has also raised its 2026 revenue guidance midpoint by $500 million. The quarterly payout rose from $0.41 in 2023 to $0.43 and has not been cut in the period shown. Risk: generic and biosimilar competition is expected to cost about $1.1 billion in 2026 revenue, and no buybacks are planned while the company reduces debt.
Income Breakdown Across All Three Positions
| Name | Forward Yield | Annual Dividend Income |
|---|---|---|
| Chevron | 3.06% | $1,021.62 |
| Philip Morris International | 3.18% | $1,058.83 |
| Pfizer | 5.68% | $1,893.44 |
| Total | 3.97% | $3,973.89 |
These 3 positions together generate $3,973.89 in annual passive income on a $100,000 investment, a combined yield of 3.97%. Chevron contributes $1,021.62, Philip Morris adds $1,058.83, and Pfizer accounts for $1,893.44.
All three pay quarterly, so the income arrives on a regular schedule. Pfizer’s next payment is due December 7, 2026. For someone covering monthly bills, that steady flow of cash from three unrelated industries can be worth as much as the yield. Investors should watch payout coverage each quarter, since it is the first sign of whether the income will hold up.
The post How Much Retirement Income Could $100,000 in These 3 Dividend Stocks Generate? appeared first on 24/7 Wall St..
]]>Wes Moss has raised his retirement happiness target. Moss said during the October 20 Ask An Advisor section of The Clark Howard Podcast that his updated research for The Retire Sooner Method shows that noticeably higher happiness relative to the baseline “starts at a million” in liquid savings. That includes 401(k), 403(b), IRA, Roth and brokerage money. Reaching that level, he said, gives retirees “a ton of peace of mind around that and what that money can produce in income.”
In his older book, Moss said, “the inflection point in the old book was at 500k.” Moss added that after inflation, the old $500,000 mark is “probably 800 today.” Back in April, he put the target this way: “We want to get to a million dollars in liquid assets. We want $100,000, let’s say, in retirement income.” So how much income can Moss’s $1 million actually produce?
Moss’s Yield Ladder Puts a Price on Peace of Mind
Moss uses what he calls a yield ladder. Each step pays more income and takes more risk. On September 29, Moss estimated the S&P 500 yields about 1.2%, while utility ETFs yield around 3%. Moss said big energy companies yield closer to 4% to 4.5%, and Moss placed REITs and closed-end funds in the 7% to 8% range. He calls that income “permission, license to feel okay about spending.”
Here is how six real holdings measure up, using their annualized forward payouts and October 23 prices:
| Holding | Current Yield | Annual Income on Moss’s $1 Million |
|---|---|---|
| SPDR S&P 500 ETF Trust (NYSEARCA:SPY) | 1.0% (trailing) | $9,978 |
| Utilities Select Sector SPDR Fund (NYSEARCA:XLU) | 2.8% (trailing) | $28,463 |
| Exxon Mobil (NYSE:XOM) | 2.2% | $22,488 |
| Chevron (NYSE:CVX) | 3.1% | $30,526 |
| Realty Income (NYSE:O) | 5.7% | $57,268 |
| PIMCO Dynamic Income Fund (NYSE:PDI) | 18.5% | $184,906 |
Energy’s Rally Shrank the Middle Rung
The SPDR S&P 500 ETF Trust is the low step, paying $7.58 per share over the trailing 12 months. The Utilities Select Sector SPDR Fund lands close to Moss’s 3% estimate.
The energy step has fallen below Moss’s range because prices ran ahead of payouts. Exxon Mobil is up 55.27% year to date and Chevron is up 57.27%. Both payouts are still rising. Exxon’s quarterly dividend went from $0.95 in 2024 to $1.03 in 2026, and the company plans $20B in buybacks this year. Chevron raised its payout to $1.78 per quarter as Brent averaged $104/BBL vs $68/BBL a year earlier. Anyone buying energy stocks for income today gets a lower starting yield than Moss’s ladder suggests.
Top Rungs Pay Monthly, With Very Different Risk
Realty Income has declared 673 consecutive monthly dividends, and its second-quarter SEC filing marked its 115th consecutive quarterly dividend increase. Occupancy stands at 98.8%, and 2026 AFFO guidance was raised to $4.44-$4.45 per share. That easily covers the $3.258 annualized dividend.
PIMCO Dynamic Income Fund yields more than twice the top of Moss’s range. Its $0.2205 monthly distribution has held steady since 2023, but shares have fallen 10.09% over the past year. A yield that high can signal that the market sees elevated risk in the fund’s credit portfolio. Moss has also said his ladder moves “into other areas, bonds and other specialty categories, so that we’re not leaning in on these ultra-high-yielding stocks.”
What a Blended Ladder Means for Retirees
Among the five lower-yielding holdings, only Realty Income produces more than $50,000 on Moss’s $1 million. For most retirees, that leaves Moss’s $100,000 target dependent on Social Security, pensions, or a blend of steps. Spreading money across the ladder gives up some yield in exchange for not relying on any single payer (we walked through how to build a dividend ladder that funds retirement without touching the principal in a free guide). Climbing higher brings in more cash each year, but the principal is less stable.
The next milestones are close. PDI pays on November 2, SPY on October 30, and Realty Income on November 13. Exxon and Chevron will show in their next announcements whether payout growth can keep up with their share prices.
The post Wes Moss: Retirement Happiness “Starts at a Million” in Liquid Savings appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) reports third-quarter results on Oct. 30, and the stock is up 57.27% year to date. Analysts see a steep earnings rebound from a weak year-ago quarter. What I want to know is how much of that is already in the share price.

Record Volumes Meet Triple-Digit Brent
Last quarter, Chevron posted adjusted EPS of $6.06, its 7th consecutive consensus beat. Revenue rose 51.4% year over year to $67.20 billion as Brent averaged $104 per barrel versus $68 a year earlier. Production climbed 20% to 4,070 MBOED.
The quarter threw off a lot of cash. Free cash flow reached $18.10 billion, and Chevron cut total debt by $8.41 billion. Management also hit its $3 billion structural cost-reduction target six months early and captured $1.5 billion in Hess synergies.
Since then, shares have gained 13.48% in a month to $233.21. Analysts have raised their third-quarter EPS estimate from $4.0094 90 days ago to $4.8878.

Consensus Estimates Point to a Massive Rebound
| Metric | Consensus | Year-Ago Actual | YoY Growth |
|---|---|---|---|
| Q3 2026 EPS | $4.8878 | $1.85 | 164% |
| Q3 2026 Revenue | $60.67 billion | $48.17 billion | 26% |
| FY 2026 EPS | $17.2857 | $6.63 | 161% |
| FY 2026 Revenue | $239.51 billion | $189.03 billion | 27% |

Refining Cracks and Kazakhstan Flows Will Set the Tone
Downstream made $4.87 billion last quarter, up from $737 million a year earlier. CEO Mike Wirth said “products are tighter than crude globally, which is why cracks have widened,” and he expected upward pressure on product pricing into the third quarter. The key question is whether diesel shortage kept refining margins strong.
Tengizchevroil (TCO) is the second swing factor. Its output rose 170,000 barrels a day versus the first quarter, and affiliate distributions came in at about $3 billion. Those barrels depend on the CPC pipeline through the Black Sea. On that risk, Wirth said, “I don’t think an intended, extended shutdown is a highly likely scenario.”
You should also look for an update on Project Kilby, the 2.67 gigawatt power deal with Microsoft (NASDAQ:MSFT). Management targeted a final investment decision later this year and said it was in advanced talks on more projects. Any delay would raise the execution concerns that already hang over Venezuela and Iraq.
Finally, capital discipline matters. Chevron guided full-year capex to the lower end of its $18 billion to $19 billion range. Holding that line while prices stay high would support continued debt reduction and buybacks.
Strong Numbers Already Sit in the Share Price
The stock trades at about 13x full-year EPS consensus, and the options market is bullish with a put/call ratio of 0.19. Recent history should moderate that optimism. After a 45.56% first-quarter beat, shares fell 4.73% within a week. If Chevron hits its numbers, management’s outlook for cash flow durability once oil prices cool will likely decide where the stock goes next.
The post Chevron Eyes 150% EPS Jump on Oct. 30 — But Are the Risks Already Priced In? appeared first on 24/7 Wall St..
]]>President Trump addressed a midterm rally at the Guardian Centers in Perry, Georgia, on Saturday, Oct. 24, and said the US is “making a freaking fortune” on oil, according to Newsweek. He said the country is making “hundreds of billions” because buyers are coming to Texas, Oklahoma and Louisiana, that advisers warned him not to mention it because people pay more at the pump, and that he doesn’t “give a damn” about the criticism.
On Oct. 14 in Bullhead City, Arizona, he said “we’re making a fortune,” citing Texas, Oklahoma and North Dakota, per Common Dreams. On Aug. 3, ABC7 reported, he said Chevron (NYSE:CVX) and Exxon Mobil (NYSE:XOM) “made too much money” and should give some back.
Where the Data Agree With Trump
EIA data show US exports of crude oil and petroleum products hit a record 13,610 thousand barrels a day in April, about 13.6 million, up 15% from March’s record. Crude exports reached about 5.6 million barrels a day, 21% above the prior record, per the EIA, as Strait of Hormuz disruptions sent buyers to US supply.
NBC reported Exxon’s second-quarter profit doubled to $14.53 billion and Chevron’s nearly quadrupled to $12.07 billion, about $26.6 billion combined by our sum. Brent crude rose from about $70 to above $100 for much of March to May and peaked at $126, per NBC.
Exports Have Retreated Since the Spring Peak
Monthly EIA totals slipped to 13,540 thousand barrels a day in May, 12,540 in June and 11,410 in July, the latest month reported. The EIA’s crude export average alone peaked. The four-week average hit 5,571 in the week ending May 15, fell to 3,391 in the week ending Aug. 7 and stood at 4,087 in the week ending Oct. 16, near the pre-surge 4,084 of the week ending March 6.
What Households Pay for the Windfall
Regular gas averaged $4.28 a gallon as of Oct. 19, up $1.22, or 40%, from a year earlier, per EIA data on FRED. Analyst Patrick De Haan estimated Americans were spending about $250 million more per day on gasoline than a month earlier, more than $1.5 billion a week, IBTimes reported. A New York Times/Siena poll found 73% of likely voters disapprove of Trump’s handling of gas prices. Export revenue goes to producers and exporters; households pay the pump price.
Net Effect: A Modest Drag on Growth
A June 23 Dallas Fed model found a 15% global oil supply disruption cuts annualized US real GDP growth by about 0.3 points. Its working paper puts fourth-quarter 2026 US output down about 0.1%, 0.2% or 0.3% for closures lasting one, two or three quarters, while rest-of-world output falls about 1.7 points annualized. Higher income for US producers partly offsets lost non-oil output. These are model estimates that leave producer gains and consumer spending unmeasured. The US has been a net oil exporter since late 2019, and oil spending fell from nearly 8% of GDP in 1980 to about 3% in 2024, per the Dallas Fed.
In April, EY-Parthenon’s Gregory Daco projected the war could cut 2026 GDP growth by 0.3 points, to 1.8%, CBS reported, mentioning March inflation of 3.3%, the highest since May 2024. Cato’s Scott Lincicome said PCE inflation could reach 4% by year-end. Since then, BEA data show real GDP grew 2.5% in the first quarter and 2.2% in the second, and August PCE inflation was 3.42%, with energy prices up 16.85% from a year earlier.
A Rough Estimate at the April Peak
By a rough 24/7 Wall St. estimate, April’s pace of about 13.6 million barrels a day annualizes to about 4.96 billion barrels. At $30 to $35 of added price per barrel, that implies about $149 billion to $174 billion a year in added export revenue. It reflects the peak month only: exports have since fallen, they mix products priced differently, and the US still imports crude.
White House Response and What to Watch
Per CBS, White House spokesperson Kush Desai responded. He called the disruptions “temporary” and said the economy “remains on a solid trajectory.” Democrats in Congress have proposed a windfall profits tax on large producers, which Exxon’s CEO called short-sighted, NBC reported. Next up: the GDP and PCE inflation releases, EIA’s August export data, and any movement on a windfall tax.
The post Trump Says “We’re Making A Freaking Fortune” From The Iran War’s Oil Spike. Here’s What The Economic Data Actually Show appeared first on 24/7 Wall St..
]]>If you want to turn a portfolio into an $8,300 monthly paycheck, that means producing $99,600 a year in cash. To achieve this goal, you’ll need a solid plan, likely built on a mix of dividend stocks, real estate investment trusts (REITs), business development companies (BDCs, lenders to midsize private firms), and covered-call ETFs. At the end of the day, one formula will drive everything: annual income divided by yield equals the capital you need.
Sleep-at-Night Tier Needs About $2.85 Million
At a 3.5% yield, $99,600 divided by 0.035 is roughly $2,846,000. That is the biggest check, and it buys the most durable income. To get that income, you’ll start with a name like Chevron (NYSE:CVX), which yields about 3.1% on its $7.12 forward dividend. Its quarterly payout rose from $1.51 in 2023 to $1.78 in 2026, up about 18%. Oil prices drive that cash, and Brent ran $104 a barrel versus $68 a year earlier.
Agree Realty (NYSE:ADC) pays monthly and yields about 4.9%. Its monthly dividend rose to $0.271 from $0.247 in early 2024, roughly 10% higher. Agree owns 2,825 properties at 99.8% occupancy, leased largely to national retailers.
Middle Ground: $1.66 Million at 6%
At 6%, $99,600 divided by 0.06 is $1,660,000. This range covers preferred shares, high-dividend equity funds, and blue chips like a large U.S. telecom carrier, which yields about 6.3% with shares near $45.
That carrier raised its 2026 adjusted EPS guidance to $4.99-$5.04 and targets buybacks of up to $4.5 billion. The catch is slow growth. Its quarterly dividend rose from $0.69 to $0.7075, barely keeping up with inflation, while capital spending runs $16.0 to $16.5 billion a year.
Maximum Income: $830,000 to $996,000
At 10%, $ 996,000 divided by 0.10 is $ 9,960,000. At 12%, it equals $830,000.
- NEOS S&P 500 High Income ETF (CBOE:SPYI) yields about 11.6% by selling S&P 500 options. Its latest monthly payout of $0.5087 fell from $0.5338 the month before.
- The Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD) yields about 9.2% on a forward basis. Payouts this year ranged from $0.2964 to $0.4088, and several 2017 checks were under $0.10.
- Ares Capital (NASDAQ:ARCC) yields about 10.3%. Its $0.48 quarterly dividend has held flat since 2023, but net asset value per share fell from $ 19.94 to $ 19.35, and non-accruals rose to 2%. In 2009, Ares cut its payout from $0.42 to $0.35.
Funds using covered calls give away upside in exchange for premium. Payouts follow market volatility, so the check you plan around today can shrink next month.
Why the Smallest Yield Can Win
Income that grows 8% a year doubles in about nine years. A conservative portfolio throwing off $99,600 today would pay roughly $199,100 in year nine. The $830,000 aggressive portfolio pays the same $99,600 in year one and, at best, the same amount a decade later. Of course, don’t forget that by then, rising prices have eaten into it, and a weak credit market or volatility can shrink it further, so choosing the right strategy matters a great deal.
One example mix puts 20% in SPYI, 15% each in XYLD, ADC and ARCC, 10% each in Chevron and the telecom carrier, and 15% in a broad high-dividend index fund. The high payers cover today’s bills, while the growers lift the income over time.
Three Moves Before You Build It
- Price your spending after tax. Most REIT and BDC payouts are taxed as ordinary income, which has higher rates than qualified dividends. A $99,600 gross target can leave you short once taxes come out, so solve for net income first.
- Check each holding’s 10-year record. Put total return next to distribution history. A fund whose payout has drifted lower over a decade is shrinking your future income, even if its yield looks high today.
- Keep a cash buffer outside the bond market. Holding a year of spending in a money market fund means a distribution cut in the aggressive allocation never forces you to sell shares at a bad price.
The post How to Build $8,300 a Month in Dividend Income Without Owning a Single Bond appeared first on 24/7 Wall St..
]]>Treasury yields still compete with dividend stocks for income money. So payouts backed by real free cash flow matter more than the headline yield. The five mega-caps below yield between roughly 2.2% and 2.9%, cover their dividends with room to spare, and have raised them through multiple cycles. One of them has grown its annual dividend per share for 43 consecutive years. The common thread is simple. These companies share growing cash generation, payout ratios near or below two-thirds of earnings, and boards with long records of raising the payout.
AbbVie: Immunology Growth Funds a Raise Every Year Since 2013
AbbVie (NYSE:ABBV) yields 2.32% on a quarterly dividend of $1.73 per share, or $6.92 annualized. The next check comes November 16, 2026.
Dividend safety: Measured against the low end of AbbVie’s full-year 2026 adjusted EPS guidance of $13.87 to $14.07, the annual dividend takes about 50% of earnings. The free cash flow yield is 3.54%, well above the dividend yield. The payout has risen every year since the 2013 spinoff from Abbott, from $0.40 per quarter in 2013 to $1.73 today. The latest raise was 5.5%. The balance sheet is the weak spot. Book value stands at -3.359 per share, and management has committed to “achieving a net leverage ratio of two times within two to three years following the deal close” for the Apogee Therapeutics acquisition.
Bull case: Skyrizi sales rose 24.4% to $5.505 billion in the second quarter, and Rinvoq rose 24.5% to $2.525 billion. That carried total revenue up 10.16% to $16.99 billion. Shares are up 28.83% year to date at $285.82, yet the forward P/E is about 16.
Risk: Humira sales fell 35.9% to $756 million, and Imbruvica fell 29.4%. The stock also trades above the average analyst target of $283.50.
Amgen: Low Payout Ratio and Free Cash Flow That Nearly Doubled
Amgen (NASDAQ:AMGN) pays $2.52 per quarter, a 6% increase from a year ago. At a $10.08 annualized rate and a $447.28 share price, the yield is about 2.25%.
Dividend safety: The annual dividend uses roughly 45% of the low end of 2026 non-GAAP EPS guidance of $22.30 to $23.50, the smallest payout on this list. Second-quarter free cash flow rose 82.57% to $3.489 billion, after full-year 2025 free cash flow of $8.1 billion. Increases have come every year, from $0.28 a quarter in 2011 to $2.52 today.
Bull case: Six growth drivers, led by Repatha and TEZSPIRE, grew 26% and now generate nearly 70% of second-quarter product sales. Adjusted EPS of $6.29 beat the $5.6176 consensus, the fifth consecutive beat. The MariTide obesity program has ten Phase 3 studies ongoing or recruiting. The stock is up 39.44% year-to-date.
Risk: Debt stands at $57.3 billion, and leverage was 3.2x EBITDA at year-end 2025. Biosimilars cut Prolia sales 32% and XGEVA sales 34%, and TAVNEOS faces an FDA request for voluntary market withdrawal.
IBM: A Dividend Paid Every Year Since 1916 at a Discounted Price
IBM (NYSE:IBM) declared its $1.69 quarterly dividend on October 21, 2026, with an ex-dividend date of November 10 and payment on December 10. At $249.75, the $6.76 annualized rate works out to about a 2.71% yield.
Dividend safety: IBM returned $4.8 billion in dividends through the first nine months of 2026 while generating about $8 billion of free cash flow, a coverage ratio of about 60%. Third-quarter free cash flow rose 22.2% to $3.027 billion, and management now expects full-year free cash flow to increase by more than $1 billion. IBM has paid consecutive quarterly dividends every year since 1916, and the 2026 raise marked its 31st consecutive year of dividend increases. Those raises are small: the quarterly payout went from $1.68 to $1.69.
Bull case: Software revenue grew 8.2% to $7.804 billion, with Red Hat up 11% and Data up 19%. Annual recurring revenue grew 8% to $24.9 billion. The shares are down 13.96% year to date, which explains why IBM’s yield now tops every other name on this list except Chevron.
Risk: Debt totals $63.8 billion, including $12.7 billion linked to the financing business, after $11.4 billion in acquisitions year to date. IBM Z revenue fell 20%, and investors are still stomaching the July earnings miss.
Chevron: Record Production and 39 Straight Annual Raises
Chevron (NYSE:CVX) yields 2.87% on a $1.78 quarterly dividend, or $7.12 annualized. That is the highest yield in this group.
Dividend safety: The latest 4% raise marked Chevron’s 39th consecutive annual increase. The dividend equals about 69% of trailing EPS of $10.39, the highest payout ratio here. Cash flow carries it: second-quarter operating cash flow reached $22.633 billion and free cash flow hit $18.095 billion. That funded an $8.41 billion debt reduction and $3,117 million in buybacks in the same quarter.
Bull case: U.S. upstream output set a record at 2,077 thousand barrels of oil equivalent per day, and worldwide production rose 20%. Chevron reached $1.5 billion in annual run-rate Hess synergies within a year of closing, and its 20-year power deal with Microsoft for a 2.67 GW West Texas data center adds a cash stream that doesn’t depend on oil prices. The forward P/E is about 15.
Risk: Second-quarter results benefited from Brent at $104/BBL versus $68/BBL a year earlier, and first-quarter free cash flow was -$1.549 billion. After a 53.6% year-to-date gain, the $227.77 stock sits just below the $230.67 analyst target.
ExxonMobil: 43 Years of Dividend Growth Backed by Advantaged Barrels
ExxonMobil (NYSE:XOM) yields 2.35% on a $1.03 quarterly dividend, or $4.12 annualized.
Dividend safety: ExxonMobil has grown its annual dividend per share for 43 consecutive years, the longest streak in this group. The payout equals about 53% of trailing EPS of $7.77. Full-year 2025 free cash flow of $26.131 billion funded the dividend plus $20.0 billion in buybacks.
Bull case: First-quarter GAAP net income of $4.18 billion included $3.88 billion of derivative timing effects and $706 million in Middle East disruption losses. Underlying earnings rose to $8.77 billion from $7.58 billion. Guyana production topped 900,000 gross barrels of oil per day, and competitive Permian, Guyana, and LNG assets made up 59% of 2025 production. Cumulative structural cost savings since 2019 reached $15.60 billion.
Risk: First-quarter free cash flow fell 61.74% to $2.699 billion, and cash dropped 50.49%. After a 51.05% year-to-date run, the $178.23 stock trades near the $179.41 analyst target, and 15 hold ratings outnumber the 3 strong buy and 7 buy ratings.
Five Payouts Built to Outlast the Next Cycle
AbbVie and Amgen pay out roughly half of forecast earnings or less, while their fastest-growing drugs replace franchises lost to biosimilars. IBM offers the biggest valuation discount and a 110-year payment record backed by growing software cash flow. At the same time, Chevron and ExxonMobil add 39 and 43 years of raises funded by record production and cost cuts. Together they span pharma, enterprise tech, and energy. Each delivers cash flows with a dividend that is well covered heading into year-end.
The post Forget Chasing 7% Yields: These 5 Dividend Stocks Offer Something Different appeared first on 24/7 Wall St..
]]>A 75-year-old who wants $9,350 a month from a portfolio needs $112,200 a year in dividends and distributions without selling any shares. It far exceeds what Social Security provides. After the 3.6% COLA for 2027, the average retired worker collects about $2,170 a month, and the maximum benefit at full retirement age is $4,188.
The math is simple: divide income by yield to get the capital you need. What changes from one yield level to the next is what you give up to get there.
Conservative Tier: $3.2 Million Buys the Safest Paycheck
At a 3.5% yield, $112,200 divided by 0.035 equals about $3,206,000, thanks to broad dividend ETFs and blue-chip dividend growers that make up this level.
The Vanguard High Dividend Yield ETF (NYSEARCA:VYM) yields about 2.2% today, below this level. Its payout has grown, though. Trailing dividends are up roughly 67% since 2016. Chevron (NYSE:CVX) yields about 3.2%. Its quarterly dividend has risen from $1.08 in 2017 to $1.78. You need the most money up front, but in return both your income and principal have room to grow.
Moderate Tier: $1.87 Million With Slower Raises
At 6%, $112,200 divided by 0.06 equals $1,870,000. REITs, preferreds, and covered call funds live here.
W. P. Carey (NYSE:WPC) yields about 6.0%. It has raised its dividend every quarter, from $0.86 to $0.95. Occupancy is 98.5%, and 47.8% of base rent is tied to CPI escalators. Goldman Sachs S&P 500 Premium Income ETF (NASDAQ:GPIX) pays about 8.5% by selling calls on the S&P 500. Those calls cap its upside, and the monthly payout moves around. It ran from $0.35 to almost $0.40 this year.
Aggressive Tier: $935,000 and a Shrinking Cushion
A 12% yield comes from $112,200 divided by 0.12, which equals $935,000. High-yield bonds, leveraged closed-end funds, and mortgage REITs make up this level.
iShares Broad USD High Yield Corporate Bond ETF (CBOE:USHY) yields about 7.4%. Its monthly payout fell as low as $0.15 in 2022. PIMCO Dynamic Income Fund (NYSE:PDI) yields about 19% at today’s price. It has paid $0.2205 a month since 2015 with no raise, and its share price has fallen 10% over the past year. Such a high yield reflects the market pricing in risk.
How the Six-Fund Mix Gets to About $1.46 Million
| Holding | Weight | Current Yield |
|---|---|---|
| VYM | 20% | 2.2% |
| GPIX | 25% | 8.5% |
| WPC | 15% | 6.0% |
| PDI | 15% | 18.8% |
| CVX | 10% | 3.2% |
| USHY | 15% | 7.4% |
The combined yield is about 7.7%, so the target takes roughly $1,458,000. Keep in mind that PDI is only 15% of the money but pays far more than its share of the income. If PDI cuts its payout, the monthly check takes a big hit.
Why a 3.5% Yield Can Pay More by Age 84
Picture a 3.5% portfolio whose dividends grow 8% a year. By age 84, its $112,200 of income grows to about $224,000. A 12% portfolio with flat payouts still sends $112,200, and inflation eats into it every year. PDI’s unchanged distribution since 2015 is a real-world example.
Total returns show the same gap. Over ten years, VYM returned 208% on an adjusted basis. PDI returned 72% and USHY 47%. At 75, the catch is that the growth path needs $3.2 million on day one.
Three Moves That Cut the Capital You Need
- Count Social Security first. A couple collecting the average $3,355 a month only needs the portfolio to fill the gap. A smaller gap lowers the capital you need at every level.
- Look at NAV and price trends, not just yield. If a fund’s share price keeps falling while it pays out, part of that payout may be your own principal coming back to you. Run that check on PDI and GPIX before relying on their monthly checks.
- Model taxes and RMDs together. REIT dividends and bond fund income face ordinary income tax rates. VYM and Chevron offer qualified dividends at lower rates. Holding high-yield funds in an IRA can soften the tax bill, but required minimum distributions may still force withdrawals that dip into principal.
The post What Does a 75-Year-Old Need Invested to Collect $9,350 a Month for Life Without Touching Principal? appeared first on 24/7 Wall St..
]]>Hess Midstream (NYSE:HESM) has fallen nearly 23% over the past month to $30.62 as of midday, Oct. 20, including a 22.63% slide over the past month. One transaction caused it. On Oct. 6, the company announced a deal with Chevron (NYSE:CVX), and the deal is expected to close by year-end. The units closed at $38.69 on Oct. 6 and $33.03 on Oct. 7. That 14.6% one-day drop a week ago set the direction for the whole month.
4 Moving Parts Reshape Hess Midstream
The pending deal has four parts:
- Cash out: Hess Midstream pays Chevron $200 million.
- Assets in: It acquires Chevron’s DJ Basin gathering and storage assets, which adds a second basin to a operations that has been all Bakken.
- Units retired: Chevron contributes its Hess Midstream interests, which offsets about 78 million Class B units and 449,000 Class A shares.
- Net effect: Shares outstanding fall by nearly 40% once the deal closes.
The DJ assets put Hess Midstream in the same basin as Western Midstream Partners (NYSE:WES), which lists the DJ as one of its core operating basins.
Lower Tariffs Buy Years of Contract Certainty
Chevron gets lower Bakken tariffs for several years starting in 2027. In return, Hess Midstream gets contracts extended well into the next decade. It trades higher rates for longer certainty. The company’s preliminary 2027 adjusted EBITDA guidance is $850 million to $950 million. Its 2026 guidance is $1,225 million to $1,250 million. At the centers, that is a drop of about 27%. The 2027 range is a forecast, and no results back it yet.
The August call had already suggested at slower growth. Chief Executive Jonathan Stein said, “Chevron did mention this, that even at a lower rig count, they’re able to maintain production.”
He said future growth would come mostly from price escalators and cost savings, “A lot of that is inflation escalation as you go forward. And so that’s really a kind of driver and some OPEX savings.” The tariff cut takes that flat volume outlook and adds lower rates on top of it.
Why a Flat Payout Costs Less With 40% Fewer Units
Hess Midstream targets annualized per-share distribution growth of at least 5% through the third and fourth quarters. After that, it holds the per-share payout flat through 2027 at the fourth-quarter level. The second-quarter payout was $0.7888, or $3.155 a year. At the current price, that is a yield of about 10.4%.
A freeze keeps each holder’s check at the same dollar amount. The company’s total distribution bill equals the per-share rate times the number of units. If units fall by nearly 40%, the total bill falls with them even though the rate stays put. EBITDA drops by roughly a quarter while the unit count drops by more than a third, so cash flow per remaining unit could hold up. The $200 million cash payment and the DJ assets’ earnings will decide how much room is left. As a limited partnership, Hess Midstream reports taxes differently from an ordinary corporation, so holders should check its year-end tax materials.
The peers show the range. MPLX (NYSE:MPLX) expects distribution increases of 12.5% in both 2026 and 2027. Western Midstream has kept its quarterly payout at $0.930. Hess Midstream is moving from MPLX’s growth model toward Western’s steady one.
Verdict: Right on Earnings, Too Harsh on the Payout
The market is right to mark down a business whose EBITDA steps down about 27%. A yield of about 10.4% on a fixed payout, though, suggests investors doubt the distribution itself (a double-digit yield usually sets off the warning signs we cataloged in a free dividend traps report). The shrinking unit count makes that doubt look overdone. Before the deal, leverage stood at three times EBITDA, and management was aiming for about two and a half times by 2028. The stock is worth watching through the closing date and the third-quarter earnings report. If leverage stays near three times after the deal, the selloff looks overdone. If it grows significantly, the discount is deserved.
The post Hess Midstream Is Down Nearly 23% in a Month. Here’s What Chevron Changed appeared first on 24/7 Wall St..
]]>To generate about $8,750 a month in dividend income, or $105,000 a year, a 67-year-old retiree would need roughly a $1.32 million portfolio. This amount would cover a comfortable retirement, with room for travel and healthcare. In this scenario, he moves the entire portfolio out of the JPMorgan Nasdaq Equity Premium Income ETF (NASDAQ:JEPQ) and into the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD). The swap sharply cuts his income, and the capital needed to fund $105,000 varies widely by yield.
His Paycheck Shrank by Almost Two-Thirds
One of the more popular dividend-income ETFs, JEPQ paid $6.88 per share over the trailing 12 months on a share price near $60. That works out to a yield of about 11.6%. On $1.32 million, that produces roughly $152,000 a year, well above his target. That means he needed only about 8% to cover his bills.
On the other hand, SCHD paid $1.05 per share on shares around $34, a yield of about 3.1%. His $1.32 million now generates about $40,600 a year, or roughly $3,380 a month. That leaves a $64,410 gap he must fill with Social Security or by selling about 5% of the portfolio each year.
Why Anyone Would Accept a Smaller Check
For its part, JEPQ’s monthly payout has risen from $0.45 to $0.70 per share over the past year, a 58% increase. Income from its equity-linked notes is generally taxed as ordinary income. For 2026, single filers pay 24% on income above $105,700. SCHD’s payouts come from companies like Coca-Cola (NYSE:KO), Chevron (NYSE:CVX) and Procter & Gamble (NYSE:PG), and those dividends typically qualify for lower tax rates.
Don’t forget that the principal growth matters too. SCHD’s adjusted price rose 32% over the past year, while JEPQ gained 17%, so consider this over the long term.
What $105,000 a Year Costs at Each Yield
Conservative Tier (3% to 4%)
If this individual wants to stick with conservative investing, they should invest $105,000 divided by 0.035, or $3,000,000. At SCHD’s current 3.1% yield, the figure rises to about $3.39 million. Dividend growth funds and broad-market equity funds live here. The portfolio stays diversified, payouts can rise over time, and principal has the best chance of growing. The catch: you need the most capital upfront.
Moderate Tier (5% to 7%)
At a more moderate investment level, $105,000 divided by 0.06 equals $1,750,000. Preferred shares, REITs, high-dividend equity funds, and S&P 500 covered-call funds (which sell options on their holdings to generate income) typically yield in this range. Dividend growth slows down, or stalls, and income tends to lag inflation over decades. His $1.32 million still falls short.
Aggressive Tier (8% to 14%)
Reaching an aggressive investment level requires accepting a certain level of risk, as you divide $105,000 by 0.10 to get $1,050,000. JEPQ sits alongside business development companies, mortgage real estate investment trusts, and funds that hold high-yield bonds. Distributions can be cut, covered calls cap upside, and principal can shrink even while the checks keep arriving.
Growth Math That Closes the Gap
Suppose SCHD’s payout grows 8% a year. His $40,600 in income would reach about $81,100 in 9 years without adding a dollar. JEPQ’s payout tracks option premiums and market volatility, so it has no built-in growth path.
Treat that 8% as an assumption to test, as SCHD’s trailing distributions grew only about 2% versus the prior four quarters. A retiree who switches now gives up certain income today in exchange for growth he has to wait for.
Three Moves Before Making the Same Swap
- Size the gap after Social Security. Subtract guaranteed income from your $105,000 target first. If benefits cover $40,000, a 3.1% portfolio comes much closer to funding the rest.
- Blend rather than switching everything at once. Some retirees keep enough high-yield income to cover the shortfall for the next five years, then let the dividend-growth position compound until its payout catches up.
- Match each fund to the right account. Ordinary-income payers like JEPQ often fit best in an IRA, while qualified-dividend payers like SCHD fit best in a taxable account. SCHD pays quarterly, so keep a cash reserve to smooth out your monthly bills.
The post A 67-Year-Old Swapped JEPQ for SCHD in a $1.32 Million Portfolio. Here’s What Happened to His $8,750 Monthly Paycheck appeared first on 24/7 Wall St..
]]>Retirement income now faces a hard benchmark. The 10-year Treasury yielded 5.09% on October 16, so a dividend stock must offer more than a bond: a growing, cash-flow-funded payout. The five large caps below pay above-market yields supported by free cash flow and long payout records. A telecom selloff on Friday drove two of them to even higher yields. We judge each on safety first, then yield.
Realty Income: Monthly Checks Backed by 98.8% Occupancy
Realty Income (NYSE:O) yields about 6.01%, based on a forward annualized dividend of $3.258 and a price of $54.17. The newest monthly payment of $0.2715 went out October 15. Bills come monthly, which is the whole case for stocks that pay on the same schedule. (We rounded up seven of our favorite monthly payers in a free report here.)
Dividend safety: For a real estate investment trust (REIT), the key coverage measure is adjusted funds from operations (AFFO), a cash-flow figure. Management raised 2026 AFFO guidance to $4.44 to $4.45; the dividend uses roughly 73% of AFFO even at the low end. Occupancy is 98.8%, Fitch rates the company “A”, and net debt runs 5.4x pro forma adjusted EBITDAre. The company’s Q1 2026 filing counts its 115th consecutive quarterly dividend increase, and its payment history goes back to 1999.
Bull case: Realty Income put $2.6 billion to work in Q2 at a 7.3% initial cash yield, raised its 2026 investment target to $10.0 billion, and launched a $6 billion hyperscale data center joint venture. Shares fell 9.41% over the past month and trade below the $66.39 analyst target.
Risk: Tenants without investment-grade ratings account for 65.7% of annualized base rent, and rising rates make the REIT’s funding more expensive.
Verizon: Friday’s Selloff Lifted the Yield Near 6.8%
Verizon (NYSE:VZ) had its worst day since 2002 after news that SpaceX plans a U.S. network. Shares fell 10.14% to $41.65, raising the yield to about 6.79% on the $2.83 forward dividend.
Dividend safety: Free cash flow was $6.43 billion in Q2, up 27.1% from a year earlier, and the 2026 forecast calls for $21.94 billion to $22.14 billion. The dividend matches about 57% of the low end of adjusted EPS guidance ($4.99). The quarterly payout has risen from $0.64 in 2021 to $0.7075 today.
Bull case: Verizon added 184,000 postpaid phone subscribers, up from a loss of 9,000 a year earlier. Its adjusted EBITDA margin expanded to 40.1%, and the Frontier deal brought fiber connections to 10.9 million.
Risk: Net unsecured debt rose to 2.5x adjusted EBITDA after the Frontier acquisition, and satellite competition is a new threat to pricing.


AT&T: A Flat Dividend With Wide Cash Coverage
AT&T (NYSE:T) yields about 5.01% after a 9.85% drop on Friday. It cut its quarterly dividend in 2022, from $0.52 to $0.2775, and has paid that same amount ever since.
Dividend safety: The company expects at least $18 billion of free cash flow this year against a dividend bill of roughly $8 billion. The payout is about 49% of the low end of adjusted EPS guidance. AT&T plans to return over $45 billion to shareholders from 2026 to 2028.
Bull case: Q2 brought 432,000 postpaid phone net adds and 646,000 internet net adds. It is on track to reach more than 40 million fiber locations by year-end, and its free cash flow targets rise each year through 2028.
Risk: Dividend income will not grow. Legacy copper revenue fell 25.9%, and net debt stands at 2.68x adjusted EBITDA.


Chevron: Lower Yield, Strongest Balance Sheet in the Group
Chevron (NYSE:CVX) yields about 3.36%, the lowest of the five. It earns its place through dividend growth: the quarterly payout has risen every year from $1.42 in 2022 to $1.78 in 2026.
Dividend safety: Q2 free cash flow of $18.10 billion covers a quarterly dividend bill of more than $3.5 billion many times over. Net debt is 1.08x EBITDA, with interest costs covered 13.7x, and Chevron paid down $8.41 billion of debt in Q2 alone.
Bull case: Production rose 20% to 4,070 MBOED after the Hess acquisition. Chevron also reached $3 billion in cost savings ahead of schedule and signed a 2.67 GW power deal with Microsoft for an AI data center.
Risk: Earnings depend on oil prices. Shares are up 42.95% this year, so the yield has fallen.
Altria: A Fresh Raise and an Ultra-High-Yield Payout
Altria (NYSE:MO) yields about 6.19%, among the highest in the market, after raising its quarterly dividend to $1.11 from $1.06. The payout has risen every year, starting at $0.80 in 2019.
Dividend safety: The new $4.44 annual rate is about 79% of the low end of 2026 adjusted EPS guidance ($5.61). Debt-to-EBITDA was 1.9x, in line with the company’s target. On the Q2 call, management called the dividend “our primary vehicle” for returning cash to shareholders.
Bull case: Pricing power holds up. Smokeable price realization was 4.5%, and the segment’s margins were 64.8%. Retail share for the on! nicotine pouch brand rose to 8.6%.
Risk: Industry cigarette volumes fell 5%, and Marlboro’s retail share slipped to 39.5% as smokers trade down to cheaper brands.


Five Income Streams Ranked on Safety and Yield
Realty Income pays monthly, the two telecoms supply heavy free cash flow at marked-down prices, Chevron brings dividend growth and the best balance sheet, and Altria raised its payout again this year. Each dividend is covered by cash flow or earnings guidance with room to spare. Over the next few months, watch how Verizon and AT&T respond to SpaceX and where the 10-year yield goes from 5.09%.
The post 5 High-Yield Stocks to Buy Now Before Your Retirement Starts appeared first on 24/7 Wall St..
]]>At the 24% federal bracket, which for 2026 applies to taxable income over $105,700 for single filers ($211,400 for married couples filing jointly), a $500,000 portfolio split across five high-yield S&P 500 stocks produces about $27,400 in annual dividends. Held in a taxable account, roughly $4,651 of that goes to the IRS every year. In a Roth IRA, the tax on that income is zero.
Roth Versus Taxable: $4,651 a Year on One Portfolio
Each of five stocks gets a $100,000 allocation from the model. Each yield is the company’s forward annualized dividend divided by its share price as of Friday. Four of the five are corporations that pay qualified dividends, which are taxed at 15% for filers in the 22% through 32% brackets. Realty Income (NYSE:O) is a real estate investment trust (REIT), and its distributions generally face your full marginal rate as ordinary income.
| Stock | Yield | Annual Income | Tax at 24% Bracket |
|---|---|---|---|
| Verizon (NYSE:VZ) | 6.81% | $6,810 | $1,022 |
| Altria (NYSE:MO) | 6.21% | $6,210 | $932 |
| Realty Income | 6.01% | $6,010 | $1,442 |
| AT&T (NYSE:T) | 5.01% | $5,010 | $751 |
| Chevron (NYSE:CVX) | 3.36% | $3,360 | $504 |
| Total | $27,400 | $4,651 |
In the taxable account, the portfolio clears about $22,749 a year. In the Roth, it keeps the full $27,400. The difference is $4,651 more income each year, or $46,510 over 10 years, before any growth.
- Realty Income: This is the strongest case for Roth location. It makes up 20% of the money in the portfolio but about 31% of the tax bill, because its monthly distributions are taxed at ordinary rates. It just paid its 115th consecutive quarterly dividend increase.
- Verizon: Shares were headed for their worst day since 2002 on SpaceX U.S. network plans, which drove the yield to the highest in this group. The quarterly payout is $0.7075.
- Altria: Altria raised its quarterly dividend to $1.11 from $1.06. Every increase adds to the taxable income a Roth would shield.
- AT&T: AT&T fell alongside Verizon on Starlink fears. It has reiterated $45B+ in shareholder returns for 2026 to 2028.
- Chevron: Shares are up 42.86% year to date, which has pulled the yield down. That makes Chevron the smallest Roth winner in this group.
How Your Bracket Changes the Roth Advantage
For the same portfolio, the tax drag rises with your bracket. At the top bracket, which starts above $640,600 for single filers, qualified dividends are taxed at 20%.
| Bracket | Annual Tax Cost | Taxable Net Income | Roth Advantage |
|---|---|---|---|
| 22% | $4,531 | $22,869 | $4,531 |
| 24% | $4,651 | $22,749 | $4,651 |
| 32% | $5,132 | $22,268 | $5,132 |
| 37% | $6,502 | $20,898 | $6,502 |
Higher earners may also owe the 3.8% net investment income tax (NIIT), which increases every figure in the 32% and 37% rows. Because Realty Income is taxed at ordinary rates, its share of the bill grows faster than the others’ as your bracket rises.
Compounding Turns the Annual Gap Into Six Figures
This annual difference compounds over time. Reinvesting the $4,651 yearly tax savings at a conservative 4% inside the Roth grows the gap to about $55,840 after 10 years and $138,498 after 20 years. These figures assume no price gains and no dividend growth. Realty Income accounts for about $42,940 of that 20-year total by itself. That gap represents the long-run tax cost of keeping these five positions subject to annual taxation.
Key Tax Items to Review Before the Next Filing
- When you own Realty Income or any other REIT in a taxable account, compare the ordinary and qualified dividend amounts on your 1099-DIV (box 1a versus box 1b). Then figure the cost using the table above for your bracket.
- A phased Roth conversion could start with the positions paying ordinary income. Balance the one-time conversion tax against that stock’s 20-year compounded delta. The low-bracket years after you stop working and before your first RMD are usually the cheapest time to run those conversions, which is the whole subject of our free Roth guide: The Roth Window.
- When Roth space is limited, the highest-taxed income benefits the most from that shelter. In the 24% bracket, Chevron’s $100,000 position costs $504 a year in tax, while the same amount in Realty Income costs $1,442.
The post 5 Dividend Stocks for 100% Tax-Free Roth IRA Income appeared first on 24/7 Wall St..
]]>Brent crude, the global oil benchmark, passed $110 a barrel soon after 2:30 p.m. ET on October 16, 2026, its highest level since May. It finished the week just under that mark at $109.86. U.S. crude (WTI) rose 3.5% and closed at $101.41.
In the same session, tech stocks lost more than a trillion dollars in value. The Nasdaq 100 fell 2.5%, and the Philadelphia semiconductor index dropped 3.8%, its eighth straight losing day.
ExxonMobil (NYSE:XOM) rose 2.46% to close at $178.98. That is just below its 52-week high of $179.16 and gives the company a market value of $735.95 billion. Chevron (NYSE:CVX) rose 2.59% to $224.99.
Both moves came from crude prices, since the companies were quiet on October 16. If you own oil and tech stocks together, that one shock raised part of your portfolio and pulled down the rest.
Why One Oil Shock Hit Two Sectors at Once
The war that began when the U.S. and Israel attacked Iran in late February closed the Strait of Hormuz. Before the fighting, nearly 20% of the world’s oil supply passed through it. Ukrainian attacks have also shut down much of Russia’s refining capacity.
Oil producers’ costs stay mostly fixed, so higher crude prices go mostly to profit. Growth stocks move in the opposite direction. Costlier fuel pushes up inflation, making it more likely the Federal Reserve will raise rates again this year. Growth stocks are priced on those future profits. Higher rates make profits expected years from now worth less in today’s dollars.
Mason Mendez works at Wells Fargo. The global real assets analyst said, “investors also remain concerned about further military escalation in the Middle East.” He added that “the need to rebuild depleted global inventories could create an additional source of demand.”
How Much $110 Oil Adds to Exxon and Chevron
Exxon produced 4.6 million oil-equivalent barrels per day in the first quarter and plans $20 billion of share buybacks in 2026. The conflict has both cost and helped Exxon. That same quarter also took $706 million in losses tied to Middle East supply disruptions.
Chevron’s results show more directly how high oil prices affect earnings. Brent averaged $104 in Chevron’s second quarter, up from $68 a year earlier. Net income reached $12.07 billion, free cash flow was $18.10 billion, and total debt fell by $8.41 billion.
Exxon is expected to report third-quarter results on October 30, though the company has not confirmed the date. The prices it actually received and its production levels will show how much of this oil rally reaches its profits.

Why a Supply Spike Can Unwind Fast
A ceasefire or a reopened strait could quickly reverse the supply shortage. In May, federal forecasters expected Brent to average $89 in the fourth quarter of 2026 once traffic through Hormuz resumed. Prices are now well above that forecast.
Refilling used-up stockpiles could keep demand strong even after oil resumes flowing. Other forces push prices down: high prices cut demand, and the U.S. already announced a Strategic Petroleum Reserve release on March 11.
Energy stocks offset tech losses only while oil drives the selloff, and if tensions suddenly ease, energy shares would fall from near their highs just as tech would likely recover.
What Exxon’s Valuation Assumes About Oil Prices
Exxon is up 51.69% in 2026 and trades at about 26 times earnings, with a 2.34% dividend yield. That price assumes oil stays high, which leaves the shares exposed if crude falls.
Chevron’s numbers look stronger by comparison. It yields 2.89%, and its free cash flow yield is 3.76%, compared with Exxon’s 3.21%. Its U.S. refineries also ran at 97% of capacity, and refining income would help if crude falls but refining profit margins hold.

Chevron’s price of 36 times trailing earnings looks high. Most of that comes from weaker 2025 results. Full-year net income was $12.30 billion, about what Chevron earned in its most recent quarter alone.
That view would be challenged. Exxon’s expected October 30 report would need to show prices and production strong enough to raise the shares above $179.16 and keep them there. If Brent falls back below $100 before that report, concerns about Exxon’s valuation grow.
The post Oil Topped $110 as Tech Stocks Lost $1 Trillion in a Day appeared first on 24/7 Wall St..
]]>Every stock in the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) passed a quality screen to qualify. The question for income investors is whether the companies paying the dividends can keep raising them. The fund tracks the Dow Jones U.S. Dividend 100 Index, which screens for cash flow to debt, return on equity, yield, and five years of dividend growth. It yields about 3.8% and charges a 0.06% expense ratio. Six veteran dividend growers in the portfolio show why that income holds up. Two of them are running much closer to the edge than the other four.
Where SCHD’s 3.8% Yield Comes From
SCHD takes in ordinary cash dividends from its 100 stocks and pays them out quarterly. Each dollar of yield comes from a dividend a real company declares.
Holdings data come from the fund’s latest portfolio filing, dated May 31, 2026. At that point, SCHD held $94.9 billion in net assets, with the largest position at about 6.7% of the fund and the top 10 making up roughly 43.6%.
Together, the six names below account for about 14.1% of the fund. The index reconstitutes every March, which means a declining dividend payer can be dropped before it weighs on the fund’s payout for long.
Six Payout Records Under the Microscope
Chevron Turns Hess Into Dividend Fuel
Chevron (NYSE:CVX) is the largest of the six at 3.8% of assets and yields 3.2%. Its quarterly dividend rose to $1.78 this year. The 2025 raise had already brought its growth run to 38 years.
Second-quarter free cash flow reached $18.10 billion as the Hess acquisition drove production to record levels, and Chevron paid down $8.41 billion of debt.
The $7.12 annualized dividend works out to about 69% of trailing EPS of $10.39. Crude prices are the main risk. A long slide in oil would quickly.
ADP Keeps Raising on Payroll Cash
Automatic Data Processing (NASDAQ:ADP) makes up 2.2% of the fund and yields 2.6%. In November 2025, it raised the quarterly dividend to $1.70, its 51st consecutive annual increase.
The $6.80 annualized payout uses about 61% of fiscal 2026 EPS of $11.12. Management guides for fiscal 2027 adjusted EPS growth of 9% to 11%.
Abbott’s Earnings Dip Comes From Deal Accounting
Abbott Laboratories (NYSE:ABT) makes up 3.0% of the fund and yields 2.5%. According to its filing, the $0.63 quarterly payout marks its 54th consecutive year of dividend increases and its 410th consecutive quarterly dividend.
Second-quarter GAAP EPS dropped to $0.53 because of charges linked to the Exact Sciences acquisition. Management raised full-year adjusted EPS guidance to $5.45 to $5.60, which puts the payout at about 45% to 46% of that range.
Kimberly-Clark Is the Closest Call
Kimberly-Clark (NASDAQ:KMB) is the smallest of the six at 0.8%, but it yields 5.3%. This year, it raised the quarterly dividend to $1.28, extending its run to 54 consecutive years.
Coverage is thinnest here. Trailing GAAP EPS of $5.07 barely covers the $5.08 per share paid out over the past year. Second-quarter adjusted EPS of $2.12 covered the quarterly dividend at a payout of about 60%.
Management expects 2026 adjusted EPS to decline slightly because a disinformation campaign in China is hurting diaper sales and a fire at a Los Angeles distribution center. The Kenvue acquisition, expected to close by the end of 2026, adds integration risk. Adjusted coverage keeps the dividend safe for now, but a second straight year of falling earnings would pressure it.
Altria Pays an Ultra-High Yield From a Shrinking Base
The group’s only ultra-high-yield name, Altria (NYSE:MO), makes up 2.9% of the fund at 6.2%. Its August raise to $1.11 per share adds to a record 60 increases in 56 years.
The $4.44 forward payout equals roughly 78% to 79% of 2026 adjusted EPS guidance of $5.61 to $5.72. That ratio is normal for a tobacco business requiring little reinvestment. The real threat is volume: domestic cigarette shipments fell 3.2% last quarter. Price increases have offset falling volume for years, and the raised guidance suggests they still do.
Fastenal Brings the Youngest Streak and the Fastest Growth
Fastenal (NASDAQ:FAST) makes up 1.3% of the fund and has the group’s lowest yield at 1.8%. Its 27 consecutive years of dividend growth surpass the 25-year threshold required to qualify as a Dividend Aristocrat.
The $0.26 quarterly dividend comes to about 89% of trailing EPS. Second-quarter dividends of $275.4 million slightly exceeded operating cash flow of $265.7 million because working capital absorbed cash.
Revenue rose 14.7% in the second quarter, driven by contract customers, so earnings are catching up to the payout.
A 22% Year and a Payout Built to Last
On a dividend-adjusted basis, SCHD is up about 22% this year and 24% over the past 12 months. Over five years, it’s up 54%, and over ten years, 227%.
SCHD’s income is safe. Chevron, ADP, and Abbott cover their dividends with room to spare. Fastenal’s revenue growth is closing the gap on its tight payout. Altria’s high payout fits a business requiring little reinvestment. Kimberly-Clark is the biggest risk, but at under 1% of the fund, the index can drop it at the March reconstitution if earnings keep falling.
Investors who need 6% or more in income across a whole portfolio won’t get it from a fund yielding 3.8%. Growth-focused investors may find that the fund’s tilt toward mature cash generators trails during tech-led rallies. The next milestones are Kimberly-Clark’s first guidance after the Kenvue deal closes, Altria’s shipment trends, and Chevron’s dividend declaration early next year.
The post Why SCHD’s Income Is Unshakable This Year: 6 Dividend Aristocrats Doing the Heavy Lifting appeared first on 24/7 Wall St..
]]>Gasoline prices rose 9.1% in September, and the government’s release spelled out what that meant: the jump was “accounting for over half of the monthly all items increase.”
The Consumer Price Index rose 0.6% on a seasonally adjusted basis in September, up from 0.4% in August. Annual inflation reached 3.7%, against an expected 3.6%. The “over half” share applies to the monthly increase, while the annual rate reflects a wider mix of prices.
Stocks sold off on the report on October 14, 2026. The S&P 500 fell 1.11%, and the Nasdaq fell 1.88%.
Energy moved against the broader market. The State Street Energy Select Sector SPDR ETF (NYSEARCA:XLE) rose 0.64% to $67.63, just under its one-year high of $67.72, after a 61.05% total return over the past year.
That leaves a problem for anyone who holds the fund or is thinking about buying it, as energy stocks worked as a hedge against the very inflation they help create, but that protection has already become expensive.
Energy Carried a Headline That Core Prices Did Not Support
The energy index rose 5.2% in September, while core prices, which exclude food and energy, rose 0.3% for a second straight month.
Over the past year, food rose 2.5%, shelter rose 3.2%, and used cars and trucks fell 1.5%. Those readings point to cooling, so once energy is set aside, the report shows no reacceleration.
Investors sold the headline anyway, because interest-rate expectations respond to headline energy even when core prices hold steady, as energy-driven inflation is the hardest case for a central bank, since higher rates cannot produce more barrels of oil.
Fuel Costs Are Already Reaching Services
Over 12 months, gasoline rose 34.2%, fuel oil rose 74.2%, and airline fares rose 22.4%. Airfares are a service price, so higher fuel costs are already showing up in what travelers pay.
Changes in crude reach the pump with a lag, which means oil has already shaped part of the next report. West Texas Intermediate (WTI), the U.S. benchmark, peaked at $107.02 on September 15 and sat at $95.09 in late trading on October 14, with Brent at $106.06.
The national average for regular gasoline fell from $4.478 on September 21 to $4.331 on October 12. That suggests gasoline will add less to the October report, although prices above $4.00 a gallon still strain household budgets.
What XLE Holders Actually Own
Exxon Mobil (NYSE:XOM) and Chevron (NYSE:CVX) were the fund’s two largest holdings as of June 30, 2026. Behind them sit producers, refiners, oilfield-service firms and pipeline operators.
That mix undermines the fund’s link to crude. Pipeline operators earn fees tied to volume, and refiners earn margins that can narrow when crude rises faster than pump prices.
Oil is the index input most likely to fall back toward its average. A supply response, demand destruction at current prices, or a production decision from the major exporters would cool CPI and the ETF at the same time.
WTI traded at $76.78 on August 5 before its September run, so today’s oil price has risen quickly and could give back gains just as fast.
Where XLE Stands After the September CPI Jump
XLE looks extended at this level. The fund sits just under its one-year high after a 61.05% run, so the fund now carries a peak price for a hedge that works only while oil stays high. Riding a run like this is fine as long as the exit is planned, which is the whole subject of our free bubble survivor’s handbook.
Core inflation at 0.3% shows the broad price trend is cooler than the headline. That undermines the case for paying extra for inflation protection.
For investors exploring more direct exposure to crude, the State Street SPDR S&P Oil & Gas Exploration & Production ETF (NYSEARCA:XOP) offers a cleaner link. Producer earnings track oil more directly. That sensitivity also means larger losses when crude falls.
Investors can test this view against the CPI release due Tuesday, November 10. If the gasoline index falls and WTI stays below $100, the hedge case is undermined, but a close above $67.72 alongside rising oil would show the market thinks otherwise.
The post Gasoline Alone Drove More Than Half of September’s Inflation Jump appeared first on 24/7 Wall St..
]]>Exxon Mobil (NYSE:XOM) shares have risen 50.94% this year to $178.10. Crude helped: WTI trades at $96.24 a barrel, up 54.0% from a year ago. Income investors care more about the quarterly check of $1.03, which comes to $4.12 a year. The U.S. Energy Information Administration expects Brent to slide to $79/b in 2027 as Middle East supply comes back. That makes it worth asking whether the dividend holds up when crude falls.
Dividend Already Survived $64 Oil
Recent results show where Exxon’s dividend breakeven is. In Q4 2025, Brent averaged $64 per barrel. That quarter, Exxon brought in $12.68 billion of operating cash flow, spent $7.45 billion on capex and paid $4.37 billion in dividends. Free cash flow covered the payout 1.2 times. In Q2 2025, when U.S. crude prices were $62.58, coverage was 1.23 times. Free cash flow fully paid the dividend with oil in the low $60s.
Coverage Across the Full Cycle
For full years, free cash flow covered the dividend 1.84 times in 2024 and 1.37 times in 2025. Single quarters swing a lot more. Q1 2026 covered only 0.52 times, dragged down by $3.88B in mark-to-market timing effects and $706M of Middle East disruption losses. Q2 2026 covered it 3.96 times. On the July call, CEO Darren Woods said:
“That strength allows us to keep investing in advantaged opportunities, return surplus cash to shareholders, and maintain one of the strongest balance sheets in industry.”
Two structural changes raise the buffer. Structural cost savings have reached $16.3 billion since 2019. In Guyana, CFO Neil Hansen said Exxon has “fully recovered the $55 billion of investment along with all the operating costs,” and he called it “very much an inflection into free cash flow.”
Borrowing Room When Cash Falls Short
The 2020 crash gives a real stress test. Operating cash flow fell to $14.67 billion against $17.28 billion of capex, so free cash flow came in at negative $2.61 billion. Exxon still paid $14.87 billion in dividends and covered the gap with debt, which rose $20.72 billion to $67.64 billion.

Exxon has more room to do that again. Total debt is $42.37 billion against $259.38 billion of equity. Net debt/EBITDA is 0.548 and interest coverage is 56x. Comparable figures for Chevron (NYSE:CVX) are 0.94 and 13.7x. Exxon also has the planned $20B of 2026 buybacks, which it can cut long before the dividend.
Track Record Versus Chevron and Shell
Exxon kept the quarterly payment at $0.87 through 2020 and raised it again in 2021. The company reports 43 consecutive years of dividend growth, the kind of run we screened for in our free Dividend Kings guide. Chevron is close behind with its 39th consecutive annual increase. Shell (NYSE:SHEL) cut its dividend in 2020, and its net debt rose to $52.6 billion in Q1 2026.
Verdict: Exxon Can Keep Paying
Yes, Exxon can keep paying its dividend through the next downturn. The payout is covered with oil in the low $60s, and the company has cut costs and turned Guyana into a cash generator since 2020. It also carries less debt than it did going into that crash. If crude drops below $60 for a long stretch, expect buybacks to shrink first and Exxon to borrow before it cuts the dividend, as it did in 2020. Income investors should watch two signals: free cash flow coverage over a full year and the size of the buyback.
The post Exxon’s Dividend Stays Safe Even if Oil Crashes to $79 a Barrel appeared first on 24/7 Wall St..
]]>Oil prices swing hard, and retirement budgets can’t. Integrated majors close that gap by owning the whole chain. When crude falls, cheaper feedstock tends to widen refining and chemicals margins, so one division supports another and the dividend keeps coming. TotalEnergies (NYSE:TTE) showed how this works in fiscal 2025, when its Refining and Chemicals segment grew adjusted net operating income 10% in a year when Brent crude fell 14%. TotalEnergies, Chevron (NYSE:CVX) and Exxon Mobil (NYSE:XOM) all run upstream, downstream and chemicals operations under one roof. All three are raising their payouts, and all three pay those dividends out of operating cash flow.
Chevron: 39 Straight Raises Backed by Record Cash Flow
Chevron yields 2.98% on a quarterly dividend of $1.78, or $7.12 a year. The yield looks modest because the stock has climbed 47.85% year to date to $219.25. The dividend itself keeps growing.
Track record: This year’s 4% raise was Chevron’s 39th consecutive annual increase, according to the company. The payment record supports the recent run. Over the past five years, the quarterly rate has gone from $1.42 to $1.51, $1.63, $1.71 and now $1.78.
Coverage and balance sheet: Chevron’s free cash flow yield of 3.88% is about 1.3 times its dividend yield. Second-quarter 2026 free cash flow reached $18.10 billion on operating cash flow of $22.63 billion. That one quarter beat the $16.6 billion of free cash flow Chevron produced in all of 2025. Debt is low: debt-to-equity is 0.219, net debt to EBITDA is 0.94 and interest coverage is 13.7x. Chevron also paid down $8.41 billion of debt in the quarter. In 2025 it returned $27.1 billion to shareholders.
For the bull case, the Hess acquisition gave Chevron a interest in Guyana’s Stabroek block. Worldwide production rose 20% year over year to 4,070 MBOED, and U.S. upstream output hit a record 2,077 MBOED. The integrated model paid off as well: downstream earnings reached $4.87 billion, up from $737 million a year earlier. Chevron reached $3 billion in run-rate structural cost cuts six months ahead of schedule and captured $1.5 billion in Hess synergies within a year of closing. It also signed a 20-year power purchase agreement with Microsoft (NASDAQ:MSFT) for a 2.67 GW West Texas data center, which adds long-term revenue tied to AI power demand.
Risk: Measured against reported earnings, the payout is stretched. The $7.12 annualized dividend is higher than Chevron’s 2025 EPS of $6.63, and a P/E near 35 shows earnings still trailing the share price. Today’s cash flow covers the dividend easily, but a long slump in oil would reduce that supports quickly.
Exxon Mobil: 43 Years of Growth and the Strongest Balance Sheet Here
Exxon Mobil yields 2.41% on a $1.03 quarterly dividend, or $4.12 a year. As with Chevron, a strong rally has pushed the yield down: shares are up 48.12% year to date at $174.77.
Track record: Exxon reports 43 consecutive years of annual dividend-per-share growth. The company’s most recent increase was 4%, in the fourth quarter of 2025. The quarterly rate has climbed from $0.41 in 1999 to $1.03 today. Recent increases were $0.88, $0.91, $0.95, $0.99 and $1.03.
Coverage and balance sheet: The forward dividend works out to about 61% of 2025 EPS of $6.70. The 3.30% free cash flow yield is about 1.4 times the dividend yield. In 2025, Exxon generated $51.97 billion of operating cash flow and $26.13 billion of free cash flow while buying back $20 billion of stock. It has the strongest balance sheet of the three, with debt-to-equity of 0.168, net debt to EBITDA of 0.548 and interest coverage running at 56.3x.
Bull case: Exxon’s growth comes from low-cost barrels. Advantaged assets (the Permian, Guyana and LNG) made up 59% of 2025 production. Upstream output hit a record 4.7 million boe per day, the highest in more than 40 years, and Guyana now tops 900,000 gross barrels a day. All 10 of 10 key 2025 projects started up, and Golden Pass LNG has loaded its first export cargo. Total structural cost savings of $15.6 billion since 2019 are heading toward a $20 billion target by 2030. Lower costs let Exxon keep paying the dividend at lower oil prices.
Risk: Quarterly results can swing sharply. First-quarter 2026 reported net income was $4.18 billion after a $3.88 billion hit from derivative timing and $706 million of losses from Middle East supply disruptions. Free cash flow was only $2.70 billion, while buybacks totaled $4.9 billion. Exxon has also committed to $20 billion of buybacks and $27 billion to $29 billion of capex this year. If weak quarters pile up, the buyback is the spending Exxon can most easily cut.
TotalEnergies: The Highest Yield at the Lowest Multiple
TotalEnergies is the high-yield name of the group at 4.56%. Its next payment is $1.021 per share, and its annualized forward dividend is $4.084.
Track record: The board raised the fiscal 2025 dividend 5.6% to €3.40 per share. It then set the first 2026 interim payment at €0.90, up 5.9%. The available payment record goes back to 2007.
Coverage and balance sheet: Trailing dividends of $4.052 per share equal about 51% of trailing EPS of $7.99, the most conservative earnings payout of the three. In 2025, operating cash flow of $27.343 billion easily covered $16.953 billion of capex and still left room for $7.5 billion in buybacks. Management’s plan calls for cash flow above $26 billion with Brent at $60, and gearing targeted around 15% at year-end. The stock trades at about 11 times trailing earnings and 9 times forward estimates. Chevron trades near 35 times trailing earnings and Exxon near 25.
Bull case: TotalEnergies runs the most diverse business of the three. It sold 43.9 Mt of LNG and produced 48.1 TWh of net electricity, while hydrocarbon production grew 4% to 2,529 kboe/d. In the full-year results, chief executive Patrick Pouyanné said the company “reaped the benefits of its integrated and balanced multi-energy strategy” in a year of falling oil prices. A $12.5 billion cash-savings plan running through 2030 gives the dividend another layer of support.
Risk: TotalEnergies sets its dividend in euros, so the dollar amount U.S. holders receive moves with exchange rates. The latest payment of $1.021 followed one of $0.969365. A stronger dollar can reduce the check even in a year when the euro dividend goes up.
One Risk All Three Share: A Price None of Them Sets
Every dividend on this list depends on oil and gas prices that these companies don’t control. Much of the recent jump in cash flow came from Brent at $104 a barrel, compared with $68 a year earlier. Part of that rise came from Middle East disruptions, which also shut in about 15% of TotalEnergies’ production at one point. Prices that spike during a conflict can fall just as fast once supply returns or OPEC+ changes its quotas.
The energy transition is the slower threat. Electrification and climate policy will weigh on long-term oil demand, and TotalEnergies already faces climate litigation in France, Belgium and the United States. Integration, low-cost barrels and cost cuts make these companies more resilient, but they still sell hydrocarbons. In a $60 oil world, retirees should expect slower dividend growth, and that is the price TotalEnergies plans its budget around.
Three Durable Payout Engines Built for the Long Haul
Exxon Mobil has the most protected payout of the trio, with a 43-year growth run and the cleanest balance sheet. Chevron pairs 39 straight raises with free cash flow that well tops its dividend. TotalEnergies pays the most income per dollar invested at the lowest valuation, with currency swings as the trade-off. Together, they show how the integrated model is designed to support dividends across oil cycles, with each segment cushioning the others when prices move. Building a ladder of payers like these is the whole idea behind our free guide to living off dividends without ever selling a share, which you can grab here.
The post These 3 Oil Giants Make Money Beyond the Wellhead. That’s Good News for Dividends appeared first on 24/7 Wall St..
]]>A retiree living off a portfolio needs income that keeps coming. The First Trust Morningstar Dividend Leaders Index Fund (NYSEARCA:FDL) has paid distributions four times a year since 2006. FDL tracks Morningstar’s dividend leaders index, a rules-based basket of established U.S. companies with long payout records. The quarterly checks change size, and that matters for anyone paying fixed bills with them.
A $7 Billion Fund Built on Dividend Payers
First Trust runs FDL, and it is a large, established fund with $7.3 billion in net assets in its June 30, 2026 filing. The fund owns dividend-paying stocks and passes along what those companies pay, so its income moves with the holdings’ own payouts.
Returns Have Rewarded Patient Holders
Shares traded near $50 on Oct. 14. The fund is up 17% year to date and 23% over the past year.
The longer record also holds up. FDL returned 88% over five years and 187% over ten. For a retiree, that history shows a fund that grew principal while paying out income, which is the main promise of a dividend strategy.
Quarterly Checks That Change Size
The most recent distribution was $0.5139 per share, ex-dividend Sept. 24, 2026. The one before it paid $0.4732 per share, ex-dividend June 25, 2026.
Over the trailing twelve months, FDL paid $1.9375 per share.
In 2026, the three payments came in at $0.4005 in the first quarter, $0.4732 in the second and $0.5139 in the third. Each check was a different size.
In recent years, the first-quarter payment has been the smallest. In 2025, the March payment of $0.3573 was the lowest of the year, and the December payment reached $0.5499.
A retiree taking income from FDL will get a different amount each quarter. Anyone meeting fixed monthly expenses with it needs a cash reserve for the leaner months. That is the whole problem our free Paycheck Portfolio method was built to solve, turning uneven payouts into something that acts like a steady paycheck. Planning around it is simple once you expect it.
Six Stocks Make Up a Large Share of the Fund
FDL is built to be concentrated, and its top positions make up a large share of net assets. The six largest holdings in the latest filing were:
| Holding | Share of Net Assets |
|---|---|
| Chevron (NYSE:CVX) | 7% |
| Verizon (NYSE:VZ) | 7% |
| Philip Morris (NYSE:PM) | 6% |
| Pfizer (NYSE:PFE) | 6% |
| PepsiCo | 5% |
| Altria | 5% |
Two tobacco companies, Philip Morris and Altria, are among the largest positions. Investors who screen out tobacco should know they are there.
Past the top names, the portfolio leans toward energy, telecom, pharmaceuticals, consumer staples, utilities and banks. It is a value-oriented income portfolio. Investors who want growth exposure will find little of it here.
Recent Trading Matters Less Than the Income
FDL is down 3% over the past month, though it has gained 2% over the past week and 0.2% early in Wednesday’s session. For a retiree, these swings matter less than whether the underlying companies keep paying dividends.
Where FDL Fits in a Retirement Portfolio
FDL fits a retiree who wants equity income from large, established companies. That investor also has to handle uneven quarterly payments and accept that most of the money sits in a handful of sectors. For that investor, the fund delivers on its core appeal: real profits this year and four checks a year from recognizable businesses.
It fits less well as someone’s only holding, because of that focus. It also fits poorly for anyone who needs same payments on a fixed schedule.
The fund’s expense ratio is a real cost for a long-term holder, so check it with First Trust before deciding. The holdings above come from the June 30 filing and will have changed since.
The post Morningstar’s Dividend ETF Is Kind of Perfect for Retirees Right Now appeared first on 24/7 Wall St..
]]>The energy major’s stock has gained sharply over the past year, and the rally changes how its full decade looks. Put $1,000 into Chevron (NYSE:CVX) ten years ago, reinvest every dividend, and you’d now hold more than three times your money. Even so, you’d still trail the S&P 500.
Oil Crashes, Oil Spikes and a Hess-Sized Push for Scale
Chevron works across the whole energy chain. Upstream, it finds and produces oil and gas. Downstream, it refines, markets and makes chemicals. Results swing with crude prices. The 2020 COVID crash hit the whole industry hard, though Chevron kept paying its dividend. Russia’s invasion of Ukraine in 2022 then brought a boom.
Chevron closed its Hess acquisition in 2025. That year production hit a record 3,723 MBOED, up 12%. In 2026, military action that began February 28 effectively shut the Strait of Hormuz, and Brent averaged $117 per barrel in April. Second-quarter revenue rose 51.4% to $67.2B. Over the whole decade, the quarterly dividend climbed from $1.07 to $1.78.
Your $1,000 Became $3,276
Chevron’s figures use dividend-adjusted prices, so they assume all dividends were reinvested. The S&P 500 figures track SPDR S&P 500 ETF Trust (NYSEARCA:SPY) on price alone and leave out its dividends.
1-Year Return
- Initial Investment: $1,000
- Current Value: $1,516
- Total Return: 51.61%
- S&P 500 (same period): $1,190 (19.01%)
5-Year Return
- Initial Investment: $1,000
- Current Value: $2,462
- Total Return: 146.21%
- Annualized Return: 19.7%
- S&P 500 (same period): $1,786 (78.59%)
10-Year Return
- Initial Investment: $1,000
- Current Value: $3,276
- Total Return: 227.63%
- Annualized Return: 12.6%
- S&P 500 (same period): $3,647 (264.67%)

Timing drove almost everything here. The 5-year window starts in October 2021, just before the 2022 surge, and Chevron beat the index easily over that period. The 10-year holder sat through the 2020 collapse and still fell behind a benchmark that wasn’t even credited with its dividends. Reinvested payouts did much of the work. Without them, Chevron’s decade would look much weaker.
Why Chevron’s Dividend Case Matters Most Right Now
Chevron’s case today depends on income that holds up across the oil cycle. Investors focused on riding the current crude spike could face more risk.
Bull case: The CEO says Hess assets generate free cash flow “roughly double the incremental dividends.” A 20-year Microsoft (NASDAQ:MSFT) power deal adds cash flow that doesn’t depend on commodity prices. Chevron also bases its 2030 targets on oil prices below current levels.
Bear case: Today’s earnings depend on a Hormuz disruption that won’t last forever. The stock trades at $217.22, right near its 52-week high of $217.78.
The income case looks stronger than the price-gain case. A decade of crashes and spikes still turned $1,000 into $3,276 for patient holders who reinvested. Energy majors reward holders who stay through a full cycle.
The post Chevron’s Big Rally Couldn’t Erase a Decade of Underperformance appeared first on 24/7 Wall St..
]]>For retirees, the hardest part of giving up a paycheck is losing the regular stream of cash that came with it. Social Security pays part of the bills. Savings have to cover the rest, ideally without forcing a sale during a selloff. Bank certificates of deposit do little here: the national average 12-month CD pays 1.73% annual percentage yield (APY). The 10-year Treasury yields 5.31%, but that coupon remains fixed for a decade. Every one of the six companies below raised its dividend over the past year.
The Dogs of the Dow strategy targets the highest-yielding blue chips in the Dow Jones Industrial Average, and these six names are current Dogs of the Dow. Splitting $500,000 equally puts about $83,333.33 into each stock. At current forward yields, that $500,000 would produce more than $16,500 in annual passive income. Below is what each position generates, from lowest yield to highest.
Merck: A Rising Payout Through the Keytruda Transition
- Forward Yield: 2.40%
- Shares for $83,333.33: 589.3
- Annual Passive Income: ~$2,003.77
Merck (NYSE:MRK) is a large-cap drugmaker built around Keytruda, which posted family sales of $8.4 billion in the second quarter of 2026. The yield ranks lowest in this group because the shares have risen 37.13% year to date to $141.40, which spreads the $3.40 forward dividend over a higher price.
On paper, this year’s coverage looks thin. Full-year EPS guidance of $2.66 to $2.76 includes a $2.31 per share upfront charge for the Terns Pharmaceuticals deal, so the payout tops reported 2026 earnings. Coverage from underlying earnings is stronger once one-time charges are excluded. CFO Caroline Litchfield said, “We remain committed to the dividend to increase it over time,” and CEO Rob Davis called Keytruda’s loss of exclusivity “more of a hill than a cliff.”


Coca-Cola: Asset-Light Margins Fund Steady Raises
- Forward Yield: 2.44%
- Shares for $83,333.33: 960.7
- Annual Passive Income: ~$2,036.74
Coca-Cola (NYSE:KO) sells concentrates and syrups to bottlers worldwide. The company’s asset-light approach delivered a 34.9% operating margin in the second quarter, when revenue grew 6.7% to $13.38 billion. The yield is modest because the shares have gained 26.49% year to date.
The $2.12 forward dividend works out to about 64% of trailing EPS of $3.33. Management raised 2026 guidance to comparable EPS growth of 9% to 10% and free cash flow of about $12.4 billion. The quarterly payout rose to $0.53 from $0.51 in 2026.


Amgen: Biotech Cash Flow Behind a 6% Raise
- Forward Yield: 2.51%
- Shares for $83,333.33: 207.7
- Annual Passive Income: ~$2,093.20
Amgen (NASDAQ:AMGN) is a large-cap biotech with 17 products running above $1 billion annualized. It pays a $10.08 forward dividend on a $401.30 share price. CFO Peter Griffith noted the $2.52 quarterly payout represents a 6% increase over the prior year.
Coverage is the strongest in this group. Raised 2026 non-GAAP EPS guidance from $22.30 to $23.50 means the dividend absorbs roughly 45% of the low end, and second-quarter free cash flow reached $3.5 billion. Risks include biosimilars, which cut combined Prolia and Xgeva sales by 33%, and $57.3 billion in debt.


Procter & Gamble: 70 Straight Years of Dividend Growth
- Forward Yield: 2.92%
- Shares for $83,333.33: 558.2
- Annual Passive Income: ~$2,430.39
Procter & Gamble (NYSE:PG) owns Tide, Pampers, Gillette, Crest, and Olay, products consumers rebuy in any economy. The company just marked its 70th consecutive year of dividend increases and 136th consecutive year of payments. Shares are up just 6.46% year to date, keeping the yield above those of Coca-Cola and Merck.
The $4.354 forward dividend equals about 63% of fiscal 2026 core EPS of $6.89, supported by $15.84 billion in free cash flow. For fiscal 2027, P&G plans about $10 billion in dividends and $5 billion in buybacks, despite an expected after-tax commodity headwind of roughly $1 billion.


Chevron: Record Output Lifts Free Cash Flow
- Forward Yield: 3.41%
- Shares for $83,333.33: 399.7
- Annual Passive Income: ~$2,845.72
As an integrated oil major, Chevron (NYSE:CVX) operates in oil and chemicals. The Hess acquisition drove production to a record 4,070 thousand barrels of oil equivalent per day (MBOED). Energy stocks carry higher yields because investors price in commodity cycles, and Chevron pays a $7.12 forward dividend.
The dividend takes about 69% of trailing EPS of $10.39. Cash flow gives a stronger read: second-quarter free cash flow hit $18.10 billion, Chevron cut debt by $8.41 billion in the quarter, and net debt to EBITDA stands at 1.08x. A 20-year, 2.67 GW power deal with a tech giant adds revenue outside oil prices.
Verizon: Ultra-High-Yield With an “Ironclad” Pledge
- Forward Yield: 6.11%
- Shares for $83,333.33: 1,799.9
- Annual Passive Income: ~$5,093.59
Verizon Communications (NYSE:VZ) is the largest U.S. wireless carrier and also runs Fios fiber broadband. Telecom is a mature, capital-intensive business carrying substantial debt, so the market prices Verizon at a forward P/E of about 9. That valuation is what makes this the group’s only ultra-high-yield name.
The $2.83 forward dividend uses about 57% of the low end of raised 2026 adjusted EPS guidance of $4.99 to $5.04, and free cash flow is guided to $21.94 billion to $22.14 billion. Net unsecured debt of $136.5 billion remains the biggest risk. Management calls the dividend “ironclad” and has raised it for the 20th consecutive year.
Six Dow Dividend Payers, One Income Stream
| Name | Forward Yield | Annual Dividend Income |
|---|---|---|
| Verizon | 6.11% | $5,093.59 |
| Chevron | 3.41% | $2,845.72 |
| Procter & Gamble | 2.92% | $2,430.39 |
| Amgen | 2.51% | $2,093.20 |
| Coca-Cola | 2.44% | $2,036.74 |
| Merck | 2.40% | $2,003.77 |
| Total | 3.30% | $16,503.42 |
Together, these six holdings produce $16,503.42 in annual income on a $500,000 investment, for a combined yield of 3.30%. Verizon contributes $5,093.59, Chevron adds $2,845.72, P&G brings in $2,430.39, Amgen delivers $2,093.20, Coca-Cola supplies $2,036.74, and Merck contributes the remaining $2,003.77.
Compounding drives this basket’s long-term value. Reinvested dividends buy more fractional shares, raising the next payment, and annual increases stack on top. For retirees who don’t need every dollar yet, that rising income can outpace rising costs. (The whole point of a dividend ladder is never having to sell a share, and our free guide shows how to build one.) Watch upcoming dividend announcements, quarterly earnings, and guidance updates, especially Merck’s Keytruda transition and Verizon’s debt load.
The post How to Turn $500,000 Into a Lazy $16,500 Yearly Passive Income Stream appeared first on 24/7 Wall St..
]]>A big yield only matters if the business can keep paying it. Every name on this month’s list pays its dividend out of cash generation that clearly tops the dividend bill, and each has years of increases to show for it. Verizon (NYSE:VZ) is the clearest example. It guides to $21.94B to $22.14B of 2026 free cash flow, while its forward dividend costs about $11.76B a year. Here are five NYSE-listed income names where the payout rests on cash flow. Two of them are trading lower right now, which has pushed their yields up.
Realty Income: Monthly Payer Near Its 52-Week Low
Realty Income (NYSE:O) yields about 5.98%, based on its $3.258 annualized forward dividend and a share price of $54.44. That makes it high-yield, sitting just under the ultra-high-yield line. The latest monthly payment of $0.2715 goes out on October 15, 2026.
Dividend safety: Management raised 2026 AFFO (adjusted funds from operations, the REIT version of cash earnings) guidance to $4.44 to $4.45 per share. At the low end of that range, the forward dividend uses about 73% of AFFO. Q2 AFFO per share came in at $1.09, up 3.8% year over year, and occupancy stands at 98.8%. Fitch rates the company “A” with a stable outlook. The Q2 release marked the 115th consecutive quarterly dividend increase, and the company had declared 670 consecutive monthly dividends as of its Q1 report.
Bull case: The stock is down 8.05% over the past month. It now trades below its 50-day average of $59.47 and its 200-day average of $61.74, close to its 52-week low of $53.15. Meanwhile, the business keeps growing. Management raised 2026 investment volume to $10.0B, renewed leases are coming in at 102.7% of prior rent, and a $6B hyperscale data center joint venture adds a new growth channel. The average analyst target is $66.39.
Risk: Tenants without investment-grade credit generate 65.7% of annualized base rent. Net debt to adjusted EBITDAre also rose to 5.4x from 5.2x in Q1, so the REIT is more exposed if interest rates stay high.
AbbVie: Dividend Growth Backed by Skyrizi and Rinvoq
AbbVie (NYSE:ABBV) yields about 2.49% on a $6.92 forward dividend. That is the lowest yield on this list. AbbVie is here for dividend growth, and the record backs that up. To get the next $1.73 quarterly payment, you must own shares before the October 15, 2026 ex-dividend date.
Dividend safety: AbbVie has raised its dividend every year since its 2013 spin-off. The quarterly payment went from $0.40 in 2013 to $1.73 in 2026. Full-year adjusted EPS guidance is $13.87 to $14.07, so the forward dividend uses about 50% of the low end. Q2 adjusted EPS of $3.65 beat the $3.08 consensus. The CFO said the company remains committed to “achieving a net leverage ratio of two times within two to three years following the deal close.”
Bull case: Newer drugs are making up for Humira’s lost sales. Skyrizi grew 24.4% to $5.51B and Rinvoq grew 24.5% to $2.53B. Management now expects full-year revenue of about $67.6 billion. The stock trades at 16 times forward earnings and is up 24.57% year to date.
Risk: Humira sales dropped 35.9% to $756M, and Imbruvica fell 29.4%. The pending $10.9B immunology acquisition is expected to reduce earnings by $0.14 per share and will add more debt to a balance sheet that already shows negative book value.
Verizon: Ultra-High Yield After a Sharp Selloff
Verizon is an ultra-high-yield name at about 6.58%, based on a $2.83 forward dividend and a $43 share price. Part of that yield comes from a recent drop. The stock is down 13.59% over one month, and telecom stocks bounced only slightly on Monday after Friday’s plunge.
Dividend safety: Free cash flow covers the dividend easily. Q2 free cash flow rose 27.1% to $6.43B, and the adjusted EBITDA margin expanded to 40.1% from 37.1%. The quarterly payment went up from $0.69 to $0.7075 in 2026. Verizon’s dividend history shows continuous quarterly payments since 1999, rising from $0.385 per quarter at the start. After the Frontier deal, net unsecured debt rose to 2.5x adjusted EBITDA.
Bull case: The core business is improving. Verizon added 184K postpaid phone subscribers, compared with a loss of 9K a year earlier. Churn (the share of customers leaving) improved to 0.92%, and fiber connections rose 43.3% to 10.9M. Management raised adjusted EPS guidance to $4.99 to $5.04. At 9 times forward earnings, the stock trades well below the average analyst target of $51.24.
Risk: Competition is the main threat. Fixed wireless net adds fell 30.6% and GAAP net income dropped 22.9%. Higher debt after Frontier also leaves less room for mistakes if a price war breaks out.
Chevron: Record Production and Hess Cash Cover the Payout
Chevron (NYSE:CVX) yields about 3.28%, based on a $1.78 quarterly dividend and a $217.18 share price. The yield is lower than it was because the stock has risen 46.46% year to date.
Dividend safety: Q2 adjusted free cash flow was $15.4 billion. The quarterly dividend costs about $3.49B, so cash flow covered it several times over. Chevron paid down more than $8 billion of debt in the quarter. Net debt to EBITDA is 0.94x and interest coverage is 13.7x. The quarterly dividend has gone up every year from 2017 through 2026, from $1.08 to $1.78. The CEO said the Hess assets generate free cash flow “roughly double the incremental dividends.”
Bull case: Chevron hit a record 2,077 MBOED of U.S. upstream production. It reached $3 billion in structural cost cuts six months ahead of schedule. It also signed a 20-year take-or-pay power contract for 2.67 gigawatts to supply an AI data center, which brings in cash that does not depend on oil prices. Management’s 2030 targets assume “flat commodity prices that are lower than today.”
Risk: High oil prices lifted Q2 results. Brent averaged $104 in the quarter versus $68 a year earlier. If oil falls back, the cash buffer over the dividend will contract.
Altria: A Raised Payout Facing Shrinking Cigarette Volumes
Altria (NYSE:MO) is ultra-high-yield at about 6.24%, based on its $4.44 annualized dividend and a $71.16 share price. In August, the board raised the quarterly payment 4.7% to $1.11, which the company called “the 61st dividend increase in the past 57 years.”
Dividend safety: Adjusted EPS guidance is $5.61 to $5.72, so the dividend uses about 79% of the low end. That is a high payout ratio, but Altria has run at that level for years. Management is aiming mid-single digits dividend per share growth annually through 2028. Altria returned nearly $3.9B to shareholders in the first half of 2026. Shareholders’ equity is negative at -$2.6B, mainly because of years of buybacks.
Bull case: Pricing power keeps cigarette profits strong even as volumes fall. on! PLUS is now in 120,000 stores. At 12 times forward earnings, the stock has a modest valuation. The stock is up 29.4% year to date.
Risk: Domestic cigarette volumes fell 5%, Marlboro’s retail share slid to 39.5%, and on! lost 4.2 pts of nicotine pouch share. The stock also trades above the average analyst target of $70.
One Roster, Five Sources of Cash
Realty Income and Verizon have fallen in price while their cash flow keeps growing. Chevron brings the strongest balance sheet on the list, and AbbVie brings a dividend-growth record dating back to its spin-off. Altria rounds it out with an ultra-high yield and a long history of increases. Each payout is supported by cash generation, and the next round of quarterly results will show whether that coverage holds.
The post 5 High-Yield Dividend Stocks That Could Turn October’s Market Weakness Into Income appeared first on 24/7 Wall St..
]]>S&P 500 futures are basically flat before the open. The index’s futures sit near 7,817, up 0.1%, after a record-setting week. Oil is the main mover this morning. Brent crude is trading near $106 a barrel because the war with Iran is still disrupting global energy supplies, and that is raising oil stocks before the bell. Investors are holding the S&P 500 steady ahead of Tuesday, when bank earnings season begins.
Where the Indexes Stand Before the Open
| Index | Latest Verified Move | Reading |
|---|---|---|
| S&P 500 | +0.6% | Friday close |
| Nasdaq Composite | +0.6% | Friday close |
| Dow Jones Industrial Average | +423 points (+0.8%) | Friday close |
| Russell 2000 | +0.5% | Friday close |
| VIX | 15 | Thursday close, latest verified |
Oil Keeps Energy Majors in the Lead
Brent settled Friday at $105, and it keeps rising. In May, the EIA expected Brent to average $89 in the fourth quarter. Prices are still well above that forecast, so producers are making more per barrel than planners expected.
Exxon Mobil (NYSE:XOM) is up 1.2% in premarket trading. Chevron (NYSE:CVX) is up about the same, and both stocks have gained close to 45% this year. In midstream, Energy Transfer (NYSE:ET) agreed last week to buy Vaquero Midstream. The deal adds to a pipeline network that already carries natural gas to power plants serving AI data centers.
Yields Above 5% Keep a Lid on Tech
On Friday the 10-year Treasury yield rose to 5.2%. It recently reached its highest level since 2002. The Fed also raised its target rate in September, which sets the upper bound at 4%. Higher rates make future profits worth less today, and fast-growing tech stocks feel that the most.
NVIDIA (NASDAQ:NVDA) is down 0.4% before the open. That small dip matters because NVIDIA makes up 8% of the SPDR S&P 500 ETF (NYSEARCA:SPY), which is barely moving near $779.
What This Rotation Means for Your Portfolio
The flat index hides money moving underneath it. Energy is gaining while the largest tech holding falls, so the two cancel out in the headline number. Owning an S&P 500 index fund means most of your results still depend on a handful of AI giants, and increasingly on the power, cooling, and pipeline companies feeding them (we highlighted seven of those suppliers in a free AI infrastructure report). Oil exposure is cushioning those holdings right now, but it can’t fully replace them.
The VIX, Wall Street’s fear gauge, is around 15, which counts as a normal reading. Options traders are calm even though bond yields are at multi-decade highs and oil is above $100.
Bank Earnings Arrive Tuesday
Four of the largest U.S. banks report before the open on October 13, along with two major health care companies. Watch the money banks set aside for bad loans. The economy added only 29,000 jobs in September, so rising reserves would show the hiring slowdown is starting to hit borrowers.
The post Stock Market Today: S&P 500 Futures Pause Near Record Highs as Oil Rises Ahead of Bank Earnings appeared first on 24/7 Wall St..
]]>Oil has been volatile. West Texas Intermediate reached $114.58 on April 7, 2026, after bottoming at $55.44 in December 2025. It stood at $96.24 on October 6. Exxon Mobil (NYSE:XOM) shares closed at $169.01, up 43.18% this year, and yield 2.48%. If you own Exxon for the quarterly check, the question that matters is what happens when oil falls and then stays down.
What Funds the $4.12 Payout
Exxon pays $1.03 a quarter, or $4.12 a year. With about 4.11 billion shares outstanding, that works out to roughly $16.9 billion a year. In 2025, Exxon generated $51.97 billion of operating cash flow, spent $29.00 billion on capex and kept $26.13 billion in free cash flow. That covered the dividend easily. Add the $20B buyback, though, and total payouts ran ahead of free cash flow. Capex guidance for 2026 is $27B to $29B.
A corporate breakeven is the oil price at which operating cash flow just pays for capital spending plus the dividend. When crude falls below that level, the shortfall has to come from cash or borrowing. Exxon has not published a specific dividend breakeven in its recent reports, so its debt capacity becomes the real buffer. Debt-to-equity is 0.168, net debt/EBITDA is 0.548 and interest coverage is 56.28x. CEO Darren Woods put it this way:
“That growth is underpinned by disciplined capital allocation and an industry-leading balance sheet that gives us unmatched flexibility to invest through the cycle and consistently deliver industry-leading returns.”
A 43-Year Streak Tested by 2020
Exxon has raised its annual dividend for 43 consecutive years. When crude collapsed in 2020, management held the quarterly payout at $0.87 from 2019 through 2021 and did not cut it. Shell (NYSE:SHEL) cut its dividend in 2020. Its quarterly dividend is now $0.3906, and net debt was $52.6 billion in Q1 2026. For now, Chevron (NYSE:CVX) pays $1.78 after its 39th consecutive annual increase. Still, Chevron posted negative $1.549 billion of free cash flow in Q1 2026 and has leverage of 1.08x net debt/EBITDA.
Where a Price Slide Hits First
Q1 2026 showed how fast the numbers can tighten. Free cash flow fell 61.74% to $2.70B. The buyback gives first. Exxon pledges its $20B buyback only “assuming reasonable market conditions.” Capex cuts would follow. Costs offer support as well: structural savings have reached $16.3 billion since 2019. CFO Neil Hansen said on the July call:
“If you took our cash expenses this year and you just annualized it, our cash OPEX would look even with 2019.”
Guyana adds more support. Exxon has “fully recovered the $55 billion of investment,” which Hansen called “very much an inflection into free cash flow.” That matters, because EIA projects Brent below $70 per barrel through 2030.
Verdict: The Dividend Holds
Yes. In a long downturn, Exxon would slow buybacks, trim capex and lean on its low debt before cutting the dividend. Last quarter it produced more than $17 billion of free cash flow and reduced net debt by more than $7 billion. What a downturn would put at risk is dividend growth. For holders screening the rest of the high-yield energy complex, the seven warning signs that typically come before a cut are laid out in a free guide here.
Signals Holders Should Track Now
- Whether buybacks stay on pace for $20B
- Quarterly free cash flow compared with the dividend
- Net debt/EBITDA moving above 0.548
- Whether the fifth Guyana FPSO starts up by year-end
- Progress toward the $20B savings target
The post Exxon’s 43-Year Dividend Streak Faces Its Biggest Test Yet as Oil Prices Slide appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) pays an annualized forward dividend of $7.12 a share, yielding 3.07%. The company reported $18.10 billion in free cash flow last quarter. WTI crude sat at $96.24 on October 6, with shares up 43.46% year to date. The payout looks secure now, but the test comes when crude falls. The EIA projects Brent at $89 in the fourth quarter and $79 in 2027.
One Quarter Showed the Dividend Relying on the Balance Sheet
Oil majors sell a commodity they cannot control, so dividend coverage swings with crude prices. Chevron’s 2026 shows how wide those swings can be.
In the first quarter, operating cash flow was only $2.514 billion, while dividends cost $3.526 billion. Free cash flow came in at -$1.549 billion, dragged down by about $2.9 billion of negative timing effects. Chevron still bought back $2.5 billion of stock, and its net debt ratio rose to 17.9% from 15.6%. For that quarter, the balance sheet paid shareholders.
The second quarter reversed the picture. Operating cash flow reached $22.63 billion against $3.504 billion in dividends, and Chevron cut debt by $8.41 billion. CFO Eimear Bonner said:
“Our net debt coverage ratio improved, reflecting strong cash generation in the quarter.”
What Crude Price Does the Dividend Need?
Chevron’s Q4 2025 results offer a breakeven test. Brent averaged $64. Operating cash flow of $10.789 billion covered $5.264 billion in capex and $3.404 billion in dividends with $2,121 million left over. For all of 2025, free cash flow of $16.60 billion beat dividends by $3.849 billion. Total shareholder returns were $27.1 billion, with buybacks making up the difference.
Management plans for prices below today’s. CEO Mike Wirth reaffirmed “our $6 billion guidance at $70 Brent” for affiliate distributions. Bonner said 2030 targets hold:
“…adjusted free cash flow growth, averaging greater than 10% per year, and more than 3% improvement on return on capital employed, all at flat commodity prices that are lower than today.”
The Hess acquisition helps. Wirth said those assets produce free cash flow “roughly double the incremental dividends.”
A 39-Year Raise Streak Helps Holders and Limits Management
The 4% raise in January was Chevron’s 39th consecutive annual increase, putting it in rare company with the longest-streak dividend payers (we ranked ten of them by valuation in a free Dividend Kings report). Past crashes tested that run. In 2020, operating cash flow of $10.6 billion just covered $9.7 billion of dividends and did not cover capex on top of them. Q2 2020 brought in only $80 million. Even so, the quarterly rate stayed at $1.29, up from $1.19 in 2019. In 2015 the rate stayed at $1.07 for all four payments. The run gives holders confidence. It also means management keeps paying through downturns and covers the gap with debt.
How ExxonMobil and ConocoPhillips Compare
ExxonMobil (NYSE:XOM) has a 43-year streak of increases and a $20 billion buyback plan for 2026. ConocoPhillips (NYSE:COP) ties payouts to cash flow, targeting 45% of CFO to shareholders. That approach reduces payouts when oil falls. Chevron must decide what to cut.
Verdict: The Dividend Is Covered by Cash, With the Balance Sheet as Backup
At the current crude prices, Chevron covers its dividend with operating cash flow. The Q1 shortfall reversed when working capital unwound by $2.9 billion. The dividend stayed covered at $64 Brent, below the EIA’s 2027 forecast. The buyback would be cut first. With net debt at 0.6 times cash flow, Chevron can keep the dividend through this downturn.
The post Chevron’s Dividend Has Survived Every Oil Crash. Can It Survive This One? appeared first on 24/7 Wall St..
]]>On October 8, 2026, the latest Treasury record available on October 9, Treasury bills yielded an average of 3.97% on 4-week bills, 4.15% on 13-week bills, 4.3% on 26-week bills and 4.44% on 52-week bills. A dividend stock has to beat that for a retiree. Three of the six income stocks below have higher starting yields. Whether those payments hold up, and how much is left after taxes, is the harder question.
How Treasury Bills Work and Why Their Rate Never Stays Put
A Treasury bill is a short-term loan to the U.S. government. The Treasury sells bills with terms of 4, 6, 8, 13, 17, 26, and 52 weeks, with a $100 minimum purchase. Bills pay no coupon. They are sold at a discount or at par, and when the bill matures you receive its face value. Your interest is the difference between what you paid and that face value, and it arrives in one lump sum when the bill matures.
The rate is fixed at auction. The 4-week to 26-week bills are auctioned weekly, and the 52-week bill is auctioned every four weeks. The lock on that rate lasts only until the bill matures. After that, you take the cash or roll it into a new bill at whatever rate the following auction sets. Even within one week the yields moved: the 52-week average was 4.46% on October 5 and 6, then 4.44% on October 8. In the latest record, longer bills paid more than the 4-week bill, so a saver choosing the shortest bill for flexibility is giving up some income right now.
That is reinvestment risk. If short-term rates fall, a retiree rolling bills finds income drop at the next auction, and nothing in the bill protects against that. The government’s guarantee covers payment of face value at maturity. It does not cover three things: the market price if you sell before it matures (prices fall when rates rise, though the effect is small on short bills), the loss of purchasing power to inflation, and the rate on your next bill. A bill also pays the same amount for its whole term and never increases it.
Dividend Safety Comes First: Six Income Stocks Measured Against a Bill
The trade-off has two sides. A dividend can be cut at any board meeting, while the interest set at a bill’s auction cannot be reduced before maturity. A dividend can also be increases year after year, while a bill’s rate remains fixed until it matures. A yield measures income against today’s share price, and that price can fall. A higher yield matters little if the payout is at risk, so each stock below starts with how well its dividend is covered.
Higher Starting Yields: Realty Income, Altria and Main Street Capital
Realty Income (NYSE:O) yielded about 5.70% as of October 9, 2026, paid monthly. Its latest monthly dividend rose to $0.2715 from $0.271, payable October 15, 2026, and the second quarter marked its 115th consecutive quarterly dividend increase. Coverage looks solid. Management increases 2026 AFFO guidance to $4.44 to $4.45 per share against an annualized dividend of $3.252. Occupancy is about 98.8%, and Fitch rates the company ‘A’ with a Stable Outlook. Shares show why a yield is not a return: they fell 10.85% over the month to October 9 and are down 3.23% over one year. A bill kept until it comes due has no equivalent drawdown.
Altria (NYSE:MO) yielded 6.11% as of October 9, 2026, the highest in this group. It increases its quarterly dividend to $1.11 from $1.06, and 2026 adjusted EPS guidance of $5.61 to $5.72 covers the $4.44 annualized forward dividend. The risk is the business itself. Industry cigarette sales are declining by about 5%, Marlboro’s retail share fell to 39.5% (down 1.5 points), and second-quarter adjusted EPS of $1.48 came in below the $1.50 consensus. The dividend depends on raising prices on a shrinking product.
Main Street Capital (NYSE:MAIN), a business development company that loans to and invests in lower middle-market companies, yielded 5.73% as of October 9, 2026. Its regular monthly dividend was $0.265 for July, August and September, and it has made 12 regular monthly dividend increases since Q4 2021. On top of that, it has paid quarterly additional dividends of $0.30, the most recent being the 20th in a row. Retirees should budget only on the regular payment, because additional dividends change and are not guaranteed. Second-quarter adjusted EPS of $1.04 beat the $0.96 consensus, but total investment income fell 15.7% year over year, and the shares are down 4.4% year to date.
Smaller Starting Yields, Steady Annual Raises: AbbVie, Chevron and Duke Energy
AbbVie (NYSE:ABBV) yielded about 2.42% as of October 9, 2026, below every bill term. It pays for that lower yield with growth. The quarterly dividend went from $1.55 in 2024 to $1.64 in 2025 and $1.73 in 2026. Skyrizi grew 24.4% and Rinvoq 24.5%, more than making up for Humira’s 35.9% decline. 2026 adjusted EPS guidance of $13.87 to $14.07 covers the $6.92 annualized forward dividend comfortably.
Chevron (NYSE:CVX) yielded about 3.07% as of October 9, 2026, also below the bill curve. Its quarterly dividend rose to $1.78 from $1.71. In 2020, during the oil-price crash, the dividend held at $1.29 all year. The Hess acquisition drove second-quarter revenue up 51.4% to $67.20 billion. Even so, the payout ultimately depends on oil prices, which no Treasury holder has to think about.
Duke Energy (NYSE:DUK) pays an annualized forward dividend of $4.34 per share, with the stock at $116.41 on October 9, 2026. The latest quarterly payment rose to $1.085 from $1.065, continuing raises that go back years in the record. As a regulated utility, Duke makes returns approved by state regulators. It confirmed 2026 adjusted EPS guidance of $6.55 to $6.80 and a long-term EPS growth target of 5% to 7% through 2030, with demand from data centers adding to growth.
| Company | Yield (Oct. 9, 2026) | Latest regular payment | Frequency | Typical tax character |
|---|---|---|---|---|
| Realty Income | 5.70% | $0.2715 | Monthly | Mostly ordinary income |
| Altria | 6.11% | $1.11 | Quarterly | Generally qualified |
| Main Street Capital | 5.73% | $0.265 plus variable supplements | Monthly | Largely ordinary income |
| AbbVie | 2.42% | $1.73 | Quarterly | Generally qualified |
| Chevron | 3.07% | $1.78 | Quarterly | Generally qualified |
| Duke Energy | Not available | $1.085 | Quarterly | Generally qualified |
Taxes Can Flip the Answer for Retirement Savers
Treasury bill interest is subject to federal tax at ordinary income rates but no state or local taxes. For a retiree in a high-tax state, that exemption makes a bill’s yield worth more after taxes than it looks.
Dividends from ordinary corporations such as Duke, AbbVie, Chevron and Altria are generally qualified dividends for most retail holders who meet the holding period. The preferential 0%, 15%, or 20% federal rates apply to qualified dividends, usually below the rate on bill interest. State income tax still applies to them, though.
REIT and BDC payouts lose most of that advantage. Realty Income’s distributions are generally ordinary income, not qualified dividends, and Main Street’s are largely ordinary income. Even distributions of net short-term capital gains from a REIT are not treated as capital gains; they are reported as ordinary dividends. That means the two highest-yielding monthly payers here are taxed at full federal rates and also owe state tax, which bills do not.
All of this applies only to taxable brokerage accounts. The IRS states that these investment-income rules do not apply to investments held in individual retirement arrangements (IRAs), section 401(k) plans, and other qualified retirement plans. Inside an IRA, the qualified-versus-ordinary difference and the state exemption on bills stop mattering, and the comparison comes down to yield, safety and growth.
Who Each Option Suits
Retirees who need a specific amount of cash on a fixed date, live in high-tax states, hold money in taxable accounts, and are willing to accept that their income will change every time a bill matures and gets rolled over are a good fit for Treasury bills. Dividend stocks such as AbbVie, Duke and Chevron suit investors with a long horizon who can sit through price swings and want income that has a chance of rising faster than a rolled bill. Higher yielders such as Realty Income, Altria and Main Street Capital suit income investors who hold them in IRAs, budget only on the regular payment, and keep an eye on dividend coverage every quarter.
The post Treasury Bills or Dividend Stocks? The Retirement Income Math May Surprise You appeared first on 24/7 Wall St..
]]>Brent crude, the global benchmark, settled at $100.20 on October 7, 2026, down 0.38%. West Texas Intermediate, the U.S. benchmark, fell 1.3% to $88.28.
Traders are treating Middle East attacks as an emergency, and stock releases are moving faster. Tropical Storm Isaias is forecast to become a hurricane and reach the northern Gulf Coast.
Energy shares fell anyway. Chevron (NYSE:CVX) dropped 1.17% to $205.16, and Shell (NYSE:SHEL) slid 0.78%.
The State Street Energy Select Sector SPDR ETF (NYSEARCA:XLE) lost 0.58%, and the United States Oil Fund (NYSEARCA:USO) gave up 0.68%. The quiet reaction suggests investors expect a temporary supply interruption.
What Isaias Has Already Taken Offline
The National Hurricane Center put the storm’s maximum sustained winds at 70 mph, just under the 74 mph hurricane threshold. It said, “Isaias is forecast to become a hurricane by Thursday morning.”
The National Hurricane Center’s official forecast peaks at Category 2 with 110 mph winds. It expects landfall “along the U.S. northern Gulf Coast late Friday or early Saturday.”
The Bureau of Safety and Environmental Enforcement reported 511,619 barrels a day of Gulf oil shut in, or 25.08% of output, with 16.37% of gas output shut in and 8 of 371 platforms evacuated.
Shell is “evacuating all personnel and shutting in production” at Mars, Olympus, Ursa, Vito and Appomattox. Chevron began shut-in procedures at four Gulf facilities it operates but did not name.
How Big the Hit Is for Chevron, Shell and the Two Funds
Chevron posted U.S. upstream output of 2,077 thousand barrels of oil equivalent a day in the second quarter. Against $18.095 billion of free cash flow that quarter, a few days of lost output is small. The bigger risk is its Pascagoula, Mississippi, refinery, which sits near the storm’s path.
For Shell, the Gulf is one piece of a global business built on liquefied natural gas, fuel marketing and chemicals. That business brought in $94.664 billion of second-quarter revenue.
XLE holds energy stocks led by Exxon Mobil (NYSE:XOM) at 22.67% and Chevron at 16.09%, plus refiners that earn more when fuel margins widen. USO holds oil futures and replaces expiring contracts monthly. In contango, when later months cost more, each switch sells low and buys high, dragging returns over time.
Why Refineries and Diesel Matter More Than Platforms
Oil shut in stays in the reservoir and flows again once crews return. Refinery damage can keep fuel prices high until the plant restarts. The Gulf Coast holds 54.4% of U.S. refining capacity, while the Gulf supplies about 15% of U.S. crude, according to Energy News Beat.
Diesel matters most because it powers freight and heating. AAA put the national diesel average at $6.30, up from $3.68 a year earlier and below a record $6.53 set on Sept. 22.
U.S. crude stocks fell 3.2 million barrels to 424.1 million, below analysts’ expected 1.7 million-barrel build, leaving a thin buffer of crude supply heading into the storm.
On the other side, emergency releases are still coming, and the forecast could weaken before landfall, which would limit how long any supply loss lasts.
What Isaias Means for XLE and USO Investors
XLE is likely better protected than crude itself. The most likely damage is offshore oil output that pauses and restarts. If a refinery goes down, that widens margins for the refiners the fund owns.
XLE is better positioned than USO for this kind of disruption. USO’s monthly contract switching erodes returns, and any storm gains fade once production restarts. XLE has gained 44.56% year to date, so much of the rally is already priced in.
Watch whether Isaias strengthens beyond the National Hurricane Center’s Category 2 forecast. Second, watch whether Pascagoula or other Gulf refineries report damage. Third, whether the next crude inventory report shows another stock drop. If no refineries are damaged, the storm’s price boost would likely fade once offshore production restarts.
The post Oil Is Already at $100. Now a Hurricane Could Shut Down Gulf Production appeared first on 24/7 Wall St..
]]>Energy has a reputation for boom and bust, yet the sector’s largest companies have turned volatile commodities into some of the market’s most reliable income. Exxon Mobil (NYSE:XOM) alone has grown its annual dividend per share for 43 consecutive years. The four large caps below split into two integrated oil majors and two midstream toll-road operators. Each pairs a well-covered payout with strong cash generation, making them natural candidates for a long-term income portfolio.
Exxon Mobil: 43 Years of Raises Backed by a Fortress Balance Sheet
At a recent price of $163.83, Exxon’s annualized forward dividend of $4.12 per share works out to a 2.51% yield. The quarterly payout is $1.03, up from $0.99 after a 4% raise late last year.
Dividend safety: Coverage is excellent. Exxon produced $26.13 billion of free cash flow last year. In the second quarter alone, it generated more than $17 billion of free cash flow, returned more than $9 billion through dividends and buybacks, and still cut net debt by more than $7 billion. Debt-to-equity is just 0.168, net debt to EBITDA is 0.55x, and interest coverage is 56.3x. For income investors, that means the dividend draws on a small piece of cash flow, with plenty left over for growth.
Bull case: Guyana is moving from an investment phase into a harvest phase. Exxon has “fully recovered the $55 billion of investment” there, and its CFO called the shift “very much an inflection into free cash flow”. Management expects Guyana’s free cash flow to double by the end of the decade compared with last year. Add $16.3 billion of cumulative structural cost savings since 2019 and a $20 billion buyback program for this year, and dividend growth has plenty of support.
Risk: Earnings still move with crude prices and geopolitics. The Middle East conflict caused the “temporary loss of approximately 10% of our upstream production” in the second quarter.
Chevron: Hess Cash Flow Is Funding Bigger Dividend Checks
Chevron (NYSE:CVX) yields 3.45% at a recent price of $206.18, based on an annualized forward dividend of $7.12. The quarterly payout rose to $1.78 from $1.71. It has climbed steadily from $1.19 per quarter in 2019, and the payment record goes back to 1999.
Dividend safety: Second-quarter free cash flow hit $18.10 billion, up 272% from a year earlier, and adjusted free cash flow came in at $15.4 billion. Chevron also paid down more than $8 billion of debt in the quarter, bringing net debt to 0.6 times operating cash flow. Debt-to-equity is 0.251, and interest coverage is 13.7x. The company has now returned over $5 billion to shareholders for 16 straight quarters.
For the bull case: the Hess deal is paying for itself. Synergies reached $1.5 billion, or 50% more than initially targeted, and management said: “The Hess assets are generating strong free cash flow, which has been roughly double the incremental dividends.” Chevron also finished $3 billion of structural cost cuts six months early. It signed a 20-year take-or-pay power agreement to supply AI data centers, which adds contracted cash flow that does not depend on oil prices. Adjusted free cash flow growth is targeted to average greater than 10% per year, using flat commodity prices below today’s levels.
Risk: Higher depreciation from the Hess assets will weigh on reported earnings, even while cash flow stays strong.
Enbridge: 31 Straight Raises From a Utility-Like Pipeline Giant
Enbridge (NYSE: ENB) brings the yield up a level. Its annualized forward distribution of $2.784 in U.S. dollars, against a recent price of $46.11, yields 6.04%. That makes it an ultra-high-yield bar. The quarterly dividend is declared at C$0.9700 per share.
Dividend safety: Enbridge has raised its dividend for 31 consecutive years. Its fee-based pipelines and utilities produced $2.95 billion of distributable cash flow in the second quarter. Management confirmed full-year guidance for distributable cash flow per share of C$5.70 to C$6.10. The Mainline averaged 3.1 million barrels per day during the quarter, so cash flow depends on volume and contracts more than on commodity prices. Debt to EBITDA of 5.1 times sits slightly above the 4.5 to 5 times target range. Management said leverage would be within that range after adjusting for currency moves.
Bull case: A $41 billion secured backlog supports about 5% annual growth in EBITDA and distributable cash flow after this year. Projects include the $4 billion Sunrise expansion and LNG-linked gas pipelines. Enbridge has returned $38 billion to shareholders over the past five years and expects to return between $40 billion and $45 billion over the next five. The shares fell 8.63% over the past month, including a drop on Friday that trailed the broader market, so new buyers get a higher starting yield.
Risk: Currency affects the check you receive. Because the dividend is declared in Canadian dollars, recent U.S.-dollar payments have changed from 0.712 to 0.707 to 0.696, even though the declared amount stayed the same.
Enterprise Products Partners: 1.9x Coverage on a 6% Yield
Enterprise Products Partners (NYSE:EPD) yields 6.10% at a recent price of $36.74, based on an annualized distribution of $2.24. The latest quarterly payout of $0.56 per unit is up 2.8% from a year earlier.
Dividend safety: Of the four names here, this one has the largest margin. Second-quarter operational distributable cash flow of $2.3 billion covered the cash distribution 1.9x. Over the past 12 months, the payout ratio on adjusted cash flow from operations was just 56%. Leverage fell to the partnership’s 3.0 target on a net basis, and about 97% of its debt carries a fixed rate. The partnership’s streak of annual distribution increases runs 27+ years, through several oil crashes.
Bull case: Adjusted EBITDA reached a record $2.83 billion, up 17%, as pipeline volumes rose to a record 14.7 MMBPD. With $6.5 billion of organic projects under construction and about 90% of its LPG export capacity contracted, management sees EBITDA growth in the 10% area from 2025 into 2027. At a forward P/E of 12x, investors pay a modest price for that growth.
Risk: As a master limited partnership, Enterprise mails unitholders a K-1 tax form instead of a 1099. That makes tax filing more complicated, and the units can be a poor fit for some retirement accounts.
Four Energy Payers Built for Decades of Income
Exxon and Chevron offer smaller yields, but their dividends come with strong balance sheets, rapidly growing free cash flow, and long records of raises. Enbridge and Enterprise yield more than 6%, and their payouts rest on fee-based pipelines, multi-decade growth streaks, and visible project backlogs. Together, they cover both sides of the energy income trade: dividend growth from the oil majors and high current yield from the toll roads.
The post 4 Historically Reliable High-Yield Dividend Stocks Ripe for Long-Term Income Seekers appeared first on 24/7 Wall St..
]]>Our 24/7 Wall St. price target for ExxonMobil (NYSE:XOM) is $132.90 over the next 12 months. That compares with a current price of $164.01.
| Metric | Value |
|---|---|
| Current Price | $164.01 |
| Price Target from 24/7 Wall St. | $132.90 |
| Upside/Downside | -18.97% |
| Model Rating | SELL |
| Confidence Level | 90% |
ExxonMobil gets a sell rating with high confidence from the model. The main reason is valuation: after a big run, the shares price in more earnings than consensus forecasts support. The rating reflects price only. The business itself keeps getting stronger.
Why We Could Be Wrong About ExxonMobil
The bull case rests on Guyana, where Exxon has already recovered its $55 billion investment, so more of that output now becomes into free cash flow. Treat our target as one data point among many.
A 38% Rally Built on Disruption and Execution
The stock is up 38.52% year to date and 51.08% over the past year. Shares trade near the top of a 52-week range of $107.28 to $174.09.
In the second quarter, Exxon gets $14.5 billion, generated more than $17 billion of free cash flow and cut net debt by more than $7 billion. First-quarter adjusted EPS of $1.16 beat the $1.01 estimate.
Why Bulls See $170 and Beyond
The $1.03 quarterly dividend continues a 43-year growth run. Guyana produced about 900,000 barrels per day gross, and a fifth FPSO (floating production vessel) is due to start up by year-end. Permian output hit a record of more than 1.8 million barrels of oil equivalent per day.
Structural cost savings reached $16.3 billion against a $20 billion goal for 2030, and a $20 billion buyback plan is in place for 2026. Management expects “two times the level of free cash flow in 2030 than we saw in 2025.”
The consensus analyst target is $173.41, with 10 of analysts rating the stock a buy or better. Our own bull scenario reaches $171.79 over five years.
Oil Price Normalization Could Undo the Premium
The stock trades at a trailing P/E of 23, while the price-to-free-cash-flow ratio is at 28.58. The effective tax rate rose to 40% in the first quarter.
Our bear case points to $122. First-quarter GAAP profit was weighed down by a $3.88 billion derivative timing charge, but underlying earnings rose to $8.77 billion.

How ExxonMobil Compares to Chevron and Shell
Chevron (NYSE:CVX) is the closest U.S. integrated peer with Guyana exposure through Hess. The stock’s trailing P/E is 33 and the yield is 3.14%. By that measure, Exxon’s multiple looks moderate.
Shell (NYSE:SHEL) offers a contrast in LNG and integrated operations. Its second-quarter EPS of $1.92 missed the $3.18 estimate, though free cash flow reached $17.5 billion.
| Company | Market Cap | Q2 2026 Free Cash Flow |
|---|---|---|
| ExxonMobil | $672.05B | >$17B |
| Chevron | $400.2B | $18.1B |
| Shell | $272.4B | $17.5B |
Exxon generates free cash flow similar to its peers while carrying the largest market value of the group. Against these peers, our target looks somewhat conservative.
ExxonMobil Price Prediction 2026-2030
The 24/7 Wall St. price target of $132.90 carries a sell model rating at 90% confidence. What tips the scale is the forward earnings outlook as oil prices return to normal.
I would become more constructive if Guyana’s free cash flow inflection shows up in earnings forecasts. Until then, the price already reflects much of the good news.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $132.90 |
| 2027 | $132.58 |
| 2028 | $120.04 |
| 2029 | $116.43 |
| 2030 | $115.91 |
ExxonMobil needs to keep executing its current strategy for these projections to hold. A longer disruption in the Strait of Hormuz, or new finds in Guyana, could move results significantly higher.
The post ExxonMobil’s Dividend Story Is Only Part of the Bull Case appeared first on 24/7 Wall St..
]]>Retirement changes how income works on the day the paychecks stop. Social Security covers part of the monthly bill, and the rest has to come from savings, an annuity, or a portfolio that pays cash on a schedule. Selling shares to cover groceries works fine until a bear market forces those sales at bad prices. Dividends let a retiree collect income and keep the same number of shares.
That is why companies with decades of dividend increases show up in so many retirement income plans. These businesses kept raising their payouts through recessions, oil crashes, and rate cycles. Here is what investing $20,000 in each of these five long-tenured dividend growers would pay: a $100,000 total investment producing more than $3,700 in annual passive income, based on forward dividends and current share prices.
The profiles count down from the lowest forward yield to the highest. Every yield below uses the forward convention.
Coca-Cola
- Stock #5: Coca-Cola (NYSE:KO)
- Yield: 2.45%
- Shares for $20,000: 231.5
- Annual Passive Income: ~$491
Coca-Cola is the world’s largest non-alcoholic beverage company. It sells the concentrates and syrups behind Coca-Cola, Sprite, Fanta, smartwater, BODYARMOR, fairlife, and Topo Chico, while bottling partners carry much of the capital load. That asset-light setup produced a 34.9% operating margin. Second-quarter 2026 revenue rose 6.7% year over year to $13.38 billion, global unit case volume grew 5%, and Coca-Cola Zero Sugar gained 16%.
The yield comes from a mature consumer staples business that hands most of its cash back to shareholders. The forward dividend of $2.12 per share is about 64% of trailing EPS of $3.33. Management also raised 2026 guidance to free cash flow of about $12.4 billion and comparable EPS growth of 9% to 10%. Coca-Cola is a Dividend King with 60+ straight years of increases, and the quarterly payout went from $0.51 in 2025 to $0.53 in 2026.
AbbVie
- Stock #4: AbbVie (NYSE:ABBV)
- Yield: 2.62%
- Shares for $20,000: 75.8
- Annual Passive Income: ~$525
AbbVie is a global drugmaker built around the immunology treatments Skyrizi and Rinvoq, with neuroscience, oncology, and aesthetics franchises behind them. Second-quarter revenue grew 10.2% to $16.99 billion, and adjusted EPS came in at $3.65. Skyrizi rose 24.4% to $5.51 billion, and Rinvoq rose 24.5% to $2.53 billion, more than covering a 36.1% Humira decline caused by biosimilars.
Big, cash-generating drug franchises pay for a generous dividend policy. The forward dividend of $6.92 is roughly 50% of the midpoint of 2026 adjusted EPS guidance of $13.87 to $14.07. The quarterly payment has grown from $0.40 in 2013 to $1.73. The next one is scheduled for November 16, 2026. The main risk is the debt behind the pending $10.9 billion Apogee Therapeutics deal. On the July call, the CFO said, “We remain committed to achieving a net leverage ratio of two times within two to three years following the deal close.”


Chevron
- Stock #3: Chevron (NYSE:CVX)
- Yield: 3.45%
- Shares for $20,000: 97.0
- Annual Passive Income: ~$691
Chevron is an integrated oil major. It produces oil and gas in the Permian Basin, the Gulf of America, and on former Hess assets, and it also refines fuel. The Hess deal raised production 20% year over year to 4.07 million barrels of oil equivalent per day (MMBOED), and second-quarter revenue rose 51% year over year to $67.2 billion.
Mature integrated oil companies put shareholder returns at the top of their capital plans, and that keeps the yield competitive even with shares up 39% year to date. Coverage is strong. Second-quarter operating cash flow reached $22.6 billion, and free cash flow hit $18.1 billion. The forward dividend of $7.12 is about 68% of trailing EPS of $10.40. Chevron raised the quarterly payout to $1.78 from $1.71, bought back $3.1 billion of stock in the quarter, and hit $3 billion in run-rate cost cuts six months ahead of schedule.
Franklin Templeton
- Stock #2: Franklin Templeton (NYSE:BEN)
- Yield: 4.00%
- Shares for $20,000: 606.4
- Annual Passive Income: ~$800
Franklin Resources changed its corporate name to Franklin Templeton on August 17, 2026, and the stock still trades as BEN. The global asset manager managed $1.79 trillion as of June 30, 2026, spread across equity, fixed income, multi-asset, and alternatives. It earns fees on those assets. The business needs little capital, so most of its cash can go to shareholders. Fees move with the markets, though, which helps explain a beta of 1.57.
Fiscal third-quarter adjusted EPS of $0.72 covers the $0.33 quarterly dividend, a payout of about 46%. The adjusted operating margin expanded to 28.0% from 23.7%, and long-term net inflows reached $18.4 billion. The company returned $521.5 million to shareholders in the quarter. On the earnings call, management said, “We’re always focused on making sure that we’re in a position where we can continue to increase our dividend. That’s always a high priority.”
Realty Income
- Stock #1: Realty Income (NYSE:O)
- Yield: 6.04%
- Shares for $20,000: 370.9
- Annual Passive Income: ~$1,208
Realty Income is a net-lease real estate investment trust (REIT) that owns single-tenant commercial properties, and its exposure to gaming, data centers, and industrial assets is growing. It pays monthly. The latest $0.2715 payment is due October 15, 2026, and the company raised its dividend for the 115th consecutive quarter.
As a REIT, Realty Income has to distribute 90% of its taxable income, and that rule sets its baseline yield. An 11.89% share price drop over the past month drove the yield into ultra-high-yield territory. The right test for a REIT is adjusted funds from operations (AFFO) coverage. AFFO per share was $1.09 in the second quarter, up 3.8%, and 2026 guidance was raised to $4.44 to $4.45. That puts the forward payout near 73% of AFFO. Occupancy stands at 98.8%, Fitch rates the company A, and management raised 2026 investment volume guidance to $10 billion after announcing a $6 billion hyperscale data center joint venture.
How the $100,000 Portfolio Adds Up
| Name | Yield | Annual Dividend Income |
|---|---|---|
| Coca-Cola | 2.45% | $491 |
| AbbVie | 2.62% | $525 |
| Chevron | 3.45% | $691 |
| Franklin Templeton | 4.00% | $800 |
| Realty Income | 6.04% | $1,208 |
| Total | 3.72% | $3,715 |
Together, the five positions generate $3,715 in annual passive income on a $100,000 investment, a blended yield of 3.72%. Realty Income contributes $1,208, Franklin Templeton adds $800, Chevron supplies $691, AbbVie adds $525, and Coca-Cola rounds out the group with $491.
Timing matters as much as the total for anyone budgeting around these payments. Realty Income pays every month and the other four pay quarterly, so checks arrive regularly throughout the year. Because five different industries fund the income, a weak year in oil, drug pricing, or asset management would hit only part of it.
The post $100,000 in 5 Dividend Kings Will Generate Close to $4,000 Each Year Safely appeared first on 24/7 Wall St..
]]>A $180,000 salary is $15,000 a month. Replacing that paycheck with portfolio income comes down to one equation: income target divided by yield equals capital required. The yield you choose swings the answer from about $1.3 million to more than $5 million. The sections below cover three yield levels, a sample combined portfolio, and the compounding math that changes the comparison.
Conservative Tier (3% to 4%): Highest Capital, Steadiest Income
At 3.5%, $180,000 divided by 0.035 equals $5,142,857. At 4%, $180,000 divided by 0.04 equals $4,500,000. This level holds dividend growth funds, broad high-dividend ETFs, and blue-chip dividend payers.
Chevron (NYSE:CVX) yields about 3.4%. Its quarterly dividend rose from $1.08 in 2017 to $1.78, a 65% increase, and second-quarter free cash flow came in at $18.1 billion. The iShares Core High Dividend ETF (NYSEARCA:HDV) and the iShares Core Dividend Growth ETF (NYSEARCA:DGRO) each charge 0.08% a year. DGRO’s forward payout is about 2.0%, which falls below the levels because its holdings raise dividends faster.
The tradeoff: you need the most capital upfront, but income cuts are least likely, and the principal tends to grow over time.
Moderate Tier (5% to 7%): Less Capital, Slower Raises
At 5%, $180,000 divided by 0.05 equals $3,600,000. At 7%, $180,000 divided by 0.07 equals $2,571,429. REITs, midstream partnerships, preferred shares, and high-dividend equity funds fill this range.
Enterprise Products Partners (NYSE:EPD) yields about 6.2%, with distributions up 2.8% year over year and covered 1.9x. Unitholders receive a K-1 tax form. VICI Properties (NYSE:VICI) yields about 7.9% and reports 100% occupancy, yet its shares fell 26% over the past year. Most leases carry 2.0% annual rent increases, which caps how fast income can grow.
Here you give up dividend growth, and over several decades the income may fall behind inflation.
Aggressive Tier (8% to 14%): Smallest Check, Shrinking Principal
At 8%, $180,000 divided by 0.08 is $2,250,000. At 12%, it is $1,500,000. At 14%, it equals $1,285,714. Typical holdings include leveraged covered call funds, business development companies, mortgage REITs, and high-yield bond funds.
The Goldman Sachs S&P 500 Premium Income ETF (NASDAQ:GPIX) is a good entry point. Its forward distributions mean about 8.5%, paid monthly, and it sells options against an S&P 500 portfolio, which limits upside. Higher up this range, distribution cuts and principal erosion become common. Investors at these yields are often spending down the asset.
Combined the Tiers Into a 5.1% Portfolio
One sample mix holds HDV 25%, DGRO 15%, GPIX 20%, VICI 15%, CVX 10%, and EPD 15% for a combined yield of 5.10%. $180,000 divided by 0.051 equals about $3,529,412. The 10-year Treasury currently yields 5.24%, slightly above that blend. The stock portfolio has to earn its place through dividend growth and price appreciation, since the Treasury pays more today.
Why the Smaller Yield Can Pay More Later
Put $5,142,857 to work at 3.5% and grow the dividends 8% a year. After nine years, the portfolio pays about $359,821 a year. A $1,500,000 portfolio yielding 12% with no growth still pays $180,000 in year nine, and inflation has cut what that money buys. The conservative investor needs more money on day one and gets a paycheck that keeps rising.
Three Steps Before Choosing a Tier
- Add up what you actually spend each year. Payroll taxes and retirement contributions come out of a $180,000 salary but do not apply to dividend income, so the amount you need to replace may be well below $15,000 a month.
- Run the after-tax numbers for each level in your bracket. Chevron and the iShares funds pay qualified dividends at lower tax rates, VICI’s REIT dividends are mostly taxed as ordinary income, and Enterprise’s distributions come with K-1 reporting.
- Look at payout histories side by side. DGRO paid $0.175 per share in its September 2016 distribution and $0.385 in September 2026. Check whether a high-yield fund you are considering grew its payout over the same stretch.
The post How Much Do You Really Need Invested to Replace a $180,000 Salary With Dividends? appeared first on 24/7 Wall St..
]]>On CNBC on Friday, Oct. 2, Michael Cuggino, president of Permanent Portfolio Family of Funds, said energy stocks “have not kept up with the broader market even as we speak.” He used that point to recommend Chevron (NYSE:CVX) and ExxonMobil (NYSE:XOM) as cheap total-return plays. The performance numbers point the other way.
Oil Majors Have Outrun the Index by a Wide Margin
As of Friday’s close on Oct. 2, Exxon is up more than 34% over the past year at $164.39. Chevron is up nearly 33% at $207.20. Over the same period, the S&P 500 gained less than 13%. Chevron also set a 52-week high of $214.06 on Sept. 11. Over the last month, the benchmark index edged up 0.75%, while Chevron lost 2.16% and Exxon gained 0.15%.
Cuggino’s Valuation Case Holds Up, With One Adjustment
Cuggino’s argument is about price. He said both stocks trade at about 13 times next year’s earnings, with dividend yields of 3.5% and 2.5%. He compared that with an S&P 500 offering a 4.5% earnings yield. Checked against consensus 2027 EPS of $14.1367 for Chevron and $11.0760 for Exxon, both stocks trade closer to 15x. Their current yields are 3.42% and 2.53%. That is a little more expensive than the on-air figure, but still a discount to the market.
Others share his view. On Sept. 8, Jim Cramer called Chevron the portfolio version of a kicker: an excellent 3.44% yield that usually doesn’t move with the rest of the market.
Rising Earnings Estimates Explain the Rally
Chevron’s second quarter brought adjusted EPS of $6.06, revenue up 51.4% to $67.20B, and free cash flow of $18.1 billion. Brent averaged $104 per barrel in the quarter. CEO Mike Wirth said: “Costs always matter. They always will.”
Analysts have been raising their numbers. The 2027 consensus for Chevron was $12.6254 90 days ago. Over the past 30 days, 10 analysts revised up and 3 revised down. Exxon CEO Darren Woods described a quarter with “more than $14 billion of earnings, more than $17 billion of free cash flow, and a more than $7 billion reduction in net debt.”
Microsoft Is Buying Chevron’s Power for AI
Chevron signed a 20-year take-or-pay power purchase agreement with Microsoft (NASDAQ:MSFT). The deal covers 2.67 gigawatts of capacity for a West Texas data center complex, and Chevron expects “mid-teens returns.” Wirth said the company is ready “to help power American AI dominance.” The companies building AI depend on energy majors to grow, and this deal gives Chevron a long-dated source of committed revenue.
A Slide in Crude Would Undercut the Pitch
WTI peaked at $102.13 in May and fallen to $83.9 by August. In its May outlook, the EIA forecast Brent averaging $79.39 in 2027. If prices follow that path, estimates shrink and today’s 15x multiple looks less cheap. Wall Street is also split: Chevron has 20 Buy ratings or Strong Buy ratings, while Exxon has 15 Hold ratings.
The stocks have already outpaced the market on returns. The case for owning them now rests on valuation, income and earnings revisions. Watch the third-quarter reports, where consensus calls for $4.7322 per share at Chevron and $3.6501 at Exxon.
The post 49% Gains Haven’t Stopped Wall Street From Calling Energy Stocks ‘Behind’ appeared first on 24/7 Wall St..
]]>Five companies in five different industries pay these dividends: drugs, oil, pipelines, private credit and nicotine. Each one is supported by cash flow that covers the payout today and a track record that shows how management handles it. Forward yields run from 2.63% to 10.18%, and the most recent sign of confidence came days ago, when Philip Morris International (NYSE:PM) raised its quarterly dividend to $1.60 from $1.47. That is an 8.8% increase. A look at each payout’s cash flow and balance sheet shows how they hold up.
AbbVie: Immunology Growth Is Paying for a Rising Dividend
AbbVie (NYSE:ABBV) pays an annualized forward dividend of $6.92. At the latest price of $262.90, that works out to a 2.63% forward yield. The next ex-dividend date is October 15, 2026, and payment follows on November 16, 2026. Its yield is the lowest on this list. AbbVie earns its place through dividend growth and coverage.
Dividend safety: AbbVie’s GAAP trailing EPS of $3.54 sits below the dividend because acquired research charges drag on reported earnings. That drives the trailing P/E to about 74x. Adjusted earnings give a better picture of cash. Management’s adjusted EPS guidance of $13.87 to $14.07 puts the forward dividend at about 50% of the center. The free cash flow yield of 3.83% is higher than the dividend yield. Net debt stands at 2.26x EBITDA, and interest coverage is 6.94x. The dividend history shows a higher quarterly payment every year since AbbVie began trading as a standalone company in 2013. The payment has gone from $0.40 in 2013 to $1.73 in 2026.
Bull case: AbbVie has replaced most of what it lost when Humira’s patent protection ended. Second-quarter results showed Skyrizi sales rising 24.4% to $5.505 billion and Rinvoq sales climbing 24.5% to $2.525 billion. Humira fell to just $756 million. Neuroscience grew 20.3% to $3.23 billion, and total revenue reached $16.99 billion, up 10.2% from a year earlier. The stock trades at about 16x forward earnings. The average analyst target is $278.86, with 8 strong buy and 16 buy ratings.
Risk: Acquisitions keep moving earnings guidance around. A pending $10.9 billion deal knocked $0.14 off the 2026 outlook. Meanwhile, Imbruvica sales fell 29.4%, so the immunology drugs have to keep growing quickly to make up the difference.
Chevron: Record Output and a 39-Year Raise Streak
Chevron (NYSE:CVX) pays $1.78 per quarter, an annualized $7.12. That is a 3.44% forward yield at $206.79. The yield has come down this year because the stock is up 39.38% year to date.
Dividend safety: Chevron generated $18.095 billion in second-quarter free cash flow. Based on the current share count, one quarter’s dividend costs about $3.49 billion. The dividend matches about 69% of trailing EPS of $10.38. The balance sheet is conservative. Net debt is 1.08x EBITDA, debt-to-equity is 0.25, and interest coverage is 13.7x. Chevron also paid down $8.41 billion of debt during the quarter. The company called its most recent increase its 39th consecutive annual raise, and the dividend history supports the recent run: $1.51 in 2023, $1.63 in 2024, $1.71 in 2025 and $1.78 in 2026.
Bull case: The Hess acquisition is paying off. Worldwide production rose 20% to 4,070 MBOED, and U.S. upstream output hit a record 2,077 MBOED. Chevron reached $3 billion in annual structural cost savings six months early and captured $1.5 billion in Hess synergies within a year of closing. It also signed a 20-year, 2.67 GW agreement to supply power to an AI data center in Texas. CEO Mike Wirth said the quarter delivered “record U.S. upstream production, record crude throughput in our U.S. refineries, and exceptional reliability across key assets.” The stock trades at about 15x forward earnings, and analysts’ average target is $224.62.
Risk: High oil prices drove much of the second-quarter result. Brent averaged $104 per barrel, compared with $68 a year earlier. In the first quarter, free cash flow was negative $1.549 billion, so cash generation can swing sharply from one quarter to the next.
MPLX: Ultra-High-Yield Distributions With 12.5% Raises Planned
MPLX (NYSE:MPLX) pays $1.0765 per unit each quarter, or $4.306 a year. At $56.39, that is a 7.64% forward yield, which puts MPLX firmly in ultra-high-yield territory. The units are down 4.42% over the past month. MPLX is a master limited partnership, so unitholders get a K-1 tax form instead of a 1099.
Dividend safety: Second-quarter distributable cash flow of $1.45 billion covered the distribution with room to spare. Management is aiming a 1.3 coverage ratio for 2026, 2027 and beyond. Leverage is 3.7x, below the partnership’s 4.0x target. The payout went from $0.85 in 2024 to $0.9565 and then $1.0765, which matches two straight raises of 12.5%. Management said on the call that it does not need acquisitions to hit its 2027 coverage goal.
Bull case: Natural gas volumes are driving growth. Operated gathering throughput rose 15% to 6,859 MMcf/d, and Natural Gas and NGL Services adjusted EBITDA increased 11% to $614 million. Harmon Creek III started operating in August. The Blackcomb pipeline should be in full service in the fourth quarter, and BANGL volumes are expected to reach 300,000 barrels per day by year-end. CEO Maryann Mannen said MPLX “anticipate[s] growing our distribution at this rate again in 2026 and in 2027.” Analysts’ average target is $62.85.
Risk: MPLX depends heavily on its parent refiner, which is its primary customer. It is also spending more: 2026 growth capital rose by $500 million to $2.9 billion, interest expense is going up, and crude pipeline throughput fell 5%.
Ares Capital: A 10% Yield Backed by $1.38 Per Share in Spillover Income
Ares Capital (NASDAQ:ARCC) pays $0.48 per quarter, or $1.92 a year. At $18.86, that is an ultra-high 10.18% forward yield. The shares trade just below net asset value (NAV) per share of $19.35, at a price-to-book ratio of 0.99.
Dividend safety: Second-quarter core EPS of $0.47 came in a cent below the dividend. Management pointed to the longer record: “Over the last 12 months, core earnings have exceeded our regular dividend.” Ares Capital also has an estimated $988 million of spillover income, or $1.38 per share. That is taxable income it earned in the past and can still pay out, which gives it a buffer. Leverage is 1.12x debt-to-equity net of cash. Liquidity is about $6 billion, and no more unsecured notes mature in 2026. The company has paid a steady or higher regular dividend for 68 consecutive quarters, and the payout has been $0.48 every quarter since March 2023.
Bull case: Ares Capital is the largest publicly traded business development company (BDC). Its portfolio totals $29.35 billion across 619 companies, and 71% of it is floating rate. The weighted average yield on its debt investments is 10.3%. New senior loan spreads were 20 basis points wider than in late 2025. A new commercial paper program could cut funding costs by 50 to 100 basis points compared with secured borrowings. Analysts’ average target is $20.77.
Risk: Credit quality is slipping. Non-accrual loans rose from 2.1% to 2.4% at cost during the quarter. NAV per share fell to $19.35 from $19.94 at the end of 2025, and $183 million in unrealized losses cut GAAP EPS to $0.24.
Philip Morris International: A Fresh Raise Funded by Smoke-Free Growth
Philip Morris’s new annualized dividend of $6.40 works out to a 3.41% forward yield at $187.50. The stock went ex-dividend on October 2, 2026, so anyone buying now will first collect the higher payment in January.
Dividend safety: The new payout matches about 77% of the center of 2026 adjusted EPS guidance, which is $8.26 to $8.41. That level is steep for a typical company but manageable for a tobacco cash machine. Philip Morris expects about $13.5 billion of operating cash flow this year against $1.4 billion to $1.6 billion of capex, and it is buying back no shares. Net debt is $43.1 billion, or 2.35x adjusted EBITDA, and the company is aiming for around 2.0x by year-end. Quarterly payments have continued without a break since 2008, and the payment has risen from $1.17 in 2020 to $1.60 now.
Bull case: Second-quarter revenue grew 10.4% to $11.19 billion, and adjusted EPS of $2.20 beat the $2.05 estimate. International smoke-free revenue rose 14.2%, and VEEV vape shipments jumped 55.1%. The FDA authorized 20 ZYN variants as modified-risk tobacco products, which lets them be marketed as lower risk. Operating cash flow rose 61.0% to $5.49 billion. CEO Jacek Olczak said the company drove “net revenues to over $11 billion for the first time.” Analysts’ average target is $208.13.
Risk: More competition in U.S. oral nicotine is weighing on ZYN sales. Philip Morris also took a $511 million non-cash impairment, and Poland’s flavor ban hits its heated tobacco business.
Five Payouts Backed by Cash Flow
All five payouts are supported by a clear source of cash: AbbVie’s immunology drugs, Chevron’s balance sheet, MPLX’s target of 1.3x coverage, Ares Capital’s spillover income and Philip Morris’s growing smoke-free business. Together, they offer a mix of growing dividends and high current income from five different sectors. For the rest of the year, keep an eye on Ares Capital’s non-accruals and MPLX’s second-half project ramp.
The post 5 High-Yield Dividend Stocks to Buy for October Income with Cash Flow to Spare appeared first on 24/7 Wall St..
]]>A $160,000 salary puts a 58-year-old near peak earnings and within a decade of Social Security’s full retirement age of 67. To replace that paycheck with portfolio income, start with one equation: divide the income target by the portfolio yield to get the required capital. Run the math at three yield levels, then test it on a six-holding sample portfolio, and you’ll likely get a result similar to the figures below.
Capital Required at Every Yield Level
| Tier | Yield | Capital Needed for $160,000 |
|---|---|---|
| Conservative | 3.5% to 4% | $4.57 million to $4.0 million |
| Moderate | 6% to 7% | $2.67 million to $2.29 million |
| Aggressive | 10% to 12% | $1.6 million to $1.33 million |
Conservative Tier Demands the Most Capital and Grows Income
Start by taking $160,000 and dividing by 0.035 is about $4,571,000. This tier holds dividend growth funds, broad high-dividend ETFs, and blue chips. WisdomTree U.S. Quality Dividend Growth Fund (NASDAQ:DGRW) yields about 1.2% on a trailing basis. iShares Core High Dividend ETF (NYSEARCA:HDV) yields roughly 3% and charges 0.08%.
Income growth is the return for investors in this tier. AbbVie (NYSE:ABBV) lifted its quarterly dividend from $1.64 to $1.73, a raise of about 5%, and yields about 2.7%. Chevron (NYSE:CVX) went from $1.71 to $1.78 and yields about 3.5%.
Moderate Tier Cuts the Requirement but Slows Growth
Another option is to take $160,000 and divide by 0.06, which is about $2,667,000. REITs, preferred shares, and covered call strategies live here. Dividend growth slows, and income may trail inflation over a 30-year retirement.
The REIT VICI Properties (NYSE:VICI) now yields about 8% because its shares fell 26% over the past year, even as it raised its quarterly payout to $0.46. Its leases carry roughly 2% annual escalators. The 10-year Treasury sets the benchmark: at 5.3%, it gives moderate-tier income without equity risk.
Aggressive Tier Pays Now and Erodes Principal
The third option is to take $160,000 and divide by 0.12, which results in about $1,333,000. Business development companies, mortgage REITs, and option-income funds dominate. Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD) yields about 10.4% trailing. Over the past decade, its share price slid about 7%, and its total return of about 126% trailed DGRW’s 267%.
Testing a Six-Holding Income Portfolio
Take this mix: DGRW 15%, HDV 20%, XYLD 20%, VICI 15%, AbbVie 15%, and Chevron 15%. Its combined yield is about 5%, meaning roughly $3.2 million to produce $160,000.
The covered call and REIT positions supply current cash. The dividend growers supply the increases, which help offset the flat payouts on the high-yield side (we laid out this mix-the-paycheck approach, with the payout calendar and withdrawal order, in a free guide here: The Paycheck Portfolio Method).
Why Lower Yields Can Out-Earn Higher Ones
A $4.57 million portfolio at 3.5% pays $160,000 in year one. If those dividends grow 8% a year, income makes about $320,000 in nine years, when this investor turns 67. A $1.33 million portfolio at 12% with no growth still pays $160,000, and inflation cuts what that buys.
At 58, a 25-year to 35-year horizon gives compounding time to work. Sequence-of-returns risk (the danger that poor returns arrive just as withdrawals begin) is highest in the years just before and after retirement, so a heavy aggressive allocation leaves less room to recover from early losses.
Three Steps to Take Before Choosing a Tier
- Measure actual spending. After payroll taxes, retirement contributions, and a paid-off mortgage, the real target may sit well below $160,000, which moves you into a lower row of the table.
- Compare 10-year total returns. Compare a dividend growth fund with a covered call fund over the same period. The gap between DGRW and XYLD shows how high payouts can trade away long-term wealth.
- Model taxes by account. Qualified dividends from AbbVie and Chevron receive lower rates, while REIT distributions and covered-call distributions are often taxed as ordinary income. At peak-bracket earnings, holding VICI and XYLD in IRAs can raise after-tax income.
The post How Much Does a 58-Year-Old Need Invested to Replace a $160,000 Salary With Dividends? appeared first on 24/7 Wall St..
]]>Energy dividends are paid out of oil and gas sales, and the companies don’t control the price of either. When crude is high, every payout looks safe. When crude falls, a weak balance sheet shows up fast. Right now prices are working in shareholders’ favor: Brent averaged $103.85 per barrel in the second quarter, and the big producers are using that cash to pay down debt, buy back stock and raise dividends. For an income investor, the real question is which payouts would still hold when oil falls. Below, Exxon Mobil (NYSE:XOM), Chevron (NYSE:CVX), BP (NYSE:BP) and Occidental Petroleum (NYSE:OXY) are compared on coverage, free cash flow, debt and dividend history, starting with the safest.
Exxon Mobil: 43 Straight Years of Raises Backed by a Fortress Balance Sheet
Exxon yields 2.56%. It is a fully integrated major. It pumps oil and gas in the Permian Basin, Guyana and its LNG projects, then processes that output and turns it into chemicals. Those best assets made up 59% of 2025 production, and total output reached a new high of 4.7M boe/d. Having refining and chemicals helps when crude prices fall, because cheaper oil brings down the cost of their raw material.
Dividend safety: This is the strongest income profile in the group. The forward annual dividend is $4.12 per share, compared with trailing diluted EPS of $7.81. The free cash flow yield of 3.50% is higher than the dividend yield, so the payout is covered by cash the business actually brings in. Exxon generated $26.13B of free cash flow in 2025. Debt is low: the debt-equity ratio is 0.168, net debt to EBITDA is 0.548, and earnings cover interest costs 56.3x. Exxon says it has grown annual dividend per share for 43 consecutive years. The quarterly payout went from $0.95 in 2024 to $0.99 in 2025 and is now $1.03.
Bull case: Exxon has cut $15.6B in structural costs since 2019 and is aiming for $20B by 2030. It also plans $20B of share repurchases this year. Fewer shares outstanding makes each future raise cheaper to fund. The stock trades at 21 and 15 times trailing and forward earnings, respectively. The CEO, Darren Woods, said “ExxonMobil is a fundamentally stronger company than it was just a few years ago,” and called it a “durable platform to grow earnings, cash flow, and shareholder value through 2030 and beyond.”
Risk: Reported earnings can swing a lot. In the first quarter, net income fell to $4.18B after a $3.88B mark-to-market timing charge and $706M in losses from Middle East supply disruptions. The effective tax rate also rose to 40%.
Chevron: Bigger After Hess and Generating Cash Fast
Chevron yields 3.14%, which is the most income of the two US majors. It is also integrated, with production, processes, chemicals and now power generation. After buying Hess, it is much larger: worldwide production grew 20% from a year earlier to 4,070 MBOED in the second quarter, and US refineries ran at 97% utilization.
Dividend safety: The forward annual dividend is $7.12, compared with trailing diluted EPS of $10.38. The free cash flow yield of 4.08% is above the dividend yield. Second-quarter operating cash flow was $22.63B against capex of $4.54B, leaving $18.10B of free cash flow. Chevron used part of that to repay $8.41B of debt. The debt-equity ratio is 0.251 and interest coverage is 13.7x. The dividend has gone up in every year of the recent record: from $1.12 a quarter in 2018 to $1.29 in 2020, $1.71 in 2025 and $1.78 now. That includes a raise during 2020, when oil prices fell.
Bull case: The Hess deal is already paying off. Chevron reached a $3B annual run rate of cost savings six months ahead of plan and captured $1.5B in Hess synergies within a year. It has now returned over $5 billion to shareholders for the 16th consecutive quarter. It also signed a 20-year power deal for a 2.67 GW West Texas AI data center project, which adds a source of income that doesn’t depend on oil prices. The forward P/E is 15.
Risk: Hess added debt. Net debt to EBITDA is 1.08, compared with Exxon’s 0.548. That gives Chevron less of a cushion if a long oil downturn hits while it is still integrating the deal.
BP: The Biggest Yield, With a Turnaround Attached
BP yields 4.59%, the highest in this group. US investors own it through an American Depositary Share (ADS), which trades on the NYSE in dollars and represents a set number of BP’s London-listed ordinary shares. BP announces its dividend in cents per ordinary share and then converts it to a per-ADS amount. The latest payout was 8.660 cents per ordinary share, or $0.5196 per ADS. BP is an integrated major with a large processes business, which helped this year: its refining margin indicator was $29.6/bbl versus $11.9/bbl a year earlier.
Dividend safety: Coverage is fine at current oil prices. Second-quarter operating cash flow was $10.86B against capex of $3.09B. Its finances are weaker. Net debt was $25.3B at the end of the first quarter, up from $22.2B at year end. The dividend history includes a cut: the ADR payout fell from $0.63 to $0.315 in 2020. It has been raised steadily since then and recently went from $0.4992 to $0.5196.
Bull case: On forward earnings, BP is the cheapest stock here at 10 times. Management expects $8 to $9B in divestment proceeds this year, including the roughly $6B Castrol sale, and has raised its cost-cutting target to $6.5 to $7.5B by 2027. The CEO, Meg O’Neill, has been direct about BP’s problems: “Our performance over the past few years has not met our own expectations… we have written off too much value; and our costs and liabilities are not resilient enough in a low price environment.”
Risk: BP carries liabilities its US peers don’t. It still has $6.9B in Gulf of America oil spill provisions on the books, it expects about $1.6B in settlement payments this year, and its UK operations pay an Energy Profits Levy with a 78% headline rate through March 2030.
Occidental Petroleum: A Fast-Growing Dividend Tied Directly to Crude
Occidental yields 1.82%, and it is a different kind of company from the other three. It is classified as an Oil & Gas E&P company, meaning exploration and production. It has no large refining business to absorb a drop in crude, and it has sold its OxyChem chemicals unit. Its cash flow therefore rises and falls almost directly with the price of oil. Its realized crude price was $96.78/bbl in the second quarter.
Dividend safety: The current payout is easy to cover. The forward annual dividend is $1.12, compared with trailing diluted EPS of $3.39, and second-quarter free cash flow was $3.02B. The company is still paying down debt. Principal debt fell to $13.3B in the first quarter and to $11.8B in the second, and the next target is $10.0B. Its dividend record is the weakest of the four. In 2020 the quarterly payout went from $0.79 to $0.01. It has since been rebuilt to $0.28.
Bull case: Dividend growth is the main appeal here. The payout has been increased 8% this year, and the next payment is on October 15. Operations are improving: production of 1,433 Mboed beat guidance, and operating costs fell to $8.70/BOE. Goldman Sachs (NYSE:GS) is getting more positive, with Barron’s reporting a Goldman upgrade this week.
Risk: Occidental has the most to lose if oil prices fall. In its May outlook, the EIA forecast OPEC output recovering from 20.90 million barrels per day in the second quarter of 2026 to 28.28 million in the fourth quarter. More supply would brings down the prices that are currently funding Occidental’s debt paydown.
Where Big Oil Income Lands Now
Exxon Mobil and Chevron are the most reliable income in this group: both cover their dividends with free cash flow, both carry little debt, and both kept raising the payout through the 2020 oil crash. BP offers the highest yield, but that yield depends on its recovery and on paying down debt. Occidental cut its dividend in 2020 and is now growing it quickly, which makes it a payout to keep an eye on in a downturn more than a foundation for an income portfolio. When oil prices fall, the dividends with strong balance sheets behind them are the ones most likely to hold.
The post 4 Big Oil Dividends Ranked by What Matters When Crude Falls appeared first on 24/7 Wall St..
]]>On October 1, 2026, Brent crude, the global benchmark, closed at $102.31 a barrel, up $4.28, and US crude at $92.87, up $2.45. Two separate supply shocks hit on the same day, and energy funds rose.
United States Oil Fund (NYSEARCA:USO) rose 3.00% to $150.03. Energy Select Sector SPDR Fund (NYSEARCA:XLE) gained 1.93%, and Chevron (NYSE:CVX) added 1.45% to $207.18.
USO is up 116.92% year to date. The latest gain, though, depends more on headlines than on physical supply changes.
What Moved on October 1 and What Is Only Reported, according to Reuters
Talks with Iran broke down. Secretary of State Marco Rubio ordered Iran’s delegation out of the country, saying “They had overstayed their welcome.” Iran says the departure was already scheduled.
President Donald Trump called Iran’s latest offer “not good enough.” Asked about escalation, he answered: “Possible. We have a lot of weapons. You know, we’ve been stocking up for the last six months.”
The Wall Street Journal reported that the USS Theodore Roosevelt left San Diego for the Middle East, making it the third US carrier in the region, with 9,000 to 10,000 more troops due by November 30, 2026. No official confirmation was available.
Brent is above $100 while US crude is below it. That gap points to stress in seaborne international supply rather than in US oil.
China’s Fuel Export Halt Hits Diesel First
PetroChina canceled October gasoline and jet fuel shipments as Chinese refiners suspended fuel exports. A crude shock pressures refiner margins, but a product shock immediately removes finished fuel from the market.
Diesel prices show the strain most clearly: AAA put regular gasoline at $4.41 and diesel at $6.39, against a record $6.53 set September 22, 2026. Because diesel moves freight, higher diesel prices tend to feed into the cost of everyday goods.
How USO, XLE and Chevron Differ
USO owns oil futures and must roll them forward as they expire. When later contracts cost more than nearer ones, every roll costs money. The fund fell 2.01% over the past week.
XLE owns companies. Exxon Mobil (NYSE:XOM) made up 22.67% of its assets and Chevron 16.09% as of June 30, 2026.
Chevron listed Brent at $104/BBL vs $68/BBL a year earlier. It pays $1.78 a quarter, trades at 15x forward earnings, and said the Middle East conflict affected about 1% of second-quarter total production.
Nothing confirmed here has removed a barrel of crude. The carrier is reported, escalation is only “possible,” and the export stop covers one month.
Risk premiums fall quickly. Weekly Brent fell from 124.61 in April to 69.7 by July 3. Federal forecasters projected Brent would average $89/b in 4Q26. Restarted talks, a Chinese export restart, or an OPEC response would each pull prices back.
Why USO Behaves Differently Over Longer Holding Periods
USO tracks oil closely over days, but over longer holding periods it faces roll costs and the risk that headlines reverse.
Chevron offers a different kind of oil exposure because it owns reserves and pays a quarterly dividend, and it avoids the monthly roll costs that a futures fund pays.
If talks resume or Chinese refiners restart exports before October 31, 2026, Brent should drop back below $100, and its gap to US crude should narrow. If Brent holds above $100 through that date without either event, this view is wrong.
The post Brent Oil Is Back Above $100 as a Third Aircraft Carrier Heads to the Middle East appeared first on 24/7 Wall St..
]]>Refining stocks are breaking away from the integrated oil majors, and the gap places the bid directly on fuel margins. Marathon Petroleum (NYSE:MPC) stock has risen 5% to $413.75 this afternoon. Also, Valero Energy (NYSE:VLO) shares are climbing 4% to $403.25, moving in step with the other large independent refiner.
Exxon Mobil (NYSE:XOM) stock is practically unchanged at $162.85, up 0.1%, which leaves the integrated major out of the refiners’ advance. Meanwhile, the Energy Select Sector SPDR ETF (NYSEARCA:XLE) is up 1% to $62.22. That broad energy-sector portfolio counts Exxon Mobil and Chevron (NYSE:CVX) as the fund’s two largest disclosed positions, giving XLE far more integrated-major weight than refining exposure.


How a Refiner’s Economics Differ From an Integrated Producer’s
Marathon Petroleum and Valero Energy are refiners, and each company’s economics rest on the margin between what crude costs and what gasoline, diesel and other refined products sell for. Crude is an input cost for Marathon Petroleum, so the company’s refining margin expands whenever product prices pull away from that input cost. The move arrives with no company announcement from Marathon Petroleum, and two large independent refiners rising together while Exxon Mobil stock holds near unchanged places the demand in refining specifically.
For Exxon Mobil and Chevron, a crude oil price move reaches each integrated company from both directions at once, with higher crude lifting what the production side at Exxon Mobil and Chevron makes while raising the input cost each company’s refining side pays. That two-way exposure explains how a single trading day can separate the integrated majors from the pure refiners.
What the Peer and Fund Figures Show
Reading the Energy Select Sector SPDR ETF takes more care. With Exxon Mobil and Chevron as the fund’s two largest disclosed positions, the fund’s gain leans heavily on the integrated majors and offers little independent confirmation of what Marathon Petroleum and Valero Energy are doing. Refining holds a much smaller share of the portfolio, so even a strong refining day can lift XLE only slightly.
Bull and Bear Cases for a Pure Refiner
The case for Marathon Petroleum in a market like this rests on what a refiner owns, since when product prices pull away from crude, Marathon Petroleum keeps all of the wider refining margin, with no production business to net that gain against. Valero Energy runs on the same structure, which helps explain why both stocks are moving in step.
However, the same structure cuts the other way. Marathon Petroleum has no upstream barrels to cushion the company’s results when crude rises faster than product prices, and that squeeze is the risk the integrated model at Exxon Mobil and Chevron exists to smooth. A refiner’s upside and downside both arrive in full.
What the Divergence Means for Investors
Marathon Petroleum stock and Valero Energy stock are both sending a refining signal, and the fund’s gain adds little to that read given XLE’s tilt toward the majors. Traders can watch for whether Exxon Mobil stock stays near unchanged while the two refiners’ gains hold, since a lasting gap would reinforce the refining-specific story.
Shareholders may want to keep an eye on whether product prices continue pulling away from crude, because that relationship drives both Marathon Petroleum’s refining margin and Valero Energy’s. A reversal in that spread would hit both refiners directly, with no production income at either company to offset the damage.
Marathon Petroleum and Valero Energy lack an upstream cushion. If crude oil climbs faster than product prices, moderate positions in both refiners fit a bullish margin setup, while Exxon Mobil and Chevron offer firmer exposure that nets both sides of the barrel.
The post Marathon Petroleum Climbs 5%, Valero Energy Gains 4% as Refiners Outrun Integrated Majors; Exxon Mobil Stays Flat appeared first on 24/7 Wall St..
]]>At the 24% bracket, a portfolio generating $50,000 in dividend income hands $12,000 to the IRS every year. What an investor actually keeps depends on where each stock sits.
In a taxable brokerage account, qualified dividends get long-term capital gains treatment. Nonqualified payouts, including most REIT distributions, are taxed as ordinary income at your marginal rate. Inside a Roth IRA, both arrive untaxed and qualified withdrawals stay tax-free.
Roth Versus Taxable: What You Keep on Each Position
A hypothetical $500,000 position yielding 8% produces $40,000 a year. At 24%, a taxable account keeps $30,400. A Roth keeps it all, a $9,600 annual advantage.
Apply that formula to six income names: Realty Income (NYSE:O), W. P. Carey (NYSE:WPC), Altria (NYSE:MO), Verizon (NYSE:VZ), AT&T (NYSE:T), and Chevron.
Realty Income
Realty Income yields 5.68%, paying monthly at $0.2715 per share. AFFO guidance of $4.44-$4.45 sits above the $3.258 forward dividend. REIT distributions face ordinary income rates, so a Roth shields the full payout.
W. P. Carey
W. P. Carey pays a $3.80 annualized dividend against a $64.15 share price, with its quarterly rate climbing from $0.86 in December 2023 to $0.95 in September 2026. AFFO guidance of $5.19-$5.27 covers the payout. Its distributions are mostly ordinary income, placing it beside Realty Income at the front of the Roth line.
Altria
Altria yields 6.13%, the highest here, after raising its quarterly dividend to $1.11 from $1.06. Adjusted EPS guidance of $5.56-$5.72 sits above the $4.44 forward rate. As yield rises, so do the dollars a taxable account generates each year.
Verizon
Verizon yields 6.08% on a $2.83 annualized dividend. Free cash flow guidance of $21.94 billion to $22.14 billion and adjusted EPS guidance of $4.99-$5.04 leave room above the payout. Its yield turns a low tax rate into a large annual dollar leak.
AT&T
AT&T yields 4.53% on a $1.11 annualized dividend held at $0.2775 quarterly since April 2022. Free cash flow guidance of $18 billion-plus and adjusted EPS guidance of $2.25-$2.35 cover it. With the payout flat, tax placement is one of the few ways to raise what an owner keeps.
Chevron
Chevron yields 3.18% on a $1.78 quarterly dividend, supported by $18.1 billion of Q2 free cash flow. Its dividends are generally qualified and taxed at capital gains rates, so it benefits least from a Roth in this group.
How Your Bracket Multiplies the Roth Advantage
Every dollar of ordinary dividend income costs your marginal rate in federal tax. The 2026 thresholds appear below:
| Bracket | Single Income Over | Joint Income Over | Tax per $1 of Ordinary Dividends |
|---|---|---|---|
| 22% | $50,400 | $100,800 | 22 cents |
| 24% | $105,700 | $211,400 | 24 cents |
| 32% | $201,775 | $403,550 | 32 cents |
| 37% | $640,600 | $768,700 | 37 cents |
A 37% filer can surrender up to 37 cents of every REIT dollar held outside tax-advantaged accounts. A 22% filer can surrender up to 22 cents. Placement decisions grow more urgent as the bracket rises.
Why the Gap Widens Every Year
The $9,600 from the example repeats annually. Inside a Roth, reinvested dividends buy shares whose future payouts are also untaxed. In a taxable account, tax trims each reinvestment first, so the shortfall compounds alongside the portfolio.
Limits That Slow the Move Into a Roth
Annual contribution limits cap new money, and income phase-outs bar higher earners from direct contributions. Conversions are the practical path for large balances but face ordinary income rates in the year of conversion. The five-year rule determines when earnings come out tax-free, so late-stage converters need a time. The cheapest years to convert are usually the quiet ones between your last paycheck and your first RMD, a window we sized up in a free Roth guide here.
Three Steps Before Your Next Tax Filing
- Pull your latest Form 1099-DIV and compare total ordinary dividends with the qualified portion for each holding. The nonqualified amount times your bracket is your annual Roth-avoidable cost.
- If Realty Income or W. P. Carey sits outside a tax-advantaged account, consider modeling how a phased Roth conversion of those ordinary-income REITs compares with Chevron.
- Run the conversion tax against the annual delta on your specific shares before assuming the upfront bill outweighs it.
The math tends to matter most for investors in the 24% bracket or higher who are at or near retirement, plan to hold income positions for decades, and can pay conversion taxes from funds outside the account.
The post A $500,000 Roth Portfolio Loaded With These Dividend Stocks Pays $40,000 a Year and the IRS Gets None of It appeared first on 24/7 Wall St..
]]>In Chevron’s second quarter, every part of the business ran strong at once. Chevron (NYSE:CVX) set a U.S. upstream production record of 2,077 MBOED, ran its U.S. refineries at 97% capacity, and captured $1.5 billion in Hess savings within a year of closing. That savings figure beat the original target by 50%.
CEO Mike Wirth credited “disciplined investment and strong execution that drove record U.S. upstream production, record crude throughput in our U.S. refineries, and exceptional reliability across key assets.”
Shares are up 40.02% year-to-date and 152.16% over five years. Brent averaged $104 in Q2, but cost cuts, Guyana, and a new AI power business give this rally more runway. Here’s how Chevron could hit $250 per share in 2027.
Analysts See Modest Upside While Chevron Keeps Beating Them
Wall Street’s average price target of $223.92 implies 7.8% upside from $207.63. Sentiment leans bullish, with 6 Strong Buy and 14 Buy ratings against one Sell.
Chevron has exceeded consensus EPS for seven consecutive quarters. Q1 EPS was $1.41 versus a $0.9687 estimate. Q2 adjusted EPS jumped to $6.06 as revenue rose 51.4% to $67.20 billion. Such a run suggests current forecasts are conservative.
Here’s What It Takes for Chevron to Reach $250
Chevron trades at 15x forward earnings, cheaper than the S&P 500’s roughly 21x to 23x. A move to $250 would be a 20.4% gain, raising the multiple to about 18x forward earnings, still below the market.
Management’s 2030 plan calls for adjusted free cash flow growth averaging greater than 10% annually, assuming flat oil prices below today’s levels. For that growth, 18x is reasonable.
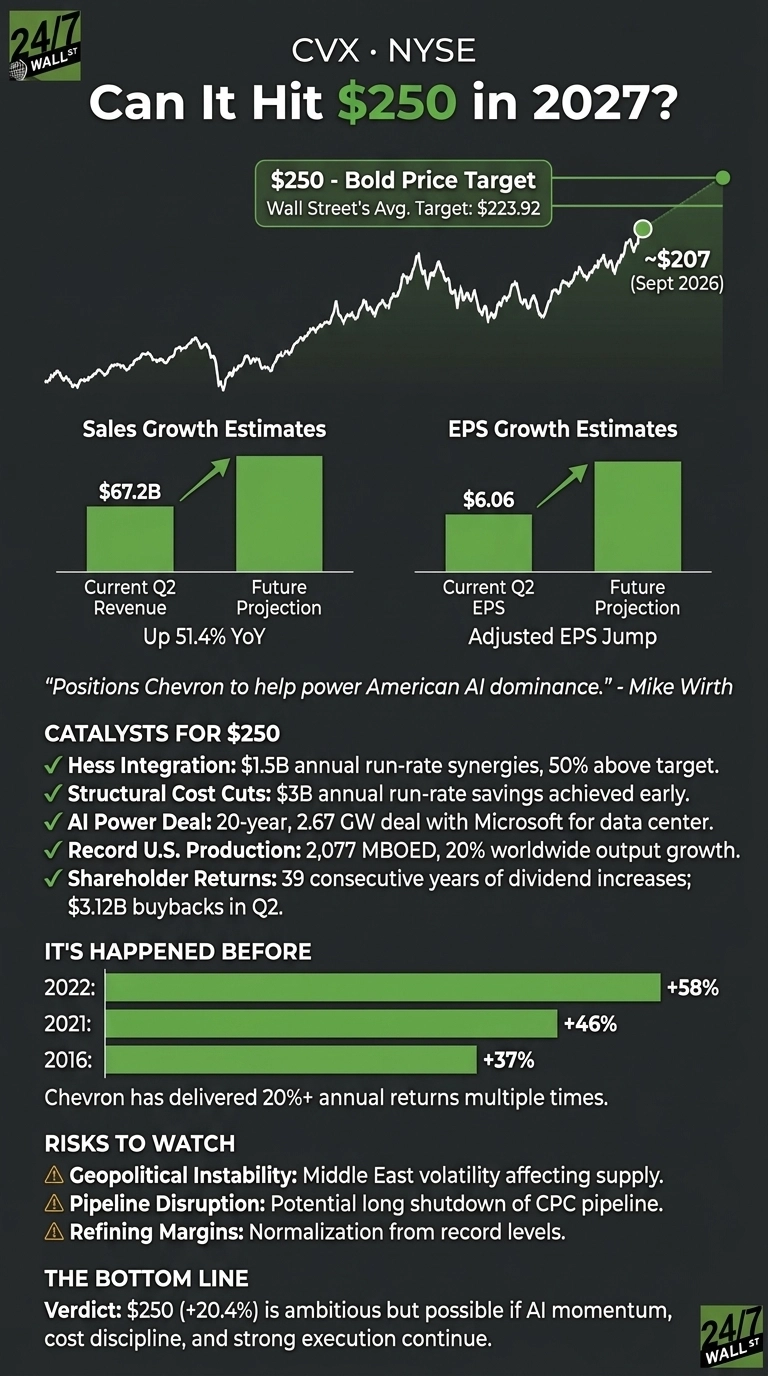
What Could Push Chevron to $250?
- Built-in savings: Chevron reached $3 billion in annual run-rate cost cuts six months early. CFO Eimear Bonner said the savings are “built into the business.”
- AI power: Project Kilby is a 20-year take-or-pay deal to supply Microsoft (NASDAQ:MSFT) with 2.67 gigawatts of power. It targets mid-teens returns from cash flows that don’t depend on commodity prices. Management calls it a repeatable model and says talks for more deals are advanced.
- Guyana: Free cash flow from the Hess assets has been “roughly double the incremental dividends,” and Guyana should keep high-margin oil growing into the 2030s.
- Refining: Downstream earnings reached $4.87 billion, up from $737 million a year ago. Management said “products are tighter than crude around the world.”
- Capital efficiency: Chevron expects to spend 25% less capex per barrel in 2026.
- Shareholder returns: Chevron bought back $3.12B of stock in Q2 and pays a $1.78 quarterly dividend. It has raised that dividend for 39 consecutive years.
- Growth options: These include Iraq’s West Qurna 2, Venezuela and Argentina, where management wants to grow the business 3x by 2035.
Chevron is one piece of a broader shift: the AI expansion runs on power, cooling, and networking, not just chips. We highlighted seven of those non-chipmaker suppliers in a free report you can grab here.
There are real risks. A long shutdown of the CPC pipeline, which carries Chevron’s Kazakhstan oil to market, conflict in the Middle East, and a return to normal refining margins could all slow progress.
Chevron’s History Says a 20% Year Is Well Within Reach
On a dividend-adjusted basis, Chevron has exceeded a 20.4% gain in eight calendar years since 2000. Total return reached 58% in 2022, 46% in 2021, 37% in 2016 and 35% in 2003.
Back-to-back big years have happened too, with 34% in 2006 followed by 31% in 2007.
$250 Is a Stretch, and Chevron Has the Tools to Get There
Reaching $250 requires a 20.4% gain, above the Street’s target. A seven-quarter beat run, $18.10B of Q2 free cash flow, commodity-proof power contracts, and a valuation below the market support it. Chevron has the tools to deliver outsized returns in 2027.
The post Chevron Has More Going for It Than Higher Oil Prices appeared first on 24/7 Wall St..
]]>
Oil markets are operating with little room for error. West Texas Intermediate crude trades above $91 a barrel this morning, while the Iran conflict, disrupted shipping, and tight diesel supplies continue putting a geopolitical premium on energy prices. Now America’s insurance policy against another supply shock is getting thinner, too.
The Strategic Petroleum Reserve has fallen to levels not seen since Ronald Reagan’s first term. And the Trump administration is releasing another 40 million barrels from it into the global market. Although the release is supposed to help temper the increase in prices by putting more oil in circulation, investors should pay attention to what it leaves behind.
The SPR Is Approaching Empty-Tank Territory
U.S. Department of Energy data show the SPR fell by roughly 800,000 barrels last week to 283.8 million barrels — its lowest level since October 1982. That represents the 27th consecutive weekly decline and leaves the reserve more than 132 million barrels below its recent peak.
Now the Energy Department is soliciting another 40 million barrels for delivery in November and December, the final installment of Washington’s commitment to a 400-million-barrel coordinated International Energy Agency release. The U.S. pledged 172 million barrels of that total.
If all 40 million barrels leave before meaningful quantities are returned, the SPR could temporarily sink below 250 million barrels.
That is important because strategic reserves are essentially catastrophe insurance. Having less oil stored does not create a shortage, but it gives Washington less flexibility if war, hurricanes, sanctions, or infrastructure failures suddenly remove supply.
It Isn’t Really a 40-Million-Barrel Giveaway
There is an important caveat. The government isn’t selling these barrels and then walking away. The DOE structured the transaction as an exchange. Companies borrow crude now and must return it later with additional barrels as a premium. Previous 2026 exchanges generated premiums of roughly 24% to 26%, according to DOE, potentially allowing the SPR eventually to receive more oil than it released.
The catch is timing. Reuters reports the oil may not be completely returned until late 2028, well beyond any near-term crises that may arise. So, although the long-term accounting could work,. the cupboard today is getting considerably and dangerously barer.
Could Venezuela Refill the Tank?
President Trump has proposed using Venezuela’s enormous oil resources to help rebuild the SPR. The White House says its August agreement provides access to low-cost Venezuelan crude, while Energy Secretary Chris Wright has discussed exchanging that heavy Venezuelan oil for lighter U.S. crude better suited to SPR storage.
That could eventually reduce replenishment costs, but it is hardly an overnight solution. Venezuelan production requires investment, its heavy crude needs specialized refining, and rebuilding hundreds of millions of SPR barrels would take years.
For investors, that keeps the energy-security premium alive. ExxonMobil (NYSE:XOM), Chevron (NYSE:CVX), and the State Street Energy Select Sector SPDR Fund (NYSEARCA:XLE) offer different ways to maintain exposure if oil stays elevated.
Key Takeaway
America isn’t permanently losing another 40 million barrels, but it is borrowing against its emergency cushion at a time when crude markets remain vulnerable.
Sharp investors shouldn’t chase oil simply because the SPR is shrinking. But with reserves at a 44-year low and geopolitical supply risks still elevated, keeping profitable oil producers represented in a diversified portfolio looks increasingly like insurance of its own.
The post America’s Strategic Oil Reserves Are at 44-Year Lows — And Trump Just Gave Away Another 40 Million Barrels appeared first on 24/7 Wall St..
]]>The SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is the default core holding for millions of investors, and for good reason. SPY delivers the entire S&P 500 in one trade for an expense ratio of 0.0945%. Income is SPY’s weak spot. State Street, the same firm behind SPY, runs a second fund built from the same index for investors who want a bigger check: the SPDR Portfolio S&P 500 High Dividend ETF (NYSEARCA:SPYD). Most SPY owners have never looked at it.
Same Index, Radically Different Weighting
SPY weights every member by company size, so a handful of giants dominate. As of September 28, 2026, NVIDIA (NASDAQ:NVDA) alone made up 8.07% of the fund.
SPYD keeps only the highest-yielding S&P 500 members and weights them roughly equally. As of September 28, 2026, no position makes up more than 2% of the portfolio.
What Each Fund Actually Paid Per Share
SPY’s most recent quarterly distribution was $1.888834 per share, with $7.582717 paid over the trailing twelve months. Shares traded at $766.19 during the September 28 session.
SPYD paid $0.517794 per share with an ex-dividend date of September 21, 2026, down from the prior quarter’s $0.542849. Its trailing twelve-month total reached $2.059958, and the forward annualized run rate is $2.071176. Shares traded at $45.88 as of September 28, 2026.
Real Estate, Utilities, and Oil Replace Megacap Tech
The yield screen changes what you own. SPYD’s June 30 holdings leaned on real estate investment trusts such as Iron Mountain, apartment owners and shopping-center landlords, plus electric utilities, regional banks, tobacco and packaged-food makers, and energy names such as Chevron (NYSE:CVX). The chipmakers and software platforms that drive SPY barely register.
That single fact explains both the higher income and the weaker returns. Mature, slower-growing businesses pay out more cash because they reinvest less.
Performance Price Tag Every Holder Must See
SPYD trailed SPY over every window below.
And the figures arrive on different bases: SPY’s are unadjusted price changes that exclude distributions, while SPYD’s are adjusted and include reinvested distributions. This is noteworthy because that difference benefits SPYD, and it still lost over every time period.
| Period | SPYD | SPY |
|---|---|---|
| One week | -2.53% | 0.59% |
| One month | -8.04% | 0.01% |
| Year to date | 9.58% | 12.36% |
| One year | 10.79% | 16.43% |
| Five years | 45.45% | 72.6% |
| Ten years | 115.77% | 255.43% |
The one-month slide stands out. The 10-year Treasury yield rose from 4.73% on August 28 to 5.18% on September 24, its highest reading in a year. Rate-sensitive REITs and utilities take that pressure directly. Meanwhile, the VIX read a calm 14.21 on September 22, pointing to sector pain rather than marketwide panic. With Treasuries paying that much, investors can demand more from a dividend fund before accepting stock risk.
A Fee Edge SPY Cannot Match
SPYD charges 0.07%, below SPY’s 0.0945%. That is notably cheap for a screened product. SPYD reported net assets of $7.37 billion as of June 30, 2026, a good size for tight trading.
How to Move Money Without a Tax Surprise
Selling SPY outside a tax-advantaged account can trigger capital gains, especially on shares held through the long bull run. Consider sending new contributions to SPYD instead, or making the swap in a retirement account. SPYD’s REIT-heavy income also includes a meaningful share of dividends taxed as ordinary income, which makes tax-deferred accounts a natural home. A partial position keeps SPY’s growth engine while raising cash flow.
Who Should Own SPYD, and Who Should Stay With SPY
SPYD suits retirees and income investors drawing cash today who accept slower growth and rate sensitivity in exchange for larger quarterly checks and a lower fee. Investors still building wealth, or anyone who plans to reinvest every dividend anyway, may find SPY the better fit. Its ten-year record and technology exposure remain the stronger vehicle for compounding. A sustained drop in Treasury yields would strengthen SPYD’s case; further dividend cuts like this quarter’s would weaken it.
The post Forget SPY’s Dividend. Here Is What $100,000 in State Street’s High-Dividend Version Pays appeared first on 24/7 Wall St..
]]>A $250,000 salary puts a household near the top of the U.S. pay scale, and this kind of pay usually goes with senior roles. Examples include a practicing specialist, a law firm partner, or an engineering director. Replacing it with dividends comes down to one formula: income target divided by yield is capital required. Depending on the yield you choose, the answer runs from about $1.8 million to more than $8.3 million.
Before looking at stocks, check the baseline. The 10-year Treasury yields 5.2%, which is its highest level in a year. Roughly $4.8 million in government bonds would produce $250,000 a year. At that rate, every dividend strategy below must measure up to that figure.
Paying $7 Million for Dividends That Grow
The math: $250,000 at a 0.035 rate works out to about $7.1 million. Across the full 3% to 4% range, the requirement falls from $8.3 million to $6.25 million. Chevron (NYSE:CVX) fits this level with a 3.2% yield. Its quarterly dividend rose from $1.42 in 2022 to $1.78 this year. The iShares Core Dividend Growth ETF (NYSEARCA:DGRO) yields about 2% on trailing payouts, giving up current income in exchange for payout growth. The iShares Core High Dividend ETF (NYSEARCA:HDV) has historically yielded around 3.5% to 4.5%. Both funds charge 0.08% a year.
This level needs the most capital, but in return, holdings are diversified, principal tends to rise over time, and the income is the least likely to be cut.
Moderate Yields Cut the Bill to About $4 Million
A $250,000 portfolio at 0.06 produces about $4.2 million. At the 5% and 7% ends of the range, the figure is $5 million and $3.6 million. W. P. Carey (NYSE:WPC) yields 5.6% and has raised its dividend every quarter since late 2023. It also cut the payout that year, from $1.065 to $0.86. Enterprise Products Partners (NYSE:EPD) yields 5.9% with distribution coverage of 1.9x. Its payout grew 3% over the past year.
The Goldman Sachs S&P 500 Core Premium Income ETF sells call options on S&P 500 stocks and pays out the premiums monthly. That cash flow comes at the cost of giving up part of the market’s gains in strong rallies, and at this level, income increases more slowly and has a harder time keeping up with inflation.
Aggressive Income Needs Only About $2 Million
A $250,000 portfolio at 0.12 returns about $2.1 million. At 8% the requirement is $3.1 million, and at 14% it falls to $1.8 million. Business development companies, mortgage REITs, leveraged covered call funds, and high-yield bond funds fill this level. Principal erosion is common here, distributions get cut, and the investor ends up slowly spending down the asset.
Running the Numbers on a Six-Fund Blend
Here is one sample mix worth considering for most investors: HDV 25%, DGRO 15%, GPIX 20%, WPC 15%, CVX 10%, and EPD 15%. Assume typical yields of 4% for HDV and 7% for the covered call fund, and use current yields for the other four. The blend comes to about 4.7%, which requires roughly $5.3 million. That puts it between conservative and moderate, with some growth and some higher income.
Why the $7 Million Portfolio Can Pull Ahead
Picture a $7.1 million portfolio yielding 3.5% whose payout increases 8% a year. The $250,000 it pays in year one rises to about $500,000 by year nine and roughly $793,000 by year 15. A 12% payer with flat distributions still pays $250,000 in year 15, and inflation has cut into its buying power every year along the way. Chevron’s dividend history shows how regular increases add up over time.
Three Moves Before Choosing a Yield Tier
- Focus on spending. Replace that, not your salary. Part of a $250,000 salary goes to payroll taxes and retirement contributions, and neither continues once you’re living on portfolio income. Your actual annual spending could lower the target by seven figures.
- Check each holding. Then match it to the right account. REIT dividends are usually taxed as ordinary income, which makes them a better fit for tax-deferred accounts. MLPs like Enterprise issue K-1 tax forms and can create tax problems inside an IRA.
- Check the Treasury yield. Then compare every level against it. With 10-year notes at 5.2%, a moderate-tier portfolio has to earn its extra risk through income growth or price appreciation.
The post How Much Do You Really Need Invested to Replace a $250,000 Salary With Dividends? appeared first on 24/7 Wall St..
]]>For a retirement-focused investor looking at oil majors today, the choice comes down to Chevron (NYSE:CVX) versus ExxonMobil (NYSE:XOM), and the question is simple: Which one deserves the closer look right now for durable oil-patch income? Both are Dividend Aristocrats. Both are throwing off record cash. The differences matter for a retiree who needs the check to keep arriving through the next commodity cycle.
Yield and the Dividend Streak: A Split Round With a Clear Winner
Chevron pays more today. At $206.24 a share on Sept. 25, Chevron yields 3.45% on a $1.78 quarterly payout, with an annualized forward dividend of $7.12. Exxon, at $161.67, yields 2.55% on a $1.03 quarterly check and $4.12 annualized.
Exxon owns the longer raise record: 43 consecutive years of annual dividend growth versus Chevron’s 39 consecutive annual increases. Both hiked roughly 4% in their latest raises, which puts both firmly in the Dividend Kings conversation (we ranked ten of them by valuation in a free report here). If your priority is the fattest current yield, Chevron wins this round. If your priority is the longest unbroken chain of raises through oil busts, Exxon wins. For a retiree writing checks in 2026, the higher cash yield today edges it: Chevron takes the income round.
Valuation: Where Exxon Pulls Ahead
Chevron trades at a P/E of 32, a P/B of 2.13, and a P/FCF of 24. Exxon trades at a P/E of 23, a P/B of 2.52, and a P/FCF of 28. Exxon’s earnings yield of 4.42% comfortably beats Chevron’s 3.10%, and Exxon posts a higher ROE of 11.03% against Chevron’s 7.26%. Chevron has run harder recently, up 38.84% year to date versus Exxon’s 36.72%, and now trades at a richer multiple as it digests the Hess deal. On the numbers that decide what a retiree is paying per dollar of earnings, Exxon wins valuation.
Balance Sheet and Production: The Dividend Durability Test
Dividend durability sits in the balance sheet, and the gap here is wide. Exxon carries a debt/equity of 0.17, net debt/EBITDA of 0.55, and interest coverage of 56.3x. Chevron’s figures: debt/equity 0.25, net debt/EBITDA 1.08, and interest coverage 13.7x. Chevron did cut $8.41 billion in total debt in Q2 2026, and management flagged net debt to CFFO of 0.6 times. Exxon’s is simply stronger.
Production tells the same story. Exxon hit record full-year production of 4.7 million oil-equivalent barrels per day, the highest in more than 40 years, with Guyana at roughly 900,000 barrels per day and a fifth FPSO on track for startup by year end. CFO Neil Hansen called Guyana “very much an inflection into free cash flow” and guided to “two times the level of free cash flow in 2030 than we saw in 2025.” Chevron’s record 4,070 MBOED is impressive, but it was driven by the Hess acquisition, which lifted leverage and DD&A. Exxon wins on durability.
Verdict: Exxon for the Retiree, Chevron for the Yield Chaser
Exxon Mobil fits the income-focused retiree profile. You get a lower P/E, a fortress balance sheet, a longer 43-year raise record, and a Guyana ramp that materially raises the odds that the dividend keeps growing through the next down cycle. The starting yield is lower, but the check is more likely to be there in 2035.
Chevron suits a different profile: the retiree who explicitly wants the highest current yield in the pair and is willing to accept a richer multiple and higher leverage after the Hess deal. If you need 3.45% today and trust management’s 2030 targets of 2% to 3% production growth and greater than 10% adjusted free cash flow growth, Chevron is defensible. For everyone else planning to draw income for the next two decades, Exxon screens as the cleaner setup.
The post For Retirees Who Want Oil Income: Chevron vs. ExxonMobil appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) is one of the clearest income math setups in the market right now: a dividend growth blue chip with a live yield in the low-3s and a payout history that spans nearly four decades. The headline number is the anchor. At the current forward annualized dividend of $7.12 per share, roughly 141 shares of Chevron throws off approximately $1,000 in annual dividend income, paid in four quarterly installments.
Share Count and What It Costs Today
Chevron’s most recent declared quarterly dividend is $1.78 per share, paid on Sept. 10 to holders of record on Aug. 19. That rate has been confirmed on the three 2026 payments to date. The share count in the headline assumes that per-share payout remains in place; if Chevron raises again on its normal January cadence, the share count needed for $1,000 falls slightly.
Cost of the position matters as much as the yield. Chevron traded at $206.32 on Sept. 24. That is a stock that has moved up 32.34% year to date and 31.06% over the past year, so income buyers today are stepping in near the upper end of the 52-week range of $142.51 to $217.78. The current yield is 3.21%, well below where CVX yielded when the stock sat in the $140s a year ago.
What Actually Backs the Dividend
Chevron is oil-linked, and earnings swing with crude. What supports the payout through cycles is cash generation, coverage, and balance sheet capacity, and the Q2 2026 numbers spoke to all three.
- Cash flow from operations excluding working capital was $19.7 billion in the quarter.
- Adjusted free cash flow came in at $15.4 billion in Q2 2026.
- Management reduced debt by more than $8 billion in the quarter, taking net debt to CFFO to 0.6 times.
- Organic capex was $4.4 billion, with full-year 2026 spending tracking to the lower end of the $18 to $19 billion guide.
The Hess assets are pulling their weight. CEO Mike Wirth told analysts the acquired portfolio is generating “strong free cash flow, which has been roughly double the incremental dividends and accretive to shareholders on a per share basis.” Chevron also captured $1.5 billion in Hess synergies six months ahead of schedule and hit its $3 billion structural cost reduction target early.
Streak and What It Really Proves
Chevron’s Q4 2025 dividend was raised 4%, marking its 39th consecutive annual dividend increase. The dividend record in the data feed extends back to 1999 and shows an unbroken march higher in the quarterly rate from $1.29 in 2020 to $1.78 in 2026, which spans the 2020 crude collapse.
That streak shows commitment rather than a contractual guarantee. Chevron is still an integrated oil and gas major, and a sustained crude price decline pressures both earnings and coverage. The EIA’s May 2026 Short-Term Energy Outlook models world oil production climbing to 109.50 million barrels per day in 2027, a supply picture that puts a ceiling on how much room prices have to run if demand softens.
What to Do Before Sizing a Position
- Refresh the quarterly dividend and share price before you place the trade. The 141-share figure is tied to a $7.12 forward annualized payout; a January increase would lower the count required for $1,000.
- Model a 25% dividend cut against your monthly income line before you build around this yield. Chevron has not cut recently, but every oil-linked payout is a function of crude realizations.
- Compare the entry yield you get today near $206 against the yield history. Buying a dividend growth name near a 52-week high locks in a lower starting yield than the same stock offered nine months ago.
For an investor building a diversified income book, Chevron at the current forward payout remains a credible core position for the conservative sleeve. Coverage, balance sheet, and the 2030 target of greater than 10% per year adjusted free cash flow growth support the dividend through a normal cycle. The starting yield is the tradeoff, and it is the tradeoff every buyer accepts here (if the goal is living off the checks without selling shares, we walked through how to build that kind of ladder in a free dividend income guide).
The post Own 141 Shares of Chevron (CVX) and Collect $1,000 a Year in Dividends appeared first on 24/7 Wall St..
]]>When Chevron (NYSE:CVX) and IBM (NYSE:IBM) reported second-quarter results this summer, the former rode record barrels from its Hess deal, while the latter leaned on software as mainframe sales declined. Capital spending shows which dividend is harder to fund.
Record Barrels for Chevron, a Mainframe Trough for IBM
Chevron’s production rose 20% to a record 4,070 thousand barrels of oil equivalent per day (MBOED) in its July 31, 2026, report, proof the Hess assets are pulling weight. Downstream earnings hit $4.87 billion versus $737 million a year earlier, a refining boom. Brent crude averaging $104 per barrel flattered both figures.
IBM’s July 22, 2026, report missed the $2.97 EPS consensus with $2.93, as IBM Z revenue fell 42% between mainframe cycles. Red Hat grew 11%, demonstrating that recurring software revenue continues to expand. IBM’s CFO called free cash flow “one of the two key leading indicators” of its investment thesis.

Chevron Owes $17 Billion to Its Oil Fields First
Fiscal 2025 operating cash flow reached $33.94 billion, but capital expenditures took $17.35 billion before any shareholder got paid. The trend makes the load greater:
| Fiscal Year | Net Income | Capex | Dividends Paid |
|---|---|---|---|
| 2023 | $21.37B | $15.83B | $11.34B |
| 2024 | $17.66B | $16.45B | $11.80B |
| 2025 | $12.30B | $17.35B | $12.75B |
Net income fell each year while capex and dividends both rose. Greater spending comes with the territory: integrated producers must reinvest to replace pumped reserves. Despite these pressures, operating cash flow still covered the $12.75 billion dividend obligation.
IBM’s Low Capex Comes With a Rising Interest Bill
| Fiscal Year | Operating Cash Flow | Capex | Dividends Paid | Interest Expense |
|---|---|---|---|---|
| 2023 | $13.93B | $1.25B | $6.04B | $1.61B |
| 2024 | $13.45B | $1.05B | $6.15B | $1.71B |
| 2025 | $13.19B | $1.09B | $6.26B | $1.94B |
Operating cash flow held about flat and capex fell, while net income jumped to $10.59 billion in 2025 from $6.02 billion in 2024. Interest expense rose every year, a growing claim on the same cash.
AI Power Deals and IBM’s Cash Target Set the Next Test
Chevron’s 20-year, 2.67 GW power deal with Microsoft (NASDAQ:MSFT) for a West Texas data center, which ties an oil major to the AI build-out IBM sells into, is worth watching. IBM must deliver the approximately $1 billion free cash flow increase it is targeting for 2026. Reaching it would widen the dividend margin further.
Why IBM’s Dividend Looks Easier to Fund, Debt and All
As of September 25, 2026, premarket trading, Chevron stood at $203.35, up 37.1% year to date with a yield near 3.4%, while IBM traded at $228.27, down 21.4%. Momentum favors Chevron.

Funding tells a different story. IBM needs far less capital to operate, so more cash reaches shareholders. Chevron suits income investors who are comfortable tying payouts to oil prices.
The post Chevron or IBM: One of These Dividends Costs $17 Billion a Year to Protect appeared first on 24/7 Wall St..
]]>What separates the S&P 500’s most reliable dividend payers from the rest of the index comes down to one thing: each payment is covered many times over by cash the business actually produces. These five names, spread across technology, retail, energy, financial data, and defense, all share that trait. The proof is on the balance sheets and in the cash flow statements. As one anchor for the theme, Microsoft alone generated $182.94B in operating cash flow in fiscal 2026 while paying a dividend that consumed a tiny fraction of it.
Microsoft
Microsoft (NASDAQ:MSFT) yields just 0.72%, and the coverage story is what matters. The company’s board declared a raised quarterly payout of $0.98 per share on September 14, 2026, extending a payment history that runs continuously back to February 2003. Coverage is overwhelming here: full-year fiscal 2026 diluted EPS came in at $18.02 against an annualized forward dividend of $3.92, and free cash flow of $66.99B comfortably funds both the dividend and buybacks. The balance sheet is fortress-grade, with interest coverage of 50.9x and net debt/EBITDA of 0.57.
The bull case for income buyers is simple. Azure just cleared $100B in annual revenue, commercial RPO sits at $678B, up 84%, and Microsoft 365 Copilot has surpassed 30 million paid seats. That is the growth funding double-digit dividend hikes. The risk: an AI capex ramp of $115.95B in FY26 is compressing free cash flow growth even as the top line accelerates.
Lowe’s Companies
Lowe’s Companies (NYSE:LOW) yields 2.49%, and after a 20.59% year-to-date decline, the shares trade at a P/E of 17 on trailing earnings of $11.54. The payout was lifted to $1.25 per share from $1.20 with the July ex-dividend date, and the payment record in the dataset stretches unbroken back to 1999, with progressive annual increases visible across the entire span. Coverage is strong: earnings cover the annualized forward dividend of $5.00 multiple times, and free cash flow yield sits at 7.23%.
The bull case is a durable, cash-generative retailer buying back stock aggressively while comps have turned positive for five straight quarters. Fiscal Q2 2026 revenue rose 8.3% to $25.96B with adjusted EPS of $4.40. The caveat is the flip side of the buyback story: aggressive repurchases have driven shareholders’ equity negative at -$7.44B, so traditional leverage ratios are not meaningful, and DIY demand remains tied to a soft housing cycle.
Chevron
Chevron (NYSE:CVX) is the highest-yielding name in the bundle at 3.16%, which still keeps it firmly in high-yield territory rather than ultra-high-yield. The quarterly dividend has stepped up steadily in the payment record, from $1.51 in 2023 to $1.63 in 2024, $1.71 in 2025, and $1.78 in 2026. Coverage is the story: Q2 2026 free cash flow was $18.10B against operating cash flow of $22.63B, and the company still cut $8.41B off total debt and repurchased $3.12B of stock in the same quarter. Interest coverage of 13.7x and net debt/EBITDA of 1.08 mark this as one of the more conservative balance sheets in integrated energy.
The bull case blends commodity leverage with a shift toward long-duration cash flows, including a 20-year power deal with Microsoft for a 2.67 GW West Texas data center. Post-Hess, Q2 revenue jumped 51.4% to $67.20B. Shares are up 38.63% year to date. The risk is unchanged: oil price volatility remains the swing factor for reported earnings and, over time, the pace of future dividend increases.
S&P Global
S&P Global (NYSE:SPGI) yields 0.96%, low on the surface but backed by one of the widest moats in the S&P 500. The board has raised the regular quarterly dividend from $0.90 in 2023 to $0.97 in 2026, and the payment history in the dataset runs back to 2001 with a consistent February, May, August, November cadence. Coverage is overwhelming: TTM diluted EPS of $16.59 against an annualized forward dividend of $3.88, and Q2 2026 free cash flow of $1.33B in a single quarter. The company has authorized more than $7B in share buybacks for 2026.
The bull case is a capital-light franchise with pricing power across Ratings, Indices, Market Intelligence, and Energy, following the July 1, 2026 spin-off of Mobility. Ratings Q2 revenue grew 17% and Indices asset-linked fees rose 22%. The share price has cooled, off 18.36% year to date, which pulls the forward P/E to 20, comfortably below the trailing multiple. The risk: Ratings transaction revenue is tied to debt issuance cyclicality, and Q2 adjusted EPS of $4.83 missed the $5.00 estimate.
Lockheed Martin
Lockheed Martin (NYSE:LMT) yields 2.61% at $523.71. The quarterly payment has stepped up in a clean annual cadence in the dataset, from $0.75 in November 2010 to $3.45 in 2026, with no reduction visible across the record. Coverage is a wide moat unto itself: management guided full-year 2026 free cash flow to more than $7.0 to $7.2B, against Q1 dividends paid of $816M. Q2 2026 delivered revenue of $20.06B, up 10.5%, EPS of $7.94, and free cash flow of $2.92B.
The bull case is a record backlog of $230.4B, boosted by a $35B multi-year THAAD contract, that offers rare multi-year revenue visibility funding both the dividend and buybacks. Missiles and Fire Control revenue was up 19% in Q2. Management raised FY26 EPS guidance to $29.95 to $30.65. The risk is program-specific: fixed-price contracts including F-16, C-130, and CH-53K have produced reach-forward losses in prior periods, and continuing resolution uncertainty remains a wildcard for Pentagon procurement timing.
What Ties These Five Together
Look past the yield column and each of these names hits the same mark: earnings and free cash flow cover the dividend by a wide margin, leverage is manageable, and the payment record shows an unbroken series of increases across many years. Microsoft and S&P Global barely feel like income stocks on yield alone, yet their coverage math is arguably the strongest in the group. Chevron and Lowe’s deliver more current income while still leaning on real cash generation, and Lockheed’s backlog turns near-term payout capacity into a multi-year visibility story. That is the one thing the S&P 500’s best dividend payers share.
The post The S&P 500’s Best Dividend Stocks Share One Powerful Advantage appeared first on 24/7 Wall St..
]]>For a Dow-focused retirement investor at the 24% federal bracket, the tax code treats qualified dividends favorably at the 15% long-term capital gains rate rather than the marginal rate. That still means a taxable portfolio throwing off $50,000 in qualified Dow dividend income hands $7,500 to the IRS every year, permanently, while the same holdings inside a Roth IRA keep every dollar.
Roth Versus Taxable on Six Dow Blue Chips
Every stock below is a current Dow Jones Industrial Average component, ranked by dividend yield. Prices and yields are as of the September 24, 2026 session.
| Stock | Price | Annualized Dividend | Yield |
|---|---|---|---|
| Chevron (NYSE:CVX) | $206.40 | $7.12 | 3.45% |
| IBM (NYSE:IBM) | $231.75 | $6.76 | 2.91% |
| Amgen (NASDAQ:AMGN) | $407.59 | $10.08 | 2.39% |
| Merck (NYSE:MRK) | $149.48 | $3.40 | 2.20% |
| Goldman Sachs (GS) | $932.33 | $20.00 | 1.79% |
| JPMorgan Chase (JPM) | $338.07 | $6.60 | 1.70% |
Chevron leads the group after raising its quarterly payout from $1.71 to $1.78, backed by $22.6B in Q2 2026 operating cash flow. IBM’s unbroken quarterly dividend streak dating to 1916 makes it a Roth staple. Amgen just stepped its quarterly payout to $2.52, extending a decade of increases from $0.28 in 2011. Goldman is the most aggressive grower, lifting its dividend from $3 in early 2025 to $5 in 2026, and JPMorgan followed with a bump to $1.65 quarterly.
Sizing the Delta at 24%
The framing case in this series: a $500,000 position yielding 8% generates $40,000 annually; at the 24% bracket the taxable account keeps $30,400, while the Roth keeps the full $40,000, a $9,600 annual advantage. Dow blue chips yield less, so the delta scales down accordingly. On a $500,000 equally weighted basket of the six names above, the blended yield sits in the low-2% range, producing roughly $12,500 in annual qualified dividends. At the 15% qualified rate, the taxable account surrenders about $1,875 per year; the Roth keeps it.
Bracket Multiplier on the Same $12,500 Income Stream
| Ordinary Bracket | Qualified Rate | Annual Roth Advantage |
|---|---|---|
| 22% | 15% | $1,875 |
| 24% | 15% | $1,875 |
| 32% | 15% or 20% | $1,875 to $2,500 |
| 37% | 20% plus 3.8% NIIT | $2,975 |
The top-bracket investor loses the most, because qualified rates step to 20% and the net investment income surtax layers on. The higher the bracket, the more urgent the Roth placement decision.
Compounding Cost of Leaving Them Taxable
Reinvested inside a Roth at a conservative 4% yield-on-cost, the recurring $1,875 annual advantage on this Dow basket compounds to roughly $22,500 over 10 years and $55,000 over 20 years in tax-free income that a taxable account would have surrendered. That is the permanent cost of Roth exclusion, before any share-price appreciation on names that have already returned 594% over 10 years for Goldman and 553% over 10 years for JPMorgan.
Action Items Before Year-End
- Pull last year’s 1099-DIV and identify which Dow payers sit in your taxable account. Multiply the qualified dividend total by 15% (or 20% if you cross the LTCG threshold) to see your annual tax cost.
- Run the Roth conversion math on your highest-yielders first. On this list, Chevron and IBM produce the largest income drag in a taxable account and the largest Roth benefit.
- If a full conversion is off the table, direct new Roth contributions and dividend reinvestments toward the two highest-yielding names above rather than the sub-2% payers.
The post How a Roth IRA Can Keep Thousands More of Your DJIA Dividend Income Compounding appeared first on 24/7 Wall St..
]]>Starting a dividend portfolio comes down to one good decision. For a beginner with $2,000 to put to work, that decision can be a single fund: the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD). One ticker, one trade and a diversified position across roughly 102 U.S. large-cap dividend payers.
Here is the core math, using inputs pulled at generation rather than any hand calculation. SCHD closed at $33.74 on Sept. 22. The fund pays quarterly, with an annualized forward dividend of $1.01 per share and a trailing 12-month total of $1.048. A $2,000 stake at that price builds a starter position that throws off modest but real cash flow, paid four times a year. Setting the expectation clearly matters here: a $2,000 position generates a small dollar figure at any realistic dividend yield. The value lies in the habit and the compounding.
Why SCHD Instead of the Highest Yield You Can Find
SCHD’s argument is methodology. The fund tracks a rules-based index that screens for dividend quality and consistency rather than raw yield. That approach filters out the two most common traps beginners walk into: Shrinking payers dressed up as bargains, and single-stock blowups where a double-digit yield signals distress. The screen leans toward companies with durable cash flows, a long record of paying, and financial strength to keep paying.
The tradeoff is that SCHD’s headline yield sits below what a mortgage REIT or leveraged closed-end fund would show. With the 10-Year Treasury yielding around 5% as of Sept. 22, SCHD’s distribution rate looks unspectacular in isolation. The reason to accept that is total return and growth of income over time. SCHD has returned 27.89% over the past year, 61.56% over five years and 234.82% over 10 years on a price basis. The dividend has stepped higher over that same window, with quarterly amounts rising from the 12-cent range in late 2011 to the 25-cent to 28-cent range in 2025 and 2026.
What You Actually Own
SCHD holds a broad mix of large, cash-generative US companies. Based on the May 31, 2026 NPORT snapshot, the top positions include:
- QUALCOMM at 6.74% of net assets
- Texas Instruments at 5.90%
- UnitedHealth Group at 5.09%
- Coca-Cola at 3.96%
- Merck at 3.86%
- Chevron at 3.83%
From there the roster reads like a dividend playbook: Verizon, Procter & Gamble, ConocoPhillips, Amgen, PepsiCo, Home Depot, Abbott Laboratories, Altria, Bristol-Myers Squibb, Accenture, Lockheed Martin and Blackstone. Sector exposure spans consumer staples, healthcare, energy, financials, semiconductors, communications, and industrials. Total net assets stand at roughly $94.9 billion, which keeps trading costs low and spreads tight.
Limits Worth Knowing Before You Buy
One fund is a starting point on the way to a finished portfolio. SCHD is entirely US large-cap dividend equity. There is no bond allocation, no international exposure, no small-cap or growth tilt. When the value factor lags, SCHD lags. It also holds cyclical weight in energy, financials, and semiconductors, so it moves with the economy. Recent trading reflects that: SCHD is down 4.17% over the past month but remains up nearly 22% year to date.
For a first dividend position, that profile is a feature. A beginner gets diversified ownership of quality payers, an income stream that has grown over more than a decade, and a single-line brokerage entry that can be added to over time. Later positions can layer in bonds, international stocks, or higher-yield vehicles once the base is in place. The point of the first $2,000 is to start the compounding clock, and SCHD is a straightforward way to do it.
The post You Only Need $2,000 and 1 Fund to Start Building a Dividend Portfolio. Here’s the ETF to Use appeared first on 24/7 Wall St..
]]>If any investor has stood the test of time, it’s Warren Buffett, and with good reason. For 60 years, the “Oracle of Omaha” has had a rock-star presence in the investing world, and his annual Berkshire Hathaway shareholder meetings have drawn thousands of loyal investors. They were stunned at last year’s meeting when Buffett announced he would step down as CEO of the investment giant at year’s end. While he remains board chair and vows to come to the office every day, he still has a voice in day-to-day operations. His pre-announced successor and long-time lieutenant, Greg Abel, has assumed the CEO position and is likely directing or having a say in most, if not all, new investments, public or private.
One major difference between Berkshire Hathaway (NYSE:BRK-B) and many similar large funds is that, despite years of calls from Wall Street and shareholders, the fund does not pay a dividend. We found that Berkshire Hathaway does not pay dividends because its leadership believes that retaining earnings creates superior long-term value for shareholders. Buffett and Abel maintain that the company can compound capital more effectively by reinvesting profits in acquisitions, its operating businesses, and strategic share repurchases. In addition, investors shouldn’t expect it to start paying one anytime soon, despite a record cash balance.
One thing is for sure: Buffett and Abel love stocks that pay dividends. In fact, the 2025 Berkshire Hathaway annual report showed the company earned a stunning $5.086 billion in dividend income. A large portion comes from five top holdings that not only pay dependable, and in some cases, outsized dividends, but also have been raising them year in and year out.
Why Do We Cover Berkshire Hathaway Stocks?
Few investors have the results and reputation that Buffett has garnered over the past 60 years. Though he has stepped away from the CEO chair, his impact and investment guidelines are likely to remain in place long after he is gone. While investing has evolved since Buffett took control of Berkshire Hathaway in 1965, and now that Abel is in charge and vowing to stay the course, buying good companies with products and services recognized worldwide and paying dividends will remain a timeless approach and never go out of style. Here are the five portfolio stocks that have raised their dividends over the past year. All are rated Buy at top Wall Street firms.
American Express
American Express (NYSE:AXP) is a bank holding company and multinational financial services corporation specializing in payment cards. The globally integrated payments company operates card-issuing, merchant-acquiring, and card-network businesses, and pays a 0.98% dividend. The company raised its quarterly dividend from $0.82 to $0.95 between January and April 2026.
The company offers products and services to customers worldwide, including consumers, small businesses, mid-sized companies, and large corporations. Its segments include:
- U.S. Consumer Services, which offers travel and lifestyle services, as well as banking and non-card financing products.
- Commercial Services offers payment, expense management, banking, and non-card financing products.
- International Card Services provides services to international customers, including travel and lifestyle services, and manages certain international joint ventures and its loyalty coalition business.
- Global Merchant and Network Services operates a payments network that processes and settles card transactions, acquires merchants, and provides multichannel marketing programs, capabilities, services, and data analytics.
Berkshire Hathaway owns 151,610,700 shares, 22.2% of American Express’s float, and 14.8% of the portfolio.
J.P. Morgan has an Overweight rating with a $400 target price.


Bank of America
While Warren Buffett has trimmed his position over the past two years and sold a whopping 50 million shares in the fourth quarter of 2025, this quality financial giant remains an exceptional long-term holding with a solid 1.83% dividend yield. The dividend was raised from $0.26 to $0.28, then to $0.32 per quarter, with two increases over the past 12 months. Bank of America (NYSE:BAC) is a bank holding company that reported impressive Q2 results. Berkshire Hathaway owns 513,624,165 shares, which is 9.1% of the portfolio and 7.3% of the float.
Its segments include:
- Consumer Banking offers a range of credit, banking, and investment products and services to consumers and small businesses.
- Global Wealth & Investment Management (GWIM) comprises two businesses: Merrill Wealth Management, which offers tailored solutions to meet clients’ needs through a comprehensive suite of investment management, brokerage, banking, and retirement products. Bank of America Private Bank provides comprehensive wealth management solutions.
- Global Banking offers a range of lending-related products and services, including integrated working capital management and treasury solutions, as well as underwriting and advisory services.
- Global Markets offers sales and trading services, as well as research services, to institutional clients across fixed income, credit, currency, commodity, and equity markets.
The Jefferies target price for the shares is $75.


Chevron
This American multinational energy company primarily focuses on oil and gas. Chevron (NYSE:CVX) is a safer option for investors looking to position themselves in the energy sector. It pays a substantial 3.58% dividend, which was raised by 5% earlier this year, and has a 39-year streak of dividend increases. The company operates integrated energy and chemicals businesses worldwide. Berkshire Hathaway holds 84,375,856 shares, representing 4.2% of the float and 4.7% of the portfolio.
The company operates in two segments. The Upstream segment is involved in:
- Exploration, development, production, and transportation of crude oil and natural gas
- Processing, liquefaction, transportation, and regasification associated with liquefied natural gas
- Transportation of crude oil through pipelines, and transportation and storage
- Marketing of natural gas, as well as operating a gas-to-liquids plant
The Downstream segment engages in:
- Refining crude oil into petroleum products
- Marketing crude oil, refined products, and lubricants
- Manufacturing and marketing renewable fuels
- Transporting crude oil and refined products by pipeline, marine vessel, motor equipment, and rail car
- Manufacturing and marketing of commodity petrochemicals, plastics for industrial uses, and fuel and lubricant additives
It also involves cash management, debt financing, insurance operations, real estate, and technology businesses.
Mizuho has a Buy rating with a $230 target price.
Coca-Cola
Coca-Cola (NYSE:KO) is an American multinational corporation founded in 1892. This company remains one of Buffett’s longest-held positions. Berkshire owns a massive 400 million shares, which is 9.3% of the float and 9.3% of the portfolio. The stock pays a dependable 2.51% dividend, which was raised to $0.53 per share in May 2026, marking the 64th straight year of dividend increases.
Coca-Cola is the world’s largest beverage company, offering consumers more than 500 sparkling and still brands. Led by Coca-Cola, one of the world’s most valuable and recognizable brands, the portfolio features 20 billion-dollar brands, including:
- Diet Coke
- Coca-Cola Light
- Coca-Cola Zero Sugar
- Caffeine-free Diet Coke
- Cherry Coke
- Fanta Orange
- Fanta Zero Orange
- Fanta Zero Sugar
- Fanta Apple
- Sprite
- Sprite Zero Sugar
- Simply Orange
- Simply Apple
- Simply Grapefruit
- Fresca
- Schweppes
- Dasani
- Fuze Tea
- Glacéau Smartwater
- Glacéau Vitaminwater
- Gold Peak
- Ice Dew
- Powerade
- Topo Chico
- Minute Maid
Globally, it is the top provider of sparkling beverages, ready-to-drink coffees, juices, and juice drinks. Through the world’s most extensive beverage distribution system, consumers in more than 200 countries enjoy the company’s beverages at a rate of over 1.9 billion servings per day. The company also owns 19.5% of Monster Beverage (NASDAQ:MNST), which continues to deliver strong financial results.
UBS has a Buy rating and a target price of $98.
Occidental Petroleum
After years of building this position, Buffett and Berkshire Hathaway are finally in the money on this company, which pays a 1.70% dividend. Occidental Petroleum (NYSE:OXY) is an international energy company with assets primarily in the United States, the Middle East, and North Africa. The company is an oil and gas producer in the United States, including the Permian and D.J. basins and offshore Gulf of America. Occidental’s most recent dividend increase was on February 19, 2026. The board raised the quarterly dividend by more than 5%, from $0.24 to $0.26 per share (bumping the annualized rate from $0.96 to $1.04).
Berkshire Hathaway has a large position in the company, owning 264,941,431 shares, representing 26.6% of the float and 4.3% of the portfolio.
Occidental’s oil and gas segment explores for, develops, and produces oil (including condensate), natural gas liquids (NGLs), and natural gas. The midstream and marketing segment purchases, markets, gathers, processes, transports, and stores oil (including condensate), NGLs, natural gas, carbon dioxide (CO2), and power. This segment provides flow assurance, maximizes the value of its oil and gas, and optimizes the company’s transportation and storage capacity. It also invests in entities that conduct similar activities, including low-carbon venture businesses.
A notable recent development was Occidental’s decision to sell its OxyChem subsidiary to Berkshire Hathaway, with the bulk of the proceeds expected to strengthen the company’s balance sheet and further concentrate its business on oil and gas. The move was notable because Buffett had reportedly long been interested in OxyChem, and Berkshire now owns the business outright. Berkshire Hathaway completed its purchase of OxyChem from Occidental on January 2, 2026, giving Berkshire full ownership of the chemicals business while providing Occidental with $9.7 billion in cash to reduce debt and sharpen its focus on energy.
Mizuho has an Overweight rating and a $75 price objective.


The post 5 of Warren Buffett’s Largest Berkshire Hathaway Stocks Are Raising Their Dividends Every Year appeared first on 24/7 Wall St..
]]>The Energy Select Sector SPDR Fund (NYSEARCA:XLE) is the default ticker most investors punch in when they want “energy” in a portfolio, and the label does a lot of quiet work. The fund holds 25 positions pulled from the energy slice of the S&P 500, with Exxon Mobil (NYSE:XOM) at 23% of net assets and Chevron (NYSE:CVX) at 16%. Two integrated majors alone drive the fund’s returns.
Utilities, solar developers, wind operators, and nuclear utilities are excluded because they live in separate S&P sectors or fall outside the large-cap benchmark. The everyday meaning of “energy” and the index definition don’t match.
With WTI crude at $107 per barrel and XLE up 46% year to date, the concentration is paying off. That is precisely why the mechanics deserve a closer look before you buy more.
What XLE Really Owns
The portfolio is a concentrated bet on integrated oil, exploration and production, refining, oilfield services, and midstream with no meaningful renewable exposure.
Beyond the two majors, the next tier includes ConocoPhillips (NYSE:COP) at 7%, Williams Cos (NYSE:WMB) at 5%, Valero (NYSE:VLO) at 5%, and Marathon Petroleum (NYSE:MPC) at 5%. Oilfield service names like SLB (NYSE:SLB) at 4% and Halliburton (NYSE:HAL) at 2% sit alongside pipelines like Kinder Morgan (NYSE:KMI) at 4%.
Total net assets stand at roughly $35.7 billion as of the June 30 filing. The fund is liquid, cheap, and tightly focused on American large-cap fossil fuels.
Because it draws only from S&P 500 energy constituents, XLE excludes small and mid-cap producers, foreign majors, and every clean-energy pure play trading in the U.S. Owning “energy” through this ticker means owning American large-cap fossil fuels.
Different Businesses, Different Return Drivers
Integrated majors care about crude and gas realizations, plus capital-return discipline. Refiners like Valero and Marathon live on the crack spread, which can widen when crude falls. Midstream operators such as Williams and Kinder Morgan earn fee-based cash flow tied to throughput volumes, so their earnings are far less directly linked to spot prices.
WTI has traveled from a low of $55.44 in December 2025 to a high of $114.58 in April 2026, with a 27% jump in the past month. That volatility flows unevenly across XLE’s buckets.
The important caveat: XLE does not track crude. Company-level costs, hedging programs, buybacks, and dividend policy can pull its stocks away from the barrel in either direction.
How It Stacks Against the Alternatives
Vanguard’s VDE tracks a broader U.S. energy index with similar oil-heavy composition at a lower expense ratio. For genuine energy transition exposure, clean-energy ETFs own solar, wind, and clean-tech names that XLE does not touch. A utility ETF adds regulated power generation, including nuclear and grid operators that will supply AI data centers (we profiled seven of the power, cooling, and networking suppliers behind that buildout in a free report).
A global energy fund widens the lens to include Shell (NYSE:SHEL), BP (NYSE:BP), and TotalEnergies (NYSE:TTE), which broadens geopolitical and refining diversification. None of these replaces XLE. Each fills a different hole.
The five-year total return of 213% shows XLE has delivered on its narrow promise during a fossil-fuel bull cycle. The one-year gain of 48% is entirely a crude-price story.
Bull and Bear Case for XLE ETF
The bull case is straightforward. With WTI in the guide’s high-price zone above the $100 threshold, integrated majors and E&Ps are generating cash that flows to shareholders through buybacks and dividends, and XLE captures that concentrated payout without dilution from non-fossil businesses.
The bear case is the same sentence read backward. The fund’s 46% year-to-date advance already prices in strength, and a return of WTI to the $60 to $80 band would compress cash returns quickly given how top-heavy the fund is in Exxon and Chevron.
Crude is the deciding variable, but refining margins, midstream volumes, and OPEC supply decisions each pull the underlying businesses in different directions. XLE works as a concentrated sector allocation that behaves differently from a crude-oil proxy or a broad “energy” fund.
It fits investors who want a tactical inflation and commodity tilt with a real income stream and accept the concentration. Anyone shopping for the energy transition should look at clean-energy or utility funds instead.
The post XLE Is 91% Oil and Gas. Investors Buying “Energy” May Own Less Than They Think appeared first on 24/7 Wall St..
]]>
U.S. imports of Venezuelan crude jumped by 183,000 barrels per day in the week ended Sept. 11, reaching 782,000 barrels per day, according to the U.S. Energy Information Administration. That was the highest weekly total since August 2017.
The bigger trend is even more striking. Over the past six months, Venezuelan imports have increased by 550,000 barrels per day, or 237%, while the three-month average reached 626,000 barrels per day.
That is a long way from Venezuela’s historical peak, when U.S. imports reached roughly 1.5 million barrels per day in 1997 and routinely exceeded 1 million barrels per day between 1995 and 2007. Still, the direction is unmistakable: American refiners are consuming more Venezuelan oil again.
And that creates an unusually direct opportunity for Chevron (NYSE:CVX).
Chevron Has a Front-Row Seat
Chevron isn’t merely watching Venezuela’s oil industry recover. It is helping drive the recovery.
On Sept. 2, Chevron announced updated agreements covering its Venezuelan joint ventures, including additional acreage in the Orinoco Belt. The company plans to invest more than $7 billion over the next five years and expects production from its Venezuelan ventures to more than double to approximately 600,000 barrels per day. Chevron says total production costs are below $20 per barrel.
That puts Chevron’s Venezuela opportunity alongside its broader financial strength. The oil and gas giant reported total revenue of $70 billion in the second quarter, up 56% from the year-ago figure, generating earnings of $12 billion, or $6.06 per share on an adjusted basis, more than quadruple the $1.45 per share it earned last year. Adjusted free cash flow was $15.4 billion while reducing debt by a record $8.4 billion.
Chevron’s board also declared a quarterly dividend of $1.78 per share, equal to a roughly 3.4% annualized yield at the Sept. 18 closing price.
The Refining Angle Matters, Too
Venezuelan crude is generally heavier than the crude produced in many U.S. shale fields, making refinery configuration important. Chevron has another advantage here: its U.S. refineries processed a record 1.07 million barrels per day of crude in the second quarter, operating at more than 97% utilization.
That creates a potentially valuable combination. Chevron can participate in Venezuela’s upstream production while its downstream business benefits from access to crude suited to sophisticated U.S. refining infrastructure.
U.S. markets have historically been the most attractive for Venezuela’s crude due to the short distance across the Gulf of America and the Gulf Coast refineries there are designed to process it.
Granted, Venezuela remains a geopolitical and regulatory risk. The U.S. Treasury continues to regulate activities involving Venezuelan entities, but the Sept. 11 Federal Register lists Chevron among companies authorized to conduct specified Venezuela-related activities.
Still, that means investors shouldn’t treat 600,000 barrels a day as guaranteed future production.
Key Takeaway
In short, Venezuela’s return to the U.S. oil supply chain is becoming a measurable trend, with imports reaching 782,000 barrels per day and a three-month average of 626,000 barrels per day. President Trump has said he will use Venezuelan oil to help refill the U.S.’s Strategic Petroleum Reserve that are near depletion levels.
Chevron has the clearest direct connection to that growth. Its Venezuelan production could more than double, while its U.S. refining system is already operating at record throughput. With $15.4 billion of quarterly adjusted free cash flow, a 3.4% dividend yield, and a plan to invest $7 billion in Venezuela, Chevron gives investors a way to participate in Venezuela’s oil revival without making a pure bet on Venezuela itself.
That makes Chevron stock worth putting on the watch list for investors seeking energy exposure with a growing Venezuelan catalyst.
The post U.S. Oil Imports From Venezuela Just Exploded to a 9-Year High — Chevron Could Be the Biggest Winner appeared first on 24/7 Wall St..
]]>For a retirement investor deciding between Chevron (NYSE:CVX) and Exxon Mobil (NYSE:XOM) as an income holding today, the question is simple: which oil major writes the more durable dividend check through the next commodity cycle? Both raised again this year, both sit on multi-decade streaks of annual increases, and both are flush with cash and WTI hovering near $100 a barrel. The comparison that matters is what happens when crude falls again.
Round 1: Current Yield and Raw Income
Chevron pays a $1.78 quarterly dividend, or $7.12 annualized, for a yield of 3.07%. Exxon pays $1.03 quarterly, or $4.12 annualized, for a yield of 2.57%. On $100,000 invested, that is roughly $3,070 versus $2,570 in year-one cash. Chevron also trades at a richer earnings multiple (P/E 34 versus Exxon’s P/E 23), but for the income-first buyer the raw cash yield is what funds the grocery bill.
Winner: Chevron. More income per dollar deployed, full stop.
Round 2: Durability Through the Cycle
This is where the verdict is decided, and Exxon wins it decisively. Start with the balance sheet. Exxon carries net debt/EBITDA of 0.548 and interest coverage of 56x. Chevron sits at net debt/EBITDA of 1.08 and interest coverage of 13.7x, with debt/equity of 0.251 against Exxon’s 0.168. Chevron’s net debt ratio climbed to 15.6% from 10.4% financing the Hess deal, and while it just paid down more than $8 billion in the quarter, the leverage gap is real.
Cash coverage tells the same story. Exxon generated more than $17 billion of free cash flow in Q2 2026 and returned more than $9 billion to shareholders while cutting net debt by more than $7 billion. Chevron posted $18.1 billion in free cash flow, but management flagged $1.4 billion in favorable timing effects, and Q1 2026 free cash flow was actually negative $1.55 billion. Structurally, Exxon’s business is more integrated: advantaged assets like Permian, Guyana and LNG were 59% of production in 2025, up seven points from 2024, and Guyana has hit a free cash flow inflection now that the $55 billion investment is fully recovered. When Brent falls, integrated refining and chemicals cushion earnings, and Exxon’s mix is deeper.
Winner: Exxon. Lower leverage, higher coverage, and a cash-generative Guyana curve that only accelerates from here.
Round 3: Dividend Growth and Track Record
Exxon has a 43-year streak of annual dividend increases; Chevron has 39. The most recent raises were comparable, with Chevron lifting the quarterly from $1.71 to $1.78 and Exxon from $0.99 to $1.03. What separates them is behavior in stress: Exxon’s quarterly dividend held flat at $0.87 across 2019 and 2020 but never cut, and it kept raising through every downturn since 1982. Chevron’s history is comparably clean, but the shorter streak crossed fewer commodity troughs at today’s scale.
Winner: Exxon. Longer runway of tested increases.
Verdict
For the retirement investor who needs the check to arrive in every crude environment, Exxon Mobil is the more durable dividend. The lower leverage, the 56x interest coverage, the integrated refining and chemicals ballast, and the Guyana free-cash-flow ramp all point the same direction. Chevron wins if the priority is maximum current income and the buyer is comfortable with the Hess-related leverage bump; its 3.07% yield is a genuine advantage. But for durability, which is the criterion that matters when you are living off the payout, Exxon takes it.
The post Chevron vs. Exxon: Which Dividend Survives the Downturn appeared first on 24/7 Wall St..
]]>Exxon Mobil (NYSE:XOM) is moving toward a return to a country it walked away from nearly two decades ago. The Wall Street Journal reported on September 16, 2026 that Exxon is nearing a deal to invest in Venezuelan oil fields, and WTVB reported on September 17, 2026 that Exxon is advancing talks to return to Venezuela’s Orinoco Belt, according to sources. According to finance.biggo.com, ExxonMobil is eyeing a return to Venezuela after 19 years, weighing an investment in fields that carry very large geological estimates.
On CNBC, Becky Quick said ExxonMobil is reportedly nearing a deal to invest in a number of Venezuela’s developed and undeveloped oil fields, and that those fields collectively contain more than 50 billion barrels of oil. Separately, Becky Quick said Harold Hamm’s Continental Resources signed a memorandum of understanding with Venezuela’s state oil company to develop an area with an estimated 30 billion barrels of oil reserves. The Wall Street Journal characterized the Continental agreement, signed on September 16, 2026, as a preliminary oil deal. According to energynewsbeat.co, Continental’s memorandum of understanding with Petroleos de Venezuela covers the Ayacucho 2 Block in the Orinoco Belt and marks the Oklahoma independent’s first move into the country.
What the Barrel Figures Actually Describe
The fields “contain” these volumes. That is a geological estimate of oil in the reservoir. It is not Exxon’s booked reserves, not Continental’s booked reserves, and not production. A memorandum of understanding is not a signed contract, and the preliminary label matters.
The two deal figures also do not add up to any headline number. The article title references Trump saying the United States secured a 65 billion barrel agreement with Venezuela. That claim comes from a different source, describes something different, and does not reconcile with either company disclosure. The barrel figures circulating around Venezuela right now come from different claims about different things.
Why Exxon Left in the First Place
Exxon operated the Cerro Negro heavy oil project in the Orinoco Belt until Hugo Chavez’s government nationalized foreign oil assets in 2007. Exxon pursued arbitration against PDVSA and Venezuela for more than a decade over that seizure. Venezuela holds the world’s largest proven oil reserves, which is why Western majors keep coming back to the conversation, and why the country’s history of expropriating foreign oil assets keeps hanging over it. Any company returning today faces that history directly.
Exxon’s current international negotiating posture leans on execution credibility built elsewhere. On the Q1 2026 8-K filing, the company detailed a portfolio anchored by Guyana and the Permian. On the Q2 2026 call, chief executive Darren Woods addressed Venezuela indirectly, noting Exxon has “a large chunk of acreage which is in force majeure waiting for the ultimate ruling from the International Court of Justice on the Venezuela dispute”.
Stock Reaction: Flat Today, Strong Behind It
Exxon shares are not rallying on the news. The stock traded at $162.01 as of 12:10 p.m. ET on September 17, 2026, down 0.80% on the session, according to WTVB. The longer trend is much stronger. Exxon is up 37.31% year to date and up 45.33% over the past year.
Context Worth Keeping in Mind
Two pieces of prior 24/7 Wall St. reporting are worth reading alongside this news. Gulf Coast refiners poured cold water on the 65 billion barrel framing that has followed Trump’s statement. A former Chevron executive has separately warned that Venezuela’s oil opportunity comes with a major catch. Both point to the same reality for readers: large reserve numbers and actual production are separated by years, significant capital commitment, and considerable political risk. The MOU stage, where Continental sits today, is a long way from a barrel of oil moving through a pipeline.
The post Exxon Nears Venezuelan Oil Deal, After Trump Says U.S. Secured 65 Billion Barrel Agreement With Country appeared first on 24/7 Wall St..
]]>Ten thousand six hundred dollars a month equals $127,200 a year, roughly the take-home of a dual-income professional household or a comfortable retirement in a coastal metro area. Replacing that check with investment yield is a math problem before it is a portfolio problem, and the answer swings by more than $2 million depending on the income tier you choose. Here is the core equation: annual income divided by portfolio yield equals capital required. Everything else is tradeoff analysis.
Sleep-at-Night Math: The 3% to 4% Tier
At a 3.5% blended yield, $127,200 divided by 0.035 equals roughly $3.63 million. At 4%, the number drops to $3.18 million. This is the range where dividend growth stocks and broad equity income funds live, and it is where the check keeps rising every year.
AbbVie (NYSE:ABBV) is the textbook example. The stock yields about 2.6%, but the quarterly payout climbed from $1.48 in 2023 to $1.73 in 2026, and the shares have returned 194% over five years. Skyrizi grew 24.4% and Rinvoq 24.5% last quarter, funding the growth. Chevron (NYSE:CVX) rounds out the tier at a 3.2% yield, with quarterly free cash flow of $18.1 billion in Q2 and 16 consecutive quarters of returning more than $5 billion to shareholders.
You need the most capital here, but you also get the most durable income stream.
Moderate Middle Ground: 5% to 7% Yields
Push the yield to 6%, and the capital requirement collapses to $2.12 million. This is net lease REIT and preferred equity territory. W. P. Carey (NYSE:WPC) yields around 5.4% with a $3.76 annualized dividend, up 4.4% year over year. The portfolio runs at 98.5% occupancy, with 47.8% of annual base rent tied to CPI escalators. That inflation link matters when the goal is a real income stream. The risks are real too: the shares have slipped nearly 7% over the past month, and Q2 included $79.4 million in impairment charges tied to tenant credit issues.
Cash Now, Growth Later: The 8% to 14% Bucket
At a 10% yield, $127,200 requires only $1.27 million. That is where business development companies, mortgage REITs, and leveraged covered call funds sit. Hercules Capital (NYSE:HTGC) yields about 9.1% with a $0.47 quarterly distribution and a portfolio that is 97.8% floating rate. It also illustrates the aggressive-tier catch. The distribution ran $0.48 across 2024 before stepping down to $0.47, non-accruals doubled from one loan to two, and the first-lien mix fell from 91.0% to 86.8%. High current yield and high total return are two different things.
Why the Low-Yield Portfolio Often Wins
An AbbVie holder in 2023 collected $1.48 per share per quarter. Three years later, that same share pays $1.73. Meanwhile, a fixed 10% distribution paid the same dollar in year one and year ten, and often less as principal eroded. The Chevron dividend has stepped up every year of the record, from $1.29 in 2020 to $1.78 in 2026. That is the compounding case for accepting a lower headline yield.
A blended approach threads the needle. A portfolio spread across broad dividend equity, high-yield equity, a net lease REIT, a BDC, pharma, energy, and a short-duration cash-plus sleeve can land near a 4.9% blended yield, requiring roughly $2.6 million to hit $10,600 a month (we mapped the full mix, the payment calendar, and the withdrawal order in a free Paycheck Portfolio guide if you want the template).
Three Moves Worth Making This Week
- Back into your actual number. Pull your last 12 months of spending, subtract Social Security or pension income you already have coming, and apply the equation to the gap. Most people need less than they assume.
- Stress test the aggressive sleeve. Model what happens to your income if a 10% yielder cuts its distribution 20% and the price falls 15%. If the resulting income still covers essentials, the allocation is defensible. If not, shift weight toward the growth tier.
- Compare 10-year total returns, not yields. A 282% ten-year total return in HTGC against a 528% ten-year total return in ABBV is the argument for owning both rather than picking one on yield alone.
The post How Large Does Your Portfolio Need to Be to Generate $10,600 a Month? appeared first on 24/7 Wall St..
]]>US retail diesel prices hit a record this week, and Washington is openly debating a tool it has never used before: an export ban on a refined petroleum product. The reported national average sat at roughly $6.31 per gallon on September 16, 2026, per AAA-sourced data cited in press coverage, according to Forbes. Against that backdrop, Colorado Politics reported on September 15, 2026 that Senate Majority Leader John Thune said he is open to exploring a diesel export ban, telling reporters, “If the United States has the supply and is exporting it, that might be one way of getting at it.”
Squeeze From Three Directions
The price move reflects three compounding supply shocks. Continued war-related disruption to Iranian and Middle East oil flows has tightened crude available to global refiners. Ukrainian drone strikes on Russian refineries have taken meaningful volumes of Russian diesel production offline, in a country responsible for roughly one in nine barrels of global diesel output. US distillate exports ran at a record pace in early August 2026, draining domestic tanks. OilPrice.com reported that US distillate stockpiles fell to their lowest seasonal level since 1996. US retail regular gasoline averaged $4.32 per gallon nationally for the week ending September 14, 2026, up $0.31 from a month earlier.
Burgum Pushes Back on the Mechanics
Speaking at the G20 Energy Ministerial in Houston, per Colorado Politics, Interior Secretary Doug Burgum said, “We would consider an export ban if we thought that actually might lower prices, but that’s not the case.” He warned a ban could invite retaliation from trading partners and hurt consumers in states like California that rely partly on foreign fuel imports.
The technical objection is sharper. The Center for Strategic and International Studies estimates roughly 70% of US refining capacity is built to process heavy, sour crude imported from abroad, not the light, sweet crude from American shale fields. Most US refineries are tuned to thicker, higher-sulfur oil they buy overseas. A ban that trapped US-produced light crude at home would not automatically yield more diesel, because the refineries best suited to make it cannot easily process what is available. CSIS argues an export ban would not deliver “sustained fuel price relief,” and warns refiners running at a loss could simply cut activity, deepening the shortage, according to Center for Strategic and International Studies.
White House Keeps Its Options Open
The administration’s response has been notably non-committal. White House spokeswoman Taylor Rogers said, “President Trump remains committed to unleashing American energy dominance, cutting costs, and putting more money back in the pockets of hardworking American families. As the U.S. continues to maintain full control of the Strait of Hormuz, oil and gas prices will fall back to pre-conflict levels.” That statement neither endorses nor rules out an export ban, according to The White House. It marks a shift from an earlier position in which the U.S. Department of the Interior said the “Trump administration has no plan to implement restrictions on oil and gas exports.”
Trump’s recent commentary has focused on producers. On August 3, 2026, Donald Trump posted on Truth Social that without his administration “the Oil Industry, and our Country itself, would be DEAD!” and accused ExxonMobil (NYSE:XOM) and Chevron (NYSE:CVX) of “making too much money.”
A Tool Washington Has Never Used
The United States banned crude oil exports beginning in 1975 and lifted that ban in 2015. Refined products like diesel and gasoline have never been subject to a comparable export ban in the modern era. Whatever Thune is willing to explore, it would be genuinely new policy.
The post Senate Majority Leader John Thune Floats a Diesel Export Ban as Prices Hit $6.31 a Gallon. Trump Team Not Convinced It Would Work appeared first on 24/7 Wall St..
]]>A commercial index provider spent 15 years watching active dividend managers try to beat its benchmark, and the scoreboard is unflattering. S&P Dow Jones Indices’ anniversary study, posted September 1, 2026, found the Dow Jones U.S. Dividend 100 Index outperformed 226 of 237 active dividend funds from August 31, 2011 through June 30, 2026.
That is the benchmark tracked by Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD), the fund most retail investors reach for when they want a screened basket of American dividend payers at a rock-bottom fee.
The S&P Dow Jones Indices paper does not identify the eleven winners or spell out fee treatment across share classes, and the index reflects gross returns rather than an investable product. Treat it as a marketing document rather than a verified ranking of SCHD itself. Still, the direction is unmistakable, and it matters because Charles Schwab Asset Management charges 0.06% annually to run this strategy. The question worth asking is whether SCHD’s recipe belongs in your income sleeve today.
And even the 11 outperformers are unlikely to keep outperforming in the next decade and a half, as active ETFs are usually inconsistent performers.
What You Actually Own
SCHD’s index screens U.S. companies with 10 or more years of dividend payments, then ranks survivors on cash-flow-to-debt, return on equity, dividend yield, and five-year dividend growth. The result tilts toward mature cash generators rather than the highest yielders.
The current book reads that way. Top positions include Qualcomm (NASDAQ:QCOM) at 6.7%, Texas Instruments (NASDAQ:TXN) at 5.9%, UnitedHealth (NYSE:UNH) at 5.1%, and Coca-Cola (NYSE:KO) near 4%, with energy majors Chevron (NYSE:CVX) and ConocoPhillips (NYSE:COP) filling out the top ten.
The fund pays quarterly. Trailing 12-month distributions totaled $1.048 per share, versus an annualized forward run rate of $1.01, pointing to a yield in the low 3% range against a recent price near $34.
What the Index Beat, and What It Did Not
The 226-of-237 figure is compelling because active dividend funds carry higher expenses and turnover, which compound against them across a 15-year window. Fee drag alone explains much of the gap.
But don’t mistake the benchmark’s record for SCHD’s. The ETF launched in October 2011, and quality-and-yield screening tends to lag growth-led markets. Over the past year, SCHD returned 30.2%, ahead of Vanguard High Dividend Yield ETF (NYSEARCA:VYM) at 17.3% and Vanguard Dividend Appreciation ETF (NYSEARCA:VIG) at 11.9%.
Zoom out five years and the picture inverts. SCHD returned 62%, VYM 76.9%, and VIG 63%. The screened-quality approach earned its keep in some periods and paid for itself in others.
Where the Strategy Pinches
SCHD carries no international exposure, so it delivers a concentrated bet on U.S. dividend payers. If the next decade favors ex-U.S. equities, this fund cannot help you.
The sector tilt runs heavy toward financials, health care, consumer staples, and energy, and light on the mega-cap technology names that have led index returns for years. iShares Core Dividend Growth ETF (NYSEARCA:DGRO), at a 0.08% expense ratio, serves a similar role with a softer value tilt.
Distribution volatility is the other quiet cost. The latest payment came in at $0.2525, down from $0.2569, a reminder that these are not fixed coupons.
Bull and Bear Case for SCHD
The bull case is that a rules-based screen focused on cash-flow quality and dividend durability has already outrun the median active manager for 15 years, and the fee it charges is essentially a rounding error. For an investor building a durable income sleeve, that combination is hard to replicate through security selection.
The bear case is that SCHD’s methodology bakes in a value and old-economy tilt that structurally underweights the market’s fastest-compounding businesses. A retiree who does not need capital appreciation may accept that trade willingly; a 40-year-old dollar-cost averaging for growth probably should not.
Which case wins depends on the next market regime. If leadership broadens beyond mega-cap tech, SCHD looks like a very good core holding. If it doesn’t, a 5% to 10% income sleeve is a reasonable ceiling for this fund in most portfolios.
The post Only 11 of 237 Active Dividend Funds Beat SCHD’s Index appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) has spent the past year quietly rewriting its story. The Microsoft (NASDAQ:MSFT) power deal, the Hess integration, and downstream margins doing the heavy lifting have all changed the pitch.
Our 24/7 Wall St. price target for Chevron is $227.15, roughly 4.31% above where CVX trades today at $217.77. That points to a hold, with high model confidence at 90%. The stock is near fair value after a strong run.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $217.77 |
| 24/7 Wall St. Price Target | $227.15 |
| Upside | 4.31% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why Chevron Is Trading Near 52-Week Highs
CVX is up 3.8% in the past week, 9.83% in a month, and 46.85% year to date, brushing the 52-week high of $217.65.
Q2 2026 was the catalyst: adjusted EPS of $6.06 on revenue of $67.20 billion, up 51.4% year over year, with downstream earnings jumping to $4.87 billion from $737 million.
Management hit $3 billion of structural cost cuts six months early and captured $1.5 billion of Hess synergies, 50% above the initial target. Debt fell $8.41 billion in the quarter alone.
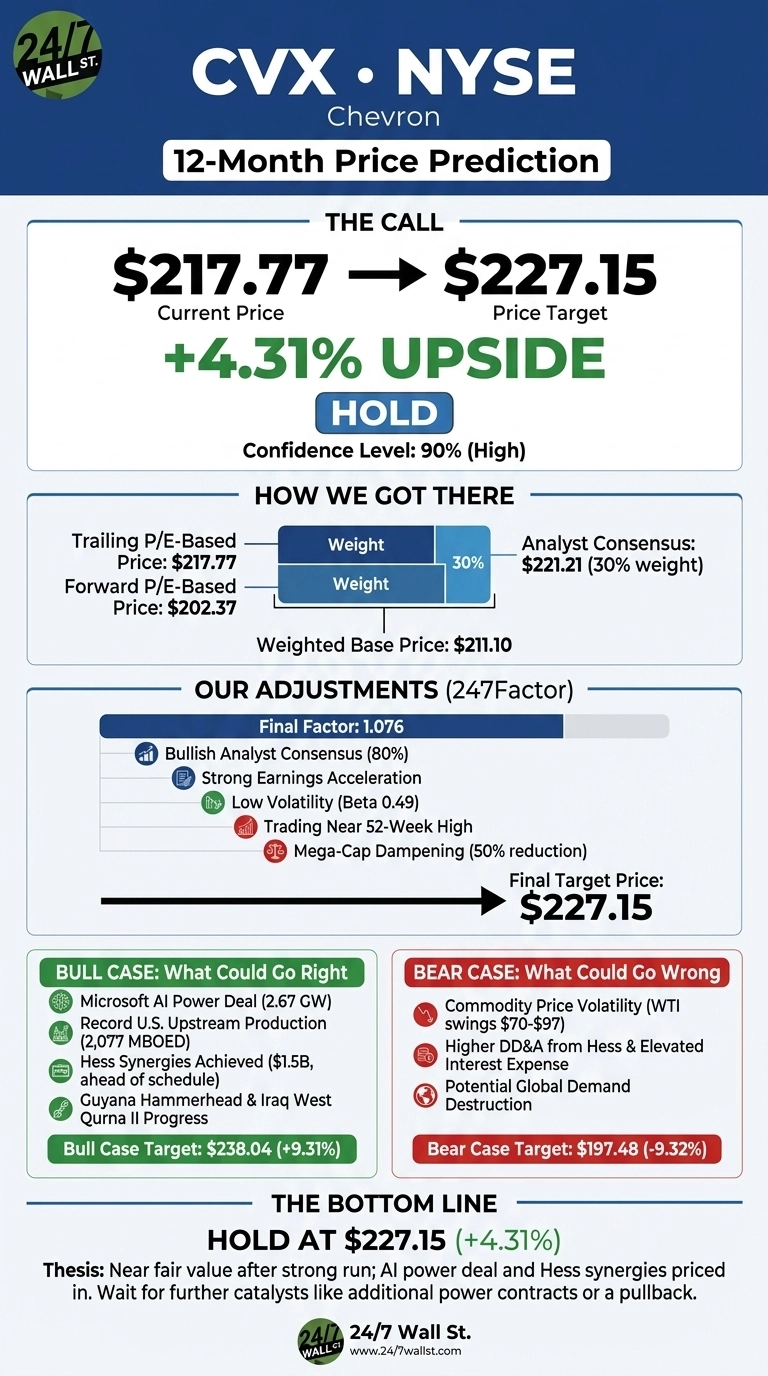
Why Bulls See a Breakout Ahead
The bull case now hinges less on Brent than on power. Chevron’s 20-year take-or-pay power purchase agreement with Microsoft for 2.67 GW of behind-the-meter capacity in West Texas, branded Project Kilby, is designed to deliver “mid-teens returns and long duration contracted cash flows that are independent of commodity price cycles.”
Management called it a “repeatable model,” with advanced discussions on more sites underway. Layer in record U.S. upstream production of 2,077 MBOED, 97% refinery utilization, Guyana’s Hammerhead FID, and Iraq’s West Qurna II negotiations, and the setup gets richer. A bull scenario supports $238 within a year.
What Could Go Wrong
Chevron carries commodity risk regardless of the AI narrative. WTI has swung from the $70s in early July to over $97 in September, and a slip back would compress upstream cash flow fast. Higher DD&A from Hess and elevated interest expense are also lingering drags.
Bears would counter that the CEO has stated Chevron’s 2030 objectives already assume flat, lower commodity prices, and the $3 billion cost program gives the company a wider margin buffer than in past cycles. Still, the model’s bear path lands around $197.48.
How Chevron Compares to ExxonMobil and ConocoPhillips
ExxonMobil (NYSE:XOM) is the closest integrated peer. XOM trades at a trailing P/E of 24 versus Chevron’s 20, with a market cap of $696 billion. Exxon delivered Q1 2026 revenue of $85.14 billion and adjusted EPS of $1.16. Chevron’s cheaper multiple and larger downstream swing this year make our target look reasonable rather than aggressive.
ConocoPhillips (NYSE:COP) is the pure U.S.-focused upstream counterpoint. COP posted Q2 2026 revenue of $19.16 billion, adjusted EPS of $3.24, and doubled buybacks to $2 billion. Without downstream or a Microsoft-scale power deal, COP is more price-sensitive. That contrast supports Chevron’s premium and reinforces our hold.
Chevron Price Prediction 2026-2030
The 24/7 Wall St. price target of $227.15 and hold rating reflect a stock that has already priced in the good news, backed by 90% confidence. The tipping factor is Project Kilby: if a second data-center power contract lands, the multiple rerates.
The setup would strengthen on any additional Microsoft-style deal or a pullback to the mid-$200s. It would weaken if Brent slides under $70 and refining cracks roll over into winter.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $220.01 |
| 2027 | $226.85 |
| 2028 | $236.56 |
| 2029 | $247.02 |
| 2030 | $259.25 |
These projections assume Chevron holds its 2-3% production growth objective and delivers Project Kilby on schedule. Meaningful upside or downside will come from Brent trajectory, additional AI power contracts (we profiled seven companies feeding the AI data-center buildout, from power to cooling, in a free report you can grab here), and Iraq’s West Qurna II terms.
The post Chevron Doesn’t Need Oil to Hit New Highs. Here’s What Could Drive the Stock Instead appeared first on 24/7 Wall St..
]]>Warren Buffett stepped down as CEO of Berkshire Hathaway on December 31, 2025, after six decades leading the conglomerate he transformed from a struggling textile mill into a $1 trillion empire. The “Oracle of Omaha” left his successor, Greg Abel, with a very concentrated portfolio: more than 71% of Berkshire’s $365.5 billion portfolio is invested in just seven stocks. Abel, who has served as vice chair overseeing non-insurance operations, officially took over as CEO on January 1, 2026. At 96, Buffett isn’t fully retiring. He remains board chair and comes to the Omaha headquarters as much as before. However, he has stated he will be “going quiet” and leaving all decision-making to Abel.
One thing that Abel has been careful about, as he has started some rearrangement of the Berkshire Hathaway (NYSE: BRK-B) portfolio, is to carefully maintain some of the longest-held stocks at Berkshire Hathaway, and with good reason. Some key holdings have not only been outstanding performers this year, but also pay dependable dividends, which are often reinvested or added to the gigantic $365 billion cash pile Buffett has been accumulating over the last five years. Berkshire Hathaway generates a stunning $4.37 billion in dividend income each year, and an additional $12 to $16 billion in risk-free interest income.
While Buffett and Abel patiently wait to put some of the cash to work, they may not have to wait long, as the stock market could be poised for a 10% to 20% correction, and it could be coming right around the corner. With the potential for higher interest rates, a massive $40 trillion national debt, a tired and overbought stock market, and fading artificial intelligence momentum, all the ingredients for a big correction are lining up. Toss in the potential for more geopolitical fallout, especially if the fighting in the Middle East expands, the sellers, and especially the short sellers, could have their fingers on the sell button.
Five of Berkshire Hathaway’s premier holdings are a good place to shift capital now, and all pay reliable dividends that, in some cases, are raised every year. Top Wall Street firms rate all as Buys, and they make sense for worried investors now.
Why Do We Cover Berkshire Hathaway Stocks?
Few investors have the results and reputation Buffett has earned over the past 60 years. Though he has stepped away from the CEO chair, his impact and investment guidelines are likely to remain in place long after he is gone. While investing has evolved since Buffett took control of Berkshire Hathaway in 1965, buying good companies with globally recognized products and services that pay dividends will remain a timeless approach.
American Express
American Express (NYSE:AXP) is a bank holding company and multinational financial services corporation specializing in payment cards, and it pays a 1.09% dividend. This globally integrated payments company operates card-issuing, merchant-acquiring, and card-network businesses. The company raised its quarterly dividend from $0.82 to $0.95 between January and April 2026.
The company offers products and services to customers worldwide, including consumers, small businesses, midsized companies, and large corporations. Its segments include:
- U.S. Consumer Services, which offers travel and lifestyle services, as well as banking and non-card financing products.
- Commercial Services offers payment, expense management, banking, and non-card financing products.
- International Card Services provides services to international customers, including travel and lifestyle services, and manages certain international joint ventures and its loyalty coalition business.
- Global Merchant and Network Services operates a payments network that processes and settles card transactions, acquires merchants, and provides multichannel marketing programs, capabilities, services, and data analytics.
Berkshire Hathaway owns 151,610,700 shares, 22.2% of American Express’s float, and 14.1% of the portfolio.
Piper Sandler has an Overweight rating with a $405 target price.
Bank of America
Buffett has trimmed his Bank of America (NYSE:BAC) position over the past two years, selling a whopping 50 million shares in the fourth quarter of 2025 and another 30 million shares in Q2 of 2026. This quality financial giant remains an exceptional long-term holding with a solid 1.79% dividend yield. The dividend was raised from $0.26 to $0.28, then to $0.32 per quarter, with two increases over the past 12 months. Bank of America is a bank holding company and financial holding company that reported impressive Q2 results. Berkshire Hathaway still owns 483,394,015 shares, or 7.9% of the portfolio and 6.9% of the float, despite the massive sales.
Its Consumer Banking segment offers a range of credit, banking, and investment products and services to consumers and small businesses. The Global Wealth & Investment Management segment comprises two businesses:
- Merrill Wealth Management offers tailored solutions to meet clients’ needs through a comprehensive suite of investment management, brokerage, banking, and retirement products.
- Private Bank provides comprehensive wealth management solutions.
Its Global Banking segment offers a range of lending-related products and services, including integrated working capital management and treasury solutions, as well as underwriting and advisory services. The Global Markets segment offers sales and trading services, as well as research services, to institutional clients across fixed income, credit, currency, commodity, and equity markets.
Jefferies has a Buy rating with a $75 target price.
Chevron
Chevron (NYSE:CVX) is an American multinational energy company primarily focused on oil and gas. This integrated giant is a safer option for investors seeking a position in the energy sector. It pays a substantial 3.26% dividend, which was raised by 5% earlier this year, and has a 39-year streak of dividend increases. Chevron operates integrated energy and chemicals businesses worldwide through its subsidiaries. Berkshire Hathaway owns 84,375,856 shares, which equals 4.2% of the float and 4.7% of the portfolio.
The company operates in two segments. The Upstream segment is involved in:
- Exploration, development, production, and transportation of crude oil and natural gas
- Processing, liquefaction, transportation, and regasification associated with liquefied natural gas
- Transportation of crude oil through pipelines, and transportation and storage
- Marketing of natural gas, as well as operating a gas-to-liquids plant
The Downstream segment engages in:
- Refining crude oil into petroleum products
- Marketing crude oil, refined products, and lubricants
- Manufacturing and marketing renewable fuels
- Transporting crude oil and refined products by pipeline, marine vessel, motor equipment, and rail car
- Manufacturing and marketing of commodity petrochemicals, plastics for industrial uses, and fuel and lubricant additives
It also involves cash management, debt financing, insurance operations, real estate, and technology businesses.
Piper Sandler has an Overweight rating with a $243 target price.
Coca-Cola
Coca-Cola (NYSE:KO) is an American multinational corporation founded in 1892. It remains one of Buffett’s longest-held holdings. Berkshire owns 400 million shares, which represent 9.3% of the float and 9.3% of the portfolio. The stock pays a dependable 2.36% dividend. The raised to $0.53 per share in May 2026, marked the 64th straight year of dividend increases.
Coca-Cola is the world’s largest beverage company, offering consumers more than 500 sparkling and still brands. Led by Coca-Cola, one of the world’s most valuable and recognizable brands, the company’s portfolio features 20 billion-dollar brands, including:
- Diet Coke
- Coca-Cola Light
- Coca-Cola Zero Sugar
- Caffeine-free Diet Coke
- Cherry Coke
- Fanta Orange
- Fanta Zero Orange
- Fanta Zero Sugar
- Fanta Apple
- Sprite
- Sprite Zero Sugar
- Simply Orange
- Simply Apple
- Simply Grapefruit
- Fresca
- Schweppes
- Dasani
- Fuze Tea
- Glacéau Smartwater
- Glacéau Vitaminwater
- Gold Peak
- Ice Dew
- Powerade
- Topo Chico
- Minute Maid
Globally, it is the top provider of sparkling beverages, ready-to-drink coffees, juices, and juice drinks. Through the world’s most extensive beverage distribution system, consumers in more than 200 countries enjoy the company’s beverages at a rate of over 1.9 billion servings per day. And the company owns 19.5% of Monster Beverage (NASDAQ:MNST), which continues to deliver strong financial results.
UBS has a Buy rating and set a target price of $104.
Occidental Petroleum
After years of building this position, Buffett and Berkshire Hathaway are finally in the money on this company, which pays a 1.63% dividend. Occidental Petroleum (NYSE:OXY) is an international energy company with assets primarily in the United States, the Middle East, and North Africa. The company is an oil and gas producer in the United States, including the Permian and D.J. basins and the offshore Gulf of America. Occidental’s most recent dividend increase was on February 19, 2026. The board raised the quarterly dividend by more than 5%, from $0.24 to $0.26 per share. That bumped the annualized rate from $0.96 to $1.04.
Berkshire Hathaway has a large position in the company, owning 264,941,431 shares, representing 26.6% of the float and 4.3% of the portfolio.
Occidental’s oil and gas segment explores for, develops, and produces oil (including condensate), natural gas liquids (NGLs), and natural gas. The midstream and marketing segment purchases, markets, gathers, processes, transports, and stores oil (including condensate), NGLs, natural gas, carbon dioxide (CO2), and power. This segment provides flow assurance, maximizes the value of its oil and gas, and optimizes the company’s transportation and storage capacity. It also invests in companies that do similar activities, including low-carbon ventures.
A notable development was Occidental’s decision to sell its OxyChem subsidiary to Berkshire Hathaway, with the bulk of the proceeds expected to strengthen the company’s balance sheet and further concentrate its business on oil and gas. The move was notable because Buffett had reportedly long coveted OxyChem, and Berkshire now owns the business outright. Berkshire Hathaway completed its purchase of OxyChem from Occidental on January 2, 2026. That gives Buffett full ownership of the chemicals business while providing Occidental with $9.7 billion in cash to reduce debt and sharpen its focus on energy.
Wells Fargo has an Overweight rating on this stock and an $82 price objective.
The post Red October Sell-Off Could Be Coming: 5 Warren Buffett Dividend Stocks Are Safe Havens appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) CEO Mike Wirth said that the emergency oil buffers that softened the market after the Iran conflict began have been largely depleted. He argues those cushions cannot be repeated indefinitely, which leaves crude vulnerable to any fresh disruption.
He is backing that view with real money. Chevron has proposed a Venezuela expansion aimed at more than doubling output there by early next decade, and the project will be funded entirely with cash generated by its existing Venezuelan joint ventures.
That self-funding structure matters because it limits capital diverted from the Permian, Guyana, or the Gulf. You get an option on Venezuelan barrels without shrinking the buyback pool.
Wirth’s Shortage Call
Wirth’s supply case rests on more than one lever. He noted that strategic reserve releases and eased restrictions on some sanctioned oil inventories helped balance the market, but those actions cannot be repeated.
Prices agree for now. Brent settled at $109.51 on September 9, 2026, well above the $61.35 close on December 31, 2025.
On the earnings call, Wirth added that “demand destruction is not obvious to me at any significant scale”. Thin buffers plus resilient demand is the setup he is underwriting.
Depleted cushions are a real condition, but not a guarantee of sustained triple-digit crude. OPEC+ discipline and Chinese consumption remain the swing variables.
Numbers Behind the Bet
The Q2 results show why Chevron can lean forward. Adjusted EPS was $6.06, revenue $67.20 billion, up 51.43% year over year, and free cash flow $18.10 billion.
Worldwide production hit a record 4,070 MBOED, up 20% year over year, with U.S. upstream at a record 2,077 MBOED. Wirth credited “disciplined investment and strong execution”.
Hess integration is running ahead of schedule, with $1.5 billion in annual run-rate synergies inside one year and the $3 billion structural cost target hit six months early.
Venezuela’s Real Risk
Wirth said “we’re in negotiations right now to try to improve the fiscal terms and enable more investment in Venezuela”, and confirmed debt recovery should be complete by early 2027.
Moreover, output across the three joint ventures has climbed from 40,000 to 250,000 barrels per day. That trajectory is the empirical basis for the expansion pitch.
The risks here are principally political. Sanctions policy has shifted before, and Caracas contract enforcement is not the Permian, so you should treat elevated prices and future output as scenarios rather than guarantees.
Because the plan draws on Venezuelan cash already in hand, a policy reversal caps the loss instead of opening a new one.
Is CVX Stock a Buy?
CVX trades at $214.04, up 44.35% year to date, on a forward earnings multiple of 16x with a 3.28% dividend yield and a 39th consecutive annual dividend increase.
Analysts carry an average target of $221.21, with 6 strong buy and 14 buy ratings against 4 holds and 1 sell. Given the cash engine, Hess synergies, and self-funded Venezuela optionality, the setup screens favorably on fundamentals.
Venezuela offers adequate compensation for exceptional risk, while the Permian, Guyana, and refining remain Chevron’s most lucrative barrels. The core thesis remains the Permian, Guyana, and refining, with Caracas a low-cost call option on Wirth being right about spare capacity. I’d tag CVX stock a Buy due to oil prices remaining high. Even if the situation in the Middle East calms down, oil will stay high for longer due to all the infrastructure damage and all the oil reserve stockpiles that would have to be replenished.
The post Chevron’s CEO Thinks the World Is Out of Spare Oil. He Is Betting $7 Billion on Being Right. appeared first on 24/7 Wall St..
]]>Warren Buffett doesn’t chase yield, but his disclosed equity book at Berkshire Hathaway still throws off a steady stream of quarterly checks. Three of those names — Chevron (NYSE:CVX), Coca-Cola (NYSE:KO) and Occidental Petroleum (NYSE:OXY) — pay dividends on a quarterly cadence that anyone with a brokerage account can plug into. That is the practical hook for readers at or near retirement: the same routine income, from the same routine payers, sitting inside one of the most watched portfolios on Wall Street.
The positions discussed here come from Berkshire’s 13F for the period ended June 30 filed on Aug. 14 (SEC filing). A 13F covers U.S.-listed long equity only, so this is Berkshire’s disclosed common-stock book, not its cash, wholly owned businesses, private stakes, or fixed-income holdings. Positions are disclosed roughly 45 days after quarter end and may have changed since. Nothing here should be read as what Berkshire owns today.
What stands out across all three names is stillness. Share counts were unchanged from the prior quarter in every case. No trims, no adds, no exits. For income-focused readers, that is arguably the more interesting signal: these are the payers Berkshire left alone while collecting the checks.
Coca-Cola: The 400 Million Share Anchor
Berkshire disclosed 400 million shares of Coca-Cola, representing 10.86% of the disclosed portfolio, with the share count unchanged from the prior filing. Coca-Cola is the beverage concentrate and syrup business famous for its namesake brand and a global bottling network.
The dividend is the whole story for holders. Coca-Cola pays a quarterly dividend of $0.53 per share, with the next payment dated Oct. 1 following a Sept. 15 ex-dividend date. The annualized forward amount is $2.12, and the payment stepped up from $0.51 in 2025 to $0.53 in 2026, extending a long streak of annual increases. Current yield sits at 2.32%.
Fundamentals under the payout look sturdy. Q2 FY2026 delivered adjusted EPS of $0.97, revenue of $13.38B (up 6.7% year over year), and net income of $4.43 billion (up 16.1%), and management raised full-year guidance to organic revenue growth of about 5% and comparable EPS growth of 9% to 10%. Trailing P/E of 26 and forward P/E of 25 reflect defensive-consumer premium, not a bargain. Analyst consensus target is $94.70, with the rating breakdown showing seven Strong Buy ratings, 12 Buy ratings, four Hold ratings, zero Sell ratings and one Strong Sell rating. Shares are up 27.69% YTD.
Chevron: The Integrated Oil Dividend
Berkshire disclosed 84,375,856 shares of Chevron, representing 4.67% of the disclosed portfolio, with the share count unchanged. Chevron is an integrated energy company covering exploration, production, refining, marketing, and chemicals.
The dividend picture is straightforward. Chevron paid $1.78 per share on September 10, 2026, matching the prior two quarterly payments and stepping up from $1.71 through 2025. The annualized forward amount is $7.12, and the yield runs at 3.05%. The dividend history file shows steady quarterly cadence stretching back over two decades.
Q2 FY2026 was a stronger quarter than the ratios suggest. Chevron reported adjusted EPS of $6.06, revenue of $67.20B (up 51.4% year over year), and free cash flow of $18.10B (up 272%), with worldwide net oil-equivalent production hitting 4,070 MBOED, up 20% year over year on the Hess Corporation acquisition. The company also cut total debt by $8.41B in the quarter and signed a 20-year 2.67 GW power purchase agreement with Microsoft for a West Texas AI data center. Trailing P/E is 21 with a forward P/E of 16. The consensus target is $221.21, with six Strong Buy ratings, 14 Buy ratings, four Hold ratings, one Sell rating and zero Strong Sell ratings. Shares are up 37.45% YTD.
Occidental Petroleum: The Smaller E&P Slice
Berkshire disclosed 264,941,431 shares of Occidental, representing 4.30% of the disclosed portfolio, with the share count unchanged. Berkshire also holds Occidental preferred stock and warrants that do not appear in the 13F common-stock row, so the common position understates the full relationship. Occidental is a hydrocarbon exploration and production company with petrochemical operations across the Americas.
The common-stock dividend was 28 cents per share with a Sept. 10 ex-dividend date and an Oct. 15 payment date, up from 26 cents earlier in 2026 and 24 cents across 2025. Annualized forward runs to $1.12, with a yield of 1.65%. The company describes the increase as 8% higher this year.
Q2 FY2026 came in hot, with adjusted EPS of $2.40, beating consensus of $1.85, revenue of $8.33 billion (up 31.8% YoY), and free cash flow of $3.02 billion (up 214% YoY). Occidental retired $1.90 billion of debt in the quarter, bringing principal debt to $11.8 billion against a $10 billion target. Trailing P/E is 18 with a forward P/E of 16. The consensus target is $67.08, and analyst posture is more cautious: Two Strong Buy ratings, seven Buy ratings, 15 Hold ratings, zero Sell ratings and zero Strong Sell ratings. Shares are up 44.05% YTD.
What the Steady Hand Says About Berkshire’s Approach
Three dividend payers, three unchanged share counts. Coca-Cola sits at 10.86% of the disclosed portfolio, dwarfing Chevron at 4.67% and Occidental at 4.30%, with the beverage stake serving as the long-duration anchor and the two energy names as a paired bet on production, cash returns, and deleveraging. The disclosed book here leans consumer defensive at the top and layered energy below, and the through-line across all three is a payout backed by real free cash flow generation.
Doing nothing was the decision of the quarter. For income-focused readers, that inaction is instructive. For a dividend book, the compounding math works when share counts stay put and the payments keep landing. Coca-Cola raised its dividend in 2026, Chevron raised its dividend in 2026, and Occidental raised its dividend in 2026. Three payers, three raises, zero trades.
What Readers Can Actually Take From This
The takeaway is that the same quarterly checks are available on the same schedule to any investor willing to buy the same tickers, rather than mirroring Berkshire’s weightings. The next visible catalysts are Coca-Cola’s Oct. 1 payment, Occidental’s Oct. 15 payment and Berkshire’s next 13F filing, which will show whether these steady positions stayed steady through the September quarter. 13F disclosures are backward looking, price targets and forecasts are projections rather than guarantees, and none of this is investment advice.
The post Warren Buffett Collects Quarterly Dividends From These 3 Stocks. Should You? appeared first on 24/7 Wall St..
]]>Brent crude vaulted back above $100 a barrel this week after CNBC reported that US Central Command destroyed five Iranian crude oil tankers Tuesday in retaliation for attempted attacks on an American warship, the latest escalation in a Middle East conflict that has already scrambled global supply. This is a supply-shock story, and the distinction matters because it changes which energy names actually benefit. Below are five US-listed stocks in the line of fire, ranked by the directness of their exposure, with a clear read on the mechanism for each, according to CNBC.
1. ConocoPhillips (COP)
ConocoPhillips (NYSE:COP) is the purest upstream leverage on this list. Q2 2026 revenue jumped to $19.16 billion, up 37.1% year over year, and adjusted EPS of $3.24 beat the $2.96 consensus as Brent averaged $104.52 versus $67.82 a year earlier. Net income roughly doubled to $3.93 billion.
Analysts appear to have taken the hint. The 2026 full-year EPS estimate has moved to $10.4435, with 14 upward revisions against 2 downward in the trailing 30 days. Shares are up 49.35% year to date to $136.85. CEO Ryan Lance is not chasing the price signal with capex, telling investors ConocoPhillips remains “firmly on track to deliver our $7 billion free cash flow inflection by 2029” and that free-cash-flow breakevens should fall from the mid-40s WTI today to the low 30s by 2029. New Kirkuk and Syria positions add growth optionality and geopolitical risk in equal measure.
2. Exxon Mobil (XOM)
Exxon Mobil (NYSE:XOM) is the largest single beneficiary in absolute dollar terms, with a $675.3 billion market cap and upstream production of 4.6 million oil-equivalent bpd. Q2 delivered “industry-leading earnings of $14.5 billion” and $23.6 billion in cash flow from operations, even as CEO Darren Woods disclosed “the temporary loss of approximately 10% of our upstream production” tied to Middle East disruption.
The setup for Q3 gets more interesting with this news. Guyana is producing approximately 900,000 gross bpd, and CFO Neil Hansen said Exxon has now “fully recovered the $55 billion of investment”, an inflection that shifts more revenue into free cash flow. Golden Pass LNG shipped its first cargo in April 2026, and the Permian hit more than 1.8 million oil equivalent barrels per day. Shares are up 40.04% year to date to $165.23, essentially at the analyst target of $170.91.
3. Chevron (CVX)
Chevron (NYSE:CVX) is the double-barreled play: upstream torque plus a refining segment already firing. Q2 revenue reached $67.20 billion, up 51.4% year over year, with net income of $12.07 billion and downstream earnings rocketing to $4.87 billion from $737 million a year earlier. Worldwide production hit 4,070 MBOED, up 20% on the Hess deal.
CEO Mike Wirth flagged “Products are tighter than crude around the world, and that’s why cracks have widened out” and expects “some upward pressure on product pricing here into the third quarter and perhaps beyond that.” Chevron reduced debt by $8.41 billion in Q2 alone and hit its $3 billion structural cost savings target six months ahead of schedule. Shares trade at $213.95, up 44.28% year to date, with 2026 EPS estimates lifted to $16.0382 on 19 upward revisions in 30 days.
4. Valero Energy (VLO)
Valero Energy (NYSE:VLO) is the double-edged case out of this group. Refining margin per barrel of throughput nearly doubled to $23.62 versus $12.35 a year earlier, US Gulf Coast ULS diesel margin surged to $43.52/bbl from $14.79, and adjusted EPS of $12.54 beat estimates by 23.84%. Renewable Diesel swung to $717 million operating income from a $79 million loss. Shares have exploded 141.89% year to date to $387.93.
Here’s the catch: sustained $100+ crude eventually compresses gasoline demand and squeezes downstream. COO Gary Simmons cited approximately 5 million bpd of global refining capacity offline and 1.7 to 1.9 million bpd of Russian capacity down, supporting a bullish mid-cycle margin view. That thesis works until it does not. Valero already has California regulatory overhang and shut refining ops at Benicia.
5. Schlumberger (SLB)
Schlumberger (NYSE:SLB) is the paradox on this list. Higher crude typically pulls customer capex, but SLB’s most profitable region is the exact geography being disrupted. Middle East & Asia revenue fell to $2.57 billion, down 14% year over year, with force majeure in Qatar, shut-ins in Iraq and security demobilizations. Net income slid 22.5%.
CEO Olivier Le Peuch is framing this as a delayed setup. He said “The market is starting to exhibit the characteristics of an upcycle” and cited third-party data pointing to FIDs for long-cycle projects rising approximately 30% year-on-year in 2026. Shares are up 47.96% year to date to $55.89 but slipped 3.85% over the past week as tanker headlines rekindled Middle East risk. Analyst target sits at $62.24.
Caveat Investors Should Not Ignore
A geopolitical risk premium can unwind as fast as it was priced in. WTI was at $91.48 on September 1 after touching $114.58 on April 7, and the one-year band has run from $55.44 to $114.58. Buying an energy name on this move means buying part of that geopolitical premium rather than a durable shift in the underlying supply picture. Upstream-heavy names get the cleanest earnings lift; a refiner rides crack spreads until demand cracks; and the services giant needs the shooting to stop before its highest-margin region can rebuild.
The post Oil Just Blew Past $100 a Barrel and These 5 Energy Stocks Are in the Line of Fire. appeared first on 24/7 Wall St..
]]>Five diesel pumps in California have run out of digits. The dispensers are showing $9.999 a gallon, the highest figure their hardware can display, according to a September 10, 2026 post from GasBuddy head of petroleum analysis Patrick De Haan, who cited the fuel-price app’s real-time crowdsourced data. As of this writing, no other outlet has independently corroborated the count or identified the stations, and GasBuddy’s real-time feed is the sole source. We are not naming stations, cities, or brands because that information is not in the sourcing, and we are not alleging any retailer chose the number on the display.
A Hardware Ceiling on the Display
The $9.999 figure is almost certainly a physical limit rather than a posted rate. The precedent is well known. During the 2008 oil spike, older mechanical pumps installed decades earlier could not show a price above $3.99 a gallon because their displays had a fixed number of digits. Retrofitting or replacing those units cost an estimated $10,000 to $15,000 per pump, a bill many small operators could not absorb. A ceiling at $9.999 today is the same category of constraint with one additional digit of headroom.
Record Prices Behind the Maxed-Out Pumps
Those five displays are the extreme edge of a genuine record. The U.S. Energy Information Administration put California’s average diesel price at $7.76 a gallon as of September 9, 55 cents higher than a week earlier and $2.81 higher than a year earlier. AAA’s figure for the same date was $7.87.
Nationally, diesel just set a fresh all-time high. The U.S. Energy Information Administration reported an average U.S. retail diesel price of $5.97, up 3.7 cents on the week and $1.97 higher than a year earlier, surpassing the U.S. Energy Information Administration’s previous record of $5.81 set in June 2022. AAA showed a record $5.94 on the same date.
A California Pattern in 2026
The state has produced outlier prints all year. In March 2026, a Chevron (NYSE:CVX) station in the remote desert stop of Fenner was reported charging $9.69 a gallon for regular gasoline. In early May 2026, a Downtown Los Angeles Chevron was reported at $8.29 for regular and $8.89 for diesel, with drivers describing fill-ups of $100 to $110. Those were separate earlier incidents at different stations preceding today’s report.
Regulators Are Already Watching
California’s Division of Petroleum Market Oversight, led by director Tai Milder, issued an enforcement bulletin and consumer advisory on March 19, 2026 and opened an investigation into outlier pricing in the Los Angeles and San Bernardino areas. The agency subpoenaed data from the state’s five major refiners under Senate Bill X1-2, the price-gouging law enacted in a 2023 special session. The probe is active and unresolved. No allegations have been proven.
Why Diesel, Why Now
The pressure is coming from several directions at once. The U.S. Department of Energy has said U.S. refineries are running at about 98% of capacity. Heavy Duty Trucking reports that since the U.S. attacked Iran in February, Iran’s control of the Strait of Hormuz has scrambled regional oil logistics. Heavy Duty Trucking also cites Ukrainian drone strikes cutting Russian refinery output and falling Chinese refiner output. Crude sits in the upper end of its recent band, with Heavy Duty Trucking placing prices between $90 and $100 per barrel.
Where the Cost Actually Lands
Diesel moves freight, tractors, and food. A record at the rack shows up in grocery aisles, restaurant menus, and the price of anything trucked across the country. Households already feel it: the national average for regular gasoline reached $4.157 a gallon the week of September 7, and the University of Michigan consumer sentiment index stood at 55.2 in July, still below the 60 threshold the survey associates with recessionary conditions. The maxed-out pumps GasBuddy is describing are the visible edge of a real crisis in the state with the country’s highest fuel prices, and the regulator with subpoena power is already inside the market.
The post “Maxed Out!” GasBuddy Says 5 California Gas Stations Hit $9.999 For A Gallon Of Diesel, The Highest Price Their Systems Allow appeared first on 24/7 Wall St..
]]>ExxonMobil (NYSE:XOM) stock is climbing Wednesday afternoon, extending a strong year for U.S. oil majors. ExxonMobil shares are up 3% in the current session to $164.83, carrying a 40% year-to-date gain. WTI crude oil has done much of the heavy lifting, and today it’s up 3.29% over the past 24 hours to $96.09 per barrel.
The question posed in the title is whether that momentum carries ExxonMobil stock to $200. That path exists, but it runs through crude prices rather than anything ExxonMobil directly controls.
Oil Prices and Refining Margins Do the Heavy Lifting
The rise of the WTI crude oil price reflects Middle East supply disruptions and tight product markets, and has a direct impact on energy majors’ financials. BP (NYSE:BP) reported a Q2 refining indicator margin of $29.6 per barrel versus $11.9 a year ago, a spread that flowed into downstream results across the group.
ExxonMobil’s Q2 2026 results delivered $14.5 billion in earnings, more than $17 billion of free cash flow, and a more than $7 billion reduction in net debt. Guyana production ran at roughly 900,000 barrels per day, and Permian output hit a record 1.8 million oil-equivalent barrels per day. The company’s cumulative structural cost savings reached $16.3 billion since 2019, part of a $20 billion target by 2030.
Sector Rally Left the Biggest Major Behind
Chevron (NYSE:CVX) stock has gained 44% year to date, outpacing ExxonMobil. Meanwhile, the Energy Select Sector SPDR ETF (NYSEARCA:XLE) has advanced 48% year to date to $65.39. ExxonMobil is the XLE ETF’s largest position at 22.7% of net assets, so the rest of the energy complex has run harder than the biggest U.S. major.
The European ADRs land lower on the leaderboard. Shell (NYSE:SHEL) stock has climbed 33% year to date. Additionally, BP stock has risen 35% year to date, leaving ExxonMobil ahead of both and confirming that the ranking depends entirely on the comparison chosen.
XOM Stock’s Path to $200
Getting ExxonMobil stock to $200 likely requires WTI crude oil to hold near its current levels and refining spreads to stay wide. With the oil price already up in recent sessions, the fade risk shouldn’t be overlooked.
ExxonMobil’s own contribution is real but incremental. Guyana is transitioning from investment recovery to free cash flow, with management guiding to twice the 2025 level by 2030. A 2026 buyback plan of $20 billion, with $4.9 billion already completed in Q1, provides a per-share tailwind even if crude softens.
What to Watch
The next WTI crude oil price move and any change in Middle East shipping conditions could matter just as much as the next ExxonMobil filing. Investors may want to keep an eye on whether the oil price holds above the mid-$90s into the fourth quarter, with refining cracks likely to stay wide as European capacity remains constrained.
The $200 level implied by the title is achievable, but it depends on macro conditions rather than company execution. Position sizing in ExxonMobil stock should reflect that this is a commodity-price story wrapped around a well-run operator, and their exposure should scale accordingly.
The post ExxonMobil Is Up 40% in 2026: Can Rising Oil Prices and Strong Earnings Boost XOM Stock to $200? appeared first on 24/7 Wall St..
]]>Chevron has ripped higher through 2026, and the rally has pushed shares within reach of a fresh record. The question I want to answer is whether the 24/7 Wall St. price target still sees room to run, or whether the market has already priced in the good news.
Chevron (NYSE:CVX) trades at $212.26, up 42.82% year to date and 36% over the past year. Our 24/7 Wall St. price target for Chevron is $204.67, implying downside of 3.81% over the next twelve months. Our recommendation is hold, with high model confidence of 90%.
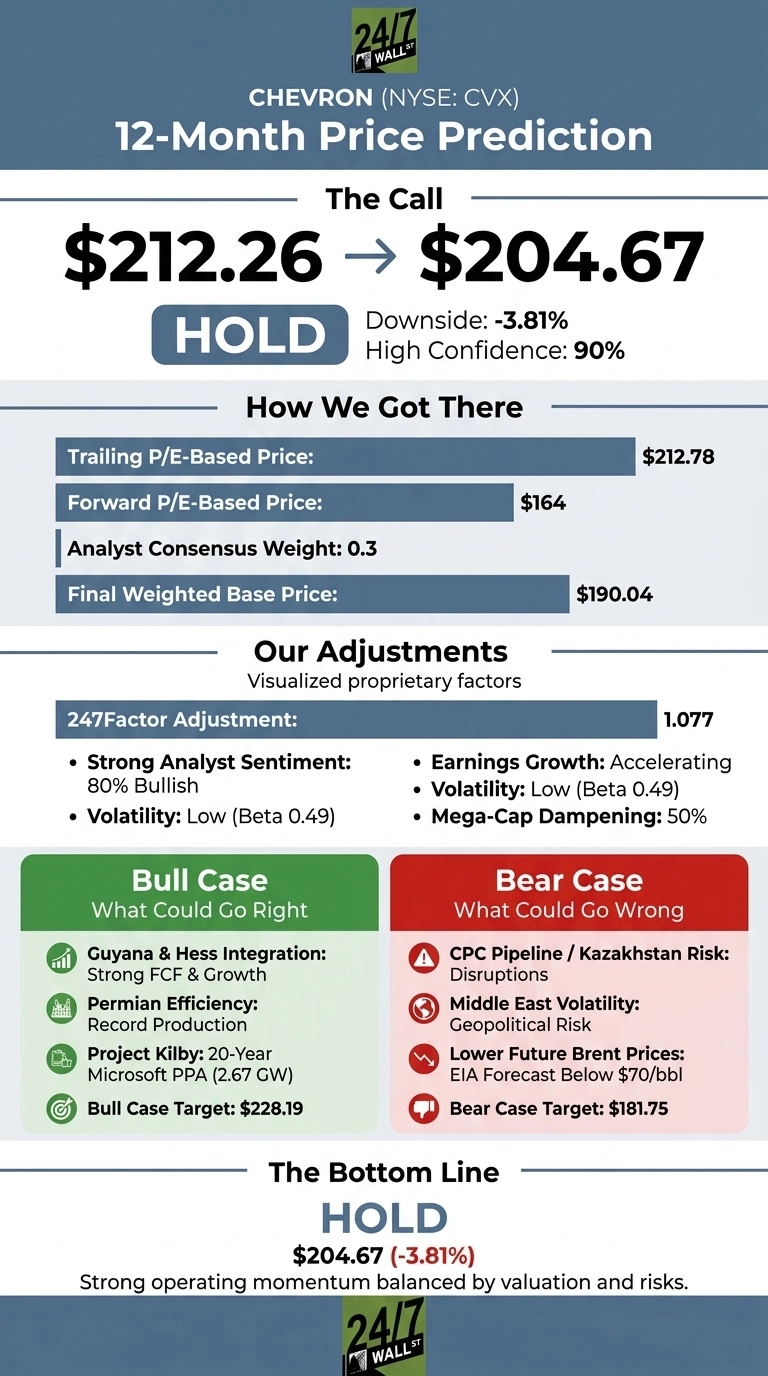
| Metric | Value |
|---|---|
| Current Price | $212.26 |
| 24/7 Wall St. Price Target | $204.67 |
| Upside/Downside | -3.81% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits just below where Chevron trades today.
Bull scenarios exist: the 20-year Microsoft (NASDAQ:MSFT) power purchase agreement covering 2.67 gigawatts at Project Kilby could unlock a new commodity-independent cash flow stream, and Brent staying elevated on Strait of Hormuz tightness could easily push earnings past current estimates. Consider the target one datapoint. A full bull case follows below.
A Rally Built on Real Numbers
Chevron is up 10.58% over the past month and 5.78% over the past week, brushing against a 52-week high of $212.79.
Q2 FY26 was the fuel: adjusted EPS of $6.06, revenue of $67.20B (+51.43% YoY), and worldwide production of 4,070 MBOED (+20% YoY), marking a seventh straight EPS beat. Chevron also cut total debt by $8.41B in the quarter. WTI has cooperated too, climbing to $91.48 on September 1 from the mid-$70s a month earlier.
Why Bulls See a Breakout Above $228
The bull case rests on four legs: Guyana, Permian efficiency, Kilby, and cash returns. Mike Wirth called Chevron’s opportunity set “the largest and highest quality opportunity set that we’ve had in years,” and the company delivered $15.4 billion in adjusted free cash flow in the quarter with net debt to CFFO of just 0.6 times.
Chevron captured 50% more Hess synergies than initially targeted and is targeting 2-3% annual production growth and 10%+ adjusted free cash flow growth through 2030.
Our bull-case one-year price is $228.19, and Wall Street’s consensus target sits at $218.29 with 20 buy or strong-buy ratings.
Risks Worth Watching Before Chasing the Rally
Chevron trades at a P/E of 34, well above peers, and the model’s bear case lands at $181.75. Brent averaging $104/BBL lifted Q2, but the EIA sees Brent below $70 per barrel in real 2025 dollars through 2030. CPC pipeline risk in Kazakhstan and Middle East volatility remain live.
A counterpoint: the elevated trailing P/E reflects prior-year charges rather than structural weakness, and Chevron already hit its $3B structural cost reduction run-rate six months ahead of schedule.
How Chevron Compares to Exxon and ConocoPhillips
Exxon Mobil (NYSE:XOM) is the natural integrated benchmark and trades at a P/E of 23 with a return on equity of 11.03%, versus Chevron’s ROE of 7.26%. Exxon’s $20 billion 2026 buyback and Guyana leadership justify a premium, and its cheaper multiple makes Chevron’s valuation look stretched.
ConocoPhillips (NYSE:COP) is the pure-play upstream counterpoint. COP delivered Q2 26 adjusted EPS of $3.24 on $19.16 billion in revenue (+37.07% YoY) and is targeting 45% of cash from operations returned to shareholders in 2026. Its capital-return intensity exceeds Chevron’s, reinforcing my view that CVX’s premium is fair rather than cheap.
| Company | P/E | Dividend Yield |
|---|---|---|
| Chevron | 34 | 3.07% |
| Exxon Mobil | 23 | 2.55% |
| ConocoPhillips | N/A | N/A |
Chevron Price Prediction 2026-2030
My verdict is hold, with 90% confidence and a 24/7 Wall St. price target of $204.67. The key factor tipping the scale: the stock is up more than 42% YTD and now sits at 52-week highs while forward multiples price in perfect execution.
The bullish setup strengthens if Brent holds above $95 and Project Kilby reaches final investment decision this year. The setup weakens if WTI slips back toward the July low of $69.60 or if CPC disruptions escalate.
Looking further out, here is where our model projects Chevron could trade, assuming current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $204.67 |
| 2027 | $202.79 |
| 2028 | $204.09 |
| 2029 | $209.02 |
| 2030 | $214.57 |
These projections assume Chevron continues executing on Hess integration, Permian efficiency, and Project Kilby. Significant upside could come from sustained Brent above $100, while a demand slowdown could push shares toward the bear case of $184 by 2030.
The post Chevron Stock Is Near a Record High. Here’s Why the Rally May Not Be Over appeared first on 24/7 Wall St..
]]>Replacing a $95,000 salary with dividends is a capital problem before it is an investment problem. At a blended portfolio yield near 4%, you need about $2.4 million. At 5%, roughly $1.9 million. At 6%, closer to $1.6 million. The lineup below, built around VYM at 30%, CVX at 30%, and UTG at 40%, is designed to sit somewhere in that middle band while paying you monthly and quarterly in real cash.
Three-Holding Income Lineup: VYM, CVX, UTG
The conservative anchor is Vanguard High Dividend Yield ETF (NYSEARCA:VYM), a broad basket of large-cap dividend payers whose top exposures include Broadcom, JPMorgan Chase, Exxon Mobil, Johnson & Johnson, and AbbVie. VYM pays quarterly, with an annualized forward dividend of $3.92 per share against a recent price near $164. Typical distribution yield sits in the low-3% range.
The dividend-growth sleeve is Chevron (NYSE:CVX). The company just paid a $1.78 quarterly dividend, up from $1.71 in 2025 and $1.63 in 2024. Trailing yield sits near 3.1%, supported by $18.10 billion of free cash flow in Q2 FY26 and a 20-year West Texas power purchase agreement with Microsoft.
The income engine is Reaves Utility Income Fund (NYSE:UTG), a closed-end fund that pays monthly. Its monthly distribution recently increased to $0.21 from $0.20, giving an annualized forward of $2.52 per share at a price near $38. That places UTG’s headline yield in the mid-to-high single digits, well above the two equity holdings.
Why a Rising Chevron Makes Your Plan More Expensive
Chevron is up 41% year-to-date and 37% over the past year, with news of a $7 billion Venezuela expansion plan pushing shares toward record highs. That is good if you already own it. It is bad if you are still buying, because yield is the dividend divided by the price. As CVX climbs, its yield compresses, which drags the blended portfolio yield lower and raises the capital you need to hit $95,000. A stock going up makes an income plan more expensive, which is counterintuitive, and it is exactly why the entry price matters as much as security selection.
UTG Is Doing the Heavy Lifting. Read the Fine Print.
The utility fund UTG is a closed-end fund, which means it trades at a market price that can drift above or below the actual value of its underlying holdings. Buying when it trades at a premium is a permanent headwind, while buying at a discount gives you a lasting advantage. Make it a point to check that before you buy.
Closed-end funds often use leverage to boost their distributions. That borrowed money lifts income when markets are strong but magnifies losses when they turn, and it makes the fund more sensitive to interest rates than an unlevered utility ETF. UTG’s distributions can also include a return of capital, which lowers your cost basis rather than paying you out of actual earnings. Pull the fund’s Section 19 notices and verify the composition.
Then there is the concentration issue. This lineup is 30% energy and 40% utilities. You are making a focused bet on regulated power, infrastructure, and integrated oil, with VYM providing the only real spread across financials, health care, and consumer staples.
Tax Layer Most Pre-Retirees Underweight
VYM and CVX distributions are generally qualified dividends, taxed at long-term capital gains rates (0%, 15%, or 20% federal, depending on bracket). UTG’s distributions vary in character: portions may be qualified, ordinary, or a return of capital. Two portfolios paying identical headline yields can leave you with very different after-tax income.
Account location changes the answer materially. In a Roth or traditional IRA, character does not matter; in a taxable brokerage, it dictates how much capital you actually need to net $95,000. Model both.
What You Are Really Signing Up For
To replace a $95,000 salary with this lineup, plan on somewhere in the neighborhood of $1.6 to $2.0 million invested, depending on where blended yield lands the day you build the position. If you want the full mix, payment calendar, and withdrawal order for turning a lump sum into monthly income, we laid the whole method out in a free guide. A few actions before you commit capital:
- Target your spending rather than your gross salary. Payroll taxes and retirement contributions are gone in retirement, so the target income is usually lower than the paycheck.
- Check UTG’s premium or discount to net asset value on the day you buy, and review the most recent Section 19 notice for return-of-capital content.
- Stress-test the plan for a Chevron dividend cut and a UTG distribution reduction at the same time, and confirm the surviving income still covers essential expenses. Dividend streams can fluctuate, and inflation over a 30-year retirement will erode any fixed stream that does not grow.
The post How Much Do You Really Need Invested to Replace a $95,000 Salary With Dividends? appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) shareholders are set to collect another $1.78 per share quarterly payment on September 10, 2026, extending a streak most oil majors envy. The check is the third at the current rate, which reflects a 4% raise announced at the start of 2026, marking the 39th consecutive annual increase. With shares at $212.21 and up 42.32% year to date, the current yield sits at roughly 3.08%.
For a commodity-linked payer, the check looks easy with Brent at $104. The real question is what happens when crude rolls over. That answer is where Chevron earns its scorecard.
Dividend Scorecard: A Grade, With an Asterisk
Q2 2026 delivered adjusted EPS of $6.06 on revenue of $67.20 billion, up 51.43% year-over-year. Free cash flow hit $18.095 billion against a quarterly dividend outlay near $3.504 billion. Full-year 2025 produced $33.94 billion in operating cash flow versus $12.75 billion in dividend payout. Balance sheet: net debt to cash flow from operations of 0.6 times after more than $8 billion in debt reduction last quarter.
FY2025 EPS came in at $6.63 while the annualized forward dividend runs $7.12. On trailing earnings, that reads over 100%. On free cash flow, it clears comfortably. Grade: A minus. Elite streak, elite coverage in a good tape, but the ratio compresses fast when crude cracks.
2020 Stress Test You Should Actually Care About
When WTI collapsed to $36.97 in November 2020, Chevron generated only $10.6 billion of operating cash flow for the full year and paid out $9.7 billion in dividends. Q2 2020 operating cash flow was just $80 million against a $2.394 billion dividend. Chevron leaned on the balance sheet, protected the payment, and kept the streak alive. That is the resilience the current management team is being paid to replicate.
What Actually Changes the Math This Cycle
The Hess integration delivered $1.5 billion in synergies six months ahead of schedule, and management called Hess free cash flow “roughly double the incremental dividends”. Also, Project Kilby, a 20-year take-or-pay power purchase agreement with Microsoft covering 2.67 gigawatts, is designed to throw off “long duration contracted cash flows that are independent of commodity price cycles.”
Mike Wirth summarized the philosophy plainly: “We’ll always focus on value over growth.” For dividend investors, the read is straightforward. The payment is safer than the ratio suggests, but only because Chevron has, again and again, chosen the check over almost everything else. Streaks like this one are the whole reason we built a free Dividend Kings screen ranking the longest-running raisers by valuation today.
The post Chevron’s Dividend Looks Great at $104 Oil—What Happens When Oil Falls? appeared first on 24/7 Wall St..
]]>Although Chevron (NYSE:CVX) shares have climbed to a 52-week high on the back of a $7 billion Venezuela expansion, to above $214 per share, Wall Street’s memory tends to be shorter than the deals it finances. The stock closed at $211.78, up 38.8% year to date, and traders appear to be treating its Venezuela Orinoco Belt agreement as a straightforward production add.
But Bloomberg Economics’ Chris Kennedy went on air September 2 and framed the arrangement in language that should give any long-term holder pause. Kennedy said “this was all about oil,” comparing the U.S. and Venezuela structure to the 1953 US-backed coup against Iran’s democratically elected Mohammad Mosaddegh, which reversed his nationalization of the Anglo-Iranian Oil Company, later BP.
The parallel is uncomfortably clean. As Kennedy described it during the Bloomberg Businessweek segment, the current arrangement involves a Pentagon equity stake in a private company granted a 100-year lease to develop nearly 17 strategic oil fields. The U.S. also receives the right to purchase 20% of the joint venture’s production at cost, below market price. Chevron CEO Mike Wirth has called it the largest financial commitment from a major oil company since Nicolás Maduro’s ouster and said the development is expected to double Chevron’s operations in the country. Marketplace’s Kimberly Adams reported that the plan targets roughly 600,000 barrels a day within five years.
What 1953 Actually Bought, and What It Cost
Operation Ajax worked, at first. The 1953 coup restored the Shah, reversed Mosaddegh’s nationalization, and gave Western majors decades of favorable Iranian crude. For 25 years the arrangement looked like a geopolitical bargain. Then 1979 arrived. The Islamic Revolution swept out the Shah, renationalized Iranian oil, and expropriated Western assets. Anti-American sentiment cemented into state policy, and the U.S. lost one of its largest imported-crude suppliers almost overnight. The lesson Wall Street has never fully absorbed is that oil concessions tied to unpopular regimes tend to expire when the regime does, not when the lease says they do.
Bloomberg’s Kennedy’s warning tracks that history closely. He argued the Venezuela structure “could rekindle nationalist and anti-American sentiment” and called a democratic transition in Caracas “a matter of when, not if.” A 100-year lease is a long time to bet against that pattern.
Why the Market Is Ignoring the Precedent
The market has plenty of reasons to focus on the immediate payoff. CVX has climbed 42.82% year to date, 36% over one year, and 165.4% over five years amid extraordinary near-term fundamentals. Chevron’s Q2 2026 report, filed July 31, 2026, showed adjusted EPS of $6.06, revenue of $67.20 billion (+51.4% YoY), and net income of $12.07 billion (+384.8% YoY).
Free cash flow hit $18.10 billion, an increase of 272%. Worldwide production reached 4.07 million barrels of oil equivalent per day, while U.S. upstream production set a record at 2.08 million barrels of oil equivalent per day. Brent averaged $104 per barrel, versus $68 a year earlier, and WTI stood at $91.48 per barrel on September 1.
Chevron has also put its cash to work aggressively: $3.117 billion in buybacks in Q2 2026, a 39th consecutive annual dividend increase (the kind of multi-decade streak we screened for in our free Dividend Kings guide, here), and $8.41 billion in debt reduction inside the quarter. The Hess acquisition, closed in 2025, is producing $1.5 billion in synergies within one year of closing. Nothing in that scorecard reads like a company priced for expropriation risk. You can see the Q2 disclosure directly in the company’s SEC filing.
Valuation Gut Check Meets Political Half-Life
Here, the historical mirror becomes sharper. Chevron trades at a P/E of 28.9, a P/FCF of 25, and a free cash flow yield of 3.99%, with a market cap of $414.9 billion. Integrated majors historically trade closer to the low-teens on earnings during comparable oil-price regimes.
Investors are paying a premium multiple for a company whose largest new development sits under a lease that, if the Iran comparison holds, has a shelf life measured by the political durability of the counterparty. Chris Kennedy noted Venezuela currently averages 1.1 million barrels per day, well below its peak of 3.5 million barrels from nearly three decades ago. The upside case requires the current arrangement to last.
Markers to Watch as the 100-Year Lease Ages
Three signals will show how much weight that century-long promise can bear. First, whether Caracas ratifies the lease through any body a successor government would recognize as legitimate. Second, whether the 20%-at-cost offtake clause survives scrutiny inside Venezuela, where subsidized exports to the U.S. read very differently on Caracas television than on a Bloomberg terminal. Third, whether Chevron’s next 10-Q quantifies the Venezuela commitment as a discrete asset, which would let analysts model an impairment scenario. The Q2 filing already flags “geopolitical uncertainty in Venezuela operations” as a named risk.
Over the long term, the benchmark S&P 500 has absorbed oil-sector expropriations before and headed higher in the decades that followed, and Chevron’s record on dividends, buybacks, and structural cost reductions is genuinely elite. The open question for CVX shareholders paying a 52-week-high price is whether they are being compensated for a risk the 1953 Iran playbook says typically arrives on someone else’s schedule.
The post Bloomberg Economist: ‘This Was All About Oil’ and Compares Chevron’s Venezuela Deal to 1953 Iran Coup appeared first on 24/7 Wall St..
]]>Venezuela reportedly lays claim to over 300 billion barrels of proven oil reserves, and the U.S. has set its sights on more of them.
Bloomberg News correspondent Tyler Kendall reported from Caracas this week that the headline prize of Washington’s Venezuela deal, a 100-year lease on 17 strategic oil fields holding a claimed 65 billion barrels, went to a private, non-supermajor bidder: North American Blue Energy Partners, a private company that cannot develop the fields alone and has yet to sign on producing partners. Meanwhile, Chevron (NYSE:CVX) stock just printed a fresh 52-week high at $212.79 on a separate, parallel Venezuela commitment. The two developments deserve to be evaluated separately.
What Washington Actually Signed
Kendall’s on-the-ground reporting laid out the mechanics. The US government is taking an equity stake in the private joint venture and securing the right to purchase 20% of the offtake at cost, below market, through a swap mechanism designed to help refill the Strategic Petroleum Reserve. US Energy Secretary Chris Wright told Bloomberg that Venezuelan production, already up 25%, with exports up 50%, could double by the end of this decade from the current 1.1 million barrels per day; that output is still far below the 3.5 million peak from nearly three decades ago.
The catch is that North American Blue Energy Partners cannot develop the 17 fields alone. It must bring in other producers, including some fields previously operated by Russian, Chinese, or smaller local companies. Constitutional questions surrounding Venezuela’s competitive-bidding requirements remain unresolved, although the State Department says the deal was fully vetted.
Chevron’s Separate Lane
Chevron is executing a distinct, older track, separate from the 65-billion-barrel lease. On the Q2 2026 call, CEO Mike Wirth described Venezuela as one of Chevron’s “special situations,” revealing, “We’re in negotiations right now to try to improve the fiscal terms and enable more investment in Venezuela.”
Management also said the company operates three Venezuelan joint ventures and has bolstered production from those agreements from 40,000 to 250,000 barrels per day, with full debt recovery expected by early 2027. Chevron’s Q1 2026 growth-initiative slate specifically listed an agreement to expand its heavy oil interest in Petroindependencia and develop the adjacent Ayacucho 8 area, alongside its long-running Petropiar operations with PDVSA.
Wirth’s framing in the Q4 2025 8-K: “We have been a part of Venezuela’s past for more than a century. We remain committed to its present.” That century of ground presence is what separates Chevron’s exposure from the newer, splashier lease.
Economist Parallel Investors Should Weigh
Not everyone is convinced. Bloomberg Economics’ Chris Kennedy compared the deal structure to the 1953 US-backed coup in Iran, warning it could rekindle nationalist and anti-American sentiment and affirming the view that “this was all about oil.” Iran’s oil was nationalized in 1979. Kennedy called a democratic transition in Venezuela “a matter of when, not if,” raising real questions about the durability of a 100-year lease under a future elected government. Wirth has emphasized contractual protections including dispute resolution and tax and royalty regime guarantees, though those provisions face a hostile-precedent problem.
What The Market Is Actually Pricing
CVX is up 39.5% year to date and 35% over one year, backed by tangible Q2 2026 numbers: adjusted EPS of 6.06, revenue of $67.2 billion up 51.43% year over year, and free cash flow of $18.1 billion. The stock trades at a forward P/E of 15 with a 3.4% dividend yield backed by 39 consecutive annual increases.
Hess synergies, Permian scale, Guyana’s Stabroek block, and a 20-year Microsoft (NASDAQ:MSFT) power purchase agreement for 2.67 GW in West Texas are doing the heavy lifting. Venezuela is optionality on top of the core thesis. Investors pricing the 52-week high should separate the 65-billion-barrel headline from what Chevron actually holds itself.
The post Who Really Got Rights to Venezuela’s 65 Billion Barrels Of Oil Prize? appeared first on 24/7 Wall St..
]]>Dividend Aristocrats get lumped together as if they are one defensive blob of consumer staples names, but the label actually spans wildly different business models. The three companies below sit in payroll processing, supplemental insurance and integrated energy, and each has stacked annual dividend increases well past the 25-year bar the headline demands.
The CEO of Aflac (NYSE:AFL) explicitly cited “43 consecutive years of dividend increases” on the company’s Q2 2026 call, and the payment histories for the other two on this list reach back to 1999 with step-ups nearly every year since.
That is the point: Aristocrat status is a discipline that cuts across sectors.
Automatic Data Processing: Payroll’s Compounding Machine
Automatic Data Processing (NASDAQ:ADP) currently yields 2.42% at a share price of $281.16. The forward annualized dividend sits at $6.80 after the quarterly rate stepped up from $1.54 to $1.70 earlier this year. The dividend history file shows a clean progression of annual increases in the regular quarterly rate from $0.07625 in 1999 to $1.70 in 2026, which comfortably clears the 25-year threshold.
Coverage is the reason income investors keep buying it. FY2026 diluted EPS came in at $11.04 against a $6.64 trailing dividend, and operating cash flow was $5.44 billion against just $196.6 million of capex. The balance sheet is investment-grade quiet, return on equity runs at 72.2%, and management funds buybacks on top of the dividend. CFO Peter Hadley described capital return this way: “this deliberate return of capital to shareholders comes in addition to our longstanding commitment to growing our dividend and to the levels of investment that we are making in our business.”
The bull case: Boring in the best way. ADP is guiding FY2027 to 5% to 6% revenue growth and 9% to 11% adjusted EPS growth, with client retention already at 92.1% and Retirement Services crossing $1 billion in annual revenue for the first time. That is the profile of a compounder that funds larger dividends year after year.
The risk: valuation. At 26 times trailing earnings and 23 times forward, ADP is priced as a premium compounder, and any slip in bookings growth or margin cadence would compress the multiple faster than the dividend can grow.
Aflac: Supplemental Insurance With a 43-Year Increase Streak
Aflac trades at $117.24 and yields 2.08% on a quarterly dividend of 61 cents, with an annualized forward rate of $2.44. The recent step-up from 58 cents to 61 cents per quarter is the increase that extends the record in 2026. CEO Dan Amos was direct on the Q2 call: “We treasure our 43 consecutive years of dividend increases and remain committed to extending this record in 2026.”
Dividend safety here starts with capital. TTM diluted EPS is $9.27 against a $2.38 dividend per share, so payout coverage is roughly a quarter of earnings. Aflac Japan reported a pre-tax margin of 34.3% in the quarter, holding-company unencumbered liquidity was $3.3 billion, adjusted leverage stayed 21.8% within the 20 to 25% target, and regulatory capital was an estimated ESR of 226% in Japan and combined RBC slightly above 600%. That is a capital fortress by any insurance standard.
The bull case: Aflac converts capital strength into steady buybacks and dividend hikes. CFO Max Broden confirmed “we’ve repurchased $983 million of our own stock and paid dividends of $309 million in Q2.” Combined shareholder returns reached $1.3 billion in the second quarter and $2.6 billion for the first six months. Adjusted ROE ex-currency was 16.6%, and dental and vision inside the US group business grew 47% in the second quarter.
The risk: The yen. Aflac’s largest earnings engine reports in yen, so a stronger dollar directly compresses reported revenue and EPS, and US group disability claims have been running hotter than plan, pressuring the segment’s margin.
Chevron: Integrated Energy With the Highest Yield in the Bundle
Chevron (NYSE:CVX) is the higher-yielding piece of this trio at 3.36%, with a quarterly dividend of $1.78 (annualized forward $7.12) and shares at $211.78. The payment history shows a clear climb in the quarterly rate from 65 cents in 2000 to $1.78 in 2026, with successive annual step-ups more than sufficient to clear the 25-year bar.
Coverage in the current cycle looks excellent. Q2 2026 delivered adjusted earnings of $12 billion, or $6.06 per share, with adjusted free cash flow of $15.4 billion and cash flow from operations excluding working capital of nearly $20 billion. Chevron reduced debt by more than $8 billion in the quarter, taking net debt to CFFO to 0.6x. Interest coverage on the trailing basis is 13.7x, and structural cost cuts hit $3 billion of annual run-rate savings, achieved six months early.
The bull case: Chevron has bolted contracted cash flow onto its commodity base. Project Kilby is a 20-year take-or-pay power purchase agreement with Microsoft for 2.67 gigawatts of firm behind-the-meter capacity, and management describes it as delivering “mid-teens returns and long duration contracted cash flows that are independent of commodity price cycles.” Wirth added: “Consistent with our longstanding financial priorities, we intend to reward our shareholders today tomorrow and long into the future.” Chevron has now returned more than $5 billion to shareholders for 16 consecutive quarters.
The risk: Commodity cycles. This is where CVX diverges sharply from ADP and AFL. Chevron’s cash flow rides Brent, and the EIA’s May 2026 Short-Term Energy Outlook shows OPEC surplus capacity and non-OPEC supply growth that can cap prices even as demand climbs. Management set 2030 targets “at flat commodity prices that are lower than today,” which acknowledges that softer oil prices would slow buybacks before slowing the dividend.
3 Streaks, 3 Different Cash Engines
The Dividend Aristocrat badge means the same thing at all three companies: management has raised the dividend every year for at least 25 years and treats that record as untouchable. What backs the checks is completely different. ADP compounds off recurring payroll fees and 92%+ client retention. Aflac funds the payout with a fortress-capital insurance book and yen-denominated earnings. Chevron underwrites the highest yield in the bundle with integrated oil cash flow, now supplemented by contracted cash flows independent of commodity price cycles.
Owning all three is how an income portfolio gets diversification inside the Aristocrat label rather than three flavors of the same defensive name (for readers who want to push the streak even further, we ranked ten companies with 50-plus years of consecutive raises by valuation in a free Dividend Kings report).
The post 3 of Wall Street’s Safest High-Yield Dividend Stocks With Over 25-Year Increase Streaks appeared first on 24/7 Wall St..
]]>CNBC’s Becky Quick reported on Wednesday, September 2, that Chevron (NYSE:CVX) is expanding its position in Venezuela through joint ventures, with the deal landing within days of the U.S.-Venezuela reserve arrangement that Washington disclosed last week.
According to Quick, “[Chevron is] saying that it is expanding its position in Venezuela with joint ventures. As part of the agreements, it will gain existing acreage where it’s established a position.” She added: “Its joint venture will invest more than $7 billion over the next five years, and it plans to double production to approximately 600,000 barrels a day.“
This investment plan targets production over a five-year horizon. Announced targets remain subject to execution risk, political developments, and the physical realities of restarting output in a country whose oil sector has been effectively closed to Western majors.
Chevron Is Moving Faster Than One Former Executive Expected
On August 28, former Chevron Africa and Latin America president Ali Moshiri argued that Venezuelan oil is a good solution for American energy security because it avoids the Strait of Hormuz, the Red Sea, and the Black Sea chokepoints. He advocated for public-private partnership because heavy and extra-heavy crude requires specialized technology the country lost after 15 years outside global markets.
Moshiri predicted the majors would move slowly on entry protocols while smaller and midsize firms moved faster. A more than $7 billion commitment from a supermajor within days of the reserve announcement cuts against that timeline.
On August 31, CNBC’s Brian Sullivan reported that Venezuelan national production has fallen from roughly 3.2 million barrels per day in 1997 to about 1.2 million today, said infrastructure is dilapidated, and cautioned that meaningful extraction is years away. Sullivan also flagged that majors would likely demand multi-year security guarantees before committing billions.
Chevron Is the First Major to Put Real Money Behind the Venezuela Deal

On August 28, President Trump announced a reported deal involving a 25-year lease of 65 billion barrels of proven reserves, with the U.S. controlling 55% and reportedly $100 billion-plus in U.S. energy company investment, with Chevron, Exxon and ConocoPhillips named as prospective participants. Sullivan noted the physical and legal structure was still unknown. Chevron’s announcement today is the first concrete corporate commitment towards that $100 billion number.
Venezuela is familiar territory for Chevron.
In the Q4 2025 earnings release, CEO Mike Wirth said Chevron had “been a part of Venezuela’s past for more than a century” and stood ready to help the country “build a better future while strengthening U.S. energy and regional security.”
Key Takeaways
Chevron’s $7 billion commitment gives Venezuela’s oil reopening its first major corporate backing. But doubling production will require much more than capital, with deteriorated infrastructure, security guarantees and execution risk standing between today’s announcement and 600,000 barrels per day.
The post Chevron Commits $7 Billion to Venezuela to Double Production to 600,000 Barrels a Day appeared first on 24/7 Wall St..
]]>BlackRock (NYSE:BLK) Investment Institute strategist Ben Powell discussed in a Bloomberg interview on September 2 that he sees a major shift underway in Gulf spending as more of the Middle East’s oil wealth is expected to continue to be invested domestically.
Powell’s argument is that the marginal dollar of Gulf Cooperation Council surplus will increasingly stay inside the region rather than being recycled into global equities, Treasuries and trophy real estate.
A $2.1 Trillion Signal: Why More Gulf Money Is Being Invested Domestically
Ben Powell told Bloomberg, “We’re gonna see upwards of $2 trillion US dollars of strategic capex here in the GCC over the next several years. And I think the change, the marginal change, is gonna be more of the money is gonna stay here in the GCC.”
Powell’s main point is that sovereign wealth funds, including PIF, Saudi Arabia’s sovereign wealth fund, have already been pivoting more domestically in recent years, and the current conflict has sharpened that trend. In Powell’s view, “It’s an accelerant to, obviously, the preexisting plans for diversification. Oil and gas is still very important. That’s not gonna change. It’s a significant generator of cash, and that’s great. But at the margin, the urgency of deploying that cash into societal and economic diversification, which was already there, I think the urgency is even greater.”
Basically, if the rest of the world beefs up its energy independence, that could hurt the Gulf’s exports over the long term and increase the importance of the Middle East investing in domestic industries outside of oil and gas.
AI, Energy and Defense Are Becoming One Investment Theme
Powell’s second idea is that energy and defense will need investment alongside data centers. Powell said, “Data centers need defense. They need energy. So clearly there are distinctions, but there is an overlap. And I think it’s hard in this very complicated world to neatly parse security from the economy, from AI. They all kind of overlap.”
AI infrastructure increasingly overlaps with energy and national security. Data centers need enormous amounts of power, while the Pentagon is spending more on AI, microelectronics and advanced energy technologies. The GAO estimates data centers could account for up to 12% of U.S. electricity demand by 2028, while the Pentagon’s FY 2027 science and technology budget request is nearly 26% higher than the prior request.
Global Chokepoints Are Accelerating the Push for Self-Reliance
Powell talked about how the Strait of Hormuz and other conflicts have highlighted the importance of domestic investment: “We can rely less, sadly, on these strategic chokepoints. We can rely less on global trading partners, so we’re gonna have to do more here at home in the region. The good news is we’ve got the funding. We’ve got the talent. We’ve got the energy to do that.”
The same morning, Treasury Secretary Scott Bessent told the G20 that the Strait of Hormuz will be “a worthless piece of water” in two years as oil moves to land pipelines, and Bloomberg’s Jon Herskovitz reported that Iran has signaled it may target energy infrastructure in neighboring countries.
Reuters this week has separately cataloged Gulf pipeline and port investment spurred by the Iran war. On August 28, former Chevron (NYSE:CVX) Latin America president Ali Moshiri argued for tying U.S. energy security to its Western Hemisphere energy supply, so the U.S. could avoid chokepoints like Hormuz, the Red Sea and the Black Sea.
Key Takeaways
Ben Powell closed by saying, “We’re gonna see more partnership between government driving societal goals and capital markets, because simply put, capital markets is where the money is. So we’re seeing a need for more funding, be that in old-fashioned infrastructure, schools, hospitals, and roads, or all the new fun stuff around AI.”
Powell’s thesis is that Gulf capital is becoming more domestic, strategic, and interconnected across AI, energy, and defense. If that shift continues, the $2.1 trillion buildout could reshape global capital flows as well.
The post BlackRock Says $2.1 Trillion Gulf Spending Boom Could Reshape Global Capital Flows appeared first on 24/7 Wall St..
]]>Treasury Secretary Scott Bessent, speaking at the G20 finance chiefs meeting, offered a two-year forecast in which he predicted the Strait of Hormuz would stop mattering to global oil. Meanwhile, Bloomberg’s Jon Herskovitz described how a fresh round of U.S.-Iran strikes is happening now.
Bessent Says Pipelines Will Make Hormuz “Worthless” in 2 Years
Bessent had an optimistic forecast for oil over the medium-term: “In two years, the Strait of Hormuz will be, like, a worthless piece of water, as the oil will be going on pipelines across land,” he said. He explained that the current disruption hurts other countries far more than it hurts the U.S.: “It’s not a choke point for the US, but it is a choke point for many, many other countries.”
Land pipeline capacity at the scale required to remove Hormuz from the global oil map demands construction, financing, host-country agreements, and physical security. Pipeline projects of that scale rarely are completely built on a two-year timeline, and the segment offered no detail on routes, capital sources, or throughput.
Recently, CNBC’s Brian Sullivan detailed why the announced Venezuela arrangement will likely not relieve near-term supply, citing production that has fallen from roughly 3.2 million barrels per day in 1997 to about 1.2 million with dilapidated infrastructure. Energy security proposals keep hitting the same timeline problem.
Hormuz Matters Far More to Asia Than the United States
The United States is a net exporter of crude and refined products, and its marginal barrels do not transit through Hormuz. For allied economies in Asia and parts of Europe, the Strait remains central for their oil imports. The Strait of Hormuz has more drastic consequences for oil importers, which is why global oil markets and allied economies absorb the risk even when U.S. domestic supply does not.
That framing echoes remarks from former Chevron (NYSE:CVX) Latin America president Ali Moshiri on August 28, who argued U.S. energy security depends on sources avoiding Hormuz, Red Sea, and Black Sea chokepoints, with Western Hemisphere supply from Brazil, Venezuela, and Argentina as the answer.
Iran Is Threatening Energy Infrastructure Beyond Hormuz
Against that two-year horizon, Herskovitz described events on a compressed timeline. “The US has escalated its round of strikes. The first strikes, which got it started, were at two launchers, artillery rocket launchers, which were suspected of being able to place mines in Hormuz. The latest attacks were broader,” he said.
“Iran has changed its strategy. It said that it’s looking to a longer-range battle where it can go after its neighbors in the region. If Iran sees its infrastructure attacked, it’s looking to go after infrastructure in the region of its neighbors, energy infrastructure, which could damage the economies of these regions and also really affect global oil supplies,” Herskovitz said. Attacks on neighboring energy infrastructure would move supply regardless of the Strait’s status.
Oil Is Back Near $90 as the Conflict Escalates
WTI opened at over $90 per barrel on September 2, down nearly 10% from a month earlier but well above the $55.44 low from December 16, 2025. U.S. regular gasoline sat at $4.07 per gallon on August 31, 2026. Overnight, CNBC reported Iran said two tankers hit Hormuz naval mines while it attacked regional targets in retaliation.
Key Takeaways
Bessent may ultimately be right that pipelines and alternative supply routes will reduce the world’s dependence on Hormuz. But with U.S.-Iran strikes escalating, regional energy assets under threat, and crude back around $90 per barrel, the oil market’s immediate problem remains the conflict happening today.
The post Strait of Hormuz Will Be a “Worthless Piece of Water” in Two Years. Why Oil Just Crossed $90/Barrel Anways appeared first on 24/7 Wall St..
]]>Jim Cramer opened Squawk on the Street on the first trading day of September with a market backdrop he described in blunt terms. Two ships had been fired on in the Strait of Hormuz, Treasury yields were pushing higher across the curve, and diesel prices were climbing amid a supply picture already strained by Ukrainian strikes on Russian refining capacity and U.S. refiners operating near full utilization. Cramer called the combination “unholy” and said the AI trade had gone nowhere for about a year. Then he offered a single actionable idea.
“Chevron over 200 is just it’s a steal here david,” he told David Faber, framing it around a distinction worth holding onto: “We are in a situation where the prism is negative, the noise is negative, the signal is positive.” That is the analytical spine of this piece. The question for an investor is whether Chevron (NYSE:CVX) deserves a bid because refining margins are widening on a disruption, or because the underlying business generates cash regardless of where crude settles next week.
What Actually Happened at Chevron Last Quarter
Chevron’s Q2 earnings report was the strongest the company has delivered in years. Adjusted EPS came in at $6.06 on revenue of $67.20 billion, with net income up 384.82% year over year and free cash flow of $18.095 billion. Worldwide production climbed 20% year over year to 4,070 MBOED.
Downstream is where the disruption thesis intersects the fundamentals. U.S. refinery utilization hit 97%, and downstream earnings jumped to $4.87 billion from $737 million a year earlier. Chevron booked $1.4 billion in favorable timing effects and cut total debt by $8.41 billion in the quarter alone.
The Hess integration is running ahead of plan. Management reached its $3 billion structural cost reduction target six months ahead of schedule and captured $1.5 billion in Hess-related synergies, roughly 50% above the initial target. CFO Eimear Bonner said the savings are durable because they are “built into the business.”
Mike Wirth’s read on refining aligns with what Faber flagged on air. He said “Products are tighter than crude around the world, and that’s why cracks have widened out,” and expected “upward pressure on product pricing here into the third quarter and perhaps beyond that.” Full detail sits in Chevron’s 8-K filing with the SEC.
The 20-year, 2.67-gigawatt power purchase agreement with Microsoft (NASDAQ:MSFT) for a West Texas data center reframes Chevron as more than a pure crude call, because contracted power cash flows are insulated from Brent curve swings.
Where the Disruption Case Gets Uncomfortable
Cramer’s positive signal rests partly on refined-product tightness that could reverse quickly. WTI has been swinging hard: from $114.58 on April 7 to $83.90 on August 25, down 8.5% in a month. Geopolitical crack spreads unwind the moment shipping lanes clear.
September seasonality is real but overrated as a standalone reason to avoid energy. Refinery turnaround season can tighten distillate further, and EIA data show refinery utilization near 0.92-0.95 in recent months, leaving little slack.
The stock has already moved. CVX is up 42.32% year-to-date and 8.15% over the past month, closing at $211.05. Buying above $200 means paying up for a quarter that has already been rewarded.
The dividend is what makes the wait tolerable. The next payment is $1.78 on September 10, with an annualized forward of $7.12. Chevron has raised the quarterly payout every year since 2024.
Cramer’s own hedge, that “the AI trade… has not been a good one for quite some time”, is why an integrated major with a Microsoft power contract is a rotation candidate rather than a defensive parking spot.
Is CVX Stock a Buy?
Chevron trades at a market cap of around $414 billion with a P/E near 34x, richer than Exxon Mobil (NYSE:XOM), which trades at a P/E of roughly 23x and a market cap of $676.62 billion. Exxon’s Guyana ramp and 43 consecutive years of dividend growth arguably make it the cleaner compounder.
ConocoPhillips (NYSE:COP) is the higher-beta upstream play, up 48.63% YTD, targeting a $7 billion free cash flow inflection by 2029. It offers more torque to crude and less downstream ballast.
Shell (NYSE:SHEL) missed Q2 EPS badly at $1.92 due to Qatar disruption, even as refinery utilization ran at 102%. Its LNG optionality is real; its earnings volatility is, too.
Chevron sits in the middle: less commodity-beta than Conoco, richer than Exxon, and more integrated than Shell right now. The Hess synergies, contracted Microsoft cash flows, and cost program give it a signal that outlasts any tanker headline. Cramer’s framing that the noise is negative and the signal positive holds up under scrutiny, but the entry price matters and CVX has already run hard.
The setup looks constructive, with the understanding that the near-term catalyst is disruption-driven and the long-term case rests on Hess, cost discipline, and power. Those seeking pure crude beta may find more torque in Conoco.
The post Cramer Called the September Open Unholy and Then Named the One Stock He Would Still Buy appeared first on 24/7 Wall St..
]]>Jim Cramer likes what he sees in Chevron (NYSE:CVX). The stock closed at $211.05 on September 1, a fresh 52-week high, and is up 42.32% year to date. On Tuesday morning, CEO Mike Wirth walked onto CNBC’s Squawk Box and gave shareholders a fresh reason to cheer: a headline Venezuela expansion. Cramer’s endorsement of the stock, however, sits next to a very specific question, one the same broadcast raised within minutes. Can Venezuela actually double its output on Chevron’s schedule?
What Chevron Just Told the Market
Chevron said its Venezuelan joint venture will invest more than $7 billion over the next five years, with plans to roughly double production to about 600,000 barrels a day. The joint venture will pick up existing acreage in the Cocoa Belt, where Chevron already has an operating footprint through Petroindependencia and Petropiar. Wirth framed the plan as additive rather than competitive with U.S. barrels, according to comments he made on CNBC.
On the July earnings call, Wirth had already told analysts Chevron is “actively working with the government to look at other opportunities” and that any additional spend has to “compete in our portfolio for capital.” Management also said existing Venezuelan JV output has grown from 40,000 to 250,000 barrels in recent years, and that Chevron expects its Venezuelan debt to be fully recovered by early 2027.
Why Analysts Are Flagging the Timeline
Kpler’s Amena Bakr has been public about her skepticism. In earlier commentary, she wrote that the barrels capable of moving U.S. pump prices are “5 to 15 years out.” Michelle Caruso-Cabrera of MCC Global has also flagged contract-sanctity risk on Venezuelan deals under the current political framework. Chevron’s five-year clock diverges from the independent view of a decade-plus ramp, and the gap matters for anyone paying a peak price today.
Financial Firepower Behind the Bet
The Q2 earnings report gives Chevron room to spend without stretching the balance sheet. Chevron reported adjusted EPS of $6.06 on revenue of $67.2 billion, up 51.43% year over year, per its 8-K filing. Free cash flow was $18.10 billion, and Chevron reduced debt by $8.41 billion in the quarter alone. Worldwide production hit 4,070 MBOED, up 20% year over year, with a record 2,077 MBOED from U.S. upstream and refineries running at 97% utilization.
Wirth summarized the quarter this way: “Our strong second quarter performance is a result of disciplined investment and strong execution that drove record U.S. upstream production, record crude throughput in our U.S. refineries, and exceptional reliability across key assets.” Chevron returned capital aggressively too, with $3.117 billion in Q2 buybacks and a $1.78 quarterly dividend.
Valuation Reality Check
CVX now trades at $211.73, with a trailing P/E near 34. Against a 2026 consensus EPS of $15.87, the forward multiple is roughly 13x. The 2027 EPS consensus, however, slips to $13.20, reflecting analyst caution about oil prices normalizing from spring highs. WTI ran to $105.67 on April 3 and has since settled at $87.35 as of August 21, still well above the $57.54 print on January 2 that anchored the year.
What CVX Shareholders Are Actually Paying For
Cramer is right that Chevron is flying. The Q2 execution, the balance-sheet strength, the Microsoft AI power deal, and the Iraq and Guyana pipelines all justify the run. The Venezuela leg is the one to watch. If Chevron hits 600,000 barrels a day within five years, shareholders paying a 52-week high are getting a compounding growth option on top of the base business. If Bakr’s decade timeline is closer to the truth, the market is already paying for barrels that arrive well after this cycle. The next catalysts to monitor are Q3 earnings on September 30, TCO affiliate distributions at higher Brent, and any confirmation of Venezuelan JV terms that would allow Chevron to book incremental reserves.
The post Chevron Is Really Flying, Jim Cramer Says, But Can Venezuela Double Output? appeared first on 24/7 Wall St..
]]>Chevron CEO Mike Wirth flew to Caracas and committed real capital, then told American drivers cheaper gas is not coming from this deal. That split screen is the story.
In a CNBC interview Tuesday, Wirth said Chevron (NYSE:CVX) will spend $7 billion across three joint ventures over five years to triple Venezuelan production from roughly 300,000 barrels per day to over 600,000 barrels per day by 2031, at a cost per barrel of less than $20. Wirth framed the economics as accretive to free cash flow, made viable by renegotiated fiscal terms, royalties, legal framework, and dispute resolution provisions.
What Wirth Told Drivers
Asked whether Venezuelan crude would bring down U.S. gasoline prices, Wirth called it “a long term add to supply globally” and said a new refinery would take “5 to 7 years” to build. He pointed to the Middle East and Russia-Ukraine as drivers of tight product markets, noting the only faster fix is routing more product to existing refineries.
The national average price of regular gas sat at $4.071 per gallon on August 31, 2026, above the $4.00 “painful for budgets” threshold. That is up from $2.779 on January 12, with a 2026 peak of $4.50 on May 11. On the Q2 call, Wirth said diesel is the tightest spot, warning of “upward pressure on product pricing here into the third quarter and perhaps beyond that.”
Pump Versus Portfolio
The same tightness squeezing drivers is a tailwind for the stock. CVX traded at $211.66 Wednesday morning, up 42.32% year to date and 5.58% in the past week. Q2 delivered adjusted EPS of $6.06, revenue of $67.20 billion, and downstream earnings of $4.87 billion versus $737 million a year ago. Debt fell by more than $8 billion in the quarter.
Long Game Wirth Is Playing
On the Q2 call, Wirth previewed the Venezuela pivot: “We are going to work it to create value, not for a year or two, not growth for a year or two, but value long, long, long into the future.” He noted debt recovery from Caracas would be “fully recovered” by early 2027.
U.S. production hit a record 2.1 million barrels per day last quarter, more than 50% of global output, and Kazakhstan and the Black Sea pipeline are running at full capacity. Shareholders got the answer. Drivers got a timeline measured in years.
The post $7 Billion for Venezuelan Oil, and Chevron’s CEO Just Told Drivers When Gas Gets Cheaper appeared first on 24/7 Wall St..
]]>A $5,700 monthly paycheck works out to $68,400 a year, roughly what a comfortable retirement runs for a debt-free 64-year-old in most of the country. The goal here is to hit that number using five individual dividend stocks, one per sector, all paying qualified dividends. No covered call ETFs, no BDCs, no monthly-pay closed-end funds.
The five-stock blueprint is straightforward: Verizon (NYSE:VZ) for telecom, Chevron (NYSE:CVX) for energy, AbbVie (NYSE:ABBV) for pharma, Philip Morris International (NYSE:PM) for tobacco and smoke-free, and Southern Company (NYSE:SO) for regulated utilities. Equal 20% weights across the five.
Where the Yields Actually Sit Today
At current prices, the forward yields shake out like this. The telecom name pays about 5.6% on a $2.83 annualized payout. The energy major yields roughly 3.4% on $7.12. The pharmaceutical company sits near 2.7% of $6.92. The tobacco giant comes in around 3.1% on $5.88. And the utility pays about 3.5% on $3.04. If you weight them equally, the basket lands at a blended yield near 3.7%. To generate $68,400 of income at that average, you need roughly $1.87 million in capital, split $374,000 across each of the five positions.
That is a meaningful sum, no question. But it is still less than what a Treasury-only strategy would require at the current 4.75% yield on the 10-year, once you factor in what these companies do that Treasuries do not. They raise the payout over time.
Three Ways to Size the Portfolio
The core math is $68,400 divided by yield. Three tiers illustrate the tradeoff:
- Conservative tier (3% to 4%): Run the math at 3.5%, and $68,400 a year requires $1,954,000 in capital. That is where the five-stock basket lands if you lean heavier into the energy major, the pharmaceutical company, and the utility. You are putting up the most money upfront, but the principal keeps compounding over time. The drug company’s quarterly payout has climbed from $1.07 in 2019 to $1.73 in 2026, and the oil giant has gone from $1.29 in 2020 to $1.78 in 2026. That is sleep-at-night income that actually grows.
- Moderate tier (5% to 7%): At a 5.5% yield, that same $68,400 annual target calls for $1,244,000. You get there by overweighting the telecom name and mixing in preferred shares, REITs, or high-dividend equity funds. The telecom company just marked its 20th consecutive year of dividend increases, though the latest raise was only 2.5%. Payout growth has flattened, and total return leans more on the coupon than on price appreciation.
- Aggressive tier (8% to 14%): $68,400 divided by 0.10 equals $684,000. Leveraged covered call funds, mortgage REITs, and high-yield bond funds live here. Distributions frequently get cut, and the principal often erodes. You are spending the asset, not living off its growth.
Why the Lower Yield Often Wins
A 3.7% yield that grows 6% to 8% annually doubles your income in roughly nine to twelve years. A 10% yield with a flat or shrinking payout stays put or slides. In this basket, Chevron has raised its dividend for more than two decades, Southern’s quarterly payout has ticked up from $0.56 in 2017 to $0.76 today, and Philip Morris has moved from $1.00 per quarter in 2015 to $1.47 in 2026.
That growth is why AbbVie is up 512% over 10 years, and Chevron is up 219%, with the yield reinvested along the way. The whole point of a ladder like this is never having to sell a share to pay a bill, and we walked through how to build one in a free guide here.
The catch: concentration. Five stocks in five sectors are diversified relative to owning one, but a Humira-style patent cliff, an oil-price collapse, or an FDA action on nicotine pouches can each hit 20% of the income stream at once. AbbVie’s $10.9 billion Apogee acquisition and 14-cent EPS dilution illustrate the reinvestment risk baked into the pharma slot.
Three Steps to Take This Week
- Price out your real number. Pull last year’s actual spending, not your pre-retirement salary. If you can live on $54,000, your capital target drops by roughly $400,000 at a 3.7% blended yield.
- Stress-test the growth assumption. Model each holding at half its recent five-year dividend growth rate. If the math still works, the plan is durable. If it does not, add a sixth or seventh position rather than reach for yield.
- Run the tax layer. All five names pay qualified dividends, taxed at 0%, 15%, or 20% federally depending on the bracket. In a state like California or New York, layer state tax on top before deciding how much of the portfolio belongs in a taxable account versus an IRA.
The post No ETFs Required: How a 64-Year-Old Built a $5,700 Monthly Paycheck From Five Dividend Stocks appeared first on 24/7 Wall St..
]]>President Trump took a historic victory lap Saturday, announcing 100-year concessions on 17 Venezuelan oil fields covering roughly 65 billion barrels of proven reserves.
Sixty-five. Billion. Barrels.
For perspective, the entire United States had about 46 billion barrels of proven reserves at the end of 2024. Washington now claims access to more petroleum in South America than exists beneath all 50 states combined.
So, cheap gas for everybody?
America’s Gulf Coast refiners would like a word.
Because while 65 billion barrels makes for one heck of a victory lap, the people responsible for turning crude oil into something you can actually pump into a Ford F-150 have a considerably less exciting story to tell.
For drivers and energy investors, the important number isn’t how much oil exists underground. It’s how much can be extracted, transported, refined, and eventually pumped into a vehicle.
Preferably sometime before your grandchildren retire.
And on that score, Venezuela’s 65-billion-barrel bonanza runs directly into industrial reality.
Under the reported framework, the fields go to a joint venture between Washington and North American Blue Energy Partners (NABEP), Venezuela’s second-largest private producer, run by Alejandro Betancourt Lopez. The Pentagon’s Office of Strategic Capital takes a 35% equity stake in NABEP’s corporate parent.
The U.S. receives a guaranteed 20% of production at cost and right of first refusal on the remaining 80%. NABEP plans up to $100 billion in new infrastructure and $200 billion in royalties and taxes over 25 years.
Those are gigantic numbers.
Unfortunately, none of them are gallons of gasoline.
Venezuela Has an Ocean of Oil. It Just Doesn’t Produce Much of It.
Here is the inconvenient thing about oil reserves:
Reserves are oil in the ground. Production is oil coming out of a pipe.
Venezuela is spectacular at the first one.
It is currently terrible at the second.
Despite sitting on the world’s largest petroleum reserves, Venezuela produces only about 1% of global oil output after two decades of state mismanagement, decaying infrastructure, and U.S. sanctions dating to 2005.
Signing a historic agreement does not cause 65 billion barrels of crude to obediently march toward the nearest tanker.
Somebody has to get it out.
And that’s going to take a while.
Rystad Energy estimates full production from existing fields may not arrive until the mid-2030s. The Council on Foreign Relations estimates repairing and modernizing Venezuela’s crippled infrastructure could cost $10 billion to $20 billion.
Developing new fields could take more than a decade and require at least $100 billion in fresh capital.
And after spending all that money and waiting all those years, you encounter another minor inconvenience:
Now you have to refine the stuff.
The Gulf Coast Refining Wall
Not all oil is created equal.
Venezuelan crude is extra-heavy and loaded with sulfur. You don’t simply pour it into any refinery and wait for gasoline to come out the other end.
It requires specialized, high-complexity coking refineries.
Fortunately, the U.S. Gulf Coast has some of the best facilities in the world for processing exactly this kind of crude.
Unfortunately, they’re already busy.
Valero Energy (NYSE), the premier processor of heavy crude, told analysts on July 30 that “we’ve been the largest U.S. consumer of Venezuelan crude over the last several years” and expects processing rates to exceed its historical maximum.
That’s not exactly an industry saying:
PLEASE SEND US 65 BILLION MORE BARRELS.
Valero management also flagged roughly 5 million barrels per day of global refining capacity offline and light-product inventories about 130 million barrels below normal seasonal levels.
So imagine Venezuela somehow manages to dramatically increase production tomorrow.
Wonderful.
Where does all that extra heavy crude go?
Finding 65 billion barrels of Venezuelan oil does not magically build more Gulf Coast distillation towers or coking units.
You can have all the oil in the world underground.
If you can’t process it fast enough, your gas tank remains unimpressed.
Your Gas Pump Does Not Care About Press Releases
The national average for regular gasoline stood at $4.08 per gallon as of August 24, up 2.1% from a month earlier.
WTI crude closed at $83.90 on August 25, well below its $114.58 April peak but still elevated amid the Iran conflict and disruption in the Strait of Hormuz.
Those are the things your gas pump cares about.
Benchmark crude prices.
Refinery capacity.
Product inventories.
Shipping routes.
Actual barrels of actual oil moving through actual infrastructure.
Oil that might emerge from Venezuela a decade from now doesn’t do much for someone filling up on Tuesday.
The market cannot pour a press release into a refinery.
And announcing another 65 billion barrels underground does not reopen a tanker route through the Strait of Hormuz.
So if you’re waiting for this deal to knock 50 cents off the gas station sign next week, you may want to bring a chair.
Possibly snacks.
Then There’s the Small Matter of Whether the Deal Survives
Let’s assume Venezuela rebuilds its infrastructure.
Let’s assume investors provide the capital.
Let’s assume production ramps.
Let’s assume Gulf Coast refiners find room for the crude.
We’re home free!
Well…
There’s still politics.
Energy lawyers have questioned the deal’s legality and called for contract transparency. Protests erupted in Caracas over the weekend. Chavismo factions have objected on sovereignty grounds, while independent U.S. producers are wary of competing against a Pentagon-backed joint venture.
Then there’s Venezuela’s rather memorable history with foreign oil companies.
Venezuela nationalized foreign oil assets in 2007, seizing billions in Western equipment.
And while this contract spans 100 years, American presidential terms famously do not.
A future administration taking office in 2029 could attempt to unwind the framework, and reports have noted that NABEP’s leadership has faced past regulatory scrutiny.
So the investment proposition looks something like this:
Spend tens of billions rebuilding Venezuela’s oil industry.
Wait perhaps a decade for major new production.
Navigate Venezuelan politics.
Navigate American politics.
Navigate legal challenges.
Find enough specialized refining capacity.
Then sell the oil.
Simple!
What This Actually Means for CVX, XOM, VLO, and XLE
For investors, the trick is separating companies that could eventually benefit from Venezuela from companies whose stocks have already moved for entirely different reasons.
Chevron (NYSE) is the essential corporate player to watch.
Chevron is the only U.S. major that remained in Venezuela through the 2007 nationalization. CEO Mike Wirth confirmed on July 31 that the company is “in negotiations right now to try to improve the fiscal terms and enable more investment in Venezuela,” with full debt recovery expected by early 2027.
Chevron shares are up 39.01% year to date.
Exxon Mobil (NYSE), up 36.41%, has no role in the Venezuelan deal and remains locked in a territorial border dispute with Caracas at the International Court of Justice.
Valero has surged a staggering 123.8%.
The Energy Select Sector SPDR Fund (NYSEARCA) is up 45%.
Those are enormous moves.
But don’t give Venezuela the credit.
The energy sector has repriced because of acute global shocks to crude supplies and refined-product bottlenecks.
Venezuela had nothing to do with it.
The Bottom Line
Sixty-five billion barrels makes for an unforgettable political victory lap.
It is also, for the moment, mostly a very impressive number on a piece of paper.
Gulf Coast refiners care about a much smaller and considerably less glamorous number:
How many barrels are actually leaving the Orinoco Belt and entering a U.S. refinery today?
Watch the export volumes.
Watch the infrastructure spending.
Watch the contracts and legal challenges.
And above all, watch how much Venezuelan crude Gulf Coast refineries actually process.
When those numbers start moving, this becomes a supply story.
Until then, Washington has acquired rights to an enormous ocean of oil that is continuing to perform the job Venezuelan crude has mastered over the past two decades:
Sitting quietly underground.
The post Gulf Coast Refineries Pour Cold Water on Trump’s 65-Billion-Barrel Venezuelan Victory Lap appeared first on 24/7 Wall St..
]]>Energy stocks led the market higher Monday morning as two major oil catalysts hit at once. CNBC’s Dominic Chu framed the setup on the network’s opening segment on Monday: “Oil prices did jump by about 3% on the resumption of those attacks, and that sent energy stocks higher.”
He added that “Chevron, Exxon Mobil, Halliburton, and Occidental Petroleum all in the green this morning after getting another boost on Friday, when President Trump said the U.S. had a deal with Venezuela to control more than 65 billion barrels of its oil reserves.” The Venezuela announcement won’t impact today’s supply, but it adds a long-horizon reserves story.
The U.S. and Iran traded strikes over the weekend, the first time in more than a month, which adds a supply-risk premium to energy prices.
Iran Strikes Send Oil Prices Up 3%
Chevron (NYSE:CVX) opened higher, trading at $208.18 Tuesday morning, up 1.00% on the session and 36.13% year-to-date. On the Q2 call, CEO Mike Wirth flagged the region directly, saying “the impact from the Middle East conflict remained isolated to the partition zone representing about 1% of second quarter total production.” Chevron still delivered $12.1 billion in earnings, or $6.11 per share, and cut debt by more than $8 billion in the quarter.
Exxon Mobil (NYSE:XOM) trades at $162.91 on Tuesday, up 1.20% intraday. Exxon’s Q1 report disclosed $706 million in losses tied to Middle East supply disruptions, and CEO Darren Woods said: “Events in the Middle East tested that strength with the safety of our people remaining our top priority.”
Halliburton (NYSE:HAL) added 1.53% to $36.74, extending a 16% one-month rally. Middle East and Asia revenue was down 2% sequentially in Q2 on activity disruptions in Kuwait, Iraq, and Qatar.
Occidental Petroleum (NYSE:OXY) rose 0.76% to $59.55. CEO Richard Jackson said on the Q2 call that Occidental “fully offset the disruptions of our production in the Middle East” through Permian and Gulf of America volumes.
Trump’s 65 Billion-Barrel Venezuela Deal Is a Very Different Catalyst
President Trump announced Friday that the U.S. had a deal with Venezuela to control more than 65 billion barrels of its oil reserves. Chevron is the most direct beneficiary given its three producing joint ventures with PDVSA.
Chevron CEO Mike Wirth told analysts Chevron has grown production from those three JVs “from 40,000 to 250,000” barrels per day and that “we’re in negotiations right now to try to improve the fiscal terms and enable more investment in Venezuela.” CFO Eimear Bonner said on debt recovery, “we expect that by early 2027, that will be fully recovered.”
The reserves headline is a long-horizon story: Venezuelan infrastructure has been degraded by years of sanctions and disinvestment, and heavy and extra-heavy crude requires specialized handling that takes time to rebuild. Retail investors have zeroed in on that gap. Reddit’s most-discussed Chevron thread over the weekend was titled “Trump announced a deal for 65 billion barrels of Venezuelan oil. How much of that is actually investable?” with sentiment scores clustering in a neutral 49 to 58 range.
Key Takeaways
Iran and Venezuela are giving energy investors two very different catalysts. Renewed Middle East fighting can move oil prices immediately, while Venezuela’s 65 billion barrels could take years to translate into meaningful production.
The post Chevron, Exxon and Other Oil Stocks Jump as Two Huge Energy Stories Collide appeared first on 24/7 Wall St..
]]>CNBC’s Brian Sullivan walked viewers through the announced U.S.-Venezuela oil arrangement Monday, delivering a simple message for investors: the headline reserve number is enormous, and the timeline to real production might not be as long as some would expect.
“Venezuela, 65 billion barrels proven reserves on the part of this deal. Venezuela obviously has more. The U.S. under this would control 55% of that,” Sullivan said, framing a reported 25-year lease structure valued at $100 billion-plus in investment by U.S. energy companies.
The announcement, covered Monday morning on CNBC, names three U.S. majors as prospective participants: Chevron (NYSE:CVX), Exxon Mobil (NYSE:XOM) and ConocoPhillips (NYSE:COP). Sullivan emphasized the physical and legal structure remains unsettled. “The report is that this is going to be 55% controlled by the United States, and private companies are going to be a part of that. We don’t know the exact physical structure, legal structure,” he said.
65 Billion Barrels in the Ground, but Only 1.2 Million Produced per Day
Venezuela holds more than 300 billion barrels in total proven reserves, and this agreement carves out just 65 billion. Yet the country’s ability to lift, transport, and sell that oil has eroded for decades.
“Venezuela has been in a rolling 30-year production collapse. Venezuela was one of the biggest oil producers in the world. It was the richest country in Latin America 30 years ago, not even close. 1997, they peaked out at about 3.2 million barrels per day on average of production. Right now, doing about 1.2,” Sullivan said. EIA’s most recent Short-Term Energy Outlook shows Venezuelan output in a similar range, with recent quarterly figures near 1.0 million barrels per day.
Sullivan had a blunt message on the feasibility of getting usage from the oil: “This oil is going to sit under the ground if there’s no capital and expertise to pull it out.“ On timing: “If this deal does happen, if this progresses, you’re talking years before we extract any significant volume of oil from Venezuela. Everything is dilapidated.”
The U.S. Could Control 55% Under a 25-Year Deal
Under the announced structure, U.S. entities would control 55% of the 65 billion-barrel carveout under a 25-year lease. Venezuela’s interim president, Delcy Rodriguez, said Venezuelans would receive around $200 billion in sales tax revenue.
Sullivan raised broader questions about who controls the Venezuelan counterparty and legal complications that could weigh on implementation. Any operator would demand multi-year security and legal guarantees before committing capital, and why such guarantees can be fragile across leadership changes.
Former Chevron Executive Warned About This Exact Problem
Sullivan’s reporting arrives three days after CNBC’s August 28 interview with Ali Moshiri, CEO of Amos Global Energy and former President of Chevron Africa and Latin America. Moshiri backed the strategic logic, arguing Venezuelan barrels bypass the Strait of Hormuz, Red Sea, and Black Sea choke points.
He advocated a public-private partnership because Venezuela’s heavy and extra-heavy crude requires specialized technology the country has lost after roughly 15 years outside global markets. He thinks: “the idea is great, the challenge is going to be implementation,” with majors likely to move slowly on entry protocols while smaller firms move faster.
What the Venezuela Deal Means for Chevron, Exxon and ConocoPhillips
The 65 billion-barrel headline makes the Venezuela deal look transformative, but with production still around 1.2 million barrels per day and infrastructure badly degraded, those reserves could take years and enormous amounts of capital to reach global markets. For Chevron, Exxon, and ConocoPhillips investors, the story now shifts to whether the deal can be implemented and when.
The post Energy Expert Warns Venezuela’s 65 Billion-Barrel Oil Deal Won’t Fix Supply Anytime Soon appeared first on 24/7 Wall St..
]]>
Oil markets have spent the past six months learning to live with an uncomfortable reality: The U.S.-Iran conflict can flare up quickly without necessarily becoming a full-scale war. That distinction matters because the Strait of Hormuz remains one of the world’s most important oil chokepoints, and even the threat of disruption can add a premium to crude prices.
This morning, that premium returned. Brent crude jumped 3.5% to $91.30 a barrel while West Texas Intermediate climbed 3.7% to $86.49 after the U.S. and Iran once again exchanged strikes.
Another Round Around The Strait
The latest escalation began when U.S. forces struck two Iranian missile launchers on Larak Island near the Strait of Hormuz. U.S. Central Command said the launchers were being prepared to fire rockets carrying sea mines into the waterway. Iran then retaliated with ballistic missiles and drones targeting two U.S. military installations in Jordan. Jordanian forces said eight missiles were intercepted.
The timing is important. Just last week, the White House said U.S. forces had cleared mines from the Strait and warned that any ship or boat attempting to lay new ones would be “immediately and systematically destroyed.” Iran, meanwhile, has warned it would “forcefully respond” to further attacks.
That leaves investors watching the same question they have faced repeatedly since the war began: Is this another tit-for-tat exchange, or the start of something larger?
The Conflict Still Has No Exit
Unfortunately, there is little evidence of a diplomatic off-ramp as there were no talks between Washington and Tehran aimed at ending the six-month conflict. The June agreement that established a 60-day framework for negotiations has expired.
Instead, Washington has shifted toward economic pressure. Last week, the U.S. Treasury launched “Operation Economic Outcast,” which Secretary Scott Bessent described as an economic campaign designed to sever Iran’s financial lifelines. Trump has called the effort an “Economic D-Day.”
The problem for oil investors is that economic pressure does not eliminate Iran’s ability to threaten the Strait. Traffic through the waterway had fallen to roughly five ships per day over the weekend, while the U.S. said it was continuing efforts to keep Gulf oil moving.
Big Oil Is Treating This Differently
Brent and WTI are back above $90 and $86, respectively, but both benchmarks fell more than 4% last week. That suggests markets are treating this morning’s strikes as another escalation — not yet a fundamental change in the war’s trajectory.
Big oil stocks are reflecting that cautious optimism. Exxon Mobil (NYSE:XOM) is rising about 2% in premarket trading, while Chevron (NYSE:CVX) is up 2.2%.Both BP (NYSE:BP) and Shell (NYSE:SHEL) were, respectively, 1.7% and 1.3% higher
Exxon generated $14.5 billion of second-quarter earnings, $23.6 billion of operating cash flow and $17.2 billion of free cash flow. Yet its 30.2% gain this year trails the 40.2% advance of the State Street Energy Select Sector SPDR Fund (NYSEARCA:XLE).
Chevron has an additional catalyst. Its second-quarter earnings reached $12.1 billion, while production increased 20% year-over-year. The company is also positioned to benefit from the emerging U.S.-Venezuela oil agreement because it remains the only major U.S. oil company with a significant Venezuelan presence.
Key Takeaway
In short, investors should respect the risk without assuming the new strikes automatically signal a wider war.
The market has seen this movie repeatedly over six months. Unless Iran successfully closes the Strait or attacks produce sustained damage to Gulf oil infrastructure, crude’s latest jump looks more like another geopolitical risk premium than the beginning of a new oil shock.
That said, the absence of negotiations raises the stakes. For energy investors, Chevron looks particularly interesting because it combines direct exposure to higher oil prices with a potential long-term Venezuelan growth opportunity. Exxon offers stronger cash generation but has lagged the broader energy sector.
The smart move is to watch the physical oil flows through Hormuz, not just the headlines. If ships keep moving, today’s oil spike may prove temporary. If they stop, $90 crude could look cheap surprisingly quickly.
The post Oil Prices Jump Above $90 As U.S. and Iran Trade Strikes. Is $100 Next? appeared first on 24/7 Wall St..
]]>Shares of Chevron (NYSE:CVX) and Exxon Mobil (NYSE:XOM) are climbing in Monday morning trading after the United States and Iran resumed military strikes over the weekend, with shipping through the Strait of Hormuz still constrained. Chevron stock is up 3% to $207.80; Exxon Mobil stock is rising 3% to $161.31.
The energy complex is repricing supply risk in real time. WTI crude oil is at $86.06 per barrel, up 3% over the past 24 hours, while Brent has topped $90. Crude trades nearly around the clock, so that 24-hour figure captures weekend headlines across venues open beyond U.S. equity hours.
Energy is the standout group this morning. The Energy Select Sector SPDR ETF (NYSEARCA:XLE) is up 2% to $64.18. Broad benchmarks are moving the other way, with the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) down 0.4% to $766.13, while Exxon Mobil and Chevron together sit at the top of the XLE weighting, so the fund is tracking crude prices almost tick for tick today.
Hormuz Risk Repricing Fuels the Bid
The driver here is geopolitical. Both Chevron and Exxon Mobil have stayed quiet on the newswires today, leaving the weekend escalation between Washington and Tehran as the sole catalyst. Traders are pricing supply optionality across the crude curve as headline sentiment shifts.
Hormuz matters for the pair because a large share of seaborne crude and LNG passes through the strait. A supply-risk premium builds quickly when tanker transit is uncertain, and it fades just as quickly once flows resume. That two-way sensitivity marks today’s move as a repricing of headline risk, with limited implications for the majors’ long-term earnings power.
WTI crude oil’s recent path adds context to today’s bid in Chevron and Exxon Mobil. The daily FRED spot series had crude near $83.90 on August 25, after touching $89.75 on August 20, so today’s bounce retraces part of last week’s slide before the weekend headlines hit. That level sits above the $60 to $80 range the EIA classifies as moderate, and beneath the year’s high of $114.58 on April 7.
Commentary from both CEOs foreshadowed this backdrop. Chevron CEO Mike Wirth cited “geopolitical uncertainty and market volatility” on the company’s most recent call. Exxon Mobil CEO Darren Woods struck a similar note, saying “Events in the Middle East tested that strength… those events also underscored the importance of reliable, affordable energy products.”
One Move, Two Different Businesses
Chevron and Exxon Mobil are both up roughly 3%, and that’s an observation worth flagging. The market is treating the pair as a single crude-beta position, glossing over how differently their segments respond to a crude spike.
Both are integrated majors, each spanning upstream production, where a higher crude price lifts realizations on every barrel produced, and downstream refining and chemicals, where crude functions as an input cost. A jump in oil therefore lands unevenly across an integrated major’s segments. Pure exploration and production companies feel that lift more uniformly across revenue and margin lines.
Scale reinforces the herd trade in Chevron and Exxon Mobil. Chevron’s Hess integration has broadened its reserve base, while Exxon Mobil’s Guyana ramp and Permian footprint anchor its upstream mix. Both names also carry sizable refining capacity, which cushions the earnings mix when crude runs and can absorb some of the upside if the risk premium sticks.
Both stocks have run hard heading into today, with Chevron stock up 36% year to date (YTD) through Friday’s close. Exxon Mobil stock was up 33% year to date through that same tag. That momentum leaves less valuation cushion in Chevron and Exxon Mobil if the geopolitical premium unwinds and crude retraces toward the summer trend.
What to Watch
The next share-price move in Chevron and Exxon Mobil depends on Hormuz traffic and OPEC’s posture. Investors can watch for whether tanker transit normalizes and for whether the cartel signals any production response as WTI crude oil holds above $85. Peer strength across the energy patch, including refiners and services names inside the XLE ETF, will provide a read on how broadly the risk premium is being priced across the value chain.
Position sizing deserves emphasis for investors of Chevron and Exxon Mobil today. A geopolitical risk premium is among the most reversible moves in energy, and it can unwind as quickly as it appeared if the conflict de-escalates or Hormuz transit normalizes. Traders sizing their exposure here can stage entries and avoid chasing the current level, since headline risk cuts in both directions and today’s bid in these two names could reverse on a single wire story.
The post Chevron and Exxon Mobil Rise 3% as U.S. Strikes on Iran Push WTI Crude Oil to $86 appeared first on 24/7 Wall St..
]]>Ali Moshiri, CEO of Amos Global Energy and former President of Chevron Africa and Latin America, recently appeared on CNBC to weigh in on what an ownership stake in Venezuelan oil fields could mean for the U.S. He believes that one of the biggest advantages of the deal will be that Venezuelan oil can reach U.S. refiners without passing through shipping corridors such as the Strait of Hormuz.
“I think it comes down to energy security for the United States. If you consider that Venezuela has the largest resource and it doesn’t have the choke point that we have seen in the Strait of Hormuz, Red Sea, and Black Sea,” he said. Venezuela holds the world’s largest proven oil reserves, and unlike Gulf barrels, they reach U.S. refiners without transiting maritime corridors that can be impacted by conflict in the Middle East.
“The Ideas Is Great.” Producing the Oil Is the Hard Part
The challenge with Venezuelan oil is the operational complexity: “The idea is great. The challenge is going to be implementation, human capacity, operational experience, and so forth, and how all of this is going to come together,” Moshiri said.
Venezuelan crude is heavy and extra-heavy, requiring specialized technology and experience. Heavy oil is less valuable and much harder to transport than lighter oil, because lighter oil can easily flow through a pipeline while heavy oil might have a viscosity closer to peanut butter. It would be very difficult to send peanut butter through a pipeline, which is what makes heavy oil more costly and difficult to transport. Heavy oil requires diluents, upgraders, coking capacity, and refineries configured for high-sulfur, high-viscosity feedstock. Reservoirs need steam or solvent techniques to move barrels to the surface.
Layered on top, Venezuela has been absent from global energy markets for the past 15 years. In Moshiri’s view, that gap erodes local operational capacity and skilled labor in ways money alone can’t quickly rebuild. “Venezuela’s oil is very complicated. It’s a heavy and extra heavy. It requires technology. It requires experience that you’ve got to come together to make that a reality. I think that’s the reason it’s very essential to be a private and public partnership,” he said.
Why Small Operators Could Move Before Big Oil
Moshiri guessed which companies might benefit from this early: “The majors, they’ve got a different protocol to entering in the country, usually takes longer than normal time frame. The smaller company, midsize company, they react much faster in the short term,” he said. Large integrated producers might move cautiously due to compliance protocols and memories of prior capital losses in Venezuela. Independents and midsize operators can commit crews and capital more quickly.
For context, Chevron (NYSE:CVX) carries a market capitalization near $393 billion, with trailing revenue of roughly $209 billion and a forward P/E of 13. Chevron’s long footprint in Venezuela was central to its Latin America business during Moshiri’s tenure and lends weight to his operating perspective.
The Western Hempisphere Is An Energy Security Play
Moshiri believes energy supply disruptions will likely happen again in the future, but Venezuela will help the U.S. achieve energy security: “I think from the energy security point of view, this is not going to be the last time this is going to happen. And we got to be ready for it. And I think we’ve got to look at the alternative for energy security. And an alternative for us is our own hemisphere. You look at Brazil, you look at Venezuela, you look at Argentina,” he said. OPEC’s current production is around 22-25 million barrels per day out of a 32 million barrel capacity, and Venezuela also holds significant critical mineral reserves alongside oil, which could help the U.S. build supply-chain sovereignty.
WTI closed at $83.40 per barrel on August 28, 2026, down 8.5% from a month earlier and off a 52-week high of $114.58 reached on April 7, 2026. At the pump, the U.S. regular gasoline average was $4.08 per gallon on August 30, 2026, above the $4.00 threshold the EIA describes as painful for household budgets.
Key Takeaways
The announced agreement puts Venezuela’s oil potential back in focus, but Moshiri’s argument turns on execution. Heavy crude, infrastructure needs, and shortages of experienced workers make production difficult to scale. Smaller operators may move first, while investors should judge progress by investment and actual output.
The post Former Chevron Executive: Venezuela’s Oil Opportunity Comes With a Major Catch appeared first on 24/7 Wall St..
]]>
Oil markets have spent 2026 wrestling with supply disruptions, Strategic Petroleum Reserve drawdowns to multi-decade lows, and stubborn pump prices that refuse to cooperate with political calendars.
That makes President Trump’s new energy agreement with Venezuela genuinely good news for long-term American energy security. It hands U.S. interests majority control of more than 65 billion barrels of proven Venezuelan reserves — roughly one-fifth of the OPEC nation’s world-leading 303 billion-barrel total — while unlocking private investment aimed at rebuilding a battered industry.
The U.S. currently holds about 46 billion barrels of proven crude oil and lease condensate reserves. Add the 65 billion barrels covered by the agreement, and the combined figure reaches roughly 111 billion barrels. That represents about 7.1% of the world’s 1.57 trillion barrels of proven crude reserves reported by OPEC at the end of 2025 (Venezuela is considering leaving OPEC). The total sits almost exactly in line with the United Arab Emirates’ 113 billion barrels and exceeds Kuwait’s 101.5 billion.
In short, the arrangement expands U.S. access to a meaningful slice of global supply without adding a single new domestic well.
What the Deal Actually Delivers
The agreement, negotiated with Venezuela’s interim leadership, grants American companies long-term access to 17 strategic fields spanning the Orinoco Belt and Lake Maracaibo. Venezuelan officials project more than $100 billion in private investment and $209 billion in eventual tax revenue. Production rights are expected to flow primarily to U.S. operators, with resulting crude directed toward American markets.
Chevron (NYSE:CVX) already operates the largest U.S. footprint in the country and accounts for a substantial share of current Venezuelan output near 1.25 million barrels per day. The company is finalizing contract migrations under the new hydrocarbons framework and is positioned to expand into additional heavy-oil blocks. Service providers such as SLB (NYSE:SLB) have also secured early contracts for technology and equipment. These moves convert political headlines into tangible capital spending and potential production growth over the next several years.
Why Gas Prices Won’t Fall Overnight
Venezuela’s oil is predominantly extra-heavy crude that requires diluents, specialized refining, and major infrastructure repairs after years of underinvestment. Current output sits at roughly 1.2 million to 1.25 million barrels per day — its highest level since 2019 — yet remains a fraction of the country’s historic peaks above 3 million barrels. Even with rapid investment, meaningful incremental supply will take time to reach global markets.
U.S. Gulf Coast refiners like Marathon Petroleum (NYSE:MPC) and Valero Energy (NYSE: VLO) already process a large share of Venezuelan crude and stand to benefit from more reliable volumes. That improves energy security and supports refining margins. It does not, however, create an immediate flood of light sweet crude that would pressure gasoline prices lower in the next few months. Global balances still reflect other disruptions, and the deal’s full production impact will unfold over years rather than quarters.
The Investing Angle for Smart Shareholders
For investors, the clearest near-term opportunity sits with companies that already have skin in the game and balance sheets strong enough to fund expansion. Chevron’s existing joint ventures and operational knowledge give it a first-mover edge. Its diversified global portfolio and consistent free-cash-flow generation provide a buffer while Venezuelan projects ramp. Service companies with early contracts stand to book incremental revenue as drilling and facility work accelerates.
Granted, political and legal risks remain. Infrastructure bottlenecks and the heavy nature of the crude could temper the pace of growth. That said, the combination of U.S. policy support, sanctions relief through updated Office of Foreign Assets Control licenses, and private capital creates a clearer path than the sector has seen in more than a decade.
Investors focused on energy security and multi-year production growth now have a concrete set of assets to watch.
Key Takeaway
The Venezuela agreement strengthens America’s long-term oil position and opens a multi-billion-dollar investment runway for U.S. energy companies. It does not deliver an overnight drop at the pump. Smart investors should treat the news as a structural positive for firms already active in the country — particularly Chevron — while recognizing that the real production and cash-flow benefits will arrive gradually.
The post Trump’s New Oil Deal With Venezuela Is Insane — U.S. Now Controls 7.1% of Proven Global Reserves appeared first on 24/7 Wall St..
]]>Chevron (NYSE:CVX) and PepsiCo (NASDAQ:PEP) both reported Q2 2026 results and raised dividends this year. Chevron carries a 39-year streak. PepsiCo, at 54 consecutive annual increases, is classified as a Dividend King. The pressures on each payout differ sharply for income-focused owners.
Gushing Cash at Chevron, Grinding Margins at PepsiCo
Chevron’s Q2 2026, reported July 31, 2026, delivered adjusted EPS of $6.06, revenue of $67.2 billion, and quarterly operating cash flow of $22.63 billion. Free cash flow reached $15.4 billion. CEO Mike Wirth noted the Hess assets are generating cash that has been “roughly double the incremental dividends and accretive to shareholders on a per share basis.” Debt fell by more than $8 billion in the quarter, showing the cycle working as intended.
PepsiCo’s Q2 2026, reported July 9, 2026, showed core EPS of $2.20 on revenue of $24.18 billion, with core operating margin contracting 40 basis points. CEO Ramon Laguarta described the North American consumer environment as “worse than what we had anticipated and driven mainly by gas prices.” CFO Steve Schmitt said full-year EPS “may be towards the low end” of guidance. International is outperforming while Frito-Lay volumes soften.

Cyclical Cushion Versus Structural Squeeze
| Dividend Durability Lens | Chevron (FY2025) | PepsiCo (FY2025) |
| Operating cash flow | $33.9B | $12.1B |
| Capital expenditures | $17.3B | $4.4B |
| Dividends paid | $12.8B | $7.6B |
| Net income | $12.3B | $8.2B |
| Yield | 3.5% | 4.1% |
Chevron’s fiscal 2025 dividend outlay exceeded reported net income; buybacks added another $12.1 billion in shareholder returns. That coverage gap reflects the cycle. Q2 2026 confirmed recovery, with net debt to CFFO at 0.6 times and debt/equity at 0.2.
PepsiCo’s problem is structural. The gap between operating cash flow and capex plus dividends is thin, net income has flattened, and shares are down 5.4% over one year and 9.8% lower over five years. Debt/equity is 2.4. The 4% yield partly rewards patience and partly signals a repricing for lower growth. (For investors who want streaks measured in half-centuries rather than years, we ranked 10 Dividend Kings by valuation in a free report here).
Triggers That Would Change the Verdict
For Chevron, watch Brent. The EIA’s May 2026 outlook pegged Brent averaging $79.39 in 2026. A sustained slide below $60 paired with continued buybacks would compress cushion fast. For PepsiCo, watch whether North American Foods volumes turn and operating cash flow reclaims its 2023 level of $13.44 billion.
Why PepsiCo’s Payout Looks Tighter Today
Chevron’s dividend looks safer than FY2025 headlines suggest. Q2 2026 free cash flow of $15.4 billion and rapid deleveraging restore clear headroom. The risk here is variance in cash flow through the cycle. PepsiCo’s payout is structurally tighter: coverage is intact, but the cushion is narrow, earnings have flattened, and the yield climbs as the share price stalls. The view on PepsiCo would change if two consecutive years show operating cash flow comfortably above capex plus dividends with Frito-Lay volumes reaccelerating. The view on Chevron changes if Brent parks below $60 while buybacks continue. Both dividends remain funded. The nature of the stresses each company faces, however, is distinct.

The post Chevron or PepsiCo: Whose Dividend Is Standing on Thinner Ice? appeared first on 24/7 Wall St..
]]>
Oil markets are being reshaped by geopolitics as much as geology. Venezuela, home to the world’s largest proven crude reserves, is now moving closer to the U.S. after years of isolation, while OPEC’s influence over global supply appears to be weakening.
Venezuela produced only about 1.16 million barrels of oil a day in July, according to Bloomberg, less than half its output a decade ago. That means a Venezuelan exit from OPEC would have little immediate effect on crude prices. The bigger implication is what comes next: another crack in OPEC’s foundation and a potentially massive reopening of Venezuela’s oil industry to U.S. companies. And that puts Chevron (NYSE:CVX) in a particularly attractive position.
OPEC Could Lose Another Piece
Bloomberg reported Thursday that Venezuela is closely examining plans to leave OPEC, although no final decision has been made. The development would follow the United Arab Emirates’ decision to leave the cartel, giving OPEC another high-profile departure in only months.
To be clear, there would likely be little immediate impact to OPEC. Venezuela already isn’t subject to production limits because its output has fallen so far. So an exit wouldn’t suddenly unleash millions of additional barrels.
The longer-term risk for OPEC is credibility. Venezuela’s departure could encourage other members to prioritize production and market share over coordinated supply restrictions. Bloomberg notes that a broader breakdown could recreate the 2020-style battle for market share. For investors, that could mean more downward pressure on crude prices over time — a mixed outcome for oil producers but potentially beneficial for refiners and consumers.
Chevron Already Has a Head Start
The more compelling opportunity is Venezuela itself. Since U.S. forces removed Nicolas Maduro from power on Jan. 3, Washington has assumed far greater influence over Venezuela’s oil industry. Reuters reports that the U.S. is negotiating long-term access to a group of Venezuelan fields that American companies could develop, with 17 fields under consideration across the Orinoco Belt and Lake Maracaibo. One structure being discussed would involve leases followed by auctions or tenders for individual fields.
Chevron isn’t waiting for the starting gun. In April, the oil and gas giant increased its working interest in the Petroindependencia joint venture to 49% by acquiring an additional 13.21% stake. It also received rights to develop the adjacent Ayacucho 8 area in the Orinoco Oil Belt through its 30%-owned Petropiar JV.
That positioning is important because Venezuela’s oil is predominantly heavy and extra-heavy crude, requiring specialized infrastructure and expertise. Chevron already has both.
The company’s financial strength gives it another advantage. Chevron generated $12 billion in adjusted earnings and $15.4 billion in adjusted free cash flow during the second quarter, while production reached a record 4.07 million barrels of oil equivalent per day. Venezuela therefore represents an opportunity to add potentially valuable long-life production without betting the company on a turnaround that hasn’t happened yet.
More Than One Winner
Chevron may have the clearest head start, but it won’t have Venezuela to itself. Exxon Mobil (NYSE:XOM) and ConocoPhillips (NYSE:COP) could compete for field-development opportunities if Washington opens the door wider. ConocoPhillips generated $7.4 billion in second-quarter operating cash flow and returned $3 billion to shareholders, giving it substantial financial firepower for new projects.
Oilfield-service companies could be even more direct beneficiaries. SLB (NYSE:SLB) already signed a long-term framework agreement with Venezuela’s PDVSA covering exploration, field development, production, digital technology, and workforce development. Halliburton (NYSE:HAL) could benefit as drilling and completion activity expands.
And then there’s Valero Energy (NYSE:VLO). Venezuela’s heavy crude fits its complex Gulf Coast refineries particularly well. During its second-quarter earnings call, Valero said Venezuelan supply was increasing and expected its processing of Venezuelan heavy crude to exceed historical maximums in coming months. Similarly, Marathon Petroleum (NYSE:MPC) is one of the world’s largest heavy crude processors and its facilities are situated on the Gulf of America.
Key Takeaway
In short, Venezuela leaving OPEC isn’t the investment catalyst by itself. The bigger prize is the potential dismantling of barriers that have kept much of the country’s enormous oil resource underdeveloped.
Chevron is best positioned to capture that opportunity today because it already operates in Venezuela, just expanded its Orinoco footprint, and has the balance sheet to invest. Granted, legal challenges, political uncertainty and the possibility of lower oil prices remain real risks. Reuters notes that proposed leases could face constitutional and legal challenges under Venezuela’s existing framework.
But if Washington and Caracas turn today’s negotiations into a durable investment framework, Chevron could be one of the first — and potentially biggest — corporate winners.
The post Chevron Could Be Big Winner If Venezuela Pulls Out of OPEC appeared first on 24/7 Wall St..
]]>Wall Street has spent the last several years discounting a handful of famous dividend names on fears of patent cliffs, volume declines, and commodity swings. But the checks keep clearing. Pfizer (NYSE:PFE) still trades 20.8% below where it was five years ago, even as management just reaffirmed its payout in front of a looming loss-of-exclusivity window. Two other names, one industrial and one energy major, are in the same conversation. Here is where the yields sit, and whether the coverage supports them.
Pfizer: A 6% Yield With Management Drawing a Line in the Sand
Pfizer currently yields 6.15% on an annualized forward dividend of $1.72 per share, paid as a $0.43 quarterly distribution. The dividend was $0.42 in 2024 and has stepped up every year in the recent record, from $0.36 in 2019 to today.
Pfizer reaffirmed adjusted diluted EPS guidance of $2.80 to $3.00 for 2026, comfortably above the $1.72 annual payout. Second-quarter operating cash flow was $3.45 billion, and the company returned $4.9 billion to shareholders via the dividend in the first half. CEO Albert Bourla said flatly, “We feel extremely confident that, even in the most stretched scenarios we are running, we will be able to maintain our dividend.” Leverage ended the quarter at 2.7 times, and management now expects $6.7 billion in net cost savings through 2029.
In terms of the bull case, Pfizer’s launched and acquired products grew 18% operationally, and the pharma giant sees a path to high single-digit revenue growth after the LOE period ends in 2028. However, the implied risk is the same LOE cliff. Pfizer’s own guidance absorbs a meaningful headwind, and any acceleration of generic entry would pressure the coverage cushion.
UPS: Yield Above 6% After a Multiyear Reset
UPS (NYSE:UPS) yields 6.39% on an annualized forward dividend of $6.56 per share, or $1.64 quarterly. That payout has held steady across the seven most recent quarters, after a large step-up from $1.02 in 2021 to $1.52 in 2022. The stock is still 30.79% below its price five years ago.
Management guided full-year adjusted EPS of approximately $7.22, against a planned dividend payout of around $5.4 billion. Expected 2026 free cash flow is approximately $5.5 billion, essentially matching the dividend. Cash on the balance sheet stood at $4.7 billion with no commercial paper outstanding. CEO Carol Tomé framed the turnaround directly: “Incremental volume today carries materially better economics than before because of the structural changes we’ve made.”
The bull case is the completed Amazon glide-down, roughly $3 billion of savings landing in 2026, and U.S. domestic operating margin already back to 9.2%. The risk remains that free cash flow barely covers the dividend, and U.S. average daily volume still fell 3.3% year-over-year. Any macro air pocket makes that math a little uncomfortable.
Chevron: Lower Yield, but the Coverage Is a Fortress
Chevron (NYSE:CVX) rounds out the group as a high-yield income name rather than an ultra-high-yield one. The stock yields 3.44% on a $1.78 quarterly payout, with an annualized forward dividend of $7.12 per share. The per-share amount has stepped up every year in the record shown, from $1.29 in 2020 to $1.78 in 2026. Skepticism here is less about the payout and more about long-term oil demand.
Recent Q2 adjusted earnings came in at $6.06 per share, adjusted free cash flow was $15.4 billion, and Chevron cut debt by more than $8 billion in the quarter. Net debt to cash flow from operations sits at 0.6 times. Management hit $3 billion of structural cost reductions six months ahead of schedule and reaffirmed a long-term target of adjusted free cash flow growth averaging greater than 10% per year through 2030.
The record U.S. upstream production of nearly 2.1 million barrels of oil equivalent per day makes a solid bull case for the stock, along with Hess assets producing free cash flow roughly double the incremental dividends, and forward P/E holding at 13. However, earnings are still tethered to Brent, and CEO Mike Wirth’s $6 billion affiliate distribution guidance is set at $70 Brent.
What Ties These Three Payouts Together
These three names share a pattern the market keeps missing: durable cash flow, explicit CEO commitments to the payout, and multiyear cost programs that widen the coverage cushion each quarter. A 6%+ yield usually means the market suspects a cut is coming, and sometimes it is right (we walked through the seven warning signs that separate a real trap from a discounted payer in a free report here). Pfizer and UPS clear those tests while their businesses reset. Chevron pays less but backs it with the strongest balance sheet of the three. For income investors, the group offers a rare combination of skepticism-driven pricing and management teams putting the dividend first.
The post Wall Street Is Sleeping on These 3 Ultra-High-Yield Dividend Stocks appeared first on 24/7 Wall St..
]]>Building a monthly income stream from quarterly dividend payers requires just a little scheduling. Three blue chips, staggered on different quarterly calendars, can deliver a paycheck in every month of the year. Altria (NYSE:MO) pays in January, April, July, and October. AbbVie (NYSE:ABBV) pays in February, May, August, and November. Chevron (NYSE:CVX) pays in March, June, September, and December. Together, these three tickers cover all 12 months while offering attractive dividends along the way.
Here is what each leg of the ladder actually pays, how it has grown, and where the risks sit.
Altria: January, April, July, October
Altria just paid investors $1.06 per share on July 10, 2026, holding the level from the two prior quarters. The tobacco maker trades at $68.08 and carries a dividend yield of 6.19%, the highest of the three. Trailing 12-month payouts total $4.24, with the annualized forward at the same level.
The growth track record is proven. Altria has stepped the payout higher every year in this dataset, from $0.86 in 2020 to the current $1.06. Fundamentals are cooperating: management guided 2026 adjusted EPS to $5.56 to $5.72, and the Q1 earnings report of $1.32 beat the $1.25 estimate on revenue of $5.43 billion. Shares are up 23.72% year to date.
The risk to watch is regulatory and legal. Several third-party securities investigation notices have circulated in recent weeks, including a August 24, 2026 notice from Schall, Brown & Schwartz. These are not company announcements, and they do not change the dividend. They do reinforce why Altria trades at a forward multiple of just 12x.
AbbVie: February, May, August, November
AbbVie just paid investors $1.73 per share on August 14, 2026, the third payment at that level after a step up from $1.64. The trailing 12-month total sits at $6.83, with the annualized forward at $6.92. At the recent $259.76 quote, the yield is 2.58%.
The cash-flow story is the point. On the Q2 call, CFO Scott Reents told analysts AbbVie has “strong cash flows, balance sheet, and business outlook” and “substantial financial flexibility to pursue additional innovative business development.” Skyrizi hit $5.5 billion in the quarter, up 24% operationally, and Rinvoq cleared $2.5 billion, up 23.7%. Management lifted full-year adjusted EPS guidance to $13.87 to $14.07.
Here’s the catch: the reported profitability was depressed by acquisition accounting, which pushes the trailing PE to 75x even though forward PE is 19x. Investors that are seriously relying on the payout should track leverage after the Apogee deal closes. Management committed to a net leverage ratio of two times within two to three years following the deal close. Shares have run 30.1% over the past year.
Chevron: March, June, September, December
Chevron declared its latest $1.78 quarterly payout on July 29, 2026, with a record date of August 19, 2026 and payment on September 10, 2026. That marks a step up from $1.71 in 2025 and $1.63 in 2024. Trailing 12-month payouts total $7.05, with the annualized forward at $7.12. Yield sits at 3.44%.
The Q2 report gave dividend investors what they wanted: adjusted earnings of $12 billion, or $6.06 per share, adjusted free cash flow of $15.4 billion, and debt reduction of more than $8 billion in the quarter. Net debt to cash flow from operations closed at 0.6 times. CEO Mike Wirth told the call, “Consistent with our longstanding financial priorities, we intend to reward our shareholders today tomorrow and long into the future.” The Hess assets are generating strong free cash flow, which has been roughly double the incremental dividends and accretive to shareholders on a per share basis.
Chevron shares are up 35.01% year to date and 32.22% over the past year. Forward PE is 13x.
Putting the Ladder Together
Equal-weighted, these three names blend to a yield around 4%, with concentrated exposures worth noting: tobacco regulation for Altria, biosimilar and pipeline execution for AbbVie, and commodity prices for Chevron. That mix is the reason the ladder works. When crude cracks widen, Chevron benefits. When defensive consumer names catch a bid, Altria carries the load. AbbVie sits in the middle as a healthcare hedge with a growing payout. If a three-stock stagger still feels too rough, there is another route: funds and stocks that cut a check every 30 days on their own, seven of which we lined up in a free report here: The 7 Monthly Dividend Stocks That Pay You Every 30 Days. The next event on the calendar: Chevron pays on September 10, 2026. Keep an eye on the stock and the ex-date if you want to be included in the next round.
The post 3 Rock Solid Dividend That Pay You Every Month appeared first on 24/7 Wall St..
]]>The recent personal consumption expenditures (PCE) report confirmed what most of Wall Street already suspected. The core PCE was flat month-over-month, but the headline annual inflation rate edged higher to 3.7% from 3.6%. That may not be enough to tip the scales and force the Federal Reserve to raise rates in September, but if the August jobs report and the consumer and producer price index readings due early next month come in hot, that could be the final straw. One thing is for sure: in a world of economic reports and mind-numbing data, all you have to do is visit the grocery store and check the price of meat, where two T-bone steaks now cost $40.
With the prospect of continued “sticky inflation,” at the very least for the foreseeable future, we researched which sectors fare best during persistent inflation. Energy, consumer staples, real estate, and healthcare tend to perform well during periods of inflation. Five Dividend Aristocrats are exceptionally well-equipped to withstand persistent inflation. With decades of uninterrupted dividend growth, these companies have the pricing power and hard-asset backing to pass rising input costs on to consumers.
Investors seeking defensive companies that pay substantial dividends are drawn to the Dividend Aristocrats, and with good reason. The 69 companies that made the cut for the 2026 S&P 500 Dividend Aristocrats list have increased their dividends (not just maintained the same level) for 25 consecutive years. But the requirements go even further, with the following attributes also mandatory for membership on the Dividend Aristocrats list:
- Companies must be worth at least $3 billion for each quarterly rebalancing.
- Their average daily volume must be at least $5 million in transactions for every trailing three-month period at every quarterly rebalancing date.
- They must be members of the S&P 500.
We reviewed the list and identified five companies that could perform well for investors during inflationary times, and they make sense for growth and income investors now. All are rated Buy at top Wall Street firms we cover.
Why Do We Cover the Dividend Aristocrats?
S&P 500 companies that have paid and raised dividends for 25 years or longer are the types of investments growth and income investors want to buy and hold in their portfolios for the long term. These stocks are mostly conservative, and if we see a dramatic market correction, they will likely hold up much better than volatile technology and momentum names.
AbbVie
AbbVie (NYSE:ABBV) is ranked sixth among the largest biomedical companies by revenue. This stock is one of Wall Street’s top pharmaceutical picks and an excellent choice for long-term ownership, offering a reliable 2.58% dividend yield. Few dividend stories in the market match what AbbVie has delivered since spinning off from Abbott Laboratories in 2013. The dividend has grown from $1.60 per share to a projected $6.92 in 2026, more than a fourfold increase in roughly a decade, compounding at better than 15% annually. That kind of dividend growth doesn’t just keep pace with inflation; it outpaces it.
AbbVie discovers, develops, manufactures, and sells pharmaceuticals worldwide. It offers:
- Humira, an injection for autoimmune and intestinal Behçet’s diseases and pyoderma gangrenosum
- Skyrizi to treat moderate to severe plaque psoriasis, psoriatic disease, and Crohn’s disease
- Rinvoq to treat rheumatoid and psoriatic arthritis, ankylosing spondylitis, atopic dermatitis, axial spondyloarthropathy, ulcerative colitis, and Crohn’s disease
Imbruvica for the treatment of adult patients with blood cancers; Epkinly to treat lymphoma - Elahere to treat cancer
- Venclexta/Venclyxto to treat blood cancers
It also provides:
- Facial injectables, plastics and regenerative medicine, body contouring, and skin care products
- Duopa and Duodopa to treat advanced Parkinson’s disease
- Ubrelvy for the acute treatment of migraine in adults
- Qulipta for episodic and chronic migraine
- Botox is therapeutic for depressive disorder
The company also offers Ozurdex for eye diseases, as well as Lumigan/Ganfort and Alphagan/Combigan to reduce elevated intraocular pressure in patients with open-angle glaucoma or ocular hypertension. AbbVie also offers Restasis to increase tear production, along with other eye care products.
Further, it provides:
- Mavyret/Maviret to treat chronic hepatitis C virus genotype 1-6 infection
- Creon, a pancreatic enzyme therapy
- Lupron to treat advanced prostate cancer, endometriosis, and central precocious puberty, and patients with anemia caused by uterine fibroids
- Linzess/Constella to treat irritable bowel syndrome with constipation and chronic idiopathic constipation
- Synthroid for hypothyroidism
Piper Sandler has an Overweight rating and a $303 price target.
Chevron
Chevron (NYSE:CVX) is an American multinational energy company primarily focused on oil and gas. This integrated giant is a safer option for investors looking to gain exposure to the energy sector and pays a substantial 3.44% dividend yield, which was raised by 5% earlier this year.
Chevron operates integrated energy and chemicals businesses worldwide through two segments. The Upstream segment is involved in the following:
- Exploration, development, production, and transportation of crude oil and natural gas
- Processing, liquefaction, transportation, and regasification associated with liquefied natural gas
- Transportation of crude oil through pipelines, and transportation and storage
- Marketing of natural gas, as well as operating a gas-to-liquids plant
The Downstream segment engages in:
- Refining crude oil into petroleum products
- Marketing crude oil, refined products, and lubricants
- Manufacturing and marketing renewable fuels
- Transporting crude oil and refined products by pipeline, marine vessel, motor equipment, and rail car
- Manufacturing and marketing of commodity petrochemicals, plastics for industrial uses, and fuel and lubricant additives
It also involves cash management, debt financing, insurance operations, real estate, and technology businesses.
Chevron completed its $53 billion acquisition of Hess in July 2025. The merger proceeded after a favorable arbitration ruling against Exxon over Hess’s lucrative offshore oil assets in Guyana. The purchase has strengthened an already solid balance sheet and earnings.
Bank of America has a Buy rating and a price target of $227.
PepsiCo
This top consumer staples stock reported surprisingly solid second-quarter earnings and will continue supplying goods for upcoming football tailgates and parties. PepsiCo (NASDAQ:PEP) is a global food and beverage company that pays a notable 4.16% dividend yield. The company’s low volatility (beta of 0.375) makes it a steady, defensive holding perfect while waiting for a comeback.
Its Frito-Lay North America segment offers:
- Lays and Ruffles potato chips
- Doritos, Tostitos, and Santitas tortilla chips
- Cheetos cheese-flavored snacks, branded dips
- Fritos corn chips
The Quaker Foods North America segment provides:
- Quaker Oatmeal
- Grits
- Rice cakes
- Natural granola and oat squares
- Pearl Milling mixes and syrups
- Quaker Chewy granola bars
- Cap’n Crunch cereal
- Life cereal
- Rice-A-Roni side dishes
The North America Beverages segment offers beverage concentrates, fountain syrups, and finished goods under these brands:
- Pepsi
- Gatorade
- Mountain Dew
- Diet Pepsi
- Aquafina
- Diet Mountain Dew
- Tropicana Pure Premium
- Sierra Mist
- Mug
J.P. Morgan has an Overweight rating with a $170 target price.

Procter & Gamble
Procter & Gamble (NYSE:PG) was founded more than 185 years ago as a soap and candle company. It has paid dividends to shareholders since 1891, raised them for 70 straight years, and currently pays a 2.98% dividend. The company is focused on providing branded consumer packaged goods to consumers worldwide and has operations in approximately 70 countries.
Procter & Gamble segments include:
- Beauty
- Grooming
- Health Care
- Fabric & Home Care
- Baby
- Feminine & Family Care
The company’s products are sold in approximately 180 countries and territories primarily through mass merchandisers, e-commerce, including social commerce channels, grocery stores, membership club stores, drug stores, department stores, distributors, wholesalers, specialty beauty stores, including airport duty-free stores, high-frequency stores, pharmacies, electronics stores, and professional channels. It also sells directly to individual consumers.
Procter & Gamble offers products under such brands as:
- Head & Shoulders
- Herbal Essences
- Pantene
- Rejoice
- Olay
- Old Spice
- Safeguard
- Secret
- SK-II
- Braun
- Gillette
- Venus
- Crest
- Oral-B
- Ariel
- Downy
- Gain
- Tide
- Always
- Always Discreet
- Tampax
- Bounty
Citigroup has a Buy rating and a $170 target price.
Target
This American retail corporation with a chain of discount department stores and hypermarkets has rebounded strongly this year after a difficult 2025. Target (NYSE:TGT) is a general merchandise retailer in the United States and pays a 2.68% dividend. It offers apparel for women, men, boys, girls, toddlers, infants, and newborns, as well as jewelry, accessories, and shoes. The company also offers beauty and personal care products, baby gear, cleaning supplies, paper products, and pet care products.
Target also provides:
- Dry grocery, dairy, frozen food, beverages, candy, snacks, deli, bakery, meat, and food service
- Electronics, which includes video game hardware and software
- Toys, entertainment, sporting goods, and luggage
- Furniture, lighting, storage, kitchenware, small appliances, home décor, bed, and bath
- Home Improvement
- School/office supplies
- Greeting cards, party supplies, and other seasonal merchandise
The company also sells merchandise through periodic design and creative partnerships, shop-in-shop experiences, and in-store amenities. It also sells its products through its stores and digital channels, including Target.com.
UBS has a Buy rating with a $185 price target.


The post When Inflation Is Sticky, 5 Dividend Aristocrats Are the Stocks to Own Now and Forever appeared first on 24/7 Wall St..
]]>Oil markets have spent 2026 learning an expensive lesson: barrels matter most when they suddenly disappear. The conflict with Iran and disruption of the Strait of Hormuz forced the U.S. and its allies to tap emergency inventories to keep crude flowing and limit the damage to consumers and refiners.
That strategy worked, but the bill is becoming clearer. U.S. Strategic Petroleum Reserve inventories fell another 3.7 million barrels last week to 289.7 million, their lowest level since November 1982, according to the Energy Dept.
The Emergency Cushion Is Getting Thin
The SPR has about 714 million barrels of authorized capacity, meaning today’s inventory represents roughly 41% of that total. The latest draw is part of a planned 172-million-barrel U.S. contribution to a broader International Energy Agency release. If the authorized U.S. releases are completed, inventories could fall toward 243 million barrels.
That number matters because the SPR is not simply a giant underground gas station. The Government Accountability Office found in 2026 that current effective drawdown capacity was already about 2.7 million barrels per day versus a 4.4-million-barrel design rate, with low cavern inventories contributing to some limitations. Federal law also restricts limited drawdowns below 252 million barrels.
In other words, every additional barrel removed doesn’t just shrink the inventory. It reduces the U.S.’s flexibility.
The Next Shock Could Hit Harder
Assuming the Strait of Hormuz situation normalizes, the U.S. Energy Information Administration expects Middle Eastern production to return closer to pre-conflict levels in early 2027, although it still expects about 600,000 barrels per day of disruption through the end of next year. That is the bullish case for rebuilding the buffer.
The problem is that oil has plenty of other ways to surprise investors. EIA data show the Strait of Malacca carried 23.2 million barrels per day in the first half of 2025, more than Hormuz’s 20.9 million barrels per day. Bab el-Mandeb handled 4.2 million barrels per day, while the Turkish Straits moved 3.7 million.
A major attack on Persian Gulf infrastructure, disruption in the Black Sea, another Red Sea escalation, or a hurricane shutting U.S. production and refining could therefore arrive when America’s strategic buffer is already depleted.
That’s the key investment thesis: the SPR has reduced today’s oil-price risk by increasing tomorrow’s sensitivity to supply disruptions.
Oil Producers Have the Better Setup
The U.S. is in a stronger position than it was in the 1980s because domestic production provides an important supply offset. But American production cannot instantly replace a global shipping disruption.
For investors, that makes upstream producers such as Exxon Mobil (NYSE:XOM) and Chevron (NYSE:CVX) potentially important beneficiaries if tighter physical markets push crude prices higher. The effect is even more significant if the government eventually begins rebuilding the SPR.
Refilling 200 million barrels would create a large buyer in the market. At $70 per barrel, that represents $14 billion of crude purchases. At $90, it becomes $18 billion. That is future demand sitting on the other side of today’s drawdown.
Key Takeaway
In short, the SPR did its job. Its releases helped moderate the price impact of the 2026 supply shock and supported refinery operations while global oil flows were disrupted. But investors should not mistake temporary relief for restored energy security. At 289.7 million barrels, the reserve is already at a 44-year low, while operational constraints make the remaining barrels less useful as inventory falls.
If the Strait of Hormuz normalizes, rebuilding can begin. If another major disruption arrives first, the U.S. will have fewer barrels to deploy and fewer days to buy time.
For investors, that argues for watching physical oil markets — not just headline crude prices. A thinner SPR makes supply shocks more valuable to producers, more expensive for consumers, and potentially more consequential for the broader economy.
The post America’s Strategic Petroleum Reserve Is Running on Fumes. What Happens When the Next Supply Shock Hits? appeared first on 24/7 Wall St..
]]>ExxonMobil (NYSE:XOM) and Chevron (NYSE:CVX) both reported blockbuster quarters this summer, and both raised dividends yet again in 2026. That makes this the right moment to look past a single earnings report and ask a harder question: over a full decade, which oil major has actually treated dividend investors better?
Two Very Different Quarters Under the Hood
Chevron’s Q2 was the louder headline. Revenue hit $67.20B, worldwide production reached a record 4,070 MBOED, and adjusted EPS came in at $6.06, a seventh straight beat. CEO Mike Wirth credited “disciplined investment and strong execution”, and it shows: US refinery throughput ran at 97% utilization, and downstream earnings jumped to $4.87B from $737M a year earlier.
ExxonMobil’s Q2 was quieter on the surface but arguably more impressive. The company posted industry-leading earnings of $14.5 billion and $23.6 billion in operating cash flow despite losing “approximately 10% of our upstream production” to Middle East disruption. Guyana alone contributed roughly 900,000 barrels per day, and Permian output topped 1.8 million oil equivalent barrels per day.
Ten Years of Dividend Checks, Side by Side
Now the payout question. Both companies have been quietly compounding for a decade, but the paths look different.
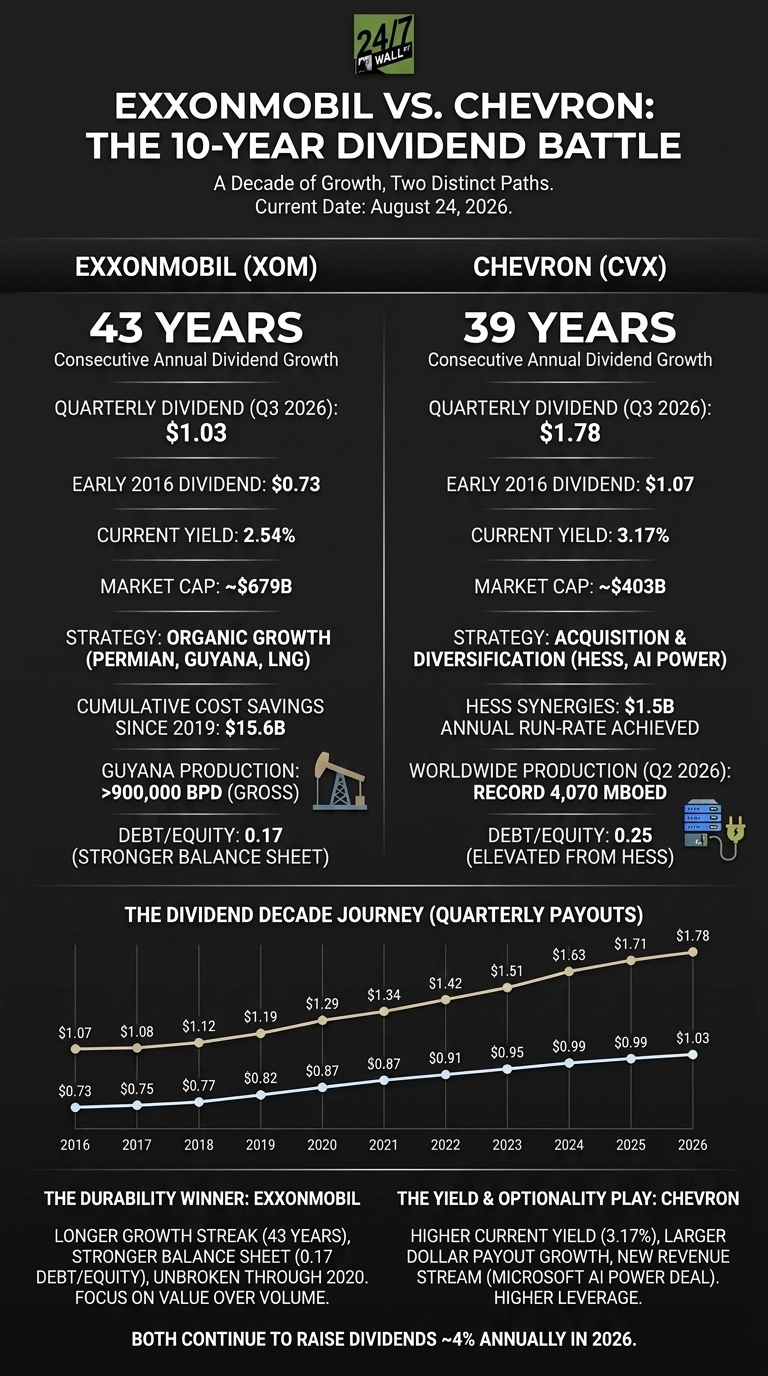
| Dividend Lens | ExxonMobil | Chevron |
| Quarterly div, early 2016 | $0.73 | $1.07 |
| Quarterly div, 2026 | $1.03 | $1.78 |
| Consecutive annual raises | 43 years | 39 years |
| Current yield | 2.46% | 3.39% |
Chevron grew its per-share payout by a larger dollar amount over the decade, and its yield today is meaningfully higher. But Exxon never blinked through the 2020 crash, when many peers cut, and now sits on 43 consecutive annual increases. On pure streak length and defensiveness, Exxon wins.
Organic Growth Vs. Buy-and-Build
The strategies funding those checks have diverged sharply. Exxon is riding organic firepower: Permian, Guyana, Golden Pass LNG, and $16.3 billion of cumulative structural cost savings since 2019. CFO Neil Hansen described Guyana as “very much an inflection into free cash flow” after full recovery of the $55 billion investment.
Chevron went the acquisition route. Hess synergies hit a $1.5 billion annual run-rate six months ahead of schedule, and Chevron cut more than $8 billion of debt in Q2 alone. Then came Project Kilby, a 20-year take-or-pay deal with Microsoft (NASDAQ:MSFT) for 2.67 gigawatts of behind-the-meter power for AI data centers. That is a genuinely new revenue stream for a Big Oil dividend.
What Decides the Next Ten Years
I will be watching whether Guyana’s cash-flow inflection lets Exxon accelerate its raises past the current roughly 4% annual pace. You should keep an eye on whether Chevron’s Microsoft deal actually clears FID later in 2026, because mid-teens returns on contracted power would change the dividend math.
Why I Give the Decade to Exxon, But Own Chevron for Yield
If someone made me pick a ten-year dividend winner based on durability, I lean Exxon. The 0.17 debt-to-equity balance sheet and unbroken streak through 2020 tell me the check keeps clearing in the ugliest markets (we ranked ten companies with the longest raise streaks by valuation in a free Dividend Kings report).
If I wanted more current income and did not mind Hess integration risk, Chevron’s 3.39% yield and Kilby optionality look more interesting. Both can work. Neither is broken. I just view them as meaningfully different investments.
The post ExxonMobil vs. Chevron: We Compared 10 Years of Dividend Growth And Here’s the Winner appeared first on 24/7 Wall St..
]]>Petrobras (NYSE:PBR) has quietly become the best-performing supermajor of 2026. The Brazilian state-controlled producer’s ADRs are up 62.64% year to date through August 20, well ahead of Exxon Mobil (NYSE:XOM) at 40.81% and Chevron (NYSE:CVX) at 38.76%. Yet the payout that made PBR a fixture in yield portfolios has shrunk sharply.
Petrobras’ trailing twelve-month distribution now stands at $0.707311 per ADS, versus roughly $1.89 across 2024’s payments. The two 2026 ex-dividend payments so far have been $0.124094 (April 24) and $0.142639 (June 3), with the next payment scheduled for September 28, 2026. The preferred ADR, Petrobras (NYSE:PBR-A), tracks the same schedule and is up 53.53% year to date.

Record First Half, Smaller Check
The 6-K filed August 20, 2026 showed a first half that any oil investor would take: revenue up 35.7% to $57.14 billion, net income attributable to shareholders up 55.3% to $16.63 billion, production up 15.1% to a record 3,281 mboed, adjusted EBITDA up 52.2% to $29.96 billion, and free cash flow of $11.51 billion. Petrobras still paid $3.74 billion in H1 shareholder dividends, but the per-share slice is down because the pie is being sliced differently.
Where the Cash Went
Two forces are absorbing the incremental cash. First, debt. Petrobras ended Q2 2026 with gross debt of $70.8 billion and net debt of $60.4 billion, and management wants gross debt steered toward $65 billion, with a $75 billion ceiling. On the Q2 call, executives said the $65 billion target was being pulled forward: “the ambition we had in our strategic planning which was supposed to take place in the end of this five-year period ending in 2030 so the idea is to bring that slightly forward”. On extraordinary dividends, they were blunt: “That’s very unlikely now because first Brent is expected to stay at the same level for quite a while.”
Second, taxes. Brazil’s new 12% crude and 50% diesel export tax under Provisional Measure No. 1,340/2026 added $1,087 million in tax expense in H1 2026, and while the regime expired in July 2026, it remains in effect pending reassessment. The controlling shareholder that sets the payout also levied the tax.
What Investors Should Watch
The Q2 earnings report was messier than the headline suggests: GAAP EPS of $0.81 missed the $1.40 consensus by 42.24% even as quarterly net income nearly doubled to $10.44 billion. With PBR trading at a forward P/E near 4 and a $22.01 analyst target, the debate for income investors is simple: capital return has been redirected to the balance sheet, and management has signaled that stance is unlikely to reverse until Brent cooperates. A double-digit trailing yield that quietly halves is exactly the pattern we mapped in a free guide to dividend trap warning signs.

The post This Oil Stock Beat Exxon and Chevron in 2026. Its Dividend Shrank appeared first on 24/7 Wall St..
]]>Brent crude traded at $95.40 a barrel in early trading this morning, up from $67.21 a year ago, after the expired US-Iran ceasefire and Strait of Hormuz disruption pushed the oil complex back into crisis mode. That matters for retirees because July CPI came in mild at a 3.4% annual rate with a 0.1% monthly gain, extending a cooling trend after annual CPI ran 4.2% in May 2026. August CPI is not published until September, so this crude spike has not yet shown up in an official inflation print. It remains a threat to the cooldown that has not yet broken the trend. The three names below convert every dollar of Brent strength into cash returns, whether the Fed likes it or not.
Chevron Turns $95 Brent Crude Into Record Cash
Chevron (NYSE:CVX) pays a quarterly dividend of $1.78 per share, raised from $1.71 and declared January 30, 2026, for a forward annualized payout of $7.12 and a current yield of 3.16%. The next check hits accounts on September 10, 2026.
Dividend safety here is the real story. Chevron generated $19.7 billion of cash flow from operations excluding working capital and $15.4 billion of adjusted free cash flow in the second quarter, while cutting debt by more than $8 billion in the quarter alone. Net debt to CFFO ended the period at 0.6 times, interest coverage sits at 13.7x, and the company reached $3 billion of structural cost reductions six months ahead of schedule. The historical dividend record is a long, steady march of quarterly hikes: $1.63 in the 2024 payments, $1.71 through 2025, and $1.78 starting with the February 2026 ex-date.
The bull case is simple. Chevron produced a record 2,077 MBOED in the US upstream and grew worldwide output by 20% year over year to 4,070 MBOED, so every $10 move on Brent lands on a much bigger production base than it did a year ago. Hess synergies of $1.5 billion have been captured within a year, and Guyana pushes high-margin barrels into the 2030s. For color, Berkshire Hathaway’s June 30, 2026 13F disclosed 84,375,856 CVX shares worth $13.99 billion, or 4.67% of the portfolio, held unchanged during the quarter. That disclosure reflects a mid-year position rather than fresh buying.
The caveat: CPC pipeline flows out of Kazakhstan and the Strait of Hormuz situation can flip from tailwind to headwind fast, and higher DD&A from the Hess deal will keep pressure on reported earnings.
Exxon Mobil Has the Balance Sheet, and the Next Raise Is Pending
Exxon Mobil (NYSE:XOM) pays a quarterly dividend of $1.03 per share, raised from $0.99 and declared October 31, 2025. All three 2026 payments have held at $1.03, so treat the next hike as still pending. Forward annualized comes to $4.12, a yield of 2.54%, with the next payment on September 10, 2026.
The safety read is arguably the strongest in Big Oil. Exxon’s second quarter delivered industry-leading earnings of $14.5 billion, cash flow from operations of $23.6 billion, more than $17 billion of free cash flow, and a more than $7 billion reduction in net debt, all while absorbing the temporary loss of approximately 10% of upstream production from Middle East disruption. Debt to equity is 0.17, net debt to EBITDA is 0.55, and interest coverage is 56.3x. Cumulative structural cost savings hit $16.3 billion since 2019. The dividend history moved from $0.95 across 2024, to $0.99 in early 2025, to $1.03 starting with the November 2025 ex-date. CEO Darren Woods told investors this is a “fundamentally stronger company than it was just a few years ago.”
The bull case for retirees is that Exxon has decoupled cash returns from crude prices. It returned more than $9 billion to shareholders through dividends and share repurchases in the quarter, is executing a $20 billion share repurchase plan for 2026, and just achieved a Guyana milestone that management called an inflection: Neil Hansen told analysts “we’ve fully recovered the $55 billion of investment along with all the operating costs” and projected two times the level of free cash flow in 2030 than we saw in 2025. Permian output hit a record 1.8 million oil equivalent barrels per day, and Golden Pass LNG Train 1 shipped its first cargo in April 2026.
The caveat: reported Q1 net income of $4.18 billion was dragged by $3.88 billion of mark-to-market timing and $706 million in Middle East disruption losses, so quarterly headlines will remain lumpy while the Strait remains contested.
Enterprise Products Partners Pays You a Toll on Every Barrel
Enterprise Products Partners (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, raised from $0.55 on July 7, 2026, for a forward annualized payout of $2.24 per unit. At a unit price near $38.20, that is a high-yield income stream backed by fee-based midstream volumes rather than crude prices themselves. One important structural note for retirement accounts: EPD is a master limited partnership that pays distributions, issues a Schedule K-1 rather than a 1099, and can generate unrelated business taxable income (UBTI) inside an IRA. That is not a reason to avoid it, but it belongs on the checklist before you buy it in a Roth.
Coverage is the headline safety number. Management reported record $2.8 billion of EBITDA, a 17% increase over the second quarter of last year, and adjusted cash flow from operations up 19% to a record $2.5 billion. Distribution coverage from operational distributable cash flow was 1.9x. Consolidated leverage sits at the company’s 3.0 target on a net basis, weighted average cost of debt is 4.7%, and 97% of debt is fixed rate with a 17-year weighted average life. Distributions have climbed steadily from $0.515 in early 2024 to $0.56 in July 2026.
The bull case is that Enterprise gets paid to move the barrels the world is fighting over. Pipeline volumes rose 8% year over year to 14.7 million barrels a day of oil equivalent, marine terminal volumes jumped 33%, and Permian gas processing hit 4.3 billion cubic feet a day, up 14%. The April-May demand surge added roughly $200 million in the quarter. Management returned $1.2 billion in cash distributions plus $159 million in unit buybacks, retaining $1.1 billion for growth and repurchases. Co-CEO Jim Teague said Enterprise posted “record earnings and cash flow in the second quarter of 2026.”
The caveat: growth capex is stepping up to the $3 billion area in 2027, and NGL prices still swing with the commodity cycle, so distribution growth is more likely to keep its slow-and-steady cadence than to accelerate on the oil spike.
Bottom Line for Income Investors
Chevron gives you a delivered 2026 raise, record US production, and a fortress balance sheet. Exxon gives you the strongest balance sheet in the industry, a Guyana free cash flow inflection, and a pending raise that its cash generation clearly supports. Enterprise gives you a toll booth on the entire US export machine with 1.9x coverage and a fresh distribution bump. If Brent settles in the mid-$90s, all three keep growing payouts; if oil rolls back to the $80s, coverage on all three still holds, which is exactly the point for a retiree portfolio. Building a lineup like this so you can live off the checks without selling shares is the whole exercise in our free dividend ladder guide.
The post Crude Hits $95 and Threatens the Inflation Cooldown: 3 Energy Stocks Turning the Oil Spike Into Bigger Shareholder Payouts appeared first on 24/7 Wall St..
]]>Exxon Mobil (NYSE:XOM) and Chevron (NYSE:CVX) both reported second quarter results on July 31, 2026, and the two supermajors are steering through the same tight oil market with very different playbooks.
Exxon leaned on Guyana, the Permian, and integrated refining. Chevron leaned on a freshly digested Hess deal and a new bet on powering AI data centers.
Guyana Cash Machine Meets a Hess-Powered Chevron
Exxon delivered $14.5 billion in quarterly earnings and $23.6 billion in operating cash flow even after losing roughly 10% of upstream production to disruptions.
Guyana hit 900,000 gross barrels per day, and the company said it has fully recovered its $55 billion of investment there, tipping the asset into what CFO Neil Hansen called an “inflection into free cash flow.” The Permian set another record at 1.8 million oil equivalent barrels per day, powered by 83 four-mile wells drilled year to date.
Chevron told a different story: scale bought and quickly monetized. Global upstream grew more than 5% quarter over quarter, U.S. upstream hit a record nearly 2.1 million barrels of oil equivalent per day, and adjusted free cash flow reached $15.4 billion.
CEO Mike Wirth said the Hess integration captured “50% more synergies than initially targeted, with $1.5 billion realized six months ahead of schedule.” Debt fell by more than $8 billion in the quarter.
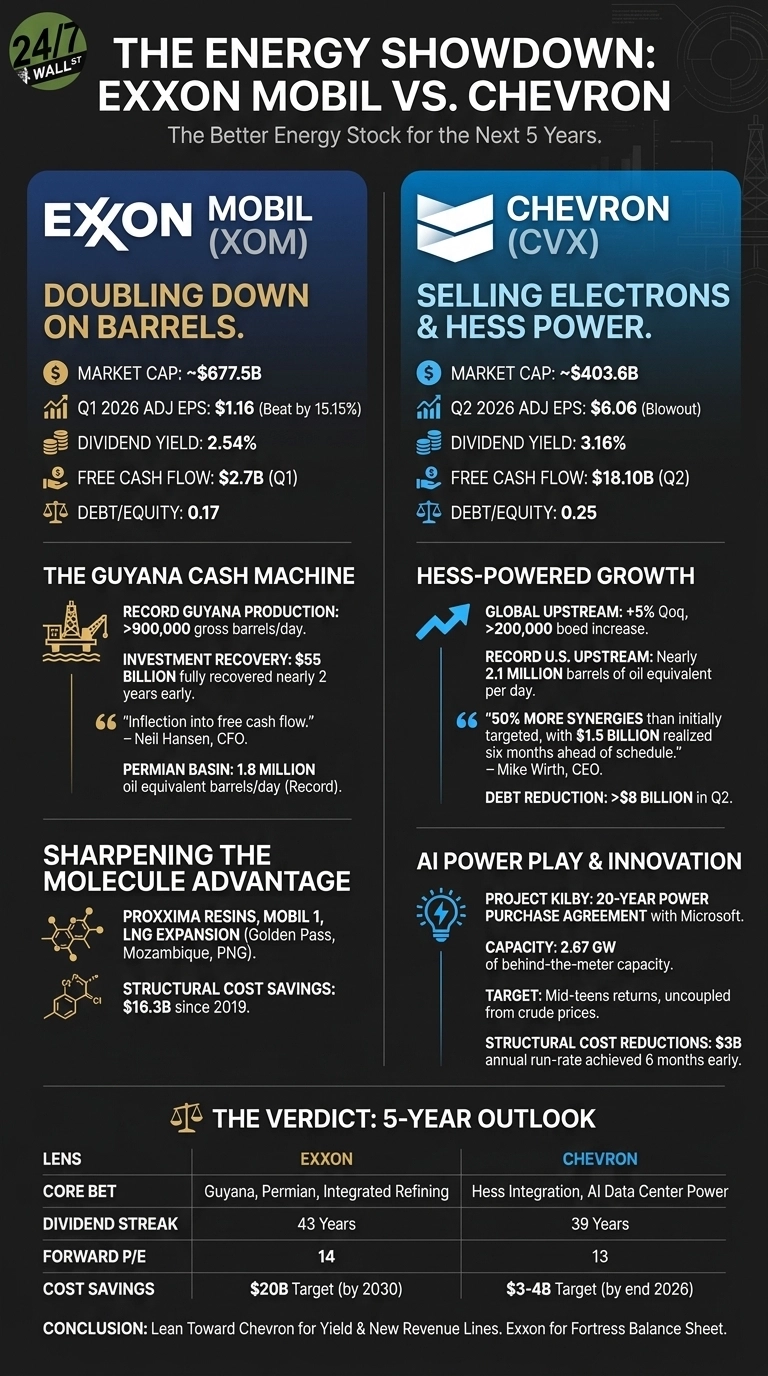
One Doubles Down on Barrels. One Sells Electrons.
| Lens | Exxon | Chevron |
| Core bet | Guyana, Permian, LNG, chemicals | Hess integration, AI data center power |
| Cost program | $16.3B saved since 2019 | $3B run-rate, hit six months early |
| Dividend yield | 2.53% | 3.44% |
| Forward P/E | 14 | 13 |
Chevron’s most eye-catching move is Project Kilby, a 20-year take-or-pay power purchase agreement with Microsoft (NASDAQ:MSFT) for 2.67 gigawatts of behind-the-meter capacity, targeting mid-teens returns uncoupled from crude prices. It is a reminder that the AI buildout runs on power as much as silicon, and we pulled together seven non-chipmaker suppliers riding that same wave in a free report here.
Exxon is going the opposite direction, sharpening its molecule advantage through Proxxima resins, Mobil 1, and expanded LNG at Golden Pass, Mozambique, and Papua New Guinea.
Next Test: Guyana Cash and Kilby Returns
I will be watching whether Exxon’s Guyana free cash flow really doubles by 2030 versus 2025, as management promised. That is the linchpin of the buyback story behind the $20 billion repurchase plan.
For Chevron, the tell will be Project Kilby’s final investment decision later this year and whether Iraq’s West Qurna II converts into competitive terms. CPC pipeline exposure and OPEC+ discipline sit uncomfortably in the background of both stories.
Why I Lean Toward Chevron for the Next Five Years
Both stocks have run hard. XOM is up 57.79% over the past year; CVX is up 40.68%. If you want the fortress balance sheet, a 43-year dividend streak, and the deepest well of long-cycle projects, Exxon is the cleaner choice. Its integrated chemical and specialty margins give it ballast that Chevron simply cannot match today.
Personally, I lean toward Chevron for the next five years. The Hess synergies are landing faster than promised, the Microsoft power deal opens a genuinely new revenue line, and the 3.44% yield pays me to wait.
My view flips if Brent collapses back below $70 and Kilby slips, because Chevron carries higher post-Hess leverage. CVX fits a yield-focused profile; XOM fits investors prioritizing the sturdier compounder.
The post Chevron vs. Exxon Mobil: The Better Energy Stock for the Next 5 Years appeared first on 24/7 Wall St..
]]>Dividend investors have had plenty to cheer in 2026. Pfizer (NYSE:PFE) is up 19.3% year to date, Chevron (NYSE:CVX) has surged 38.76%, and AbbVie (NYSE:ABBV) has added 19.16%.
With all three throwing off healthy yields and beating estimates, I want to lay out how Pfizer could reach $35, Chevron $250, and AbbVie $325 in 2027.
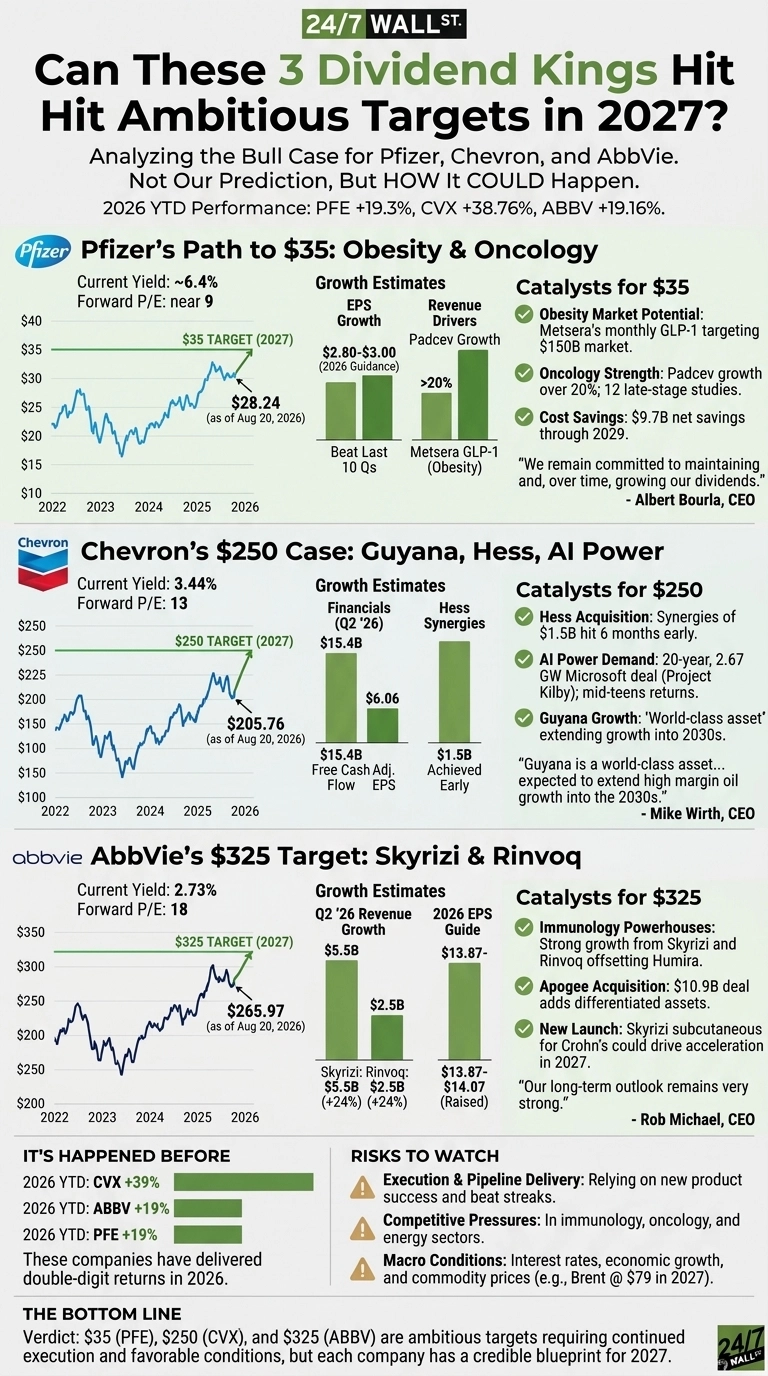
Pfizer’s Path to $35 Runs Through Obesity and Oncology
Pfizer trades at a forward P/E near 9 while paying a $1.72 annualized dividend yielding roughly 6.4%. At $35, shares would still trade under 12x the midpoint of 2026 guidance of $2.80 to $3. CEO Albert Bourla told investors, “we remain committed to maintaining and, over time, growing our dividends.”
Pfizer has beaten EPS expectations in all ten of the last ten quarters. Catalysts for a re-rating include Metsera’s monthly GLP-1 targeting a $150 billion obesity market, Padcev growth over 20%, and $9.7 billion in cost savings through 2029.

Chevron’s $250 Case Rests on Guyana, Hess, and AI Power
Chevron just delivered $6.06 in adjusted Q2 EPS and $15.4 billion in free cash flow, with debt cut by more than $8 billion. The $7.12 annualized dividend is comfortably covered. At forward P/E of 13, $250 would push the multiple toward 16, reasonable given Hess synergies of $1.5 billion hit six months early.
The Microsoft 20-year, 2.67 gigawatt Project Kilby offers mid-teens returns uncorrelated to oil. CEO Mike Wirth described Guyana as a “world-class asset” extending growth into the 2030s. EIA sees Brent averaging $79/b in 2027, a headwind Chevron has already stress-tested.
AbbVie’s $325 Target Hinges on Skyrizi and Rinvoq
AbbVie posted Q2 revenue of nearly $17 billion, up 10.2%, with Skyrizi at $5.5 billion (+24%) and Rinvoq topping $2.5 billion (+23.7%). Management raised full-year EPS to $13.87 to $14.07. On forward P/E of 18, $325 implies roughly 23x, in line with the S&P 500. Piper Sandler raised the firm’s price target on AbbVie to $303 from $298 and keeps an Overweight rating on the shares.
CEO Rob Michael said AbbVie’s “long-term outlook remains very strong.” The $10.9 billion Apogee deal and Skyrizi subcutaneous Crohn’s launch could “drive a meaningful acceleration” in 2027. The $6.92 annualized dividend keeps growing, up from $1.64 quarterly in 2025 to $1.73 today.

Bottom Line on Three Dividend Bull Cases
Wall Street’s consensus targets sit at $28.61 for Pfizer, $216.83 for Chevron, and $276.41 for AbbVie. My stretch targets of $35, $250, and $325 require beat streaks to continue, pipelines to deliver, and macro conditions to cooperate.
Returns like these carry execution risk each year, yet each name has laid out a credible blueprint for 2027 (for investors who want the longest-running dividend growers screened by valuation, we ranked ten of them in a free Dividend Kings report).
The post Dividend Giants Pfizer, Chevron, AbbVie: Bold 2027 Price Targets Ahead appeared first on 24/7 Wall St..
]]>
Oil has become one of the clearest financial beneficiaries of the Iran war — and one of the biggest headaches for American drivers. The Strait of Hormuz, a critical artery for global energy shipments, remains effectively closed, with little tanker traffic moving through the waterway.
West Texas Intermediate (WTI) crude is above $82 a barrel and Brent is above $88, compared with roughly $73 Brent before the war. The result has been a windfall for Big Oil. Bloomberg reported in July that combined earnings for the five supermajors were on track to be the third-highest in history, while several companies have already reported profits more than double a year ago.
Exxon And Chevron Are Already Cashing In
Exxon Mobil (NYSE:XOM) reported $14.5 billion of second-quarter profit, up from $7.1 billion a year earlier. Chevron (NYSE:CVX) reported $12.1 billion, compared with $3.1 billion. Together, they generated roughly $26.6 billion in quarterly earnings.
Both companies are integrated — meaning they produce crude, refine it into gasoline and diesel, and market those products. That matters when a geopolitical shock disrupts the entire energy chain.
Chevron’s upstream earnings jumped to $8.2 billion, while downstream earnings reached $4.9 billion. Exxon generated $17.2 billion of free cash flow and returned $9.4 billion to shareholders through dividends and buybacks.
Their stocks reflect that strength, with Exxon and Chevron both up 33% year-to-date. Neither, though, is at its March peak, leaving room for further gains if crude prices remain elevated.
War Escalation Could Raise Gas Prices Further
Trump has repeatedly accused oil companies of gouging consumers, singling out Exxon, Chevron, BP (NYSE:BP), and Shell (NYSE:SHEL), and demanding lower prices. In June, he said gasoline should be $2.25 a gallon and ordered a Justice Department investigation into potential price gouging.
However, Exxon and Chevron don’t simply choose the price posted at every gas station. Local competition, regional supply, refining margins, transportation costs, and crude prices all influence what motorists pay.
AAA’s national average was about $4.06 a gallon this morning, versus $3.98 a month earlier and $3.11 a year ago. Gasoline had been below $3 before the Iran war began. Notably, widening the war could make Trump’s price problem worse.
Trump has repeatedly extended the truce to give negotiations with Iran more time. Yet Iran continues threatening shipping through Hormuz, and Reuters reported today that Tehran is considering a shift to a “fully offensive” posture if diplomacy fails.
Now Trump has threatened to bomb Oman if it “gets in the way” of peace talks. Oman is a U.S. ally and has been mediating between Washington and Tehran.
The Bigger Risk For Investors
An attack on Oman would introduce another Middle Eastern country into the conflict. If other Gulf states that have so far remained outside the fighting begin choosing sides, the market could price an even larger supply disruption.
That would be bullish for Exxon and Chevron’s upstream businesses and potentially their refining operations. But investors shouldn’t assume every additional $10 in crude translates directly into another $10 billion of profit. Demand can weaken, refining margins can reverse, and a peace deal reopening Hormuz could send oil prices sharply lower. Brent crude is already well below its $126 wartime peak.
Key Takeaway
In short, Exxon and Chevron are unusually well positioned for a prolonged oil shock because their integrated businesses can capture profits from production through refining and marketing. Another escalation could push quarterly earnings above their already massive Q2 totals — but investors shouldn’t chase the stocks solely on the prospect of war.
The better thesis is that Exxon and Chevron have demonstrated they can convert elevated crude and refining margins into billions of dollars of cash. If Hormuz remains closed, that cash machine could keep running. If peace finally reopens the strait, the windfall can disappear almost as quickly as it arrived.
The post Oil Profits Have More Than Doubled. Here’s What Trump Escalating the Iran War Could Mean for XOM and CVX appeared first on 24/7 Wall St..
]]>The Wall Street Journal published a report today, Monday, August 17, 2026, titled “Iran’s Secret Plan to Escalate the War,” the same day the 60-day US-Iran memorandum of understanding signed in June expires with no follow-on deal in sight. For investors, the question is narrower: if the ceasefire framework is dead and the Strait of Hormuz has effectively stopped moving cargo, why aren’t oil equities rising on the news?
The WSJ report, based on Arab and Iranian sources, alleges that hardline elements in Iran’s leadership treated the June memorandum as preparation for future conflict and reportedly decided to violate it from the moment it was signed. According to the report, the hardliners gave the Islamic Revolutionary Guard Corps greater authority over Iran’s military, appointed veteran Iran-Iraq War commanders to senior posts, and accelerated missile and UAV production. US officials reportedly warned Gulf countries, particularly Kuwait, that Iran was preparing to strike in “enemy territory.”
The Strait Has Effectively Stopped
Kpler data cited by Reuters and CNBC shows the mechanism. Only five cargo ships passed through the Strait of Hormuz on Saturday, versus 31 the previous weekend, and no ships were registered to pass on Sunday. Shipping is down 90% since the war began February 28, 2026. The Strait normally averages about 130 vessel transits per day and carries about one fifth of the world’s oil. Yet Monday morning, per CNBC, Brent crude futures traded at $88.45 per barrel, down 0.15%, and WTI at $81.79, down 0.74%. Reuters reported the near-term potential for gains is seen as limited amid the stalemate. The muted crude reaction is itself the story.
The Majors and the War Premium
At Friday’s close, Exxon Mobil (NYSE:XOM) sat at $160.10, up 34.83% year to date and 53.82% over the past year. Chevron (NYSE:CVX) closed at $200.00, up 33.71% year to date, and Occidental Petroleum (NYSE:OXY) at $58.36, up 43.27% year to date. Exxon CEO Darren Woods told analysts the company absorbed “the temporary loss of approximately 10% of our upstream production” from the Middle East conflict.
The war premium moves violently in both directions. WTI peaked at $114.58 on April 7, 2026, fell to $69.60 by July 6, rebounded to $93.08 on July 23, dropped to $76.78 on August 5, and stood at $84.77 on August 11.
Exxon’s Valuation Tension
Wall Street’s consensus target of $168.55 sits above Friday’s close, but the ratings mix, 3 strong buy, 7 buy, 14 hold, 1 sell, tilts to holds. Our proprietary model rates XOM a HOLD with a base case of $138.68, citing roughly 13% overvaluation. Forward EPS of $7.07 implies a P/E around 25 on a $658.3 billion market cap.
The Tanker Trade
Frontline (NYSE:FRO) closed Friday at $41.21, up 102.93% year to date and 143.50% over the past year. DHT Holdings (NYSE:DHT) closed at $19.52, up 69.65% year to date. Both posted far larger year-to-date gains than the three majors. Tankers benefit directly from rerouting and higher freight rates.
A caveat on DHT: the latest quarterly dividend was $1.22, versus $0.24 in the same quarter of 2025, and the company pays 100% of ordinary net income. That payout structure means the yield falls when VLCC spot rates fall, not a fixed coupon.
Insurance and the Close
Per The National, citing Marsh broker Marcus Baker, war-risk premiums on tanker hull value rose from a pre-war baseline of about 0.25% of hull value to roughly 3% to 10% now. Insurers collect; operators absorb. HSBC’s Parash Jain told CNBC’s Squawk Box Europe Monday that investors should treat “chaos is the norm” as the base assumption. Watch Kpler’s Strait transit count over the next two weeks and whether Qatar and Pakistan, the current message-carriers, produce anything resembling resumed negotiation.
The post Here’s What “Iran’s Secret Plan To Escalate The War” Means For Oil Stocks appeared first on 24/7 Wall St..
]]>Brian, a caller from Pennsylvania, phoned in to Mad Money on August 13, 2026 with a stock his son had been researching. “My son has been following a stock that has over a 7% dividend yield, and they’ve historically raised the dividend every quarter,” he told Jim Cramer, before asking whether he should build a position in Hess Midstream (NYSE:HESM). Cramer’s verdict landed quickly: “I happen to like Hess Midstream. I happen to like the midstreams, especially Hess… I think you have a winner.”
The Caller’s Case
Brian built his question around two claims. The first was the yield: over 7%, as he described it on air. The second was more striking: Brian said the company had “historically raised the dividend every quarter.” That assertion about a partnership public since 2017 holds up cleanly when checked against the record. Brian also flagged something Cramer glossed past: “Chevron happens to make up about 3.5% of my portfolio.”
What the Distribution Record Actually Shows
Hess Midstream pays quarterly distributions, and the dataset contains 37 records going back to 2017. Every payment in that series is larger than the one before it. There is no cut and no flat quarter anywhere in the progression, which runs from $0.2703 in 2017 to $0.7888 today. That works out to an average annual growth rate of roughly 11% over nine years, which puts the consistency of the streak in sharper relief.
The most recent distribution was declared July 27, 2026, went ex-dividend on August 6, 2026, and was paid on August 14, 2026, at $0.7888 per share. The prior payout was $0.7792. Trailing twelve-month distributions total $3.0869, and the annualized forward figure sits at $3.1552. On the Q2 2026 earnings call, CEO Jonathan Stein reiterated a “targeted 5% annual distribution growth, which we expect to continue.” Past distribution growth does not guarantee future distributions.
The Q2 2026 Numbers Behind the Story
Hess Midstream’s second-quarter 2026 results gave income-focused holders a fresh look at the underlying finances. Net income came in at $173.7 million, with $96.4 million attributable to Class A shareholders, or $0.75 basic earnings per share. Adjusted EBITDA reached $314 million, producing a gross adjusted EBITDA margin of roughly 85%, well above the company’s stated 75% target. Revenue of $399 million slipped about 4% from $414 million a year earlier, as lower Bakken throughput from reduced new-well activity and planned maintenance at the Tioga Gas Plant offset higher tariff rates and growing third-party services.
Management kept its full-year 2026 guidance unchanged: adjusted EBITDA of $1.225 billion to $1.275 billion and adjusted free cash flow of $910 million to $960 million, which the company says represents roughly 20% growth at the midpoint from the prior year. Excess cash after distributions is targeted toward share repurchases and debt reduction, with leverage expected to decline from roughly 3 times toward 2.5 times by 2028.
Cramer’s Answer and the Chevron Link
Cramer stated a preference for the midstream category and for Hess Midstream in particular. He also connected the dots on the customer relationship: “Hess was bought by Chevron, which is why they had the related Chevron.”
Chevron (NYSE:CVX) closed its acquisition of Hess Corporation on July 18, 2025, in an all-stock deal valued at approximately $48 billion. Hess Midstream is a separate, publicly traded partnership that was not itself acquired. Its anchor customer is Hess Corporation, now a Chevron subsidiary, which holds an approximately 38% ownership interest in Hess Midstream as part of that transaction. One year after the close, Chevron CFO Eimear Bonner said on CNBC that the company is “fully integrated” and had already realized $1.5 billion in synergies, 50% more than initially targeted and six months ahead of schedule.
Midstream operators handle gathering, processing, transportation and storage of oil and gas rather than drilling for it, and revenue typically comes from fee-based contracts with producers. That fee-based structure is central to why these partnerships attract income-focused holders: cash flows are relatively predictable even when commodity prices move. The flip side, visible in Q2’s revenue dip, is that throughput volumes depend directly on how much the anchor customer drills.
The Question Cramer Did Not Answer
Brian effectively asked two questions on that call, and Cramer answered the one about the stock. The other was buried in the setup: he already holds Chevron at about 3.5% of his portfolio, and he is considering adding a company whose principal customer relationship runs through Chevron. As Hess Midstream itself noted in its Q2 2026 filings, its results depend materially on Chevron’s drilling plans, nominated volumes, and ability to meet its contractual obligations to the partnership.
A reader in a similar position might reasonably think about what that stacking looks like. Both names sit in energy. Both depend, to different degrees, on Chevron’s Bakken development pace and capital allocation choices. This is a consideration to weigh, not a criticism of Cramer’s view on the stock itself and not advice on what any particular investor should do.
Where the Stock Stands
Hess Midstream closed on August 13, 2026 at $39.78, down 0.75% on the day. The units were up 22.58% year to date from $32.45 at the end of 2025, up 2.62% over the prior year from $38.77 on August 13, 2025, and up 137.7% over five years from $16.74 on August 13, 2021. Market capitalization sits at approximately $5.14 billion.
The Kicker
A distribution record that runs uninterrupted across 37 quarterly payments, with every payment larger than the one before, is unusual in any corner of the market. That is the part of Brian’s case that stands on its own regardless of whose verdict you find persuasive, and it is the part any prospective holder can verify without taking anyone’s word for it. This article is informational and not a recommendation on either stock.
Editor’s note: This update adds Hess Midstream’s Q2 2026 financial results (net income of $173.7 million, adjusted EBITDA of $314 million, and full-year guidance of $910 million to $960 million in free cash flow), the confirmed close date and purchase price of Chevron’s acquisition of Hess Corporation, Chevron’s approximately 38% ownership stake in Hess Midstream, and the one-year integration milestone of $1.5 billion in realized synergies. The nine-year average annual distribution growth rate of roughly 11% was also added to contextualize the 37-quarter streak.
The post “I Think You Have a Winner” Cramer Excited About Hess Midstream’s 7% Dividend Yield appeared first on 24/7 Wall St..
]]>The iShares Core High Dividend ETF (NYSEARCA:HDV) leans hard on two sectors to fund its payout. Energy and pharma names account for the top four holdings, combining for 25.96% of net assets. With HDV up 19.66% year-to-date and yielding roughly 3%, I want to know whether the checks these four giants send to BlackRock are actually safe.
The Four Dividends Powering HDV
| Holding | Weight | Yield | Streak |
|---|---|---|---|
| Exxon Mobil (NYSE:XOM) | 8.42% | 2.65% | 43 yrs |
| Chevron (NYSE:CVX) | 6.42% | 3.67% | 38+ yrs |
| Johnson & Johnson (NYSE:JNJ) | 5.68% | 2.06% | 64 yrs (King) |
| AbbVie (NYSE:ABBV) | 5.44% | 2.80% | 13 yrs standalone |
Exxon: The Cleanest Balance Sheet in the Group
Chevron: Hess Cash Flow Reset the Math
Johnson & Johnson: The Dividend King Earns Its Crown
AbbVie: Growing but Leveraged
The Verdict on HDV’s Income Engine
The post The Energy and Pharma Giants Quietly Funding HDV’s 3% Yield, and How Safe Each One Is appeared first on 24/7 Wall St..
]]>Oil has come alive again in 2026. Brent crude spiked to $138 per barrel on April 7 during the Strait of Hormuz disruption, retraced to the high $60s in early July, and now sits near $89. That volatility has fueled the U.S. majors.
Chevron (NYSE:CVX) is up 24.73% year-to-date, Exxon Mobil (NYSE:XOM) has advanced 28.88%, and Occidental Petroleum (NYSE:OXY) leads the group at 37.26%. Here is the path to CVX at $225, XOM at $180, and OXY at $75 in the year ahead.
Why Wall Street Is Warming Up to Oil Majors
All three companies are beating expectations. Chevron posted seven consecutive quarterly EPS beats, with Q2 2026 adjusted EPS of $6.06 on revenue of $67.20 billion (+51.4% YoY). CEO Mike Wirth credited “disciplined investment and strong execution that drove record U.S. upstream production, record crude throughput in our U.S. refineries, and exceptional reliability across key assets.”
Exxon has strung together 4 consecutive EPS beats, and CEO Darren Woods says the company is “fundamentally stronger” after growing advantaged volumes in Guyana and the Permian. Occidental claims five straight beats, capped by a 29.8% Q2 EPS surprise at $2.40.
The Path to $225, $180, and $75
Chevron at $186.56 needs roughly 21% to hit $225. Exxon at $153.04 needs about 18% to reach $180. Occidental at $55.91 requires roughly 34% to $75.
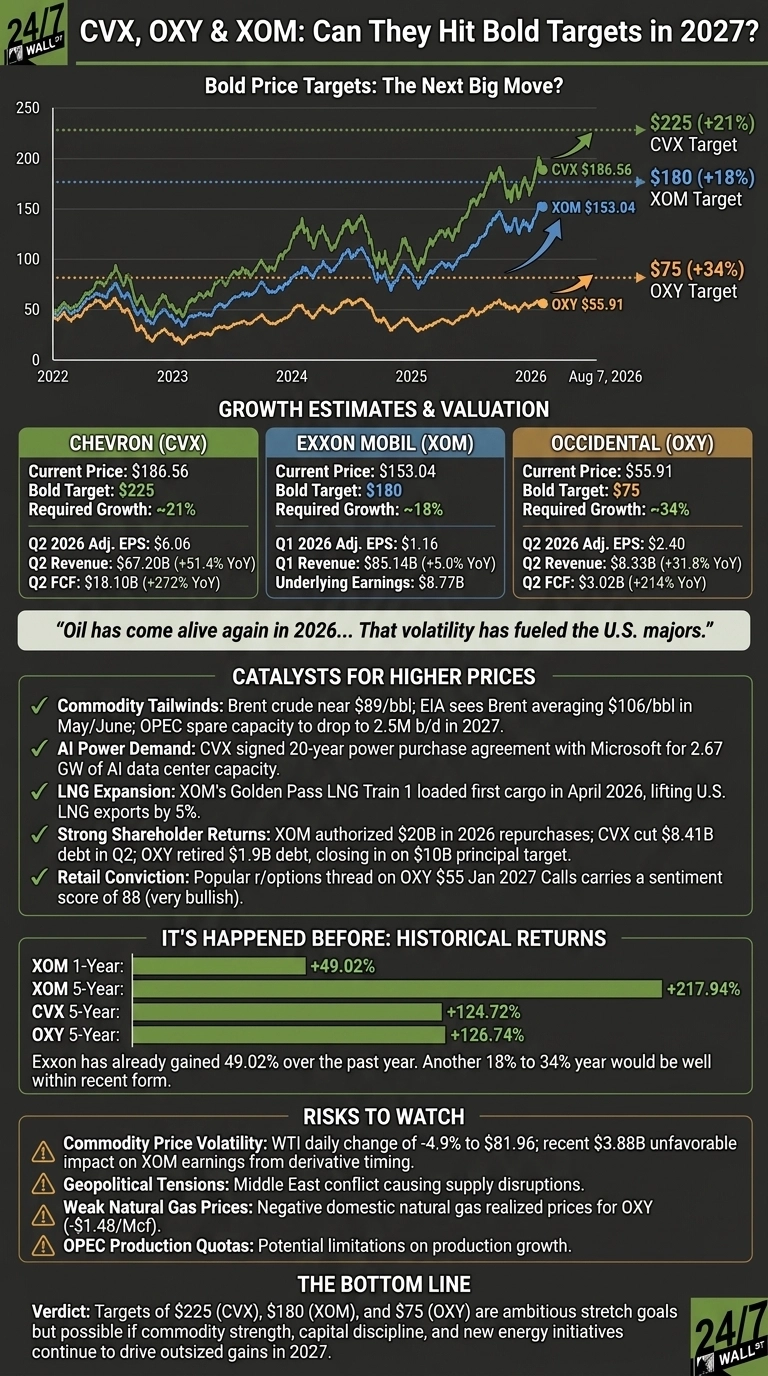
At $180, Exxon would trade near 27x its full-year 2025 EPS of $6.70, close to the S&P 500 average, before factoring in 2026 growth. Occidental at $75 would sit near 15x its forward EPS of $4.85, hardly demanding given the deleveraging story. Chevron’s Q2 run-rate annualizes above $24 in EPS, keeping $225 in normal multiple territory.
What Could Push These Stocks Higher
- Commodity tailwinds. The EIA sees Brent averaging $106 per barrel in May and June and warns OPEC spare capacity will drop to 2.5 million b/d in 2027 after the UAE’s departure.
- AI power demand. Chevron signed a 20-year power purchase agreement with Microsoft (NASDAQ:MSFT) for 2.67 GW of dedicated capacity in West Texas.
- LNG expansion. Exxon’s Golden Pass LNG Train 1 loaded its first cargo in April 2026, lifting U.S. LNG exports by 5%.
- Buybacks and deleveraging. Exxon authorized $20 billion in 2026 repurchases. Chevron cut $8.41 billion of debt in a single quarter. Occidental retired $1.9 billion and is closing in on its $10 billion principal target.
- Retail conviction. One popular r/options thread, “Oil is going to $150+ OXY $55 Jan 15th 2027 Calls,” carries a sentiment score of 88 (very bullish).

History Says These Moves Are Possible
Exxon has already gained 49.02% over the past year and 217.94% over five years. Chevron is up 124.72% over five years, and Occidental has climbed 126.74% in the same span. Another 18% to 34% year would be well within recent form.
The Bottom Line on the Bull Case
Chevron’s $18.10 billion in Q2 free cash flow, Exxon’s $15.60 billion in structural cost savings since 2019, and Occidental’s aggressive deleveraging support higher multiples.
Risks remain (OPEC quotas, weak U.S. natural gas prices, and Middle East supply shocks), but with Brent structurally supported and buybacks running hot, $225 for CVX, $180 for XOM, and $75 for OXY are stretch goals worth watching. Returns at this level should not be expected every year, but we have outlined the blueprint for how this trio could see outsized gains in 2027.
The post CVX, OXY & XOM: The Next Big Move in Oil Could Be Just Getting Started appeared first on 24/7 Wall St..
]]>