By the time SBC merged back into AT&T, AT&T was revamping its alternative channels under one umbrella and also picking winners.
The carriers created the beast that is the TSD.
Some carriers treat the TSD like a Tech Data (distributor) and bankroll employees to ensure that the orders are clean and the order process is followed to a Tee.
This is how the top 10 carriers utilize the TSD model. Few contracts, fewer checks to cut, bigger players to deal with, cleaner orders. Roughly 85% of the orders that pour through a TSD go to the top 10 carriers.
The only thing a Technology Services Distributor (TSD) distributes are commission checks.
Most vendors unfamiliar with the Channel don’t realize it was designed to supply demand of the small business. Cisco, Microsoft and the Baby Bells couldn’t knock on enough of the 5-6 million doors of the small business, so the channel was used. The three vendors had controls: certifications. For Cisco and Microsoft, these classes became a billion dollar industry that spins off Brand Ambassadors into every business that hires them. Of course, it is real training that many community colleges across the US provide.
The Baby Bells fudged their certs and classes. Quota was more important. Bonuses and President’s Club beat integrity. Which is also how the channel got its reputation snudged and labeled “coin-operated”.
So what about the other 300 vendors that aren’t in the top 10? Usually they flounder because they didn’t understand the game. Think about Office Depot who was in and out of the channel in two years, dropping a couple of million. They just didn’t know the game.
Think about the POTS Replacement vendors. They did not create the demand. Verizon, AT&T and Lumen did – the Baby Bells. They did that by closing down wire centers, decommissioning switches and turning off the copper lines. Yet there is Demand, especially in small business, and the Channel will supply that demand.
UCaaS providers (2000+), CX providers (1000+), Agentic Voice AI (2400+), MSPs (42K+), MSSPs (5000+), cloud providers, hosting companies, and data center companies all want customers. Some think that the Channel is a free sales force. You only pay on success. True, but not.
So much goes into a Partner Program. There are ingredients needed just so the vendor looks like they are serious about the Channel. Like the ability to see order status and commissions. That’s a baseline.
In Red Oceans, partners pick 3 vendors to work with. They vet them. They test them. Then they Partner with them. Then the magic happens: Sales!
However, if you are not one of those three, you are like the ugly kid with braces sitting on the bleachers at the high school dance. And that’s where the work begins.
The TSD does not hand you partners. It may provide an email list, which as a vendor, you will proceed to spam, because no one has ever read Permission Marketing! No one gave you permission to email that list. The TSD handed it to you — usually without telling the partners that is what they do. So the partner gets hammered with spam. And I mean it is SPAM: unsolicited commercial email, but it is really just ads. If vendors just improved how they handled email lists from TSDs and expos they would be ahead of the game. But vendors are lazy and in a hurry and are, oh, so important! With this Purple Cow that every business has to find out about and buy because it is so much better than the other 200 on the market!
That is sarcasm, by the way. If you are in the cloud comm space or AI or CX or CyberSec or MSP, WHY YOU? Why you and not the next booth? Answer that truthfully, to start.
But back to the TSD.
Mr. Co-Founder/CEO hires a consultant who tells them to get in the Channel. Pick a TSD. Go Bronze at least! Orders will flow in 90 days!
All of that is bullshit. It doesn’t work that way at all!
The TSD just holds the partner contract so you don’t end up like Windstream with 132 different partner agreements. With or without a TSD, you need solid structure around your partner program, a budget and the patience to wait 2-3 years for a pay off. If not, go through the pain of hiring SDRs and sales reps. At least that way, you have control, a feedback loop and if you pay attention, you might learn something.
This is where you either (A) buy my book; or (B) hire me to make your channel program work.
]]>For more information, you can watch the launch webinar HERE or head to their website.
If the video does embed correctly for you, please watch the interview HERE.
]]>The Technology Services Distributor (TSD) is a brokerage for vendor contracts. The only thing they distribute is commission checks to partners. They have over 300 suppliers, but only a handful are relevant to most partners. Roughly 85% of the orders are for the top vendors: AT&T, Verizon, Lumen, Cox, Charter, Comcast, WIND/Uniti, Zoom, and RingCentral.
They came to power because AT&T, XO and Level(3) (thanks, Craig!) decided that they only wanted to deal with 10 partner contracts. So they made everyone else go under one of the 10. Instead of cutting 250 checks each month; they cut 10. Then PE came along and POOF! there’s only 4 pure TSDs left.
Every vendor I talk to thinks 2 things: (1) the channel is coin operated; and (2) sales happen fast! Both are very wrong.
AT&T and the other top vendors get most of the deals because Brand and Demand. The channel was designed by Microsoft and Cisco to supply the SMB for the 2 IT titans. MS and Cisco created demand and the channel – VARs mostly – made a business out of selling, installing and maintaining Cisco router and switches and Microsoft products. Ingram and Tech Data stepped in so the vendors didn’t have to sell 1 box at a time and get involved in logistics for 60K VARs! The Distributors handled it. The licensing management, too.
If you have a bone to pick with the TSDs or the Channel, it tells me that you don’t understand the Channel and the partner program you have is struggling.
If the channel didn’t work, the UCaaS vendors wouldn’t bother with it, but 45-55% of sales come in from the channel.
Look at it another way, remember Juniper? They had similar products — some say better — than Cisco, but partners were Cisco certified and knew the product and no one ever got fired buying Cisco or IBM or AT&T. Colleges were training Cisco engineers and MSCE’s. Brand Ambassadors for the two vendors in every organization.
Juniper had a good product; there was demand; but they lacked brand and awareness and ambassadors. You notice today that the MSP community has a number of Brand Ambassadors, because vendors learned from Juniper that just because you build a better mouse trap doesn’t mean it will sell without a lot of marketing.
When a partner approaches a prospect, having a Brand name product to offer that the partner is familiar with makes the sale easier. Reduces Friction!
UCaaS providers did not follow the Mitel-Avaya route to market. Mitel, NEC, and Avaya dealers were authorized and trained – and were loyal! That’s what most vendors are looking for, but that doesn’t happen in a vacuum, signing a bronze level agreement with a TSD. Do you know the number of moving parts involved in creating a dealer network or a successful partner program? Many. We discuss them on The Disconnect podcast every week.
If you aren’t one of the top 10 vendors, then you should really hire me to examine your partner program to see how we can get it off the struggle bus.
]]>I have a weird thought: Stop with all the AI!
Here’s where I see things going with UCaaS:
Broadsoft shops will be Webex resellers with an expensive class 4 switch for call control. But they won’t dump the Broadsoft due to sunk cost thinking and hold over from days of being a real voice provider.
Residential voice and simple business voice (SIP Trunks!) will be the business focus for years to come. Is a Broadsoft a cost effective way to deliver that?
For small business, Agentic AI, SMS, and voice are going to move to the PSA, the professional software that runs the business. Think ServiceTitan. I see it with HVAC, appliance repair, car repair and other service shops that have software handling quote to cash plus all of the comms in-between. When is the technician arriving? It even sends and email or text asking for a review or a survey or both.
Weave already does this for healthcare, veterinarians, and dentists. Bluip is doing this for hospitality. VERTICALS, people! VERTICALS. This was discussed at the summit twice, but I feel like it fell on deaf ears. INTEGRATIONS can make you sticky!
Consider this: 2000+ Voice AI providers have been funded in the last 3 years. Read that again. And BCStrategies counts 1300 CX providers in their research!
Thinking that getting Agentic AI from your switch provider is going to make you a contender is folly. Most UCaaS providers didn’t sell call analytics, but now they think they are going to be leading the charge? How many call recording clients do you have? Probably not many.
How many contact center clients do you have? If it isn’t a meaningful percentage of your seats (like 20K UCaaS seats and 2K CC seats), then how do you imagine your AI Agent sales will go? Or your CX sales? Unless you retool your sales and marketing departments, consider that you may be in the VOICE business and strategize accordingly.
RingCentral and Zoom are fighting to be the end all be all — up against Microsoft Teams. There isn’t room in that space for anyone else. They are fighting for Enterprise and Midmarket – anyone over 250 seats!
Dialpad is in that fight because they were talking AI for practical use before anyone, but they have a very concrete story and ICP.
The majority of the market is 10-250 employees. 700K businesses have 10-250 employees in the US.
This article from UX Today explains a lot. “Zoom told investors in May that its first quarter of fiscal 2027 was one of its best in years. Revenue grew 5.5%, beating the top of its own guidance range, and CEO Eric Yuan called it “among our best growth rates in recent years” on the call. In that same breath, Zoom guided Q2 lower: $1.265 billion to $1.270 billion, which at the midpoint is 4.1% year-on-year growth. A company doesn’t usually follow its best quarter in years with guidance for a weaker one unless it has a specific reason to expect the slowdown.
That reason matters more now than it would have three months ago. Cisco’s Collaboration segment just delivered its best quarter in seven years, up 12%. RingCentral grew 5.9% in its own most recent quarter. Zoom’s 5.5% in Q1 sat ahead of RingCentral’s pace. Its 4.1% guidance for Q2, if it holds, would sit behind both.
Online churn, from self-serve and non-enterprise customers at Zoom, rose from 2.8% to 3% in Q1.”
RingCentral and Zoom have a lot of AI adoption but not a lot of revenue from it. They are spending like drunken sailors on a shore pass on AI, but are only seeing it stave off revenue decline. Is that a game you want to be in?
Since most UCaaS providers launched (between 2003 and 2009), they were selling PBX replacement, but forgot about chat, video, meetings and other functions (like call recording). In fact, it took the 2020 pandemic for anyone to remember that they offered those functions. Some of it was due to how the sales operation was set up, some was about sales compensation, but it also has to do with a lack of product management. There wasn’t a product champion in place educating the company, the customers and the market on all the cool things that the platform was capable of.
From 2020 to 2022, Cisco added over 400 features to Webex. Most Broadsoft providers had no idea! No one was paying attention or keeping up with that.
We see how that worked out for UCaaS providers. How will that work when UCaaS providers try to become Agentic AI providers?
AI is even more complicated than CX in both sales and implementation. And every AI product is also a Data project. Who handles all of that professional services?
If churn is 2% and growth is 4%, um, barely outpacing churn, maybe spending all your dollars and sales cycles talking AI instead of Collab isn’t resonating with Buyers.
There needs to a strategy, a plan, and proper messaging for your CSP. There also needs to be serious thought into questions like: Why YOU and not MS Teams? Why not RingCentral or Zoom or Dialpad? Not enough CSPs have real answers to the questions: Why should we buy from you? It is about time they did.
SIDE NOTE:
On the Channel for UCaaS Providers. At most CCA events, the members are not very channel friendly. In fact, yesterday they were talking about how useless TSD’s are. I will get into this in another post or podcast. It really shows how little most vendors understand the channel that delivers 40-55% of sales to most UCaaS providers!
Here you go: Why Are You So Mad at the Channel?
]]>
Cloudbrink launched VeriAIfy as part of its zero trust network platform which developed out of a WAN optimization service. The VeriAIfy system allows IT to identify all AI agents on the network, even remotely (if the remote worker is using the VPN alternative). It allows IT to see what the AI is doing and shut it down. That seems pretty unique to me.
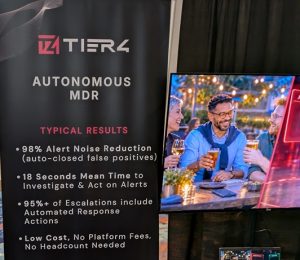
Tier4 AI is an autonomous MDR system. The AI looks at and responds to every alert in under 5 seconds. Saw the demo at the MSP Summit last month from my buddy, Lenny Chesal!
SmartTile is a single pane of glass monitoring solution for IT teams or MSP’s to view live video feeds, call volumes, bandwidth usage, and network statuses in one spot. It goes beyond that when integrated into other security systems and workflows. It will drop trouble tickets for you into the ISP and elsewhere.
Aggregators or Resellers of circuits are adding this extra layer of visibility. BCN Prism and AireSpring AireControl are just two examples of similar functions being added to the network aggregator for visibility and differentiation. If you are looking to add this platform to your reseller business or your MSP, please call RAD-INFO!
At CVX Expo on Nov. 17-18, 2026, I will be running a CyberSecurity panel titled The Steps to a Complex Cybersecurity Sale. Join us!
I was working with SIPMedia on MyPhoneCo in 2004. It was $7 per VoIP Line. That ran on a Nortel DMS-500 and the Level(3) SONUS network that Lumen is closing down.
Nuvio, Sentito, VayaIP, World Accxx, Starnet, Reywood, Phonetag, Peerio, ICG Voicepipe, i2, Cloudplus, Comm Partners, VoIP, Inc. (OTCBB:VOII), Smoothstone, M5, Vox, Voxox, VPF and 100’s of other companies were trying to sell VoIP from 2003-2008. Most were closed before UNE-P died. One reason was they couldn’t figure out how to get past the DSL routers of the ILECs. Another was the scattered approach to selling wholesale, retail, white-label to small, medium and large businesses. That approach never works. It screams: Please Give Us Revenue – any revenue!
I was a beta tester for AT&T CallVantage (2004) and Primus (2003) VoIP lines. I had to return the Cisco ATA’s they sent me when the trials were over. I recall that 44 minutes was the longest call you could make before the ATA overheated and dropped the call.
There was a battle over VoIP Protocols: MGCP and SIP. Cablecos (and AT&T) were using MGCP until 2006, when Comcast signed with NGT (later acquiring NGT), which was a Broadsoft white-label provider. That’s when MGCP started to phase out.
There were so many terms for this product: VoIP, IP Centrex, IP-PBX, Hosted PBX, Cloud Phone, Cloud PBX, and others until it got dumped into the UCaaS garbage can. Except for Vonage, RingCentral and 8×8, most providers weren’t growing, nationwide or branding. Then the pandemic hit and it all changed. 30+% Growth while everyone was asking for Zoom!
Many forget that PGi GlobalMeet was a video conferencing service that Siris acquired in 2015 for $1B that did not seem to get any traction during the pandemic. (PGi’s final gasp.) Cisco’s Webex built on Jabber was the best quality video calling software, but Zoom was the easiest to setup and use (best User Design!) — and was free! The rest is history!
Now, growth is single digits for cloud comms, just outpacing churn. Many providers are looking to sell — but have unrealistic ideas of valuation! A few are looking to buy at favorable rates.
There were 2 large deals this week.
CallTower and Momentum did a merger, since they share an investor, Court Square Capital Partners. CSCP has backed Momentum since 2018 and took a majority stake in CallTower earlier this year. CSCP is grouping voice and collaboration under CallTower, and leaving connectivity and infrastructure with Momentum.
CallTower adds 3,500+ customers and 250+ employees, for a total of more than 8,500 organizations.
Various websites put Momentum’s revenue at between $66M and $278M. With 450 employees (and 250 going to CallTower) at $500K per telecom employee is inline with the online search estimates of $200M.
It makes CallTower bigger, but also means they have to run a couple of versions of Broadworks on top of their Metaswitch and whatever else is legacy back there. The efficiency comes from consolidating all the platforms to one!
More on this story HERE.
This week Sangoma sold to B Riley. BRC Group Holdings, Inc. Agrees to Acquire Sangoma Technologies Corporation to Scale Communications Portfolio for $204M plus $27M in debt for $200M in revenue. B Riley owns Lingo, Bullseye, magicJack, NetZero and Juno (United Online)! Seems like the Bending Spoons strategy!
These transactions are 1X Revenue!
The size of the most recent deals in 2026 is $200M in revenue.
Two question marks in the UCaaS space: 8×8 and Vonage. Vonage is for sale. Ericcson already wrote down the acquisition and just wants to keep Nexmo. They would be happy to unload the UCaaS and contact center pieces.
8×8 stock price is at $2.31 as I write this. The market cap is $334M; the debt is $370M; the deal would be $725M for $750M in revenue and 3M seats!
Have you been listening to our podcast, The Disconnect? on YouTube.
Another post I wrote about what is happening in Cloud Comms in 2026.
Also, if you are attending Cavell Summit NA or CCA in Boston, let’s grab coffee!
Many of my engagements have been to fix problems: sales team that needs training and a system; a channel program that is missing its mark; product messaging that needs refinement; value proposition needs to be defined; or strategy that needs to be evaluated relative to the market.
Seth has created a tool for 2 people to come together to work through a problem, Knotchat. “A Knot-chat is a simple, guided conversation. One person coaches; the other surfaces a knot, names the baggage, and drops it. Nothing you say or write is captured — bring pen and paper.” Here is How to host a Knot-chat [video by Seth].
Coaching and mentoring people has been the best part of my business life.
Over 25 years, I have worked with over 150 service providers of all types – CLEC, VoIP, ISP, MSP, CSP, ILEC. Learned a lot of lessons and have deep domain knowledge in the telecom space. Looking for some help through a problem?
Make an appointment to speak with me: https://radinfo.youcanbook.me/
We can use the Knot-chat or Zoom or Google Meet or the phone. You get 15 minutes for free. If you need more time than that you can buy an hour of time now:
]]>
Earlier this year, Lumen announced that is was exiting the voice game. Level3 was the a vendor to more than 70% of the VoIP Providers in the US, either directly or through a reseller. This goes beyond closing the copper plant. They have shut of the Global Crossing voice network.
They sold CenturyLink assets to AT&T this year. One more step in ridding itself of “technical debt”.
Lumen sent an email yesterday stating that they are no longer quoting DIA (dedicated internet access).
“Effective October 1, 2026, Dedicated Internet Access (DIA) closes to new quotes, with a defined exception path. New DIA quoting will be restricted in our quoting systems, with exceptions available where a customer’s validated solutioning needs cannot yet be met by Intelligent Internet. DIA is not going away and is not being retired. Our existing DIA customers continue to be fully supported operationally, including renewals, allowable modifications, and disconnects.”internet
I understand leaning on Fiber for AI like Zayo, Lumen and UNITI are doing. I understand closing legacy voice networks. Yet no more DIA seems like a bridge too far. Partners will have to explain to customers why NaaS or Dynamic Bandwidth are better, yet more expensive options.
“Together, we have an opportunity to help customers modernize for the AI era. You can now position Lumen® Intelligent Internet as a smarter, more agile approach to connectivity that empowers organizations to scale, innovate, and adapt with confidence.”
This is almost saying: we no longer want SMB business. We want Enterprise, GEM and larger mid-size. This is a recipe many have tried, but there are only 21,000 businesses that fit that size. And you have to convince them, inside their own budget cycles, initiatives and carrier renewals, to migrate to Dynamic Bandwidth. Okay. That is a tough road to plow.
Lumen is re-branding for the next gen, but leaving behind all the services that pay the bills – and service their huge debt load ($15B).
During the last 24 months, dealing with customers who have 60 days to find an alternative has been challenging. For switched long distance and toll-free numbers, it was a challenge to keep the numbers and port to a new carrier.
For DIA customers, this will be a different difficulty since a lot of business addresses do not have multiple fiber connections. Never was there a better time for Connectbase and other fiber finder services.
If Lumen is your vendor, give me a shout to help you find an alternative solution! 813-963-5884
Fierce has an opinion on this strategy as well.
RAD-INFO’s State of ISP Report 2026 will be available in PDF in October. Pre-sale rate of $25
]]>You might also like to read My thoughts on the Channel Right now.
]]>The channel partner community is seeing a lot of interest. Private equity is looking under the hood. For Trusted Advisors growth is a challenge, so TSB’s have been either loaning them cash or investing in them.
Last week, AppDirect acquired a partner, CCI, that was owned by a PE firm. The only news about it was a transaction note from the bankers. The bankers were involved in brokerage firm ARG getting investment. Recently, they authored a paper about the channel being ripe for more investment – because it is asset-light and recurring revenue.
Telarus just had their annual event, where they launched their annual report about trends in the space. (And launched a bunch of employees off the payroll right after the event!) [Podcast about the report HERE.]
Both reports have similar themes, like CyberSecurity is a growth market for partners. AI is here to save us.
“As the advisor channel continues to embrace new categories of technology spend and platforms continue investing in data, security, and AI-enabled tools, the businesses that combine scale, independence, and technology differentiation will continue to command significant interest from both strategic acquirers and financial sponsors.”
Private equity has already snapped up most of the top agencies. Upstack, Bluewave, Bridgepointe, Amplix, Intelisys, AppDirect, ARG and a few others have been in the M&A game in the trusted advisor space since April, 2021. About $400 million dollars has been invested in agencies.
Upstack has almost 40 transactions. Amplix is on its 15th deal since the TA accepted funding from Gemspring Capital, a private equity group, in late 2022. The firm has 275 employees now! Bridgepointe got another investment in April 2026.
Upstack had a RIF recently and managing partners are buying champagne because they are told an exit will occur in the next 12 months. If someone could explain where the exit is, I would be delighted.
I can understand Scansource and AppDirect buying agencies to get closer to the customer, neither TSB has a deep understanding of the trusted advisor channel.
“Telarus has an expanding range of technology to put in front of customers. The harder task, according to CEO Adam Edwards, is developing enough advisors who can sell it effectively.” I don’t see the channel growing, but both Avant and Telarus say they recruit partners. Edwards said Telarus is bringing on approximately 1,700 new partners a year. How many actually sell a deal, we don’t know.
The TSBs were originally TA focused, then the shift went to recruiting VARs – even the channel events embraced this move. Now the focus is MSPs. TAs accounted for 76% of TSDs’ gross billings in 2024, but value-added resellers and managed service providers accounted for 12% and 7%, respectively. Moreover, the smaller VAR subset often drives the most revenue per deal, making them strategic yet elusive targets for TSD sales teams. [source]
There are legitimate reasons why the VARs and MSPs are a hard nut to crack and it goes back to the business model. But that’s a story for another day.
“Dimas said Telarus has dedicated resources to helping newly signed advisors understand the next action to take, the training available and the people who can support a deal. She also described AI education that has moved beyond terminology toward discovery questions, customer conversations and practical sales support.”
To really bring partners along there has to be structured training. MBA classes have done a poor job of teaching sales. Have the TSBs developed an LMS system or a training platform that is effectively developing newbies? Or are they relying on AI? Training people on sales skills is a challenging effort. Those students will also need technical learning about the generalities of the new technology and managed services.
At CVX Expo, we provide great content for partners to add knowledge and sales tips – and I know how much effort and diligence goes into creating that content. I have trained over 1000 channel managers, partners and sales reps. I don’t think AI videos are going to replace a half day with me or Dale Carnegie.
At one point, the TSBs were adding a ton of vendors/suppliers. Data showed that upwards of 85% of deals were with the top 15 suppliers – AT&T, Verizon, Charter, Comcast, Lumen, Cox, Frontier, Uniti/WIND, Altice/Optimum, Zayo, Brightspeed, Breezeline, Fidum, Zoom, RingCentral.
“That returns the strategy to Edwards’ central concern. Adding suppliers expands the portfolio, but a broader portfolio does not automatically create a broader advisory practice. Partners need customer access, confidence, time and delivery support to turn available services into revenue.” In other words, most of the suppliers didn’t see a deal, so it was wasted effort to onboard and manage these relationships.
The Telarus Trends report derives much of its data from its top partners. It makes me wonder what the other 80% of the partners will be dealing with. Partners already see the musical chairs and other changes at the TSBs. AppDirect has been hiring partner managers in Latin America!
There is a fundamental foundation to the channel that most people want to paint over, but it is why we are at this crossroads. Historically, the channel was built to supply demand that vendors – Cisco, Microsoft and the ILECs – created in the SMB market. The channel has traditionally been about pushing product on SMB. The tech has always been the product: UCaaS, POTS, PRI, broadband, 5G and integrated T1.
This sales force was motivated by transactional sales — getting ink and getting paid. That is a match for small business.
There are 2 very distinct markets: enterprise and SMB. PE, suppliers and TSBs want more of the Enterprise pie. That’s great, but no one wants to hire salaried sales rep to chase that business. The average B2B buying cycle runs over ten months – and have 5-12 decision makers involved. This is non-transactional. This is not what a majority of partners are comfortable with.
There are different types of sales people: farmers, hunters, whales. Motivation is different. Skills are different.
You cannot take a transactional seller and force them to handle a 10-month sales cycle with 5 decision makers. They enjoy closing quick and moving on to the next kill. They are motivated by ink. Follow up is nil.
Follow up is so difficult that while 80% of sales require follow up, half (44%) of sales reps give up after one follow-up! 92% of reps quit after four calls or rejections. And these are PAID sales reps. Imagine if they surveyed commission only sales reps?
Buyers indicate that AI, CX and Cyber are main topics. Partners are not equipped with technical acumen and sales skills for solution selling to meet those needs.
“Telarus has an expanding range of technology to put in front of customers. The harder task, according to CEO Adam Edwards, is developing enough advisors who can sell it effectively.” This takes us back to the training problem.
The issue everyone avoids is on commission only sales, how do you motivate partners to learn the tech and the sales skills? The vendors have added a bunch of certificates around AI. Colleges have been capitalizing on AI with certificates as well. Understanding what RAG is and how to prompt isn’t going to help you SELL an AI project.
It is a whole other skill set to push product – POTS, PRI, broadband, 5G – that can close in two meetings than it is to ask probing questions during a needs analysis and figure out the decision makers and the budget cycle. This is why companies hire sales teams. In fact, there are numerous types of sales positions: inside, outside/field, enterprise, midmarket, small business, customer success, retention – and vendors want to rely on the channel to replace that apparatus – on an outcome based rewards system that they steadily change.
]]>